
 China Intensive Care Unit (ICU) Beds and Surfaces Market | 2026-2036
China Intensive Care Unit (ICU) Beds and Surfaces Market Size, Share, and Industry Trends Forecast 2026-2036
China Intensive Care Unit (ICU) Beds and Surfaces Market Insights
Carbon fiber composites are decoupling from traditional steel framing in premium ICU bed construction, reducing weight by nearly half while maintaining load-bearing specifications. Pukang Medical leverages in-house polymer molding to control component costs across its electric bed portfolio. Saikang Medical Equipment anchors its position through dedicated production lines for convertible bed systems serving provincial hospital networks. Jianghai Medical competes on modular platform architectures that allow rapid reconfiguration between post-operative and respiratory distress applications.
China Intensive Care Unit (ICU) Beds and Surfaces encompass electrically actuated and manually operated patient support platforms together with specialized pressure redistribution surfaces designed for continuous critical care monitoring and intervention. Electric beds incorporate motor-driven height, trendelenburg, and lateral tilt adjustments with load capacities typically exceeding 250 kilograms to accommodate bariatric patients and attached therapeutic equipment. Electric beds command the largest revenue share due to mandatory inclusion in tier-3 hospital construction standards, while smart beds with integrated monitoring systems represent the fastest-expanding technology segment as hospitals seek to reduce nurse-patient ratios through automated vital sign capture. Surface mattresses maintain stable margin pools despite slower growth, driven by recurring replacement cycles tied to infection control protocols in public hospital procurement frameworks.
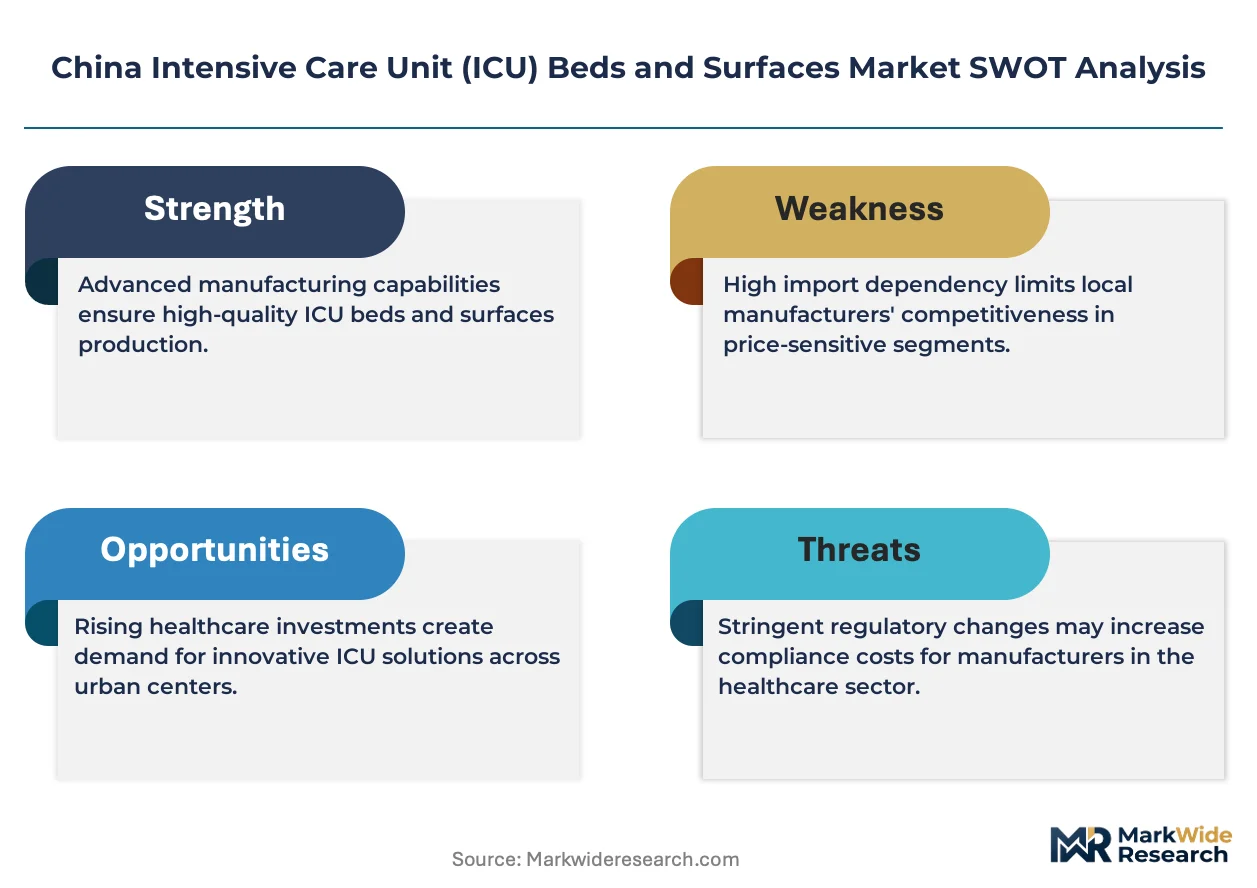
NMPA medical device registration requirements and GB standards for hospital furniture safety shape product development timelines and market access conditions for domestic and imported manufacturers alike. The dual carbon goals issued by MEE are forcing material selection changes across Jiangsu and Zhejiang production bases, with producers now certifying recycled aluminum content in frame assemblies. Stakeholders must monitor how provincial centralized procurement platforms alter pricing transparency and supplier qualification thresholds before committing to capacity expansion decisions.
Market Dynamics
Centralized provincial procurement platforms in Jiangsu and Zhejiang are compressing supplier margins while accelerating domestic manufacturer consolidation across China's ICU bed ecosystem.
Growth Catalysts
- NMPA registration pathway acceleration:Streamlined domestic certification timelines reduce product launch delays by eliminating redundant technical documentation reviews for manufacturers with existing GB standard compliance.
- Tier-3 hospital construction mandates:National healthcare infrastructure targets require electric ICU bed inclusion in all new critical care facility builds, creating sustained equipment replacement demand.
- Carbon fiber composite adoption:Jiangsu manufacturing clusters are scaling polymer molding capabilities that halve bed frame weight without sacrificing load-bearing specifications.
Market Restraints
- Aluminum and steel input volatility:Frame assembly costs fluctuate with commodity pricing, squeezing margin pools for producers without backward integration into metal sourcing.
- Jiangsu-Zhejiang supply concentration:Over 70 percent of domestic production capacity sits within these two provinces, exposing national distribution to localized logistics disruptions or environmental compliance shutdowns.
- Smart bed interoperability limitations:Proprietary data protocols between monitoring systems and hospital information platforms create integration friction that slows automated vital sign capture deployment.
Strategic Opportunities
- Central and Western China hospital networks:Tier-2 and tier-3 cities in Sichuan, Shaanxi, and Henan provinces remain underpenetrated relative to coastal infrastructure density.
- Convertible bed system applications:Post-operative and respiratory distress reconfiguration capabilities address workflow efficiency demands in provincial hospitals with limited dedicated ICU footprint.
- MEE dual carbon incentive alignment:Recycled aluminum content certification opens preferential procurement scoring on centralized government hospital purchasing platforms.
Industry Challenges
- Biomedical engineering talent scarcity:Shortages of firmware developers and electromechanical integration specialists constrain smart bed R&D pipeline velocity.
- GB standard recertification timelines:Updated hospital furniture safety requirements demand extensive third-party testing that extends product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Intensive Care Unit (ICU) Beds and Surfaces Market |
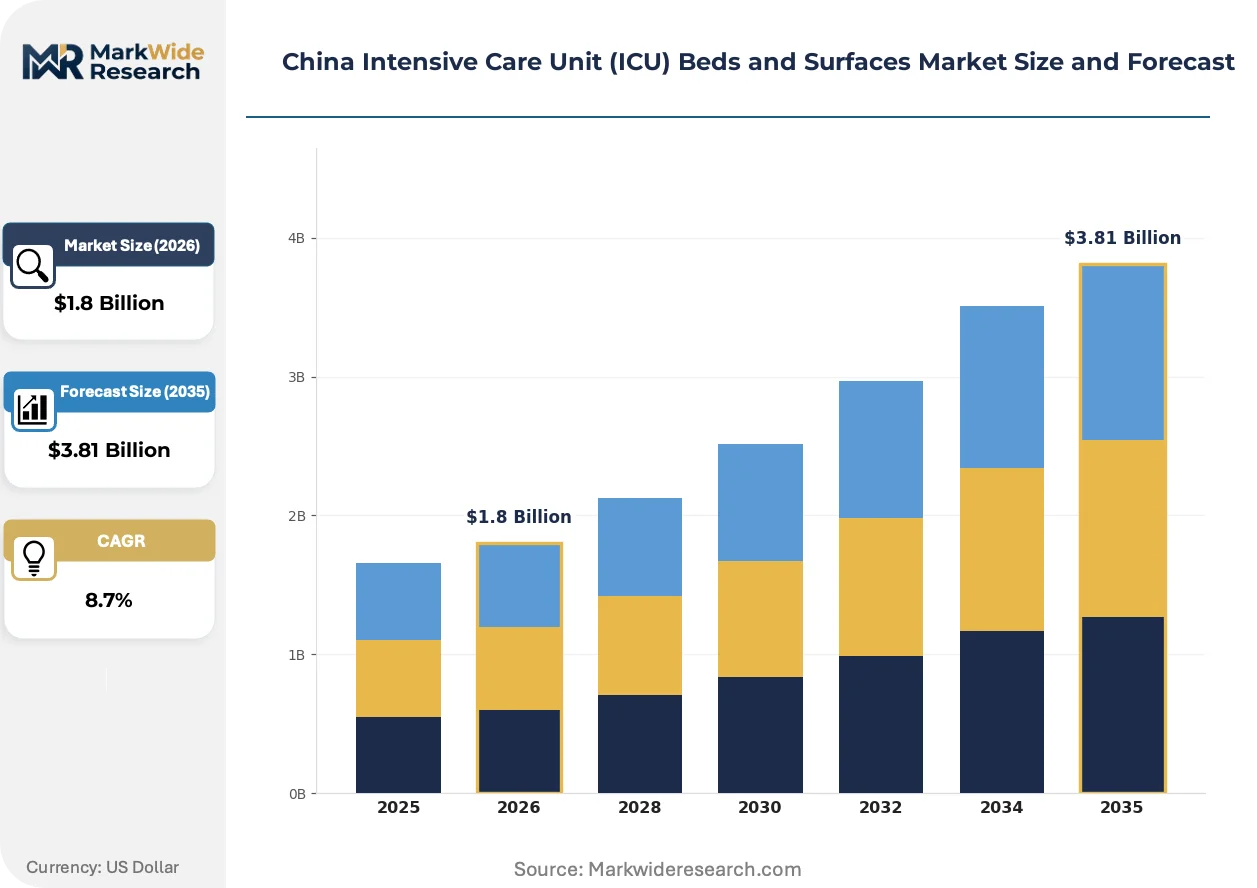
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Beds, Manual Beds, Convertible Beds, Surface Mattresses End User: Public Hospitals, Private Clinics, Research Institutions, Long-term Care Facilities Technology: Smart Beds, Pressure Relief Surfaces, Integrated Monitoring Systems, Modular Beds Application: Post-operative Care, Respiratory Distress, Trauma Care, Multisystem Failure |
| Companies Covered | Pukang Medical, Saikang Medical Equipment, Grace Medy, Anyang Top Medical Devices, Satcon Medical, Jianghai Medical, Maidesite Medical, Hope-Full Medical Equipment, Yonghui Medical Equipment Factory, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Intensive Care Unit (ICU) Beds and Surfaces Market Trends and Innovations
Sensor-embedded surfaces and motor control systems are merging into unified care platforms that automate patient monitoring while reducing nursing workload intensity.
Integrated pressure sensing arrays are converging with electric bed actuation systems to enable automated repositioning protocols that prevent pressure injury formation. Tier-3 hospital procurement committees are prioritizing these capabilities in new equipment specifications. The technology is converging with nurse call systems to create closed-loop alert workflows that reduce response latency during respiratory distress events.
China's NMPA issued updated medical device software validation guidelines that extend registration timelines for smart beds with embedded diagnostic algorithms. Manufacturers must now submit cybersecurity documentation and clinical evidence for vital sign measurement accuracy. Domestic producers in Jiangsu are establishing dedicated regulatory affairs teams to navigate these documentation burdens while maintaining price competitiveness against manual bed alternatives.
Hospital procurement committees are consolidating supplier relationships through multi-year framework agreements that bundle bed frames, surfaces, and maintenance services. Provincial centralized procurement platforms in Zhejiang are displacing hospital-level tendering for standardized electric bed configurations. This concentration is most visible in Jiangsu public hospital networks, where single-source contracts now cover entire regional critical care bed replacement cycles.
China Intensive Care Unit (ICU) Beds and Surfaces Market Segmentation
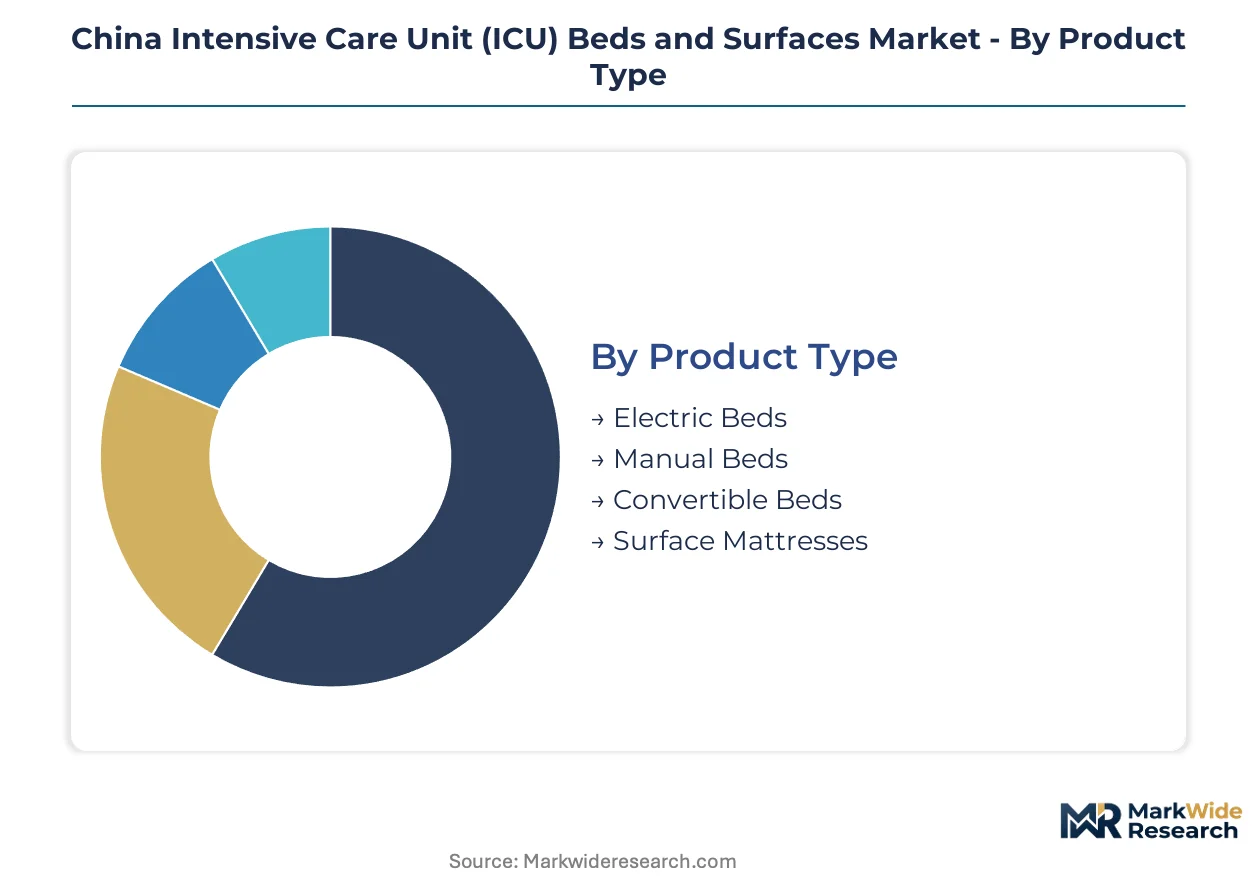
ICU bed procurement in China fragments across hospital tiers, clinical applications, and technology readiness levels. Understanding these divides reveals where NMPA certification investments translate into revenue and where modular architectures unlock workflow efficiency.
Product Type:
Cost tier separates buyers—tier-3 public hospitals prioritize electric functionality while county-level facilities balance capital constraints against patient acuity needs.
- Electric Beds:Motor-driven height, trendelenburg, and lateral tilt adjustments with load capacities exceeding 250 kilograms accommodate bariatric patients and attached therapeutic equipment. Jiangsu and Zhejiang provincial procurement platforms mandate electric bed inclusion in all tier-3 hospital construction, creating sustained replacement demand tied to GB standard compliance cycles.
- Surface Mattresses:Pressure redistribution surfaces designed for continuous critical care monitoring utilize viscoelastic foam and air-cell technologies to prevent hospital-acquired pressure injuries. Public hospital infection control protocols in Jiangsu drive recurring replacement cycles despite slower overall growth relative to powered platforms.
- Manual Beds:Hand-crank height and positioning adjustments serve cost-constrained county hospitals and overflow wards where electrical infrastructure remains unreliable.
- Convertible Beds:Reconfigurable frame architectures enable rapid transition between post-operative recovery and intensive intervention modes.
Volume sits with electric beds; growth tilts toward convertible systems addressing workflow efficiency in space-constrained provincial facilities.
End User:
Procurement authority concentration varies—public hospital networks operate through centralized provincial platforms while private clinics retain direct supplier relationships.
- Public Hospitals:Tier-1 and tier-2 city critical care departments anchor national demand through centralized procurement frameworks in Jiangsu and Zhejiang. NMPA registration requirements and GB standard compliance shape supplier qualification thresholds for multi-year framework agreements.
- Private Clinics:Smaller-scale facilities in tier-2 cities prioritize manual and semi-electric configurations where capital recovery timelines pressure equipment selection.
- Long-term Care Facilities:Post-acute and rehabilitation centers outside traditional hospital networks source pressure relief surfaces for extended immobility management.
- Research Institutions:Academic medical centers pilot smart bed integrations with hospital information platforms before broader procurement rollout.
Procurement volume concentrates in public hospitals; private clinic expansion in Central and Western provinces offers the steepest expansion trajectory.
Technology:
Maturity gaps separate commercially proven platforms from emerging categories facing NMPA software validation delays.
- Smart Beds:Embedded sensor arrays and diagnostic algorithms automate vital sign capture and pressure injury prevention protocols. NMPA medical device software validation guidelines extend registration timelines for manufacturers submitting cybersecurity documentation and clinical accuracy evidence.
- Integrated Monitoring Systems:Closed-loop convergence of nurse call systems, bed actuation, and respiratory distress alerts reduces response latency in tier-3 hospital workflows.
- Pressure Relief Surfaces:Alternating air and low-air-loss technologies maintain stable margin pools through recurring replacement cycles.
- Modular Beds:Platform architectures enabling rapid reconfiguration between clinical applications address footprint constraints in provincial hospital networks.
Revenue concentrates in pressure relief surfaces; capability investment tilts toward smart beds as hospitals seek nurse-patient ratio reductions.
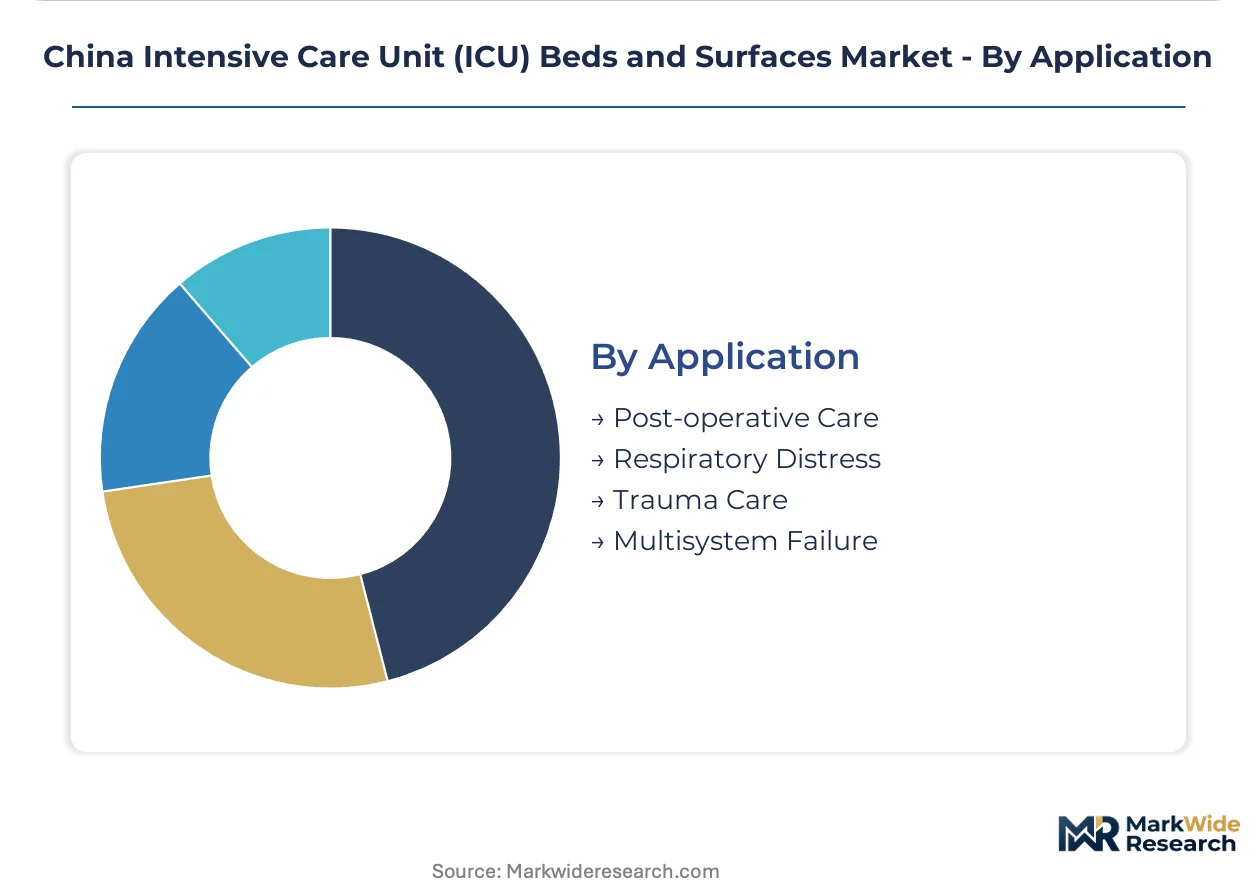
Application:
Acuity level determines equipment specification intensity—respiratory and multisystem failure cases demand the most sophisticated monitoring integration.
- Respiratory Distress:Automated repositioning protocols and integrated SpO2 monitoring support prone positioning and ventilation weaning in COVID-19 and ARDS management. Tier-3 hospital procurement committees prioritize these capabilities in pandemic preparedness specifications.
- Multisystem Failure:Continuous hemodynamic monitoring and rapid intervention access require highest-load-capacity electric platforms with full articulation ranges.
- Post-operative Care:Moderate-acuity recovery wards utilize convertible bed systems balancing monitoring capability against capital efficiency.
- Trauma Care:Emergency department and surgical ICU integration demands rapid imaging compatibility and radiolucent frame materials.
Equipment density peaks in respiratory distress applications; modular reconfiguration capabilities gain share fastest in post-operative settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate Jiangsu and Zhejiang production bases, anchoring over seventy percent of domestic ICU bed manufacturing capacity within tax-advantaged development corridors.
Jiangsu Province
Tier-3 hospital construction mandates in Nanjing and Suzhou drive electric bed procurement through centralized provincial platforms. NMPA streamlined registration pathways accelerate product launch timelines for manufacturers with existing GB standard compliance. Medical device clusters in Changzhou and Wuxi scale carbon fiber composite molding capabilities for premium frame assemblies.
Zhejiang Province
Hangzhou and Ningbo public hospital networks consolidate supplier relationships through multi-year framework agreements bundling equipment and maintenance services. Provincial centralized procurement platforms displace hospital-level tendering for standardized electric bed configurations. Wenzhou manufacturing bases specialize in polymer component production for convertible bed systems.
Sichuan-Chongqing Region
Tier-2 and tier-3 cities in Chengdu and Chongqing remain underpenetrated relative to coastal infrastructure density, creating expansion opportunities for domestic manufacturers. MEE dual carbon goals incentivize recycled aluminum content certification for preferential procurement scoring. Local distributors establish regional service networks to support equipment deployment in Western China hospital systems.
Shandong Peninsula
Qingdao and Jinan medical device industrial parks attract producers seeking proximity to northern hospital procurement programs. GB standard recertification requirements for hospital furniture safety shape product development timelines for manufacturers serving provincial public health networks. Jinan-based fabricators focus on manual and semi-electric configurations for county-level facilities.
Guangdong Province
Pearl River Delta manufacturing bases in Shenzhen and Dongguan supply pressure redistribution surfaces to national hospital networks through established distribution channels. SAMR market supervision administration enforces medical device quality management system requirements across production facilities. Dongguan clusters specialize in sensor-embedded surface technologies for smart bed integration.
China Intensive Care Unit (ICU) Beds and Surfaces Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with provincial procurement concentration favoring established domestic names over import alternatives. The vendor base organizes around three strategic archetypes: vertically integrated polymer molders controlling component costs, dedicated convertible system producers serving regional networks, and modular platform architects enabling rapid clinical reconfiguration. Competitive moves center on backward integration into metal sourcing to buffer commodity volatility and regulatory affairs team expansion to navigate NMPA software validation documentation burdens.
Among Jiangsu-Zhejiang based fabricators, Pukang Medical and Saikang Medical Equipment exemplify the integrated production archetype, while Jianghai Medical occupies a position within modular platform development. These entities represent how domestic manufacturers anchor market presence through geographic proximity to centralized procurement platforms and specialized production line configurations. Their positioning reflects the broader industry pattern where regional manufacturing concentration directly shapes competitive access to tier-3 hospital construction mandates.
| Leading Market Players |
|---|
| Pukang Medical |
| Saikang Medical Equipment |
| Grace Medy |
| Anyang Top Medical Devices |
| Satcon Medical |
| Jianghai Medical |
| Maidesite Medical |
| Hope-Full Medical Equipment |
| Yonghui Medical Equipment Factory |
| Others |
Pricing and Supply Chain Analysis
Aluminum and steel futures volatility on the Shanghai Futures Exchange cascades through Jiangsu and Zhejiang manufacturing clusters, compressing margin pools for fabricators without captive metal sourcing while tier-3 hospital procurement committees exploit supplier concentration to extract multi-year framework concessions.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to electric bed orders fulfilling urgent tier-3 hospital construction timelines, while spot inventory of manual configurations trades at discounts to clear warehouse space ahead of GB standard recertification deadlines. Pricing stratifies across premium smart beds with NMPA software validation, standard electric platforms with full motor actuation, and economy manual frames for county-level overflow wards. Cost compression in the standard electric tier is intensifying because provincial centralized procurement platforms publish transparent benchmark pricing that eliminates information asymmetry between buyers. County hospital procurement managers exhibit highest price sensitivity due to capital recovery timeline pressures, while tier-3 academic medical centers prioritize interoperability certification over unit cost.
Supply Chain Analysis
Dual-sourcing requirements embedded in Zhejiang provincial procurement mandates force tier-3 hospitals to qualify minimum two domestic manufacturers per bed category, fragmenting volume concentration and extending supplier onboarding timelines. Production gravity centers on Jiangsu and Zhejiang provinces, with secondary fabrication in Shandong and Guangdong feeding northern and southern hospital networks respectively. Frame assemblies draw from aluminum extrusion, carbon fiber composite molding, and electric motor actuator supply bases concentrated in Changzhou, Wuxi, and Wenzhou manufacturing clusters. Single-source vulnerability persists in embedded sensor arrays and diagnostic algorithm firmware, where NMPA cybersecurity documentation requirements constrain qualified vendor pools. Distribution runs through provincial centralized procurement platforms that displace direct hospital relationships for standardized configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber composite molding capacity constraints in Jiangsu production bases prop pricing premiums for lightweight frame platforms, creating supply-constrained conditions that favor incumbent fabricators with qualified polymer supply chains.
For Market Incumbents: Extend regulatory affairs capabilities to navigate NMPA software validation documentation burdens for smart bed portfolios, while adding captive aluminum extrusion capacity in Changzhou or Wuxi to buffer commodity volatility threatening standard electric bed margins. Centralized provincial procurement concentration poses margin compression risk that demands multi-year service bundling to defend pricing power. For New Entrants and Emerging Players: Launch via regional distributor partnerships targeting Sichuan and Chongqing tier-2 hospital networks where electric bed penetration lags coastal infrastructure density by substantial margins. Convertible bed systems for post-operative respiratory reconfiguration represent the most penetrable white-space segment, as provincial hospitals with limited dedicated ICU footprint prioritize workflow efficiency over specialized equipment capital outlay. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular platform architects with established GB standard compliance and existing NMPA registrations in Jiangsu-Zhejiang manufacturing corridors, where environmental compliance shutdowns periodically constrain qualified supply. Long-term viability hinges on firmware development capabilities and hospital information system integration expertise. Watch NMPA medical device software validation guideline revisions as the signal indicating smart bed registration timeline compression or extension.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Software Validation Investment | Cybersecurity documentation capabilities accelerate smart bed registration timelines against manual alternatives. |
| Carbon Fiber Composite Molding Scale-Up | Changzhou and Wuxi polymer capacity expansion captures premium lightweight frame demand from tier-3 hospitals. |
| Provincial Framework Agreement Capture | Multi-year bundling of beds, surfaces, and maintenance services locks out competitor access in Jiangsu public networks. |
| Central China Distribution Partnership | Chengdu and Chongqing regional service networks address underpenetrated Western China hospital procurement programs. |
| Recycled Aluminum Certification | MEE dual carbon compliance opens preferential scoring on centralized government hospital purchasing platforms. |
Research Methodology
Multi-period observation of NMPA registration timeline trends, provincial procurement platform award disclosures, and Jiangsu-Zhejiang manufacturing capacity utilization anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineering directors at tier-3 facilities, GPO contracts managers, and domestic manufacturer regulatory affairs leads. Secondary validation drew from SAMR medical device quality management system filings, hospital procurement database extracts, GB standard revision notices, and MEE environmental compliance disclosure records. Bottom-up bed shipment estimates by province and hospital tier triangulated against top-down healthcare infrastructure expenditure forecasts.
Input-output matrices mapped electric bed, surface mattress, manual bed, and convertible bed production volumes against aluminum and carbon fiber raw material throughput, patient acuity admission patterns by application, and technology readiness levels across smart bed and integrated monitoring system categories over the projection horizon. CAGRs were derived from segmented demand modeling incorporating tier-3 hospital construction mandate compliance schedules and replacement cycle timing. Forecast inputs included NMPA registration pipeline velocity and provincial centralized procurement platform pricing benchmark trajectories.
Commodity price volatility, NMPA software validation guideline revision timing, and MEE environmental enforcement intensity are the dominant revision risks to the outlook. Deviation in NMPA registration timeline compression would shift the smart bed adoption trajectory materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Biofeedback Equipment Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
Total Lab Automation Market