
 Sharps Destruction Device Market | 2026-2036
Sharps Destruction Device Market Size, Share, and Industry Trends Forecast 2026-2036
Sharps Destruction Device Market Analytics
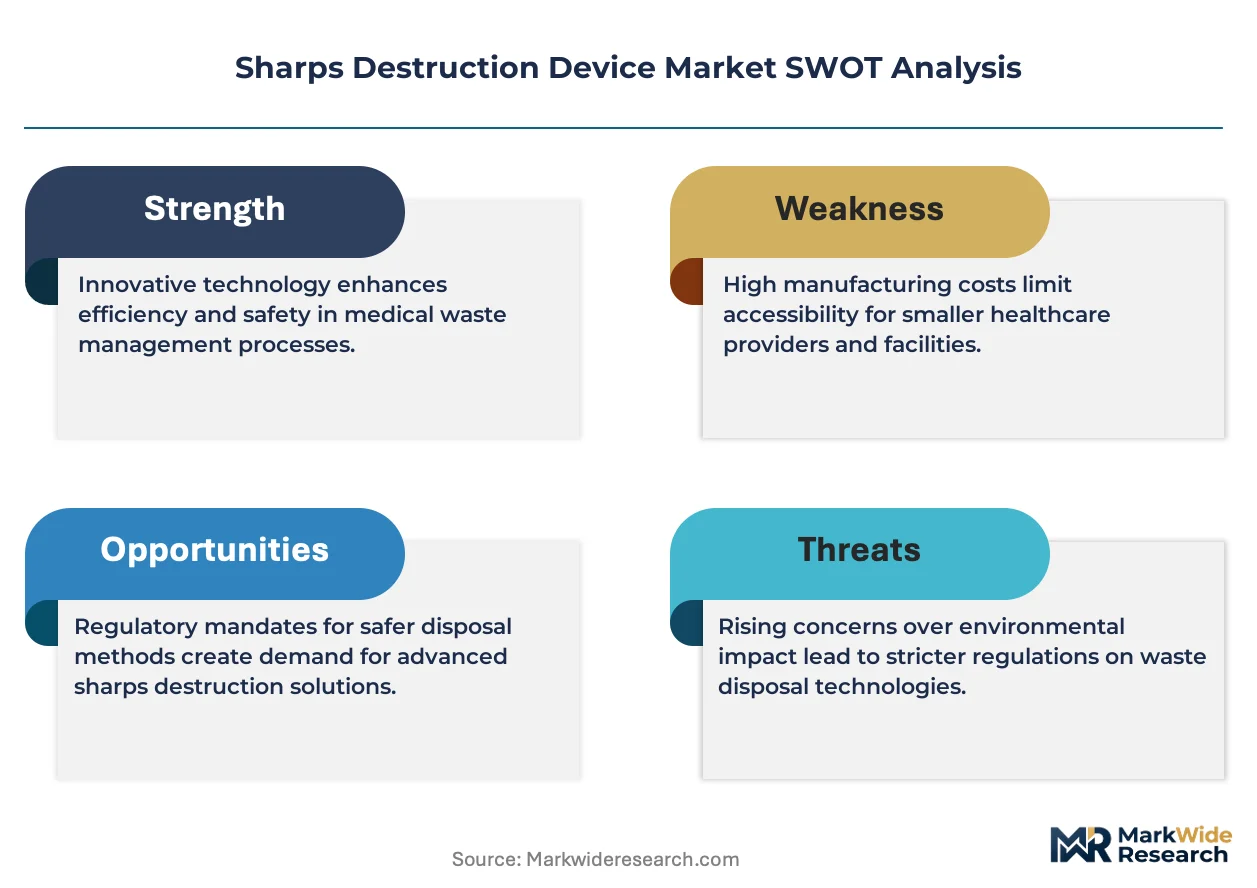
Biomedical engineering talent scarcity is bifurcating the competitive landscape between scaled incumbents and niche specialists. Stericycle leverages its national service infrastructure to bundle device placement with recurring disposal contracts. Becton, Dickinson and Company anchors its position through backward integration into needle manufacturing, capturing synergies across the sharps lifecycle. Nolato AB specializes in polymer engineering for containment housings, differentiating on material compliance rather than mechanical innovation.
Sharps destruction devices are electromechanical or thermal systems engineered to render hypodermic needles, lancets, and surgical blades irreversibly unusable through melting, shearing, or chemical neutralization, typically achieving temperature thresholds above 1,200°C or mechanical severance below 2mm particle size to eliminate puncture risk. Electrical and thermal technology segments dominate current procurement volumes, though microwave-based units are gaining traction in laboratory settings for their energy efficiency and reduced cycle times. Manual portable devices retain share in small clinics and ambulatory settings where capital budgets constrain electrical installation, while fixed integrated systems command premium positioning within hospital central sterile supply departments.
OSHA bloodborne pathogen standards, FDA 510(k) device clearance pathways, and EU MDR technical documentation requirements collectively elevate compliance costs and extend commercialization timelines for new entrants. The EPA's hazardous waste generator regulations in the United States further shape product design by mandating documentation trails that integrated software systems must automate. Stakeholders must monitor evolving state-level substitution mandates that could accelerate replacement cycles for legacy equipment ahead of federal compliance deadlines.
Market Dynamics
Healthcare networks are consolidating sharps waste handling from outsourced haulers toward in-house electromechanical destruction, driven by OSHA audit accountability and the operational cost of manifest documentation for off-site treatment.
Growth Catalysts
- OSHA Bloodborne Pathogen Standard:Enforcement of exposure control plans mandates point-of-use treatment, expanding installed base in US hospital emergency departments and surgical suites.
- EU Medical Device Regulation (MDR):Technical documentation requirements for containment systems accelerate replacement of non-compliant legacy units in German and French healthcare procurement.
- Microwave plasma technology:Energy-efficient sterilization cycles below four minutes are displacing conventional thermal units in high-throughput laboratory environments.
Market Restraints
- Stainless steel input volatility:Chamber and blade alloy costs fluctuate with nickel pricing, compressing margins for thermal device manufacturers.
- FDA 510(k) clearance timelines:Electromechanical device submissions average fourteen months, delaying commercialization for novel shear mechanisms.
- Reusable container substitution:Hardened polymer collection systems with mail-back logistics threaten low-capacity destruction unit demand in ambulatory settings.
Strategic Opportunities
- India CDSCO pathway alignment:Harmonized quality standards for Class B medical devices open procurement channels in tertiary care expansion zones.
- Home healthcare infusion:Portable battery-powered units address sharps accumulation in residential settings where municipal biohazard pickup is unavailable.
- Software-integrated documentation:Automated manifest generation links destruction cycles to EPA hazardous waste generator logs, creating service bundling potential.
Industry Challenges
- Biomedical electromechanical engineering scarcity:Cross-trained talent combining sterilization physics with embedded systems design commands premium compensation, constraining R&D expansion.
- Legacy electrical infrastructure retrofitting:Fixed thermal units require 480V three-phase installation, complicating deployment in older clinical buildings without capital renovation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sharps Destruction Device Market |
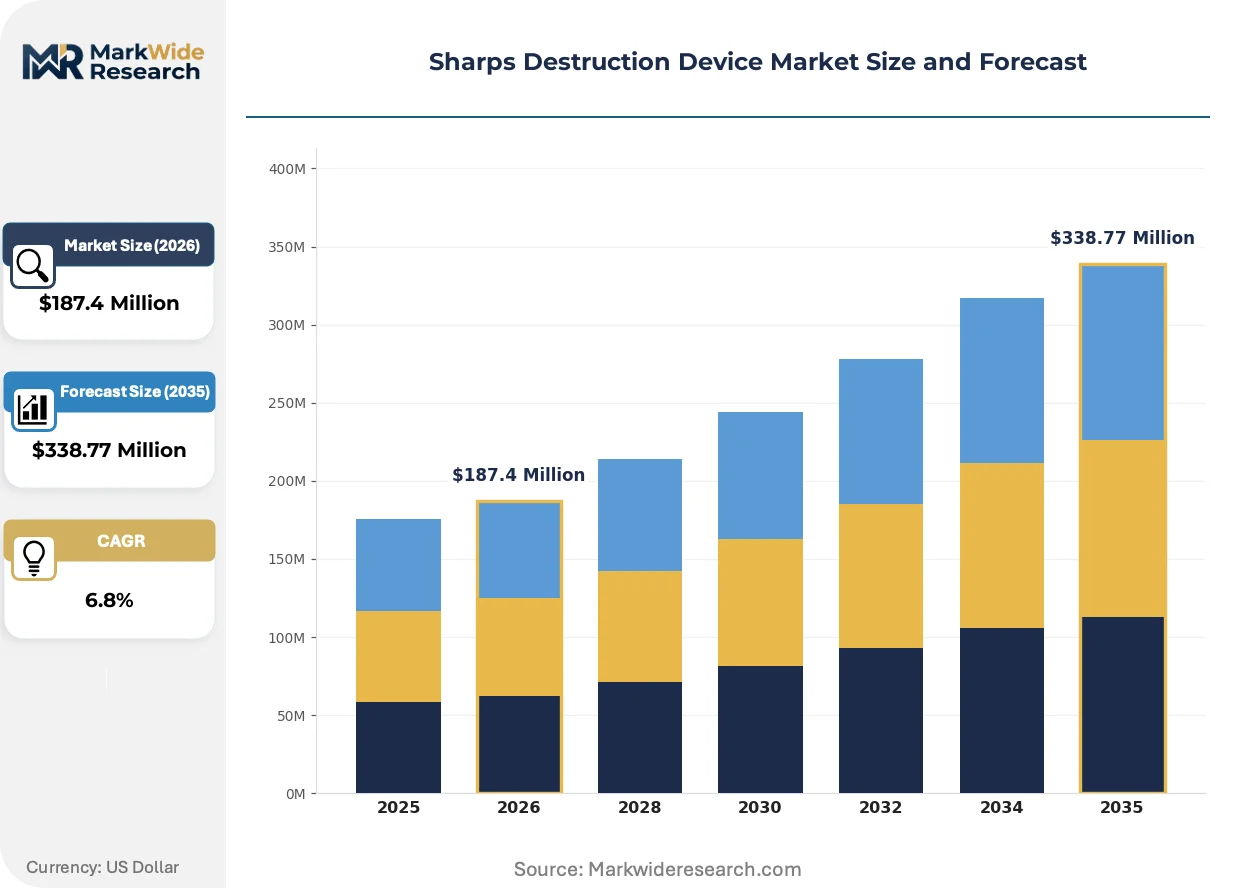
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical, Manual, Portable, Fixed End User: Hospitals, Clinics, Laboratories, Pharmacies Technology: Microwave, Thermal, Chemical, Mechanical Installation: On-site, Off-site, Standalone, Integrated |
| Companies Covered | Stericycle, Becton, Dickinson and Company, Nolato AB, Seton, Safety First Aid Group Ltd, GPC Medical, RedHawk Holdings Corp, Surgitech, Thermofisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sharps Destruction Device Market Evolving Landscape
Microwave-based sterilization and embedded compliance software are compressing treatment cycles while automating regulatory documentation, reshaping capital equipment procurement criteria across acute care networks.
Plasma arc technology is decomposing organic sharps matrices at 1,400°C with 40% energy reduction versus resistive heating. Academic medical centers in the United States are piloting these units for surgical suite integration. The technology is decomposing the historical trade-off between throughput capacity and energy consumption, enabling smaller footprint installations in space-constrained central sterile supply departments.
REACH chemical restriction amendments are phasing out halogenated flame retardants in polymer containment housings, forcing reformulation of polycarbonate blends used in portable device casings. European manufacturers face eighteen-month material qualification cycles. German hospital procurement consortiums are now specifying RoHS-compliant alternatives in tender specifications, accelerating supplier qualification bottlenecks.
Integrated service contracts are displacing capital purchase models for high-volume users, bundling device placement with preventive maintenance and compliance software subscriptions. US integrated delivery networks favor this structure for multi-site standardization. The shift is most pronounced in California and Texas health systems where facility count exceeds fifteen locations.
Sharps Destruction Device Market Segmentation
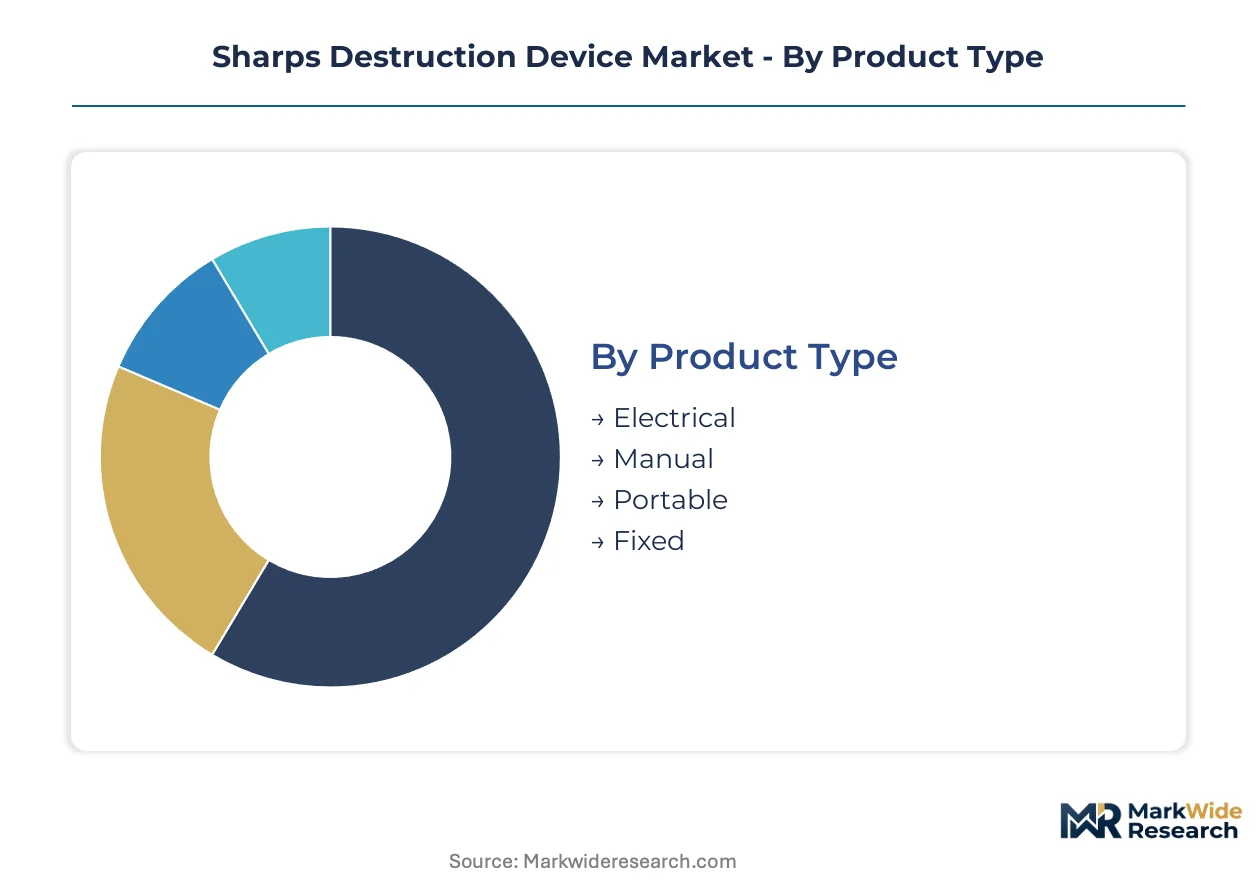
Sharps destruction device procurement splits across multiple decision axes that reshape vendor positioning. Hospital capital committees weigh throughput capacity against installation constraints, while laboratory managers prioritize cycle speed and energy footprint. Understanding these trade-offs clarifies where substitution threats concentrate and where technology differentiation commands premium pricing.
Product Type:
Manual portable devices face the most acute substitution pressure from hardened polymer mail-back containers, while electrical systems deepen their hospital installed base through software integration mandates.
- Electrical:Electromechanical units with embedded cycle logging automate EPA manifest documentation for high-volume generators. Demand concentrates in United States integrated delivery networks where OSHA audit trails justify capital expenditure over recurring hauler contracts.
- Manual:Hand-operated shear or clip mechanisms require no electrical infrastructure and deploy in ambulatory settings with severe capital constraints. Small clinics in rural Texas and Florida substitute these with mail-back polymer containers when municipal biohazard pickup proves unreliable.
- Portable:Battery-powered units address sharps accumulation in home healthcare settings where patients self-administer infusion therapy. Compact housings trade destruction capacity for mobility, appealing to visiting nurse services in California's dispersed suburban markets.
- Fixed:Permanently installed thermal or plasma systems anchor central sterile supply departments in tertiary care facilities. These units require 480V three-phase electrical infrastructure, limiting deployment to newer construction or renovation-funded projects.
Electrical systems anchor the volume base while portable units gain share at the steepest rate as home healthcare expands.
End User:
Procurement authority varies sharply across customer types, with hospitals consolidating vendor relationships and laboratories demanding specialized throughput specifications.
- Hospitals:Acute care networks standardize on integrated destruction systems with automated documentation software. United States health systems with fifteen-plus facilities favor service contracts bundling equipment placement with preventive maintenance.
- Clinics:Outpatient facilities balance capital budgets against regulatory exposure, often selecting manual devices or outsourcing to regional haulers. German and French clinic procurement now specifies EU MDR-compliant containment housings.
- Laboratories:High-throughput research and diagnostic facilities drive adoption of microwave plasma technology with sub-four-minute cycle times. Academic medical centers in Boston and San Francisco pilot these units for surgical suite integration.
- Pharmacies:Retail vaccination sites accumulate lower sharps volumes and favor compact electrical units or mail-back logistics. Chain pharmacies in California face state-level substitution mandates that accelerate equipment replacement cycles.
Hospitals dominate absolute procurement value while laboratories expand most quickly through technology upgrade cycles.
Technology:
Energy efficiency standards and REACH chemical restrictions are forcing material and thermal design revisions across technology platforms.
- Microwave:Plasma-based sterilization achieves organic matrix decomposition at reduced energy consumption versus resistive heating. Laboratory adoption climbs fastest where electricity costs and carbon accounting carry procurement weight.
- Thermal:Conventional resistive heating to 1,200°C-plus remains the hospital workhorse for needle melting and blade neutralization. Stainless steel chamber alloys face nickel price volatility that compresses manufacturer margins.
- Chemical:Neutralization systems using chlorine or enzyme treatments serve specialized waste streams with mixed organic content. Limited penetration reflects disposal complexity of spent chemical reagents under EPA hazardous waste rules.
- Mechanical:Shearing and grinding mechanisms achieve particle sizes below 2mm to eliminate puncture risk. FDA 510(k) clearance timelines averaging fourteen months delay commercialization for novel shear geometries.
Thermal technology retains the largest installed base while microwave systems climb fastest on energy efficiency metrics.
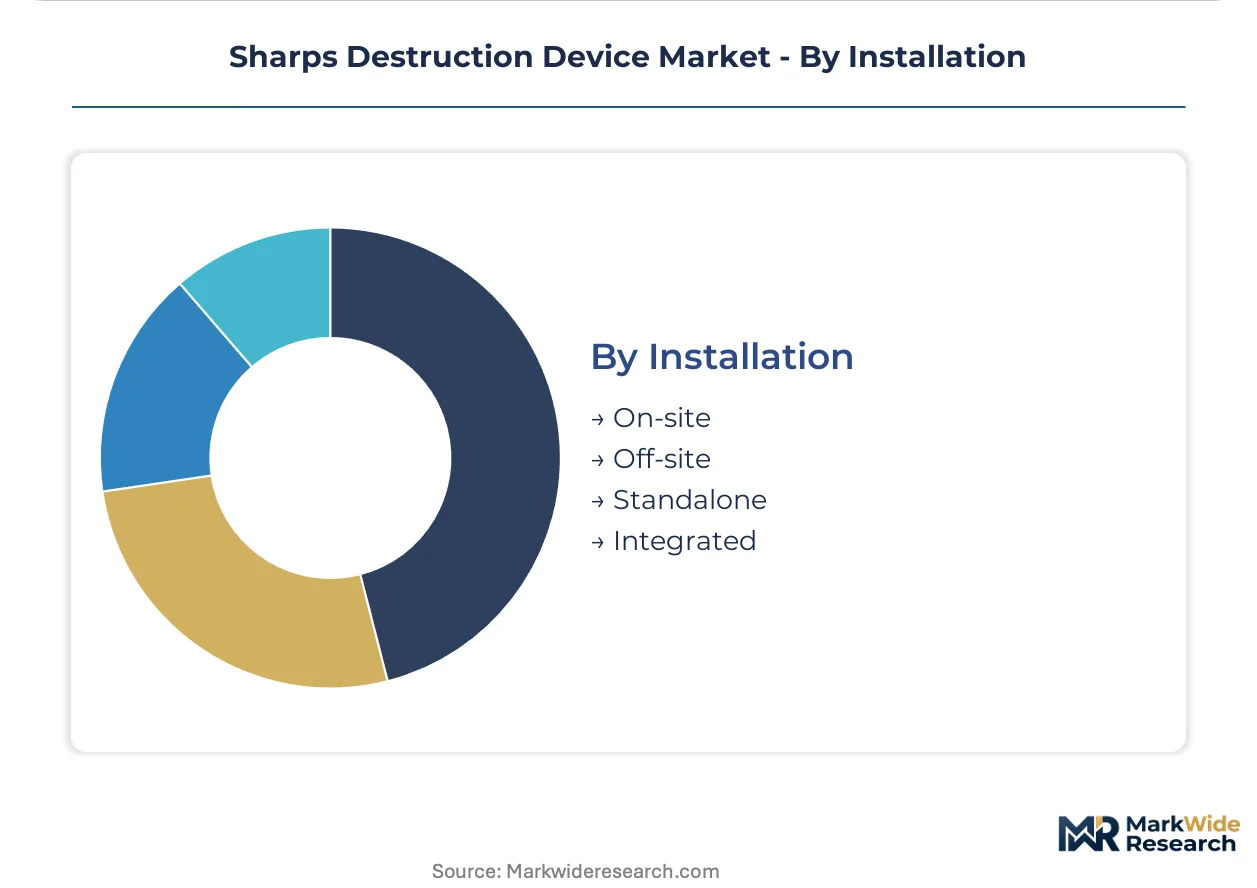
Installation:
Capital availability and facility vintage determine whether customers own destruction assets or outsource treatment liability.
- On-site:Point-of-use destruction eliminates manifest documentation for off-site transport and treatment. United States hospital emergency departments and surgical suites prioritize this configuration under OSHA exposure control mandates.
- Off-site:Centralized treatment through regional haulers persists where capital budgets preclude equipment acquisition. This model faces margin pressure from rising transportation costs and documentation automation requirements.
- Standalone:Independent units without network connectivity serve small facilities with basic compliance needs. These systems lack the automated logging that integrated delivery networks now require for multi-site standardization.
- Integrated:Networked destruction systems feed data directly into EPA hazardous waste generator logs and hospital inventory management platforms. California and Texas health systems lead adoption of this service-bundled structure.
On-site installation anchors procurement volume while integrated systems gain share fastest through software-linked compliance automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA bloodborne pathogen standards anchor procurement patterns in the United States, where hospital networks are consolidating point-of-use destruction systems. Divergent regulatory timelines across major economies are creating asynchronous replacement cycles that favor established suppliers with multi-market certification capabilities.
United States
Integrated delivery networks with fifteen-plus facilities are standardizing on electromechanical destruction systems with automated EPA manifest documentation. OSHA enforcement of exposure control plans mandates point-of-use treatment in emergency departments and surgical suites. Texas and California health systems lead adoption of service-bundled structures linking equipment placement to compliance software subscriptions.
Germany
Hospital procurement consortiums are specifying RoHS-compliant polymer containment housings in tender specifications, accelerating supplier qualification bottlenecks. EU MDR technical documentation requirements for containment systems are driving replacement of legacy units ahead of federal deadlines. The Baden-Württemberg medical technology cluster is piloting plasma arc installations in tertiary care central sterile supply departments.
France
ANSM oversight of medical device safety is tightening documentation requirements for sharps containment systems in public hospital networks. REACH chemical restriction amendments are phasing out halogenated flame retardants in portable device casings, forcing eighteen-month material qualification cycles. The Île-de-France academic medical center network is evaluating microwave plasma technology for laboratory integration.
India
Tertiary care expansion in Maharashtra and Karnataka is opening procurement channels for Class B medical devices under CDSCO harmonized quality standards. Central government biohazard waste management rules are mandating on-site treatment capacity for hospitals exceeding defined bed thresholds. The Delhi-NCR corridor is seeing concentrated demand for manual portable units in outpatient clinics with severe capital constraints.
Japan
METI energy efficiency guidelines are favoring microwave-based sterilization systems in high-throughput diagnostic laboratories. PMDA device clearance pathways for electromechanical systems are extending commercialization timelines for novel shear mechanisms. The Kanto region's academic medical centers are piloting integrated documentation systems linking destruction cycles to inventory management platforms.
Sharps Destruction Device Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with scaled service infrastructure providers commanding integrated delivery network contracts while polymer engineering specialists capture premium positioning on material compliance. The market structure bifurcates between national-scale incumbents bundling device placement with recurring service contracts and mid-cap specialists differentiating on thermal design or containment housing innovation. Three archetypes dominate: waste management service integrators, medical device manufacturers with backward integration into needle production, and polymer engineering houses. Competitive moves concentrate on strategic partnerships for software-integrated documentation and geographic expansion through distributor networks in tertiary care expansion zones.
Within the waste management service tier, Stericycle exemplifies the bundled-contract archetype, anchoring multi-site standardization through national infrastructure. Among medical device manufacturers, Becton, Dickinson and Company occupies a position representing lifecycle control from needle production through destruction system placement. On the materials specialization vector, Nolato AB sits within the polymer engineering tier, differentiating on REACH-compliant containment housing formulation rather than mechanical system design. These three anchors illustrate the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Stericycle |
| Becton, Dickinson and Company |
| Nolato AB |
| Seton |
| Safety First Aid Group Ltd |
| GPC Medical |
| RedHawk Holdings Corp |
| Surgitech |
| Thermofisher Scientific |
| Others |
Value Network & Pricing Analysis
Fourteen-month FDA 510(k) clearance timelines compress supplier margins by extending capital recovery periods, concentrating pricing power with established manufacturers holding multi-market certifications while forcing new entrants toward lower-margin manual device tiers.
Pricing Analysis
United States hospital procurement commands 35-50% premiums over Indian clinic markets for equivalent electromechanical units. Three-tier pricing structure across premium, standard, and economy levels separates integrated software-bundled systems from standalone thermal units and manual portable devices. Cost compression in economy tiers intensifies because hardened polymer mail-back containers substitute low-capacity destruction demand. Small rural clinics exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
China and Germany anchor stainless steel chamber fabrication and precision polymer molding respectively. Device assembly draws from nickel-alloy inputs for thermal chambers, polycarbonate blends for containment housings, and embedded control systems from semiconductor foundries. Single-source vulnerability concentrates in specialized biomedical electromechanical engineering talent pools. Distribution runs through GPO contracts for hospital networks and regional medical distributors for ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against hardened polymer mail-back logistics threatening low-capacity device demand, requiring strategic repositioning toward software-integrated service contracts.
For Market Incumbents: Compound defensive positioning through backward integration into needle manufacturing supply chains and captive software development for EPA manifest automation. Hardened polymer container substitution threatens manual device revenue streams. Certification investment in EU MDR technical documentation creates switching costs against emerging competitors. For New Entrants and Emerging Players: Software-layer gaps in automated compliance documentation for mid-size clinic chains offer white-space entry. Home healthcare infusion therapy represents the most penetrable segment. Target visiting nurse services with battery-powered portable units through direct clinical educator channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized medical device divisions. Long-term viability centers on regulatory compliance automation capabilities rather than hardware differentiation. Watch CDSCO pathway harmonization progress in Indian tertiary care expansion zones as inflection indicator for emerging market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Integrated Documentation Development | Automated EPA manifest generation links destruction cycles to hazardous waste generator logs for hospital networks. |
| EU MDR Technical Documentation Investment | CE marking pathway acceleration captures replacement demand from legacy unit phase-outs in German procurement. |
| Hospital System Partnership | Multi-site service contracts standardize equipment placement across integrated delivery networks in Texas and California. |
| Plasma Arc Technology Licensing | Energy-efficient sterilization at 1,400°C enables surgical suite integration in space-constrained central sterile supply departments. |
| REACH-Compliant Polymer Reformulation | RoHS-compliant containment housings satisfy eighteen-month qualification cycles for European tender specifications. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and sharps waste compliance officers and refined through secondary validation against FDA 510(k) clearance databases, EPA hazardous waste generator reports, EU MDR technical documentation filings, and hospital procurement contract records. Bottom-up installed base estimates triangulated against top-down healthcare capital expenditure flows.
Variance decomposition across technology segments, end-user facility types, installation configurations, and regional regulatory clusters shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated OSHA enforcement intensity trajectories, nickel price volatility bands, and CDSCO harmonization progress indicators.
Forecasts assume regulatory continuity in OSHA bloodborne pathogen standards, EU MDR implementation timelines, and EPA hazardous waste generator rules; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in enforcement patterns, alloy input costs, and substitution technology penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Pancreas Market
Medical Devices
Silastic Implant Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
Global Hi-Tech Medical Devices Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Global Cardiac Resuscitation Device Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Steam Inhaler Devices Market