
 Australia and New Zealand Tomato Sauce Market | 2026-2036
Australia and New Zealand Tomato Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Tomato Sauce Market Analysis
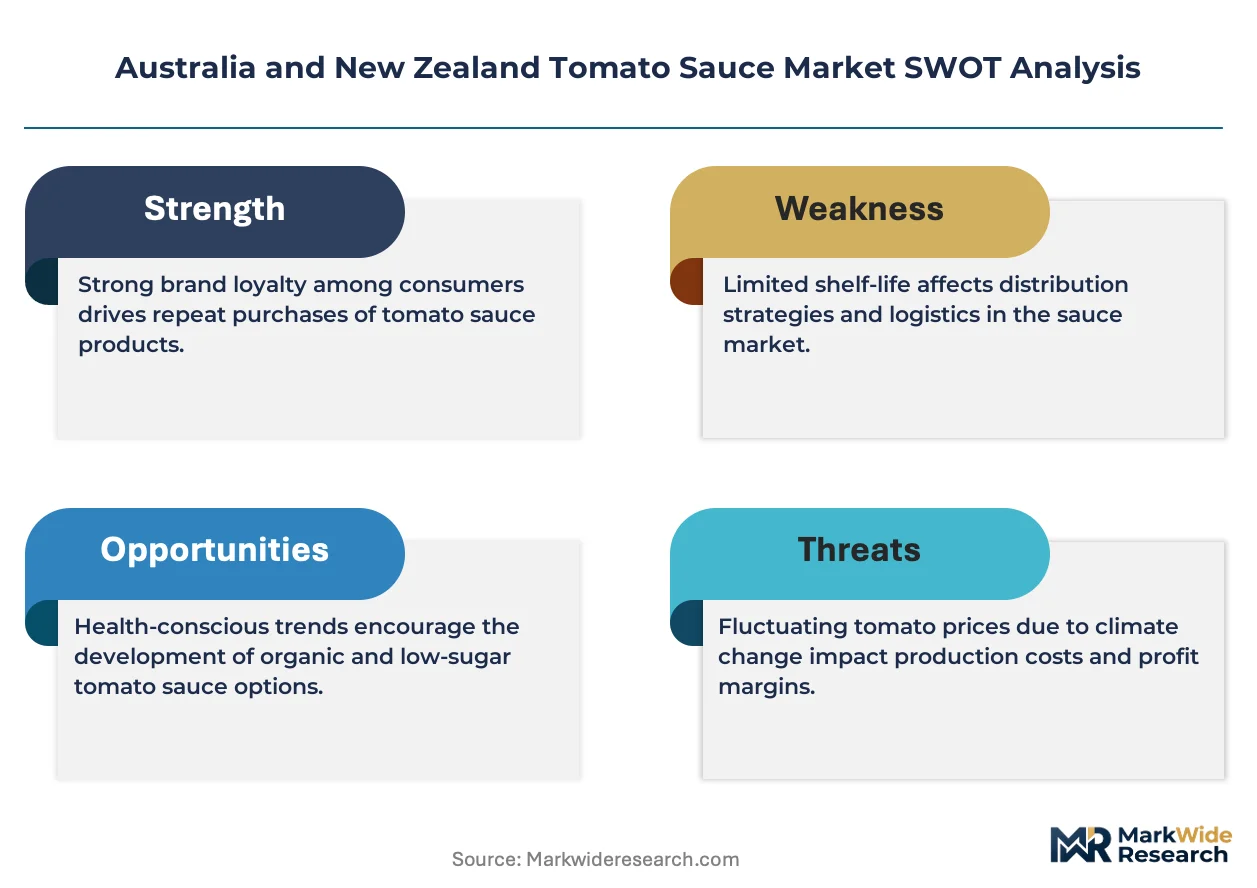
Food processing labor shortages across regional Victoria and Queensland is unwinding manufacturing capacity for tomato sauce producers. Kraft Heinz Company anchors its Oceania supply chain through established distribution networks spanning both countries. Beerenberg Pty Ltd differentiates through premium positioning tied to Barossa Valley provenance and small-batch production heritage. Spring Gully Foods Pty Ltd competes on heritage brand recognition and South Australian manufacturing loyalty.
Australia and New Zealand tomato sauce denotes a cooked, seasoned tomato-based condiment typically containing 15-30% tomato solids, vinegar, sugar, salt, and spices, manufactured through evaporation and pasteurization to achieve shelf-stable acidity below pH 4.6. The product serves as a table condiment, cooking ingredient, and foodservice portion-control item across retail and commercial channels. Organic variants command premium shelf positioning as health-conscious households shift ingredient scrutiny toward pesticide residues and additive content. Foodservice packaging in sachets and pouches captures margin pools through volume contracts with quick-service restaurant chains and institutional catering operators. Conventional bottled formats sustain supermarket dominance through price accessibility and familiar brand loyalty among mainstream consumers.
Food Standards Australia New Zealand governs compositional standards, additive permissions, and nutrition labelling under the Australia New Zealand Food Standards Code, directly influencing reformulation costs and claim eligibility for reduced-sugar variants. Biosecurity Australia and New Zealand's Ministry for Primary Industries enforce import conditions on tomato paste and concentrate, shaping raw material sourcing strategies and seasonal procurement timing. Manufacturers must monitor evolving sustainability packaging mandates from the Australian Packaging Covenant Organisation and New Zealand's proposed container return schemes, which will alter material selection and cost structures for bottles and flexible formats.
Market Dynamics
Food Standards Australia New Zealand's tightened labelling mandates for added sugars are forcing wholesale reformulation across the condiment sector, compressing margin structures while accelerating clean-label R&D cycles among established manufacturers.
Growth Catalysts
- Foodservice expansion:Quick-service restaurant chains across Sydney and Auckland are diversifying tomato-based condiment applications, driving volume contracts for portion-control sachets and pouches.
- Clean-label regulation:FSANZ sugar disclosure requirements are pulling reformulation investment toward reduced-sugar variants with claim-eligible nutritional profiles.
- Eastern seaboard concentration:Australia's New South Wales and Victoria states sustain demand density through population clustering and institutional catering penetration.
Market Restraints
- Input cost volatility:Tomato paste and concentrate prices fluctuate with biosecurity import conditions enforced by Biosecurity Australia and New Zealand's Ministry for Primary Industries.
- Regional labor scarcity:Food processing workforce shortages across regional Victoria and Queensland are constraining manufacturing throughput for domestic producers.
- Packaging mandate compliance:Australian Packaging Covenant Organisation sustainability targets and New Zealand's proposed container return schemes will elevate material costs for rigid and flexible formats.
Strategic Opportunities
- Organic premium tier:Health-conscious households in Australian metropolitan markets are shifting scrutiny toward pesticide residues, opening shelf-space for certified organic variants.
- Heritage provenance positioning:South Australian and Barossa Valley geographic indications offer differentiation vectors against mass-market competitors through small-batch production narratives.
- Reformulation R&D:FSANZ compliance timelines create first-mover advantages for manufacturers achieving clean-label certification ahead of enforcement deadlines.
Industry Challenges
- Biosecurity procurement timing:Seasonal import condition variations for tomato concentrate require sophisticated inventory management to avoid raw material shortfalls.
- Reformulation capex cycles:Achieving pH stability below 4.6 while reducing sugar content demands capital investment in modified evaporation and pasteurization equipment.
- Multi-jurisdiction compliance:Dual-track adherence to Australian Packaging Covenant Organisation and forthcoming New Zealand container scheme rules complicates unified supply chain design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Tomato Sauce Market |
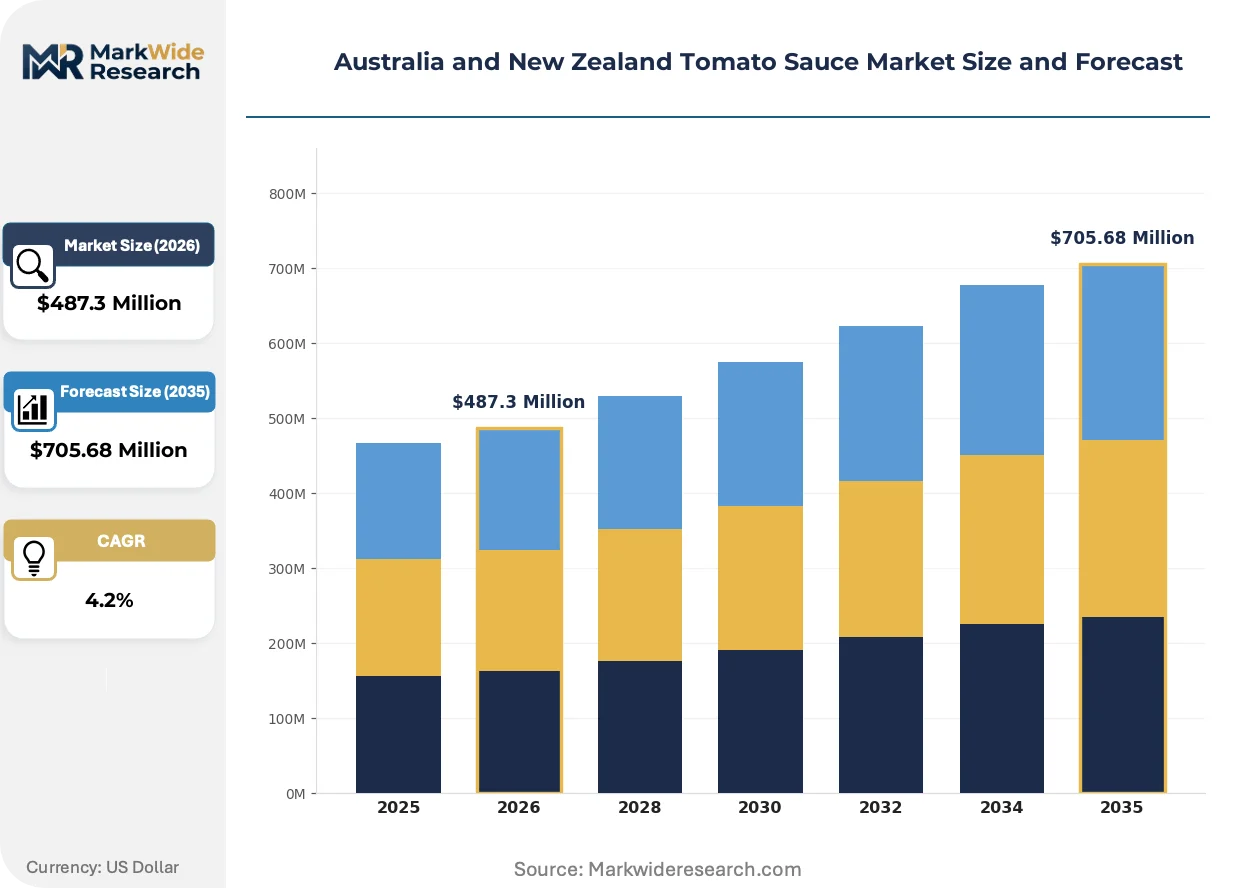
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $705.68 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Low Sugar, Spicy Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Foodservice Packaging Type: Bottles, Sachets, Cans, Pouches End User: Households, Restaurants, Food Manufacturers, Catering Services |
| Companies Covered | J.R. Simplot Company, Spring Gully Foods Pty Ltd., Kraft Heinz Company, KAGOME Australia Pty Ltd., SPC Ardmona, Mars, Incorporated, Beerenberg Pty Ltd., Wilmar International Ltd., Goodman Fielder Pty Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Tomato Sauce Market Emerging Trajectories
Reformulation chemistry and packaging material science are converging to reshape competitive positioning, as regulatory pressure intersects with sustainability mandates and shifting household ingredient scrutiny.
High-pressure processing and cold-fill aseptic technologies are supplanting traditional hot-fill pasteurization in premium sauce manufacturing. Barossa Valley and Adelaide Hills producers are adopting these methods to preserve volatile aromatic compounds in reduced-sugar formulations. This shift is compressing shelf-life differentials between conventional and clean-label products while enabling vinegar-reduced recipes that meet FSANZ acidity standards.
FSANZ Standard 1.2.8 nutrition labelling requirements are mandating added sugars disclosure in the nutrition information panel. Manufacturers must now reformulate or sacrifice front-of-pack claim eligibility, particularly affecting products positioned toward health-conscious segments. The eastern seaboard retail channel is responding with accelerated SKU rationalization, delisting non-compliant variants ahead of enforcement phases.
Ingredient transparency is reshaping household purchase criteria beyond the traditional price-accessibility calculus. Australian supermarket private-label buyers are now cross-referencing additive content against environmental working group databases, displacing brand loyalty with certification-driven selection. This pattern concentrates in Queensland and New South Wales metropolitan corridors, where digital-native consumer segments exhibit highest engagement with clean-label verification platforms.
Australia and New Zealand Tomato Sauce Market Segmentation
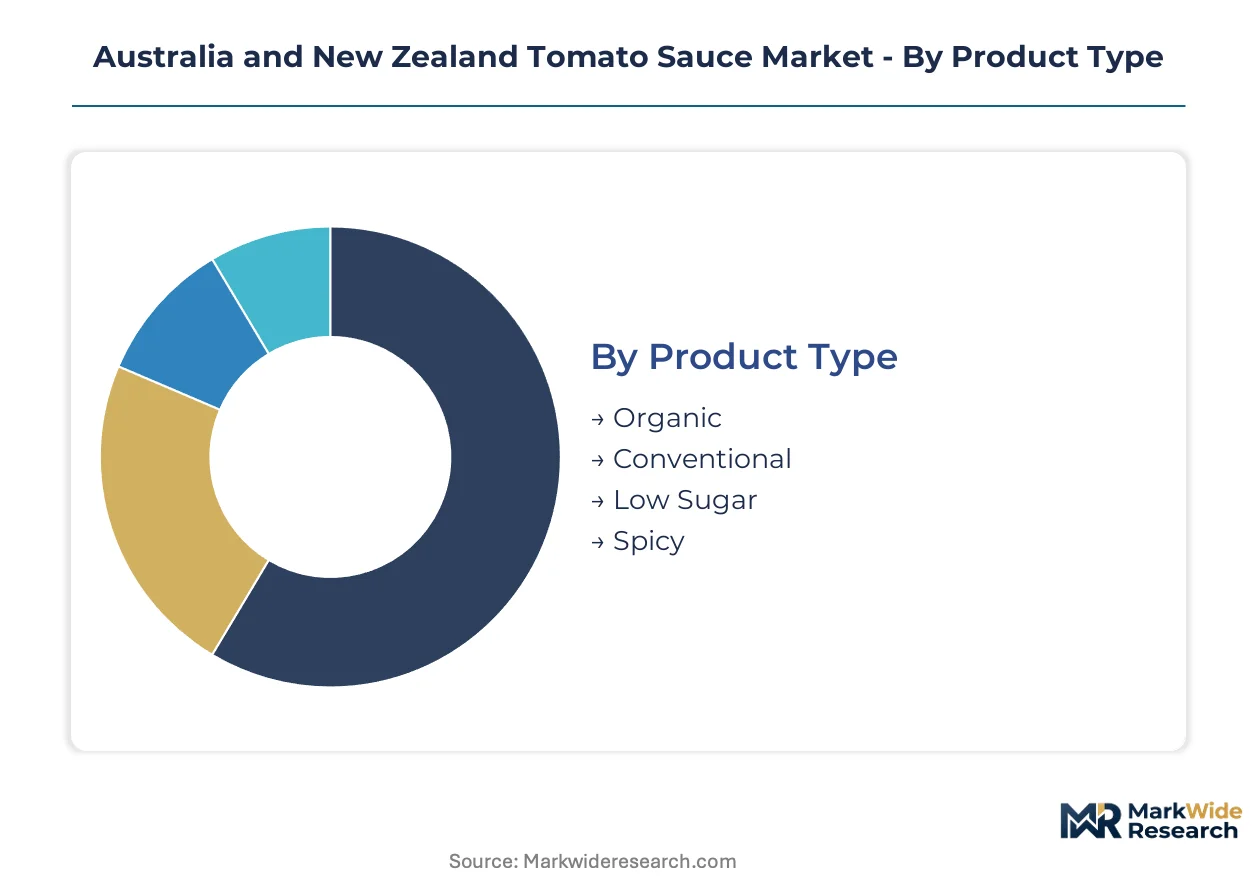
Tomato sauce segmentation in Australia and New Zealand reflects divergent pressure points from regulatory reformulation mandates, foodservice channel expansion, and shifting household ingredient scrutiny. Understanding where substitution threats concentrate enables manufacturers to prioritize R&D investment and channel resource allocation.
Product Type:
Conventional variants face acute substitution pressure from clean-label alternatives as FSANZ sugar disclosure requirements reshape retail shelf dynamics.
- Conventional:Standard formulations with 15-30% tomato solids, vinegar, sugar, salt, and spices manufactured through traditional evaporation and pasteurization. Demand concentrates in Queensland and New South Wales supermarkets where price accessibility sustains volume among mainstream households despite accelerating SKU rationalization.
- Organic:Certified organic tomato solids processed without synthetic pesticides or additives, commanding premium positioning in metropolitan Australian retail. Adoption concentrates in Sydney and Melbourne health-conscious segments where Barossa Valley provenance credentials support price premiums above conventional tiers.
- Low Sugar:Reformulated variants achieving FSANZ claim-eligible nutritional profiles through modified acidity management and alternative sweetening systems.
- Spicy:Heat-infused formulations incorporating chili, pepper, or regional spice blends targeting experimental cooking applications and younger demographic trial.
Conventional retains volume leadership; organic holds the steepest expansion curve.
Distribution Channel:
Channel cost structures vary sharply, with foodservice contracts delivering volume certainty at compressed margins while direct-to-consumer pathways capture premium pricing.
- Supermarkets:Dominant retail channel spanning Coles, Woolworths, and independent grocers across eastern seaboard states. Shelf-space allocation increasingly favors FSANZ-compliant variants as private-label buyers cross-reference additive databases against certification platforms.
- Foodservice:Volume contracts with quick-service restaurant chains, institutional catering operators, and Sydney-Auckland hospitality groups driving sachet and pouch procurement. Margin pools concentrate in portion-control specifications where manufacturing scale offsets per-unit pricing pressure.
- Online Retailers:Direct-to-consumer and marketplace platforms enabling subscription models and bulk purchasing for metropolitan households.
- Convenience Stores:Impulse-oriented channel capturing travel and immediate-consumption occasions with smaller format bottles and single-serve packaging.
Foodservice captures volume concentration; online retail gains share fastest through metropolitan subscription adoption.
Packaging Type:
Material selection increasingly hinges on Australian Packaging Covenant Organisation sustainability targets and New Zealand's proposed container return scheme compliance costs.
- Bottles:Rigid glass and plastic formats sustaining supermarket dominance through familiar handling characteristics and shelf stability. Eastern seaboard retail concentration drives standardized bottle specifications, though APCO mandates are elevating recycled content requirements and cost structures.
- Sachets:Single-serve flexible formats capturing foodservice margin pools through portion-control contracts with quick-service chains. Sydney and Auckland restaurant expansion sustains volume growth despite higher per-unit material costs versus bulk alternatives.
- Pouches:Stand-up and spouted flexible formats targeting household convenience and reduced shipping weight in online retail channels.
- Cans:Metal formats retaining niche positioning in institutional catering and bulk food manufacturing applications.
Bottles retain volume leadership; pouches climb the fastest through e-commerce channel expansion.
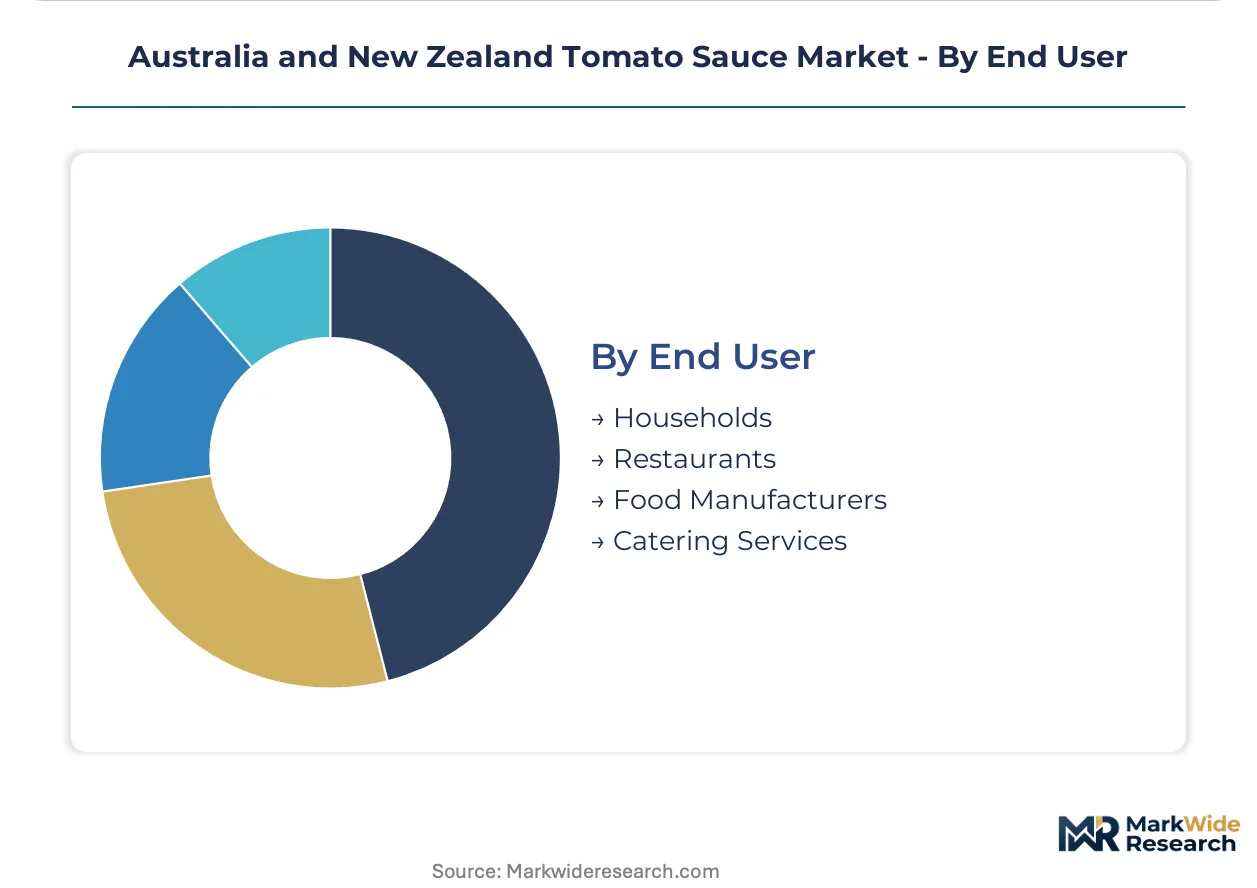
End User:
User segmentation maps directly to application intensity, with commercial operators demanding specification consistency and households prioritizing ingredient transparency.
- Households:Residential consumers across Australian metropolitan corridors and New Zealand urban centers driving retail purchase decisions. Queensland and New South Wales digital-native segments exhibit highest engagement with clean-label verification platforms, displacing traditional brand loyalty.
- Restaurants:Full-service and quick-service operators across Sydney and Auckland diversifying tomato-based condiment applications. Menu innovation sustains volume contracts for specialized formulations and portion-control formats.
- Food Manufacturers:Industrial purchasers integrating tomato sauce as input ingredient for processed foods, ready meals, and sauce-based products.
- Catering Services:Institutional and event-based operators requiring bulk formats and consistent supply scheduling for high-volume service occasions.
Households retain volume leadership; restaurants gain share fastest through menu application diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's eastern seaboard states consume tomato sauce predominantly through foodservice channels, while New Zealand households favor retail formats with stronger provenance storytelling.
New South Wales
Sydney's quick-service restaurant chains drive sachet and pouch procurement through volume contracts with institutional catering operators. Food Standards Australia New Zealand mandates added sugars disclosure on all retail packaging, forcing reformulation timelines for manufacturers supplying Coles and Woolworths. The Sydney metropolitan corridor concentrates demand density through population clustering and hospitality sector expansion.
Victoria
Melbourne's metropolitan households exhibit highest engagement with clean-label verification platforms, displacing traditional brand loyalty with certification-driven selection. Biosecurity Australia enforces seasonal import conditions on tomato concentrate, complicating raw material procurement for processors in regional Victoria. Food processing labor shortages across Gippsland and the Murray Valley are constraining manufacturing throughput for domestic producers.
Queensland
Brisbane and Gold Coast retail channels sustain conventional format dominance through price accessibility among mainstream households. The Australian Packaging Covenant Organisation mandates recycled content requirements for rigid packaging, elevating material cost structures for bottle specifications. Southeast Queensland's digital-native consumer segments cross-reference additive content against environmental databases with highest frequency nationally.
South Australia
Adelaide Hills and Barossa Valley producers leverage geographic indication credentials to command premium positioning in metropolitan Australian retail. Small-batch manufacturing heritage supports differentiation against mass-market competitors through provenance narratives tied to regional identity. The state's manufacturing loyalty sustains heritage brand recognition for established condiment processors.
New Zealand
Auckland's restaurant chains diversify tomato-based condiment applications across menu categories, driving specialized formulation contracts. The Ministry for Primary Industries enforces biosecurity import conditions on tomato paste, shaping seasonal procurement timing for domestic manufacturers. New Zealand's proposed container return scheme will alter material selection and cost structures for bottles and flexible formats entering the market.
Australia and New Zealand Tomato Sauce Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational condiment conglomerates anchoring supply chain scale while regional heritage brands occupy premium positioning vectors. Market structure reflects dual-track consolidation: volume-driven players secure foodservice contracts through manufacturing scale, while provenance-focused specialists capture metropolitan retail premiums. Three archetypes dominate: integrated multinationals with Oceania distribution networks, heritage regional manufacturers with geographic indication credentials, and private-label suppliers serving supermarket chains. Competitive moves concentrate on reformulation R&D for FSANZ compliance and sustainable packaging transitions ahead of APCO deadlines.
Among integrated multinationals, Kraft Heinz Company anchors supply chain scale across both countries, while KAGOME Australia Pty Ltd exemplifies the transnational specialist archetype with regional manufacturing presence. Heritage positioning is occupied by Spring Gully Foods Pty Ltd and Beerenberg Pty Ltd, representing the Barossa Valley and South Australian provenance tier. These three entities collectively illustrate the competitive tension between scale-driven foodservice penetration and premium retail differentiation through geographic storytelling.
| Leading Market Players |
|---|
| J.R. Simplot Company |
| Spring Gully Foods Pty Ltd. |
| Kraft Heinz Company |
| KAGOME Australia Pty Ltd. |
| SPC Ardmona |
| Mars, Incorporated |
| Beerenberg Pty Ltd. |
| Wilmar International Ltd. |
| Goodman Fielder Pty Ltd. |
| Others |
Supply Flow & Price Mechanics
Food Standards Australia New Zealand's clean-label certification gates both supplier qualification and price-tier eligibility, forcing manufacturers to invest in reformulation infrastructure before accessing premium shelf positioning or foodservice contract tiers. This regulatory threshold compresses margins for non-compliant producers while enabling certified players to command measurable price premiums in metropolitan retail channels.
Pricing Analysis
Long-term offtake contracts with quick-service restaurant chains anchor volume pricing for sachet and pouch formats, while spot procurement for tomato concentrate introduces quarterly cost volatility that squeezes margin predictability. Three-tier pricing structure across premium organic, standard clean-label, and conventional economy levels separates Barossa Valley provenance products from mass-market alternatives through certification grade and geographic storytelling. Pricing pressure stems from FSANZ reformulation capex cycles and APCO packaging compliance costs, with cost compression running through the conventional tier most acutely. Mainstream Queensland and New South Wales households exhibit highest price sensitivity, whereas Sydney and Melbourne health-conscious segments accept premiums for organic and low-sugar variants.
Supply Chain Analysis
Inventory lead times for tomato paste and concentrate stretch across seasonal biosecurity windows enforced by Biosecurity Australia and New Zealand's Ministry for Primary Industries, forcing processors to carry buffer stocks through southern hemisphere winter months. Geographic supply concentration centers on Italy, China, and the United States for imported tomato concentrate, with domestic sourcing from Queensland and Victoria processing facilities for fresh tomato inputs. Raw material dependencies hinge on tomato paste, vinegar, sugar, and flexible packaging films. Single-source vulnerability concentrates in Italian paste supply during European harvest shortfalls. Distribution runs through Coles and Woolworths supermarket networks for retail, with direct-to-foodservice contracts bypassing wholesale layers for institutional catering volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping this market as FSANZ's standardized disclosure requirements create interoperability between clean-label verification databases and retailer procurement systems, enabling certification-driven purchasing at scale.
For Market Incumbents: Compound heritage brand equity through accelerated organic certification timelines ahead of FSANZ enforcement phases, locking in premium shelf allocation before SKU rationalization accelerates. Defend foodservice contract renewals by integrating portion-control format innovation with sustainability packaging transitions that meet APCO recycled content mandates. Vertical integration into Barossa Valley tomato cultivation secures provenance credentialing against emerging regional challengers.
For New Entrants and Emerging Players: Direct-to-consumer subscription gaps in metropolitan Melbourne and Sydney represent the most penetrable white-space, where incumbents under-serve digital-native households seeking ingredient transparency beyond supermarket availability. Target online retail channel expansion with pouch-format convenience positioning and bulk purchasing options. A go-to-market angle anchored in carbon-neutral shipping certification differentiates against established brand loyalty.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed condiment specialists holding South Australian manufacturing footprints and heritage brand portfolios. Long-term viability frames around clean-label transition completion and sustainable packaging compliance rather than volume scale alone. Acquisition target archetypes include regional processors with FSANZ-compliant reformulation pipelines and provenance-tied geographic indications. The signal to watch is accelerated delisting velocity for non-compliant SKUs across eastern seaboard retail channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Program | FSANZ sugar disclosure mandates force R&D investment to maintain front-of-pack claim eligibility. |
| Sustainable Packaging Transition | APCO recycled content targets and New Zealand container return schemes elevate material cost structures. |
| Foodservice Contract Expansion | Sydney and Auckland quick-service chain diversification drives volume certainty for portion-control formats. |
| Organic Certification Acceleration | Metropolitan health-conscious households shift purchase criteria toward pesticide-free verification platforms. |
| Heritage Provenance Repositioning | Barossa Valley and Adelaide Hills geographic indications support premium pricing against mass-market competitors. |
Methodological Framework
A spread of perspectives from condiment manufacturing executives, foodservice procurement directors, supermarket category buyers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with supply chain planners at tomato processing facilities and sustainability officers at packaging suppliers anchored demand-side validation. Secondary sources included FSANZ standards documentation, Australian Packaging Covenant Organisation progress reports, Biosecurity Australia import condition databases, and New Zealand Ministry for Primary Industries trade statistics. Bottom-up volume modeling across product type, distribution channel, and end-user segments triangulated against top-down value estimates from customs records and industry association publications.
Segmentation dimensions modeled encompassed product type tiers, packaging material categories, and regional demand clusters across the projection horizon. Analytical framework development applied elasticity-adjusted growth coefficients derived from historical volume patterns and regulatory phase-in schedules. CAGRs were computed through iterative convergence of demand-side adoption curves and supply-side capacity constraints. Industry-specific forecast inputs included seasonal tomato harvest variability, biosecurity inspection throughput rates, and foodservice contract renewal cycles.
Underlying assumptions cover FSANZ enforcement adherence timelines, APCO recycled content compliance trajectories, and stable biosecurity import conditions, with deviation risk concentrated in regulatory delay scenarios and tomato concentrate price spikes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
UK Prepared Mustard Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Latin America Pasta Sauce Market