
 Tomato Processing Market | 2026-2036
Tomato Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Tomato Processing Market Intelligence
California's Central Valley is reconfiguring processing capacity around drought-adaptive agriculture. Morning Star leverages vertical integration from field to can to control paste quality and supply timing. Conagra Brands anchors North American retail shelf presence through brand strength in sauces and diced products. Olam International extends sourcing networks across multiple growing regions to navigate climate volatility.
Tomato processing encompasses the industrial transformation of fresh tomatoes into shelf-stable products through thermal treatment, concentration, and preservation techniques. Hot break processing preserves pectin content for thicker paste viscosity, while cold break methods retain brighter color and fresher flavor for sauce applications. Tomato paste dominates value capture due to its role as an input across food manufacturing, while tomato sauce competes on branded retail differentiation. The food service end user segment leads volume throughput as quick-service chains and institutional kitchens standardize around bulk tomato products.
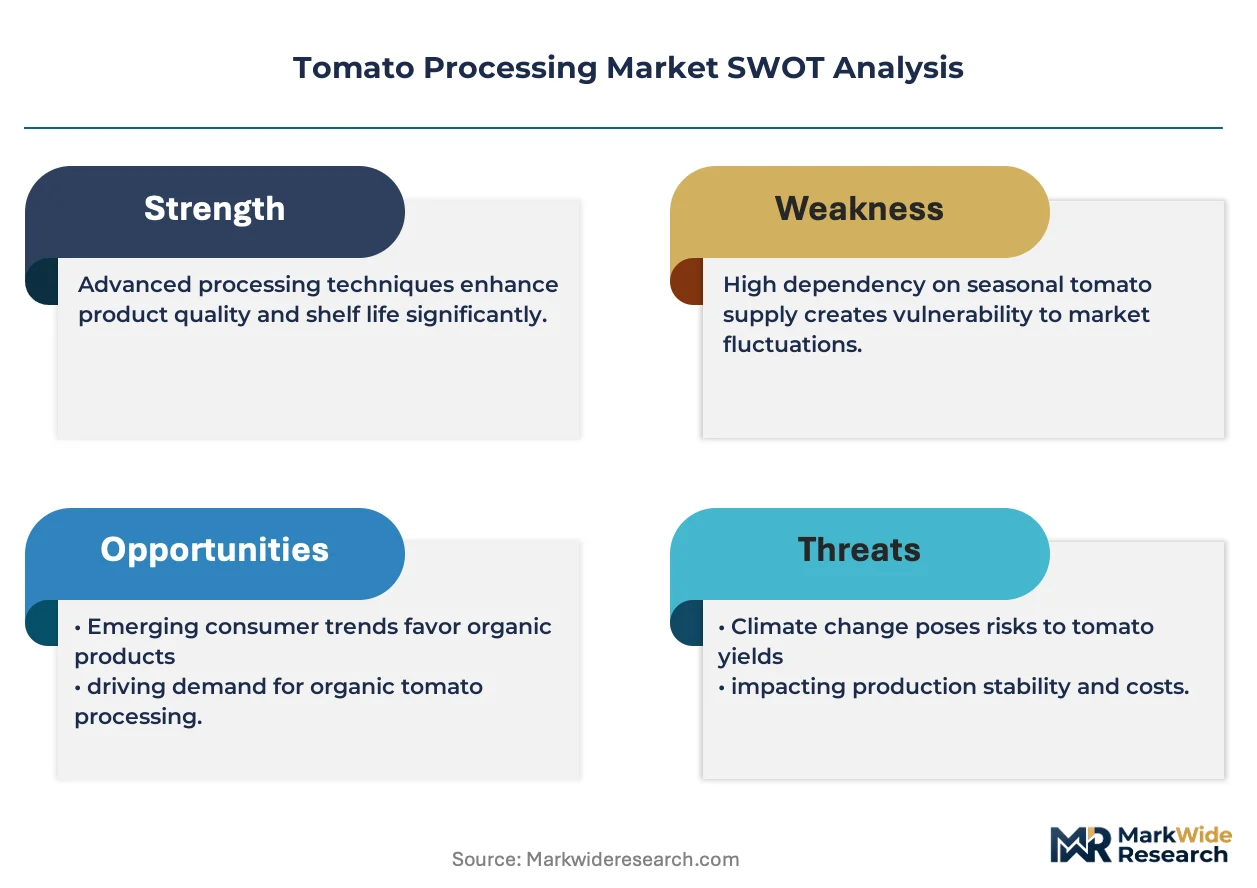
FDA standards for acidified foods and USDA grading protocols shape product specifications and market access for US processors. EU F-Gas Regulation and REACH compliance requirements influence equipment choices and cold-chain packaging across European operations. India's FSSAI safety mandates and BIS quality certifications are tightening as domestic processing scales. Stakeholders must monitor water-right allocations, energy transition costs in thermal processing, and shifting retail-private-label dynamics to calibrate capacity investments.
Market Dynamics
Water scarcity in California's Central Valley is forcing processors to consolidate around drip-irrigation-dependent growing districts and thermal-efficiency retrofits, compressing the viable production geography for bulk paste supply.
Growth Catalysts
- Quick-service restaurant standardization:Chains across India and Southeast Asia are locking in long-term paste contracts to secure sauce consistency for regional menu rollouts.
- FSSAI safety mandate tightening:India's domestic processing capacity is expanding to meet BIS quality certifications previously satisfied by imports.
- Hot break pectin retention:Industrial sauce manufacturers prefer this processing method for viscosity control in bulk manufacturing applications.
Market Restraints
- California water-right allocations:Growers face acreage reductions under state groundwater sustainability mandates, constraining raw material availability.
- Natural gas price volatility:Thermal processing energy costs fluctuate with pipeline capacity constraints and seasonal demand spikes.
- Fresh tomato substitution:Food service operators in premium segments increasingly specify refrigerated crushed tomatoes over shelf-stable alternatives.
Strategic Opportunities
- Sub-Saharan Africa paste demand:Urbanization in Nigeria and Kenya is creating import substitution opportunities for regional processing investment.
- EU F-Gas Regulation compliance:Cold-chain equipment upgrades unlock retrofit service contracts and refrigerant transition advisory revenue.
- E-commerce bulk sourcing:Institutional buyers in India are bypassing traditional distributor tiers through direct processor platform procurement.
Industry Challenges
- Process engineering talent scarcity:Retention of thermal systems specialists lags plant automation deployment timelines.
- Legacy equipment integration:Water-recovery retrofits face compatibility constraints with decades-old evaporator infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tomato Processing Market |
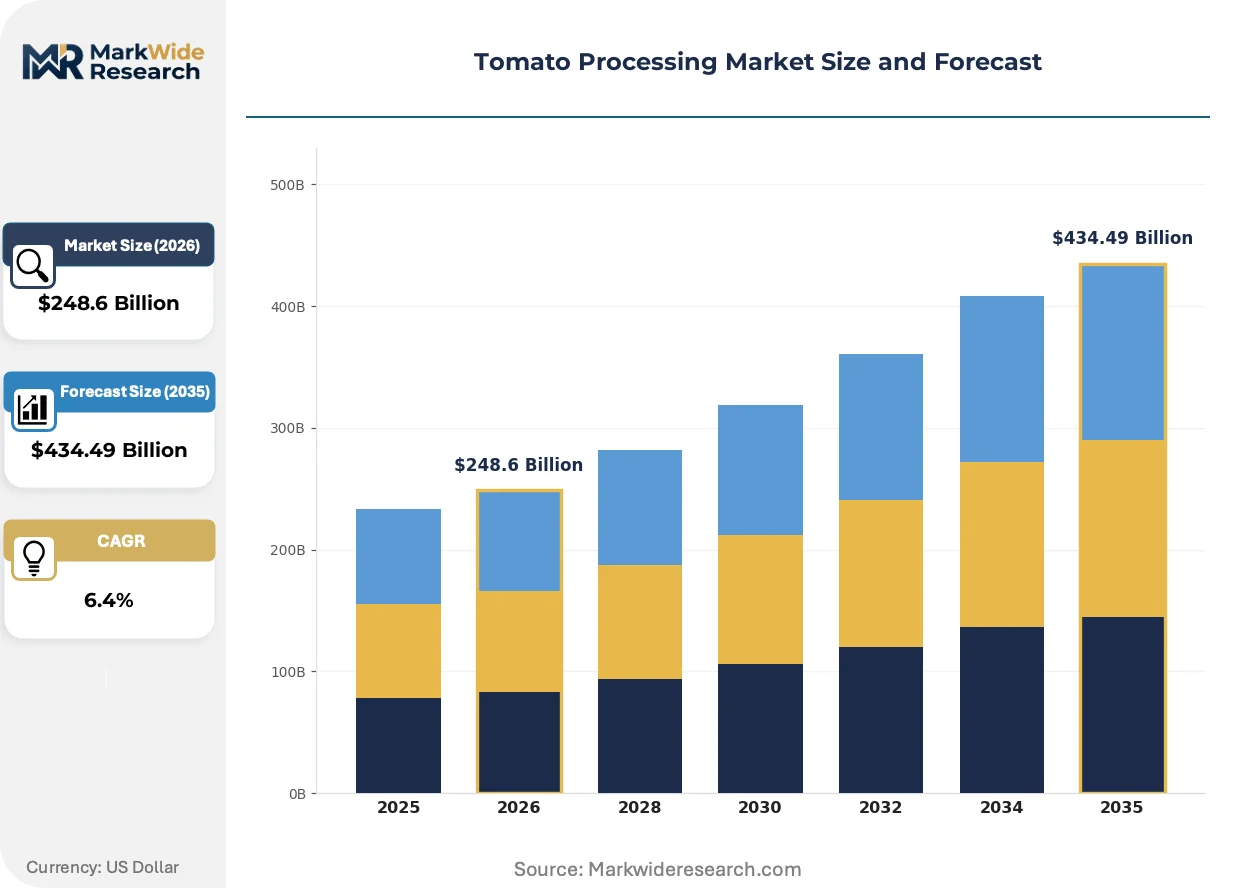
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $434.49 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tomato Paste, Tomato Sauce, Diced Tomatoes, Tomato Juice End User: Food Service, Retail, Industrial, Catering Technology: Hot Break, Cold Break, Dehydration, Freeze Dried Packaging Type: Bottles, Pouches, Cans, Tetra Packs |
| Companies Covered | Conagra Brands, Casalasco Società Agricola, Heinz, Ontario Processing Vegetable Growers, Houwelings International, Olam International, Nestlé, Conserve Italia, Morning Star, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tomato Processing Market Strategic Shifts & Innovations
Processing technology is converging around water and energy efficiency as drought stress and carbon accounting reshape capital allocation decisions across the value chain.
Membrane filtration is collapsing the water-intensity profile of paste concentration operations. Mid-scale processors in water-stressed districts are retrofitting reverse osmosis pre-concentration ahead of thermal finishing, cutting evaporation loads by half. This technology is collapsing the capital barrier between artisan-scale and industrial-volume production.
REACH compliance requirements are redirecting equipment procurement toward stainless steel grades with full material certification chains. European processors now specify 316L with mill test reports for all paste-contact surfaces, disqualifying lower-grade Asian suppliers. Cold-break sauce specialists face the steepest cost adjustments due to stricter temperature-control documentation.
Food service procurement teams are consolidating supplier panels around single-source paste specifications with locked viscosity and color metrics. Distributor networks that previously carried multiple regional brands are narrowing to two approved processors per district. India quick-service chains are driving this consolidation fastest, using centralized procurement hubs to enforce batch-to-batch consistency.
Tomato Processing Market Segmentation
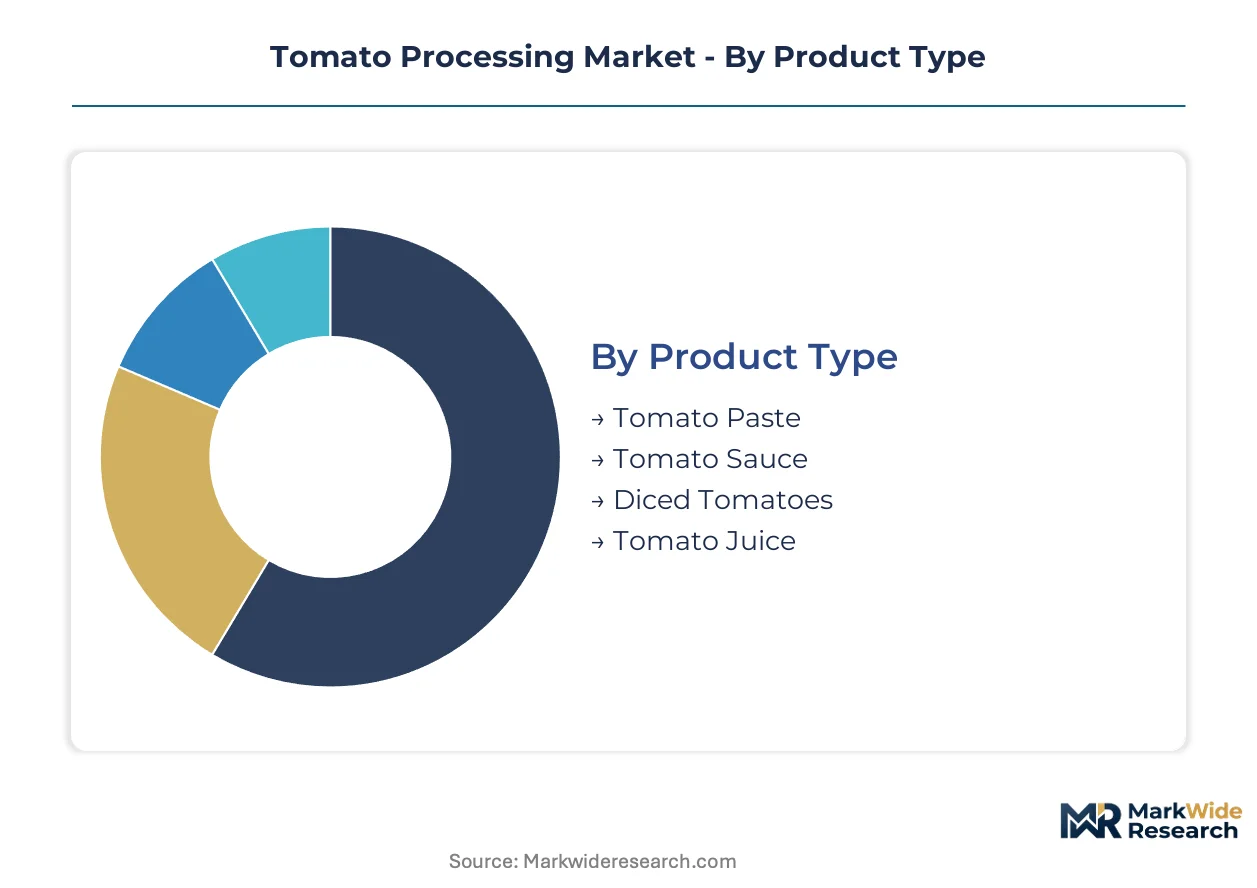
Segmentation in tomato processing reveals how value migrates across product forms and customer channels. Cycle times vary dramatically: food service contracts reset annually while industrial paste agreements span multiple growing seasons. Understanding these velocity differences shapes capacity planning and working capital deployment.
Product Type:
Inventory velocity separates commodity pastes from differentiated sauces, with paste turning fastest due to standardized specifications and sauce holding longer on balance sheets due to brand development cycles.
- Tomato Paste:Concentrated solids ranging from 24% to 36% Brix serve as the foundational input for sauce manufacturing and institutional cooking. Demand concentrates in quick-service chains across India where centralized procurement locks in multi-year contracts for viscosity-standardized product.
- Tomato Sauce:Formulated with seasonings and acidifiers for direct retail or food service use, requiring tighter pH control and color consistency. Premium positioning in North American retail drives reformulation cycles as private-label competition intensifies.
- Diced Tomatoes:Firmness retention through calcium chloride treatment defines quality grades for pizza and pasta applications.
- Tomato Juice:Single-strength or concentrated forms compete in beverage channels with shorter shelf life constraints.
Tomato paste dominates installed base. Tomato sauce is where expansion concentrates.
End User:
Customer type determines margin structure, with industrial buyers extracting volume discounts and food service operators paying premiums for specification reliability.
- Food Service:Quick-service chains and institutional kitchens demand batch-to-batch consistency in viscosity and color metrics. Chains across Southeast Asia are consolidating supplier panels to two approved processors per district to enforce standardization.
- Retail:Branded and private-label shelf-stable products compete on packaging differentiation and placement economics. European supermarkets are narrowing tomato sauce assortments to three price tiers as inflation compresses discretionary spending.
- Industrial:Food manufacturers purchase paste as an ingredient input for soups, condiments, and ready meals.
- Catering:Event and contract food providers seek mid-tier paste and sauce in flexible pack sizes.
Food service commands premium pricing. Industrial volume is climbing the fastest.
Technology:
Capital intensity and energy throughput differentiate processing methods, with hot break requiring heavier evaporator investment and cold break demanding precise temperature control infrastructure.
- Hot Break:Rapid heating to 85-100°C preserves pectin for thicker paste viscosity preferred by industrial sauce manufacturers. California processors are retrofitting evaporator trains to recover water and reduce natural gas exposure under state sustainability mandates.
- Cold Break:Gentle heating below 70°C retains brighter color and fresher flavor for premium sauce applications. REACH compliance documentation for temperature-control equipment is raising capital barriers for European cold-break specialists.
- Dehydration:Moisture removal through heated air circulation produces shelf-stable flakes and powders.
- Freeze Dried:Sublimation preservation maintains cellular structure for premium ingredient applications.
Hot break holds installed capacity leadership. Cold break is where technology investment concentrates.
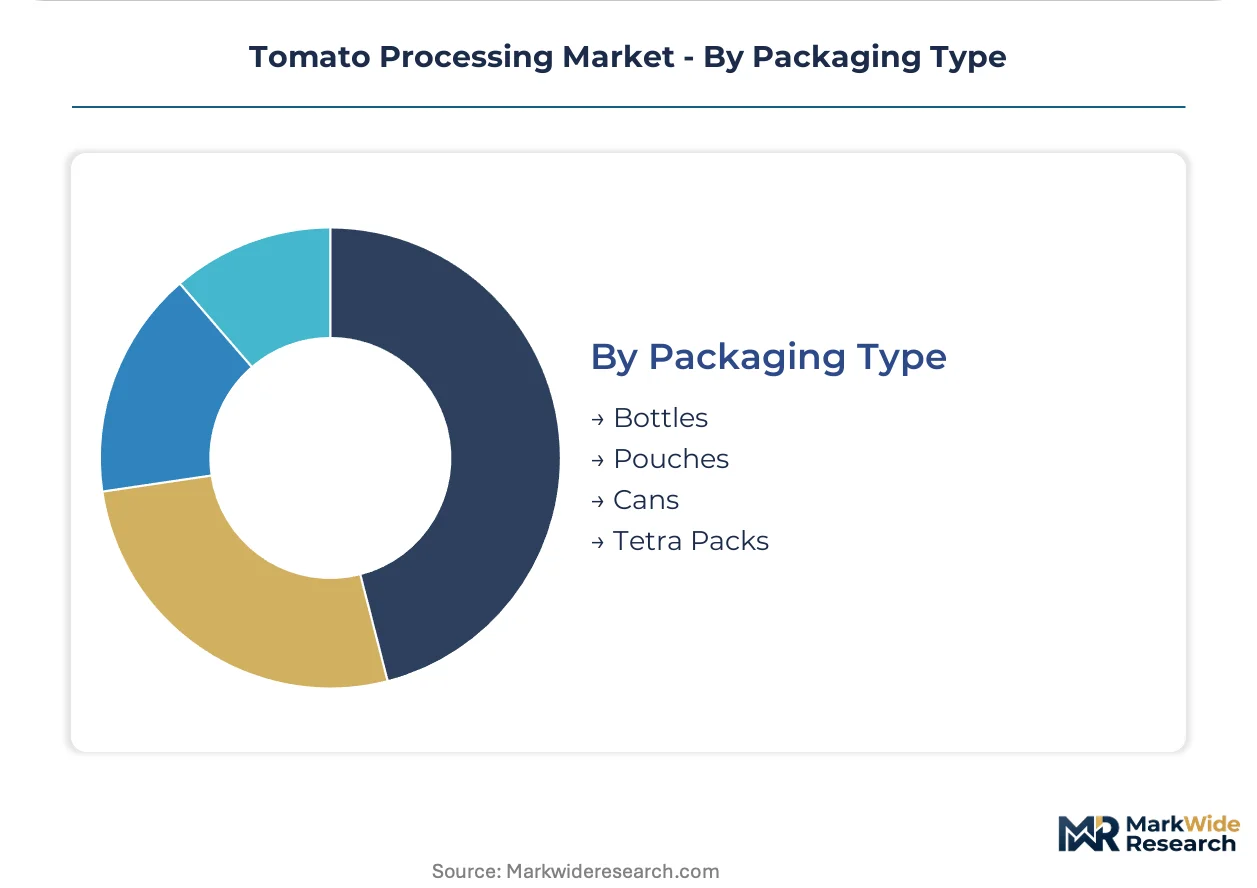
Packaging Type:
Material cost trajectories and shelf-life engineering shape format selection, with metal cans facing aluminum price volatility and flexible pouches requiring barrier film innovation.
- Bottles:Glass and PET containers dominate retail sauce presentation with resealability advantages. Indian e-commerce platforms are driving bottle specification consolidation as direct procurement bypasses traditional distributor tiers.
- Pouches:Flexible multilayer films reduce shipping cube and material weight for institutional buyers. EU F-Gas Regulation compliance for cold-chain pouch filling equipment is redirecting procurement toward certified machinery vendors.
- Cans:Two-piece and three-piece metal containers remain standard for paste export logistics.
- Tetra Packs:Aseptic carton systems extend ambient shelf life for juice and sauce applications.
Cans anchor export infrastructure. Pouches are gaining share fastest in food service channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA standards for acidified foods and USDA grading protocols anchor United States processing specifications, while EU F-Gas Regulation and REACH compliance redirect equipment procurement across European operations. India's FSSAI safety mandates and BIS quality certifications are tightening as domestic processing scales. Water-right allocations, energy transition costs in thermal processing, and shifting retail-private-label dynamics calibrate capacity investments across geographies.
United States
California's Central Valley reconfigures processing capacity around drought-adaptive agriculture as groundwater sustainability mandates compress viable production geography. FDA acidified food standards and USDA grading protocols shape product specifications and market access for domestic processors. Morning Star leverages vertical integration from field to can in the Central Valley to control paste quality and supply timing.
Italy
Emilia-Romagna and Campania processing clusters serve European food service and retail channels with paste and sauce specialization. EU F-Gas Regulation and REACH compliance requirements influence equipment choices and cold-chain packaging across Italian operations. Casalasco Società Agricola and Conserve Italia anchor production concentration in the Po Valley tomato belt.
India
Maharashtra and Karnataka processing hubs expand capacity to meet FSSAI safety mandates and BIS quality certifications previously satisfied by imports. Quick-service chains across India lock in long-term paste contracts to secure sauce consistency for regional menu rollouts. E-commerce bulk sourcing allows institutional buyers to bypass traditional distributor tiers through direct processor platform procurement.
China
Xinjiang and Inner Mongolia growing regions supply paste for domestic sauce manufacturing and export logistics. NMPA food safety regulations and GB standards shape processing specifications for domestic market access. Zhengzhou and Shanghai equipment fabricators supply thermal processing infrastructure to regional paste concentrators.
Spain
Extremadura and Andalusia tomato belts concentrate paste production for European industrial buyers and Mediterranean export markets. EU REACH compliance documentation for temperature-control equipment raises capital barriers for cold-break specialists. Seville and Badajoz processing plants retrofit evaporator trains to recover water and reduce energy exposure.
Tomato Processing Market Key Industry Players
Vertically integrated processors and diversified food conglomerates split the market between supply-chain control and brand portfolio breadth. Morning Star exemplifies field-to-factory integration, while Conagra Brands and Nestlé leverage multi-category scale. Strategic moves concentrate on water-recovery retrofits and supplier panel consolidation as drought stress and procurement standardization reshape competitive positioning.
Among North American processors, Morning Star and Conagra Brands occupy positions at opposite ends of the integration spectrum. Olam International exemplifies multi-region sourcing networks that navigate climate volatility across growing regions. European specialists including Casalasco Società Agricola and Conserve Italia sit within heritage-processing archetypes serving regional sauce and paste demand.
| Leading Market Players |
|---|
| Conagra Brands |
| Casalasco Società Agricola |
| Heinz |
| Ontario Processing Vegetable Growers |
| Houwelings International |
| Olam International |
| Nestlé |
| Conserve Italia |
| Morning Star |
| Others |
Cost & Logistics Intelligence
Freight corridors connecting California's Central Valley to Asian export hubs transmit cost volatility directly into paste price spreads, compressing margins for non-integrated processors while amplifying geographic price differentiation between drought-stressed domestic supply and import alternatives.
Pricing Analysis
Geographic price spreads between California-origin paste and Xinjiang-sourced alternatives have widened as water-right scarcity inflates domestic production costs. Contract-based long-term offtake dominates industrial procurement, with price differentiation driven by viscosity certification grade and volume scale commitments. Cost compression in standard-grade paste is intensifying because natural gas price volatility erodes thermal processing margins. Quick-service chains exhibit least price sensitivity due to specification lock-in, while catering operators face acute pressure from flexible pack size premiums.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for paste traders. Raw material flows draw from California, Xinjiang, and Andalusia growing belts, with concentrated dependence on natural gas, aluminum can sheet, and multilayer barrier films. Single-source vulnerability in California water allocations threatens bulk paste availability for North American sauce manufacturers. Distribution runs through processor-direct platforms for institutional buyers and traditional distributor tiers for fragmented food service accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics is reshaping procurement relationships as Indian quick-service chains consolidate supplier panels and e-commerce bulk sourcing collapses traditional distributor margins, creating interoperability demands between processor ERP systems and buyer procurement hubs.
For Market Incumbents: Harden field-to-factory integration through captive drip-irrigation acreage in water-secure districts, insulating paste supply from California groundwater sustainability mandates. Deepen backward integration into seed genetics and harvesting equipment to control viscosity consistency batch-to-batch. Lock in multi-season contracts with Southeast Asian quick-service chains before regional processing capacity scales. For New Entrants and Emerging Players: Pursue membrane filtration retrofit services for mid-scale processors in water-stressed districts, capturing technology upgrade cycles as drought stress accelerates evaporator replacement timelines. Sub-Saharan Africa paste demand offers the most penetrable geography, with Nigeria and Kenya urbanization outpacing regional processing investment. Lead with water-recovery engineering expertise rather than commodity paste production. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates seeking to divest non-core paste assets as brand portfolio rationalization accelerates. Long-term viability hinges on water-right security and thermal efficiency positioning rather than scale alone. Watch FSSAI enforcement intensity as the inflection signal for Indian domestic processing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Irrigation Infrastructure | Morning Star's field-to-can model demonstrates margin protection against California water allocation cuts. |
| Membrane Filtration Technology Deployment | Reverse osmosis pre-concentration halves evaporation loads for processors in drought-stressed districts. |
| Supplier Panel Consolidation | Indian quick-service chains narrowing to two approved processors per district enforces batch consistency. |
| REACH Compliance Equipment Upgrade | European cold-break specialists face capital barriers from 316L stainless steel documentation requirements. |
| E-commerce Bulk Sourcing Platform Launch | Direct processor procurement bypasses distributor tiers for institutional buyers in India's expanding market. |
Research Approach
The analysis maps hot break and cold break processing technologies, each validated through plant operations directors, food service procurement managers, agricultural water rights attorneys, and thermal systems engineers. Primary interviews with California Central Valley growers, Maharashtra processing hub executives, and EU equipment fabricators combined with secondary validation from USDA grading protocols, FSSAI safety mandates, ECHA REACH documentation, and customs trade flows. Bottom-up paste volume modeling and top-down sauce value aggregation triangulated segment outputs.
Assumptions held fixed include California groundwater sustainability mandate enforcement timelines and EU F-Gas Regulation compliance deadlines, while natural gas price trajectories and Indian quick-service chain expansion rates varied across scenarios. Segmentation dimensions modeled encompass product type, end user channel, processing technology, and packaging format. CAGRs derived from historical volume elasticity to input cost shifts and procurement contract renewal patterns. Water-right allocation severity and membrane filtration adoption curves served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in energy commodity prices, trade tariff schedules, or currency exchange rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and climate stress patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market
Fruits and Vegetables Processing Equipment
Avocado Processing Market
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Portable Juicer Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
Juicer Market