
 Sulfur Recovery Tail Gas Analyzer Market | 2026-2036
Sulfur Recovery Tail Gas Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfur Recovery Tail Gas Analyzer Market Insights
Market Dynamics
The Middle East refinery expansion belt is reconfiguring demand geography for sulfur recovery tail gas analyzers. Emerson Electric leverages its process automation footprint across Saudi Aramco-linked installations. AMETEK sustains R&D intensity in ultraviolet spectroscopy for Claus process streams. Yokogawa Electric Corporation anchors its position through distributed control system integration with analyzer hardware.
Technology and Segmentation
Sulfur recovery tail gas analyzers measure hydrogen sulfide, sulfur dioxide, and elemental sulfur concentrations in Claus unit effluent streams, typically operating at temperatures exceeding 250°C with sample conditioning systems to prevent condensation. Infrared analyzers dominate refinery operations due to proven reliability in high-sulfur environments, while electrochemical analyzers represent the fastest-growing product category for portable verification applications. Continuous Emission Monitoring technology commands the largest technology share as oil and gas companies face real-time reporting obligations, whereas Process Analytics yields higher margins through integration with advanced process control systems.
Regulatory Environment
The EPA enforces Maximum Achievable Control Technology standards for petroleum refineries, directly mandating tail gas analyzer installation and calibration frequencies. EMA's Industrial Emissions Directive and REACH chemical safety protocols shape European procurement specifications, while China's MEE administers ultra-low emission thresholds for sulfur recovery units. Stakeholders must monitor evolving mercury and nitrogen oxide co-measurement requirements that could expand analyzer specification scopes beyond sulfur species alone.
Market Dynamics
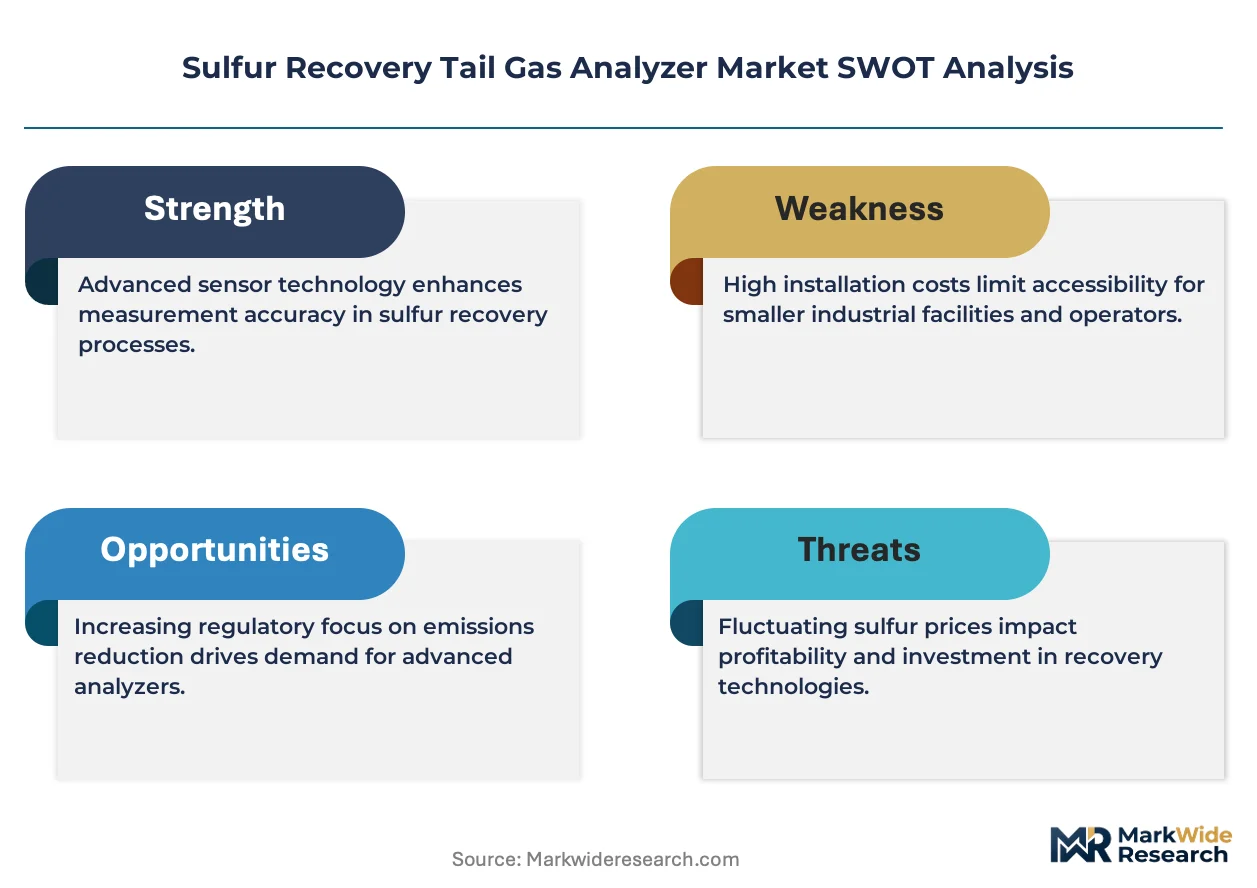
Refinery operators face mounting pressure to upgrade Claus unit monitoring as sulfur emission thresholds tighten across multiple jurisdictions. The EPA's Maximum Achievable Control Technology standards and parallel mandates in Europe and Asia are forcing continuous investment in analyzer infrastructure.
Growth Catalysts
- EPA Cross-State Air Pollution Rule:Petroleum refineries in the United States must install continuous emission monitoring systems, directly mandating tail gas analyzer deployment and calibration protocols.
- Claus process optimization:Refinery operators seek real-time hydrogen sulfide and sulfur dioxide data to maximize sulfur recovery efficiency and minimize stack emissions.
- United States Gulf Coast corridor:Concentrated petrochemical infrastructure along the Texas-Louisiana refining belt generates concentrated demand for high-temperature analyzer systems.
Market Restraints
- Specialized sensor materials:Platinum and palladium components in electrochemical cells face price volatility, compressing margins for analyzer manufacturers.
- Sample conditioning complexity:Maintaining analyzer accuracy above 250°C requires exotic alloys and precision engineering that limit supplier pool depth.
- Ultraviolet spectroscopy substitution:Alternative measurement technologies threaten infrared analyzer dominance in new refinery construction specifications.
Strategic Opportunities
- India refinery expansion:Reliance Industries and Indian Oil Corporation are building mega-refineries requiring integrated tail gas monitoring suites.
- Mercury co-measurement mandate:Evolving EPA standards may expand analyzer specification scopes to include mercury detection capabilities.
- Portable verification segment:Electrochemical analyzers for field calibration represent underdeveloped white space with higher margin profiles.
Industry Challenges
- Spectroscopy technician scarcity:Refinery sites struggle to recruit personnel capable of maintaining ultraviolet and infrared optical systems in hazardous environments.
- Distributed control system integration:Retrofitting new analyzers into legacy Yokogawa or Honeywell control architectures demands costly custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfur Recovery Tail Gas Analyzer Market |
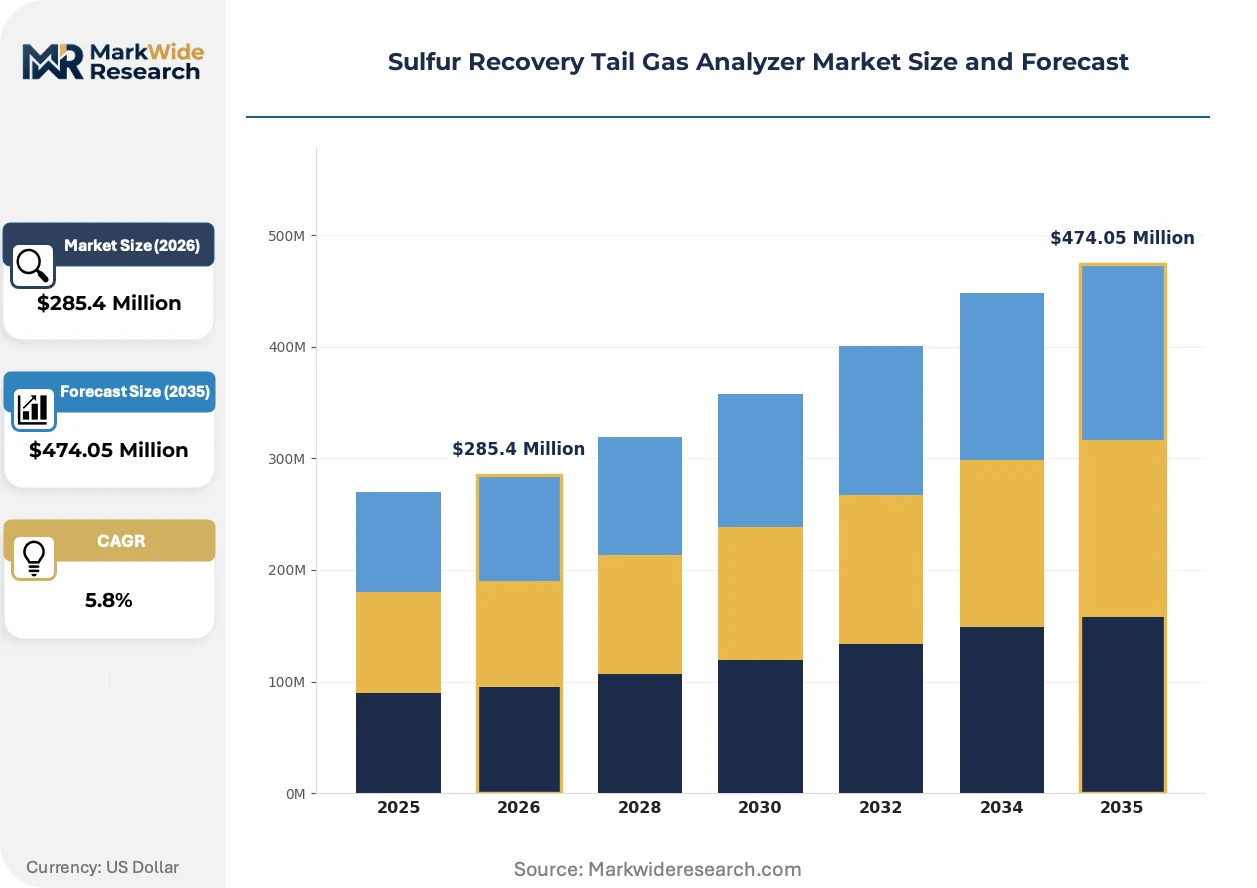
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Analyzers, Ultraviolet Analyzers, Electrochemical Analyzers, Gas Chromatographs Application: Refinery Operations, Chemical Production, Power Generation, Environmental Monitoring End User: Oil & Gas Companies, Chemical Manufacturers, Power Plants, Environmental Agencies Technology: Continuous Emission Monitoring, Process Analytics, Ambient Air Monitoring, Laboratory Analysis |
| Companies Covered | Norsk Analyse, Emerson Electric, AMETEK, ABB, Yokogawa Electric Corporation, Galvanic Applied Sciences, Thermo Fisher Scientific, Honeywell International, Applied Analytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfur Recovery Tail Gas Analyzer Market Trends and Innovations
Analyzer technology is converging with process control systems, creating demand for unified data platforms. Vendors are responding with integrated hardware-software offerings that compress deployment timelines and reduce operator training burdens.
Multi-wavelength infrared spectroscopy is hybridizing with electrochemical sensing in hybrid analyzer architectures. Refinery operators in the United States Gulf Coast are piloting these dual-technology units to gain redundancy without duplicate capital expenditure. The approach is compressing maintenance windows while expanding measurement confidence intervals for regulatory reporting.
China's Ministry of Ecology and Environment has enacted ultra-low emission thresholds for sulfur recovery units that exceed prior national standards. Domestic refiners must retrofit existing Claus trains with continuous monitoring or face production curtailments. Analyzer vendors are localizing production to meet procurement rules favoring domestic content in state-owned refinery projects.
Refinery procurement teams are unbundling analyzer hardware from long-term service contracts that previously locked them into single-vendor relationships. Third-party calibration specialists and independent system integrators are capturing service revenue that equipment manufacturers once controlled. This pattern is most visible in European refining where REACH compliance documentation requirements favor independent validation.
Sulfur Recovery Tail Gas Analyzer Market Segmentation
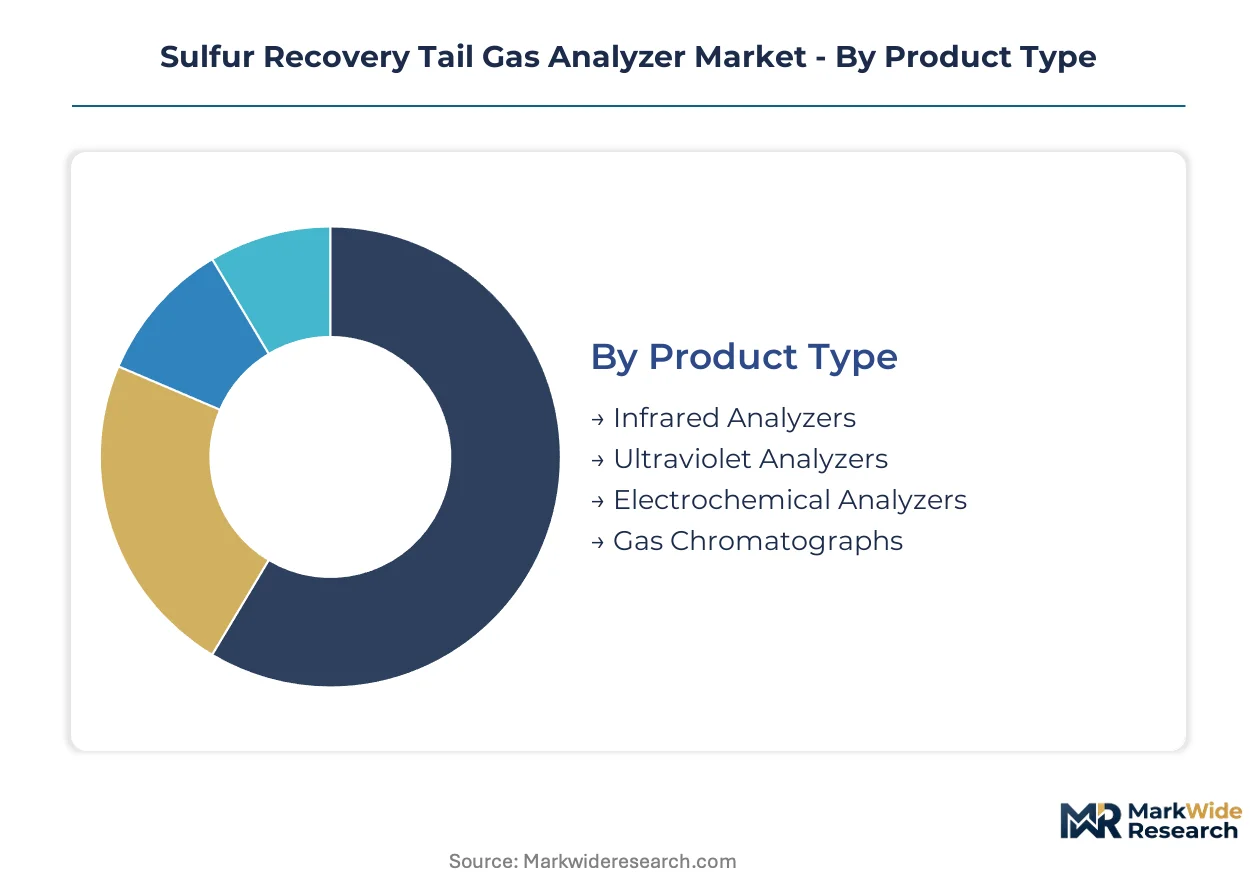
Sulfur recovery tail gas analyzers serve distinct operational profiles across the Claus process chain. Segment boundaries align with measurement precision requirements, regulatory reporting obligations, and integration depth with refinery control systems.
Product Type:
Use-case spectrum spans continuous process monitoring, portable verification, and laboratory-grade speciation across refinery and chemical plant environments.
- Infrared Analyzers:Non-dispersive infrared technology measures hydrogen sulfide and sulfur dioxide concentrations through absorption spectroscopy at characteristic wavelengths. Refinery operators along the United States Gulf Coast specify these units for Claus unit tail gas streams above 250°C due to thermal stability and minimal drift in high-sulfur matrices.
- Electrochemical Analyzers:Solid-state sensors with platinum-palladium catalytic elements enable portable field verification and spot-check calibration of fixed installations. Chemical manufacturers in specialty sulfur compound production favor these units for rapid deployment during maintenance turnarounds.
- Ultraviolet Analyzers:UV spectroscopy targets low-concentration sulfur dioxide detection with reduced cross-sensitivity to hydrocarbon interference.
- Gas Chromatographs:Laboratory-grade separation technology provides complete sulfur speciation including carbonyl sulfide and mercaptans for environmental compliance documentation.
Established volume favors Infrared Analyzers; emerging adoption favors Electrochemical Analyzers.
Application:
Cost tier stratification separates capital-intensive permanent installations from modular monitoring solutions.
- Refinery Operations:Claus sulfur recovery units require continuous hydrogen sulfide-to-sulfur-dioxide ratio monitoring to optimize air demand and maximize conversion efficiency. Operators face EPA Maximum Achievable Control Technology mandates for real-time emission reporting.
- Chemical Production:Carbon disulfide and specialty sulfur chemical manufacturers deploy analyzers to prevent off-spec product formation and protect downstream catalyst beds from poisoning.
- Power Generation:Coal and residual oil-fired plants with flue gas desulfurization systems use tail gas analyzers to verify scrubber performance and sulfur capture rates.
- Environmental Monitoring:Stack testing contractors and regulatory agencies employ portable analyzers for enforcement inspections and source attribution studies.
Capital commitment intensity peaks in Refinery Operations; deployment flexibility defines Environmental Monitoring.
End User:
Customer type determines procurement sophistication and service contract structures.
- Oil & Gas Companies:Integrated majors and independent refiners operate the largest installed base with centralized maintenance programs and multi-site standardization protocols.
- Chemical Manufacturers:Specialty and commodity chemical producers prioritize analyzer uptime for batch process control and product quality certification.
- Power Plants:Utility and independent power producers face cross-state air pollution regulations driving retrofit investments in continuous monitoring infrastructure.
- Environmental Agencies:Federal and state regulators procure reference-grade analyzers for compliance auditing and enforcement actions.
Procurement scale concentrates with Oil & Gas Companies; technical specification authority resides with Environmental Agencies.
Technology:
Integration depth with process control architectures defines margin structures and vendor selection criteria.
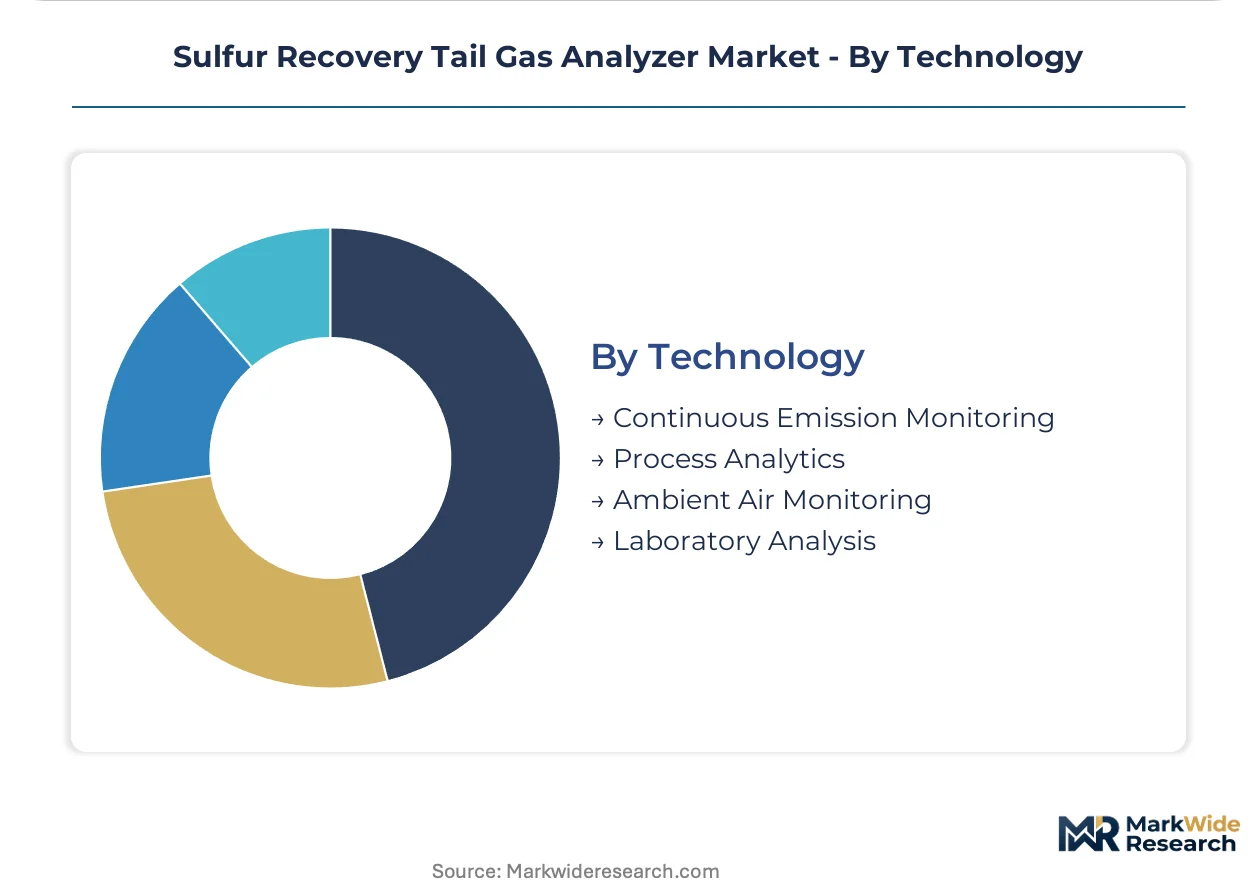
- Continuous Emission Monitoring:Integrated hardware-software systems transmit real-time data to regulatory databases with automated calibration checks and audit trails. Oil & Gas Companies deploy these systems to satisfy EPA reporting requirements without manual intervention.
- Process Analytics:Tight coupling with distributed control systems enables closed-loop air demand adjustment in Claus units, yielding sulfur recovery efficiency gains and stack emission reductions.
- Ambient Air Monitoring:Fence-line and community monitoring stations track sulfur compound dispersion patterns using standardized reference methods.
- Laboratory Analysis:Extractive sampling with chromatographic separation provides definitive speciation for dispute resolution and permit renewal documentation.
Margin concentration favors Process Analytics; regulatory compulsion drives Continuous Emission Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Analyzer manufacturing concentrates in industrial automation hubs across Germany, Japan, and the United States, with final system assembly gravitating toward major refinery corridors. Demand geography follows sulfur recovery unit installations, creating distinct procurement patterns across national oil company portfolios.
United States
The Texas-Louisiana Gulf Coast petrochemical corridor hosts the densest concentration of Claus sulfur recovery units outside the Middle East. EPA Maximum Achievable Control Technology standards mandate continuous emission monitoring with automated calibration protocols. Houston-area refiners operate integrated analyzer networks tied to real-time regulatory reporting systems.
Germany
REACH chemical safety protocols and the EU Industrial Emissions Directive shape analyzer specifications for BASF and Evonik chemical complexes. ECHA documentation requirements favor independent validation specialists over bundled manufacturer service contracts. The Rhine-Ruhr industrial belt drives demand for multi-species analyzers capable of mercury co-measurement.
Saudi Arabia
Saudi Aramco's master gas system expansion and Jubail Industrial City refinery builds create concentrated procurement volumes. The SFDA and national environmental regulator enforce sulfur recovery efficiency benchmarks exceeding prior regional standards. Domestic content rules are pushing analyzer vendors toward local assembly partnerships in the Eastern Province.
China
MEE ultra-low emission thresholds for sulfur recovery units now exceed prior national standards, forcing retrofit investments at Sinopec and PetroChina facilities. The Yangtze River Delta refining cluster is piloting hybrid infrared-electrochemical analyzer architectures. State-owned refinery projects increasingly specify domestic analyzer production under procurement localization mandates.
India
Reliance Industries' Jamnagar refinery expansion and Indian Oil Corporation's Paradip mega-refinery builds require integrated tail gas monitoring suites. The Central Pollution Control Board is tightening sulfur emission limits for coastal refineries. The Gujarat refining corridor is emerging as the primary demand node for high-temperature analyzer systems.
Sulfur Recovery Tail Gas Analyzer Market Competitive Landscape
Process automation conglomerates and specialized analyzer houses split the market into distinct capability tiers. Consolidation around integrated hardware-software offerings has compressed the vendor pool serving mega-refinery projects. Two strategic archetypes dominate: diversified industrial technology groups with distributed control system integration capabilities, and focused instrumentation specialists with deep spectroscopy expertise. Competitive moves center on technology licensing partnerships for sample conditioning systems and backward integration into exotic alloy component manufacturing.
Among diversified automation providers, Emerson Electric and Yokogawa Electric Corporation occupy positions spanning process control integration. ABB and Honeywell International exemplify the scale-driven conglomerate archetype with cross-portfolio refinery relationships. AMETEK represents the specialized instrumentation house model, while Thermo Fisher Scientific anchors the analytical science tier. Norsk Analyse, Galvanic Applied Sciences, and Applied Analytics sit within the focused technology specialist segment.
| Leading Market Players |
|---|
| Norsk Analyse |
| Emerson Electric |
| AMETEK |
| ABB |
| Yokogawa Electric Corporation |
| Galvanic Applied Sciences |
| Thermo Fisher Scientific |
| Honeywell International |
| Applied Analytics |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp-Houston maritime corridor governs freight cost dynamics for analyzer manufacturers shipping sample conditioning systems and exotic alloy components. Concentrated supply of platinum-group metals and precision optical assemblies in Germany and Japan compresses procurement timelines for Gulf Coast refiners while elevating price premiums for expedited delivery. Downstream buyers face tiered cost structures that separate continuous emission monitoring installations from portable verification units based on integration complexity and calibration protocol stringency.
Pricing Analysis
EPA Maximum Achievable Control Technology standards dictate the pricing tier structure across the sulfur recovery tail gas analyzer market. Three-tier pricing structure across premium, standard, and economy levels segments buyers by calibration automation level and regulatory audit trail sophistication. Price differentiation rests on certification grade (ISO 17025-accredited versus factory-standard) and after-sales service bundling. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are localizing infrared analyzer production under MEE procurement mandates. Environmental agencies exhibit highest price sensitivity due to budget-constrained reference-grade procurement cycles, while integrated oil majors demonstrate lowest sensitivity given operational risk mitigation priorities.
Supply Chain Analysis
Specialized contract manufacturers in Bavaria, Osaka, and Texas hold concentrated capacity for high-temperature sample conditioning systems and non-dispersive infrared optical benches. Geographic supply concentrates in Germany for precision-engineered exotic alloys, Japan for ultraviolet spectroscopy components, and the United States for distributed control system integration modules. Raw material dependencies draw from South African platinum-group metal suppliers, Chinese rare earth optical substrate producers, and German specialty glass foundries. Single-source vulnerability in platinum-palladium catalytic elements for electrochemical sensors creates exposure to commodity price volatility. Distribution runs through authorized system integrators with refinery automation expertise, bypassing direct equipment sales for complex Claus unit retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultraviolet spectroscopy substitution threatens incumbent infrared analyzer positions as refinery engineering specifications evolve toward multi-wavelength hybrid architectures. Incumbents must defend against this technology displacement while navigating unbundling of hardware from long-term service contracts.
For Market Incumbents: Insulate installed base relationships by backward integration into exotic alloy component manufacturing to secure sample conditioning system supply. Acquire independent calibration specialists in Europe to capture service revenue streams previously lost to third-party validators. UV spectroscopy hybridization represents the primary substitution threat requiring R&D investment in dual-technology architectures.
For New Entrants and Emerging Players: Portable electrochemical verification units for field calibration represent the most penetrable entry point given margin premiums and underdeveloped vendor concentration. India's Gujarat refining corridor offers geographic white space as Reliance Industries and Indian Oil Corporation execute mega-refinery builds without established analyzer supplier relationships. A go-to-market angle anchored to mercury co-measurement capability addresses evolving EPA standards that expand specification scopes beyond sulfur species alone.
For Investors and Strategic Acquirers: Focused instrumentation houses with deep spectroscopy expertise and existing sample conditioning technology partnerships offer the strongest acquisition target archetype. Long-term viability hinges on regulatory compulsion durability across multiple jurisdictions rather than cyclical refinery capital expenditure timing. Watch for MEE enforcement intensity at Sinopec facilities as the inflection indicator signaling Chinese market acceleration or deceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Exotic Alloy Manufacturing | Captive supply of Hastelloy and Inconel sample conditioning components secures margin control against platinum price volatility. |
| UV Spectroscopy Technology Licensing | AMETEK's ultraviolet expertise transfer enables hybrid analyzer architectures that displace pure infrared installations. |
| Independent Calibration Specialist Acquisition | European REACH documentation requirements favor third-party validation over bundled manufacturer service contracts. |
| Domestic Production Localization | China's state-owned refinery procurement rules increasingly specify domestic analyzer assembly partnerships. |
| Mercury Co-Measurement Capability Development | Evolution of EPA standards expands analyzer specification scopes beyond hydrogen sulfide and sulfur dioxide monitoring. |
Research Methodology
A standing panel of refinery process engineers, analyzer maintenance technicians, environmental compliance officers, and distributed control system integrators provided ongoing calibration of demand assumptions and technology substitution timelines. Primary fieldwork combined structured interviews with procurement leads at integrated oil majors and independent refiners across the Texas-Louisiana Gulf Coast, Rotterdam-Antwerp chemical corridor, and Jubail Industrial City. Secondary validation drew from EPA enforcement and compliance databases, ECHA REACH registration dossiers, MEE ultra-low emission threshold announcements, and SEC 10-K disclosures of publicly traded automation conglomerates. Bottom-up unit deployment estimates triangulated against top-down refinery capacity expansion projections.
Scenario bracketing around regulatory enforcement intensity and refinery capital expenditure cycles anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include analyzer product type, application environment, end-user procurement sophistication, and technology integration depth with process control architectures. CAGRs were derived from regression analysis of historical installation patterns against regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated Claus unit sulfur recovery efficiency benchmarks and sample conditioning system replacement cycle data.
Practitioners should monitor EPA mercury co-measurement rulemaking progress and MEE enforcement actions at Yangtze River Delta refineries for early signals of specification scope expansion. Forecasts reflect assumptions regarding regulatory compulsion durability, platinum-group metal price stability, and spectroscopy technician labor availability. Quarterly review of refinery turnaround schedules and domestic content rule changes in China and Saudi Arabia is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Argon Gas Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Europe Syngas Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
Neon Gas Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
Industrial Oxygen Market
Industrial Gases
US Industrial Gas Regulator Market