
 North America Industrial Gases Market | 2026-2036
North America Industrial Gases Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Gases Market Analytics
Project finance tied to long-term offtake agreements is narrowing the competitive field for new entrants seeking to build large-scale air separation units. Linde plc leverages its integrated pipeline networks across the US Gulf Coast to sustain feedstock security for chemical processing clients. Air Products and Chemicals, Inc. anchors its position through on-site generation contracts with hydrogen-heavy industrial users. Messer North America, Inc. specializes in regional cylinder supply chains that compete on delivery speed rather than volume scale.
Industrial gases comprise atmospheric gases—oxygen, nitrogen, and argon recovered through cryogenic air separation at temperatures below minus 180 degrees Celsius—along with process gases like carbon dioxide captured from industrial flue streams, serving primarily as process enablers for oxidation, inerting, cooling, and pH control across manufacturing operations. Oxygen dominates the type category through steelmaking and medical respiratory demand, while on-site generation represents the fastest-expanding delivery mode as semiconductor fabs and chemical plants seek supply certainty over unit cost optimization. Electronics applications within the end-user matrix command premium pricing due to ultra-high purity specifications and continuous-flow requirements that tolerate zero supply interruption.
The US EPA enforces emissions thresholds that elevate carbon capture and utilization economics, indirectly stimulating carbon dioxide recovery infrastructure investments, while OSHA mandates on compressed gas handling shape cylinder design and workplace distribution protocols across US manufacturing facilities. Health Canada and PMRA coordinate with provincial regulators on medical gas purity standards that govern cross-border trade flows. Stakeholders must weigh pipeline network density against modular on-site generation economics when committing capital to serve the next wave of domestic semiconductor and battery material facilities.
Market Dynamics
Long-term offtake agreements for semiconductor fabrication are concentrating capital commitments among integrated gas suppliers capable of delivering ultra-high purity nitrogen and argon through dedicated on-site generation facilities. This contracting structure favors incumbents with balance sheet capacity to absorb billion-dollar air separation unit investments against 15-20 year supply commitments.
Growth Catalysts
- CHIPS and Science Act incentives:Federal tax credits and direct funding for domestic semiconductor manufacturing are accelerating demand for bulk nitrogen and specialty gases in Texas and Arizona fabrication clusters.
- Carbon capture economics:EPA emissions thresholds under the Clean Air Act are improving project returns for carbon dioxide recovery from ammonia and ethanol plants, expanding merchant CO₂ supply.
- Hydrogen hub development:Department of Energy regional clean hydrogen hubs are creating anchor demand for large-scale oxygen supply to support electrolyzer and gasification operations.
Market Restraints
- Electricity cost volatility:Cryogenic air separation consumes 3,000-4,000 kWh per ton of oxygen equivalent, exposing margins to ERCOT and CAISO pricing spikes.
- Gulf Coast supply concentration:Pipeline network density along the Texas-Louisiana corridor creates single-point vulnerability for chemical processing feedstock security.
- Helium resource depletion:Bureau of Land Management reserve drawdowns and Qatar supply disruptions are constraining availability for MRI cooling and semiconductor annealing.
Strategic Opportunities
- Mexico manufacturing expansion:Nearshoring of automotive and electronics assembly is outpacing local gas infrastructure, creating greenfield on-site generation openings in Nuevo León and Baja California.
- Biogas upgrading integration:Landfill and dairy digester operators are pairing membrane and pressure swing adsorption systems with CO₂ liquefaction for food-grade merchant supply.
- Inflation Reduction Act credits:45Q carbon capture incentives and clean fuel production credits are restructuring project finance for blue hydrogen and carbon utilization ventures.
Industry Challenges
- Cryogenic engineering talent scarcity:Retirement of experienced plant operators and process engineers is lengthening commissioning timelines for complex air separation units.
- Ultra-high purity certification delays:SEMI standard compliance for sub-ppb contamination specifications requires 18-24 month validation cycles that gate semiconductor contract awards.
- Legacy pipeline interoperability:Integrating new on-site generation with existing Gulf Coast pipeline networks requires complex pressure and purity matching protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Gases Market |
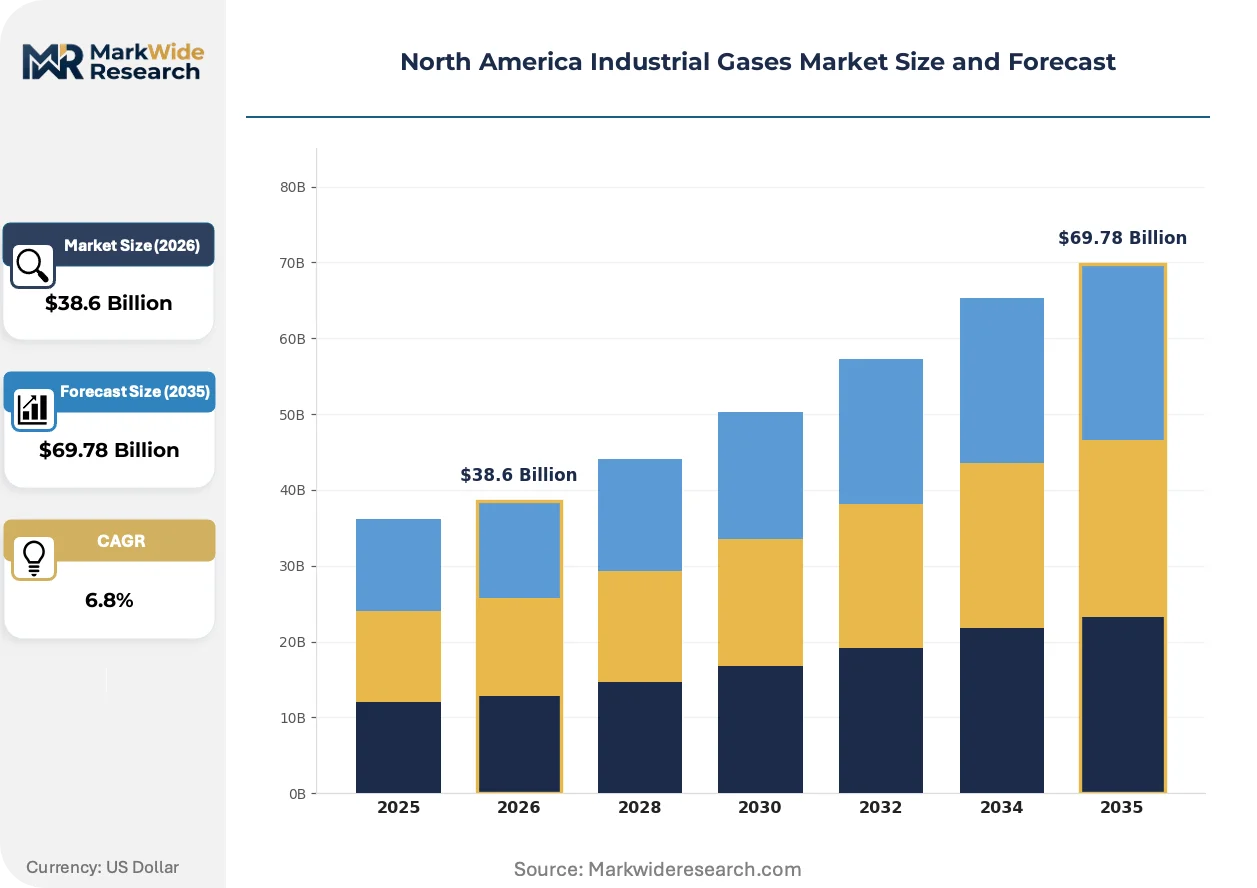
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Oxygen, Nitrogen, Argon, Carbon Dioxide Application: Metal Fabrication, Chemical Processing, Food & Beverage, Electronics Delivery Mode: Bulk Supply, Cylinder Supply, On-site Generation, Pipeline Supply End User: Manufacturing, Healthcare, Energy, Aerospace |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Messer North America, Inc., Matheson Tri-Gas, Inc., BASF SE, Universal Industrial Gases, Inc., MESA Specialty Gases & Equipment, Airgas, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Gases Market Evolving Landscape
Modular air separation technology and digital distribution platforms are compressing the traditional scale advantages that anchored regional gas supply for decades. These shifts are enabling smaller footprints, faster deployment, and direct contracting relationships that bypass conventional merchant distribution tiers.
Membrane and pressure swing adsorption systems for on-site nitrogen generation are collapsing the minimum efficient scale for electronics and food packaging applications. Mid-sized semiconductor fabs and battery material plants are adopting these units to avoid pipeline dependency and reduce capital lock-up. The technology is collapsing the historical volume threshold that separated on-site from merchant supply economics.
OSHA's updated compressed gas cylinder handling standards and EPA risk management plan amendments are tightening workplace safety and environmental release protocols. These rules are accelerating investment in automated cylinder tracking and telemetry systems. Smaller regional distributors face disproportionate compliance burdens relative to integrated operators with dedicated regulatory affairs functions.
Direct procurement of industrial gases through digital platforms is fragmenting traditional distributor relationships in cylinder and small bulk segments. Food and beverage processors are increasingly sourcing through consolidated national contracts rather than regional merchant relationships. This pattern is most visible in California and the Northeast, where buyer concentration and sustainability reporting requirements favor transparent, auditable supply chains.
North America Industrial Gases Market Segmentation
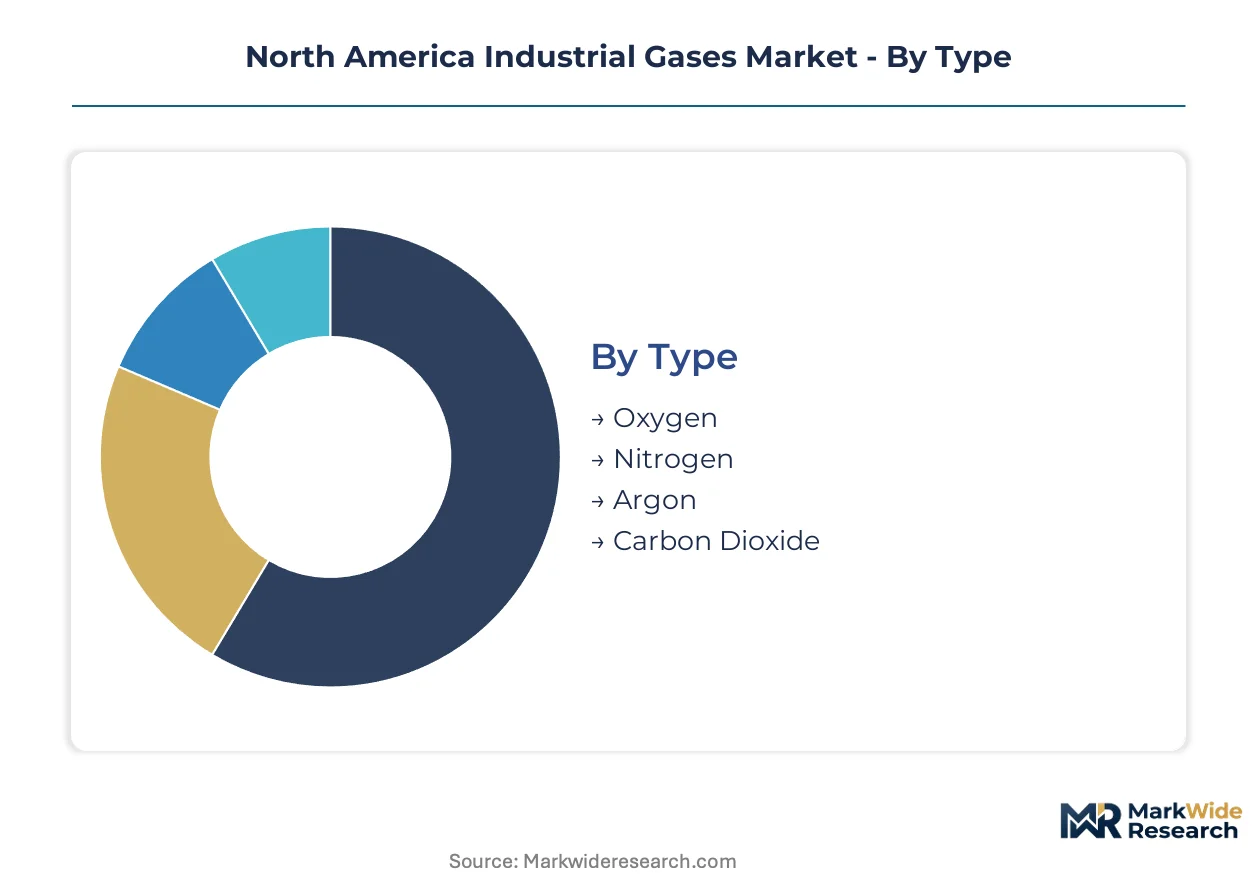
Industrial gas suppliers structure their offerings around four distinct segmentation axes that determine capital deployment, margin profiles, and contractual risk. Each axis carries different implications for purity specifications, delivery reliability, and customer switching costs.
Type:
Mature atmospheric gases anchor volume throughput while process gases occupy higher-margin niches.
- Oxygen:Cryogenic air separation yields gaseous and liquid oxygen with purity levels exceeding 99.5 percent for medical and industrial grades. Steelmaking in the US Great Lakes region and Gulf Coast chemical oxidation processes concentrate demand, with EPA emissions enforcement indirectly stimulating oxy-combustion adoption.
- Nitrogen:Inerting properties dominate applications requiring oxygen displacement at sub-ppm contamination thresholds. Arizona and Texas semiconductor fabrication clusters are absorbing bulk nitrogen through dedicated on-site generation, with CHIPS Act incentives accelerating contract velocity for ultra-high purity supply.
- Argon:Shielding gas for arc welding and semiconductor crystal pulling, recovered as a byproduct of oxygen/nitrogen separation.
- Carbon Dioxide:Captured from ammonia and ethanol plant flue streams for food-grade freezing and beverage carbonation; 45Q credits are restructuring project economics.
Oxygen handles the majority of throughput; nitrogen is the fastest mover on share.
Application:
Application segmentation tracks customer technical requirements from commodity processing to precision manufacturing.
- Metal Fabrication:Oxygen-fuel cutting and argon-shielded welding dominate steel service centers and automotive stamping operations across Michigan and Ohio.
- Chemical Processing:Oxidation reactions and inert blanketing in Texas and Louisiana petrochemical corridors drive pipeline-connected bulk demand.
- Food & Beverage:Modified atmosphere packaging and cryogenic freezing require food-grade nitrogen and carbon dioxide with FDA-compliant certification chains.
- Electronics:Ultra-high purity nitrogen, argon, and specialty mixtures for semiconductor etching and deposition processes command premium pricing with zero-tolerance supply interruption clauses.
Metal fabrication maintains the largest installed demand base; electronics is expanding most quickly on contract value.
Delivery Mode:
Delivery mode selection reflects the trade-off between capital efficiency and supply security.
- Bulk Supply:Liquid oxygen, nitrogen, and argon delivered by cryogenic tanker truck to customer storage vessels; standard for mid-scale chemical and food processors with predictable consumption profiles.
- Cylinder Supply:High-pressure gas cylinders for intermittent users and remote locations; OSHA cylinder handling standards and automated tracking requirements are raising compliance costs for regional distributors.
- On-site Generation:Dedicated air separation units or pressure swing adsorption systems eliminate transport costs and supply interruption risk. Semiconductor fabs and hydrogen electrolyzer projects in Texas and Arizona are locking in 15-20 year offtake agreements for captive supply.
- Pipeline Supply:Dense network infrastructure along the US Gulf Coast delivers oxygen and hydrogen to integrated chemical complexes; new projects face legacy interoperability challenges.
Pipeline supply anchors the highest-volume relationships; on-site generation is climbing the fastest as fabs seek supply certainty.
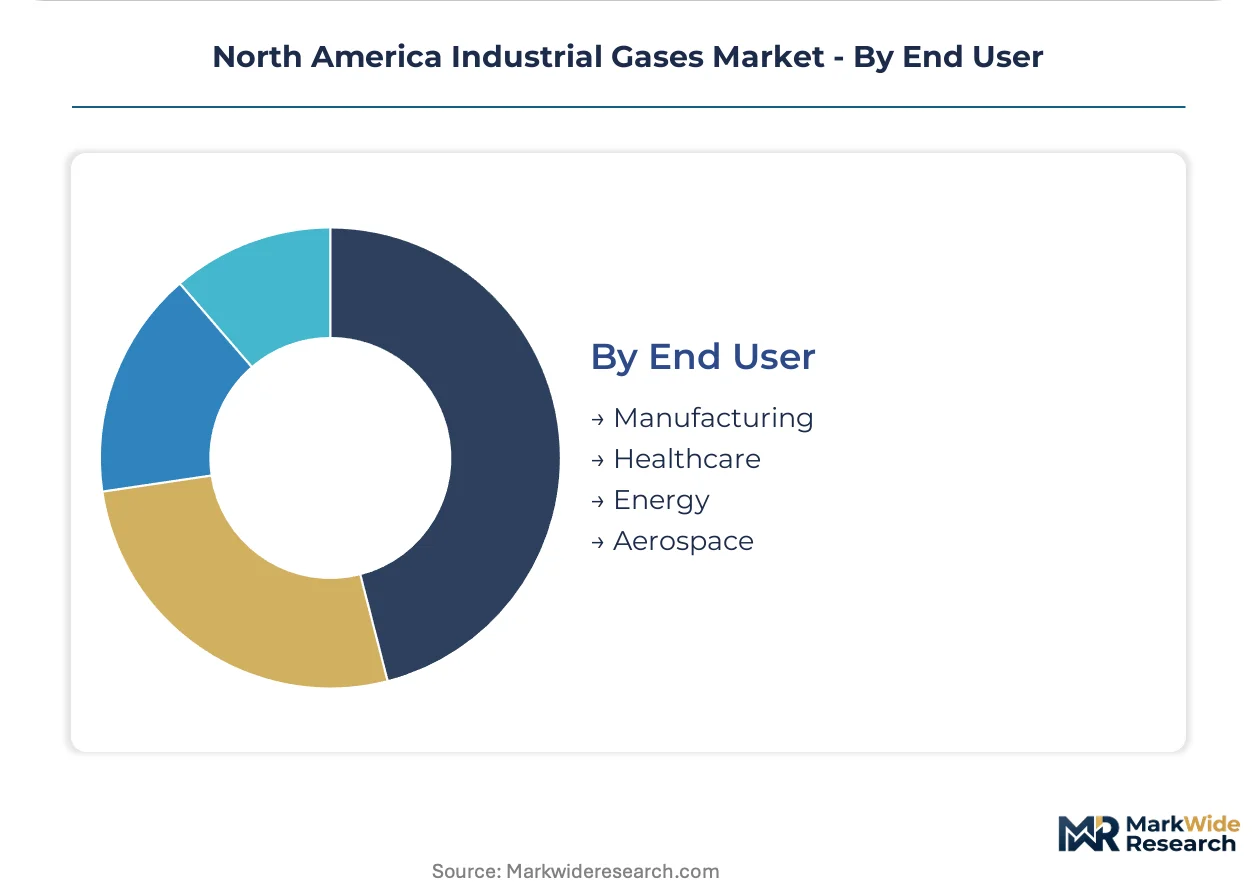
End User:
End-user segmentation reveals diverging purity requirements and procurement sophistication.
- Manufacturing:Steel, chemicals, and automotive production absorb atmospheric gases at industrial-grade specifications; Mexico nearshoring is outpacing local infrastructure in Nuevo León.
- Healthcare:Medical oxygen and respiratory mixtures require FDA and Health Canada compliance with stringent purity documentation; home healthcare cylinder demand is fragmenting toward digital procurement platforms.
- Energy:Hydrogen production, carbon capture, and enhanced oil recovery are creating anchor demand for oxygen and carbon dioxide; Department of Energy hydrogen hubs are restructuring regional supply economics.
- Aerospace:Launch vehicle propulsion and aircraft inerting systems require high-purity nitrogen and helium; Bureau of Land Management reserve drawdowns are constraining helium availability.
Manufacturing commands the greatest volume throughput; energy is gaining share fastest on hydrogen hub development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border gas flows between the three North American economies are intensifying as semiconductor fabs and hydrogen projects concentrate demand in specific corridors. Canada and Mexico now serve as critical supply buffers and emerging demand centers rather than peripheral markets.
United States
CHIPS Act subsidies have locked in fifteen-year nitrogen supply contracts for Arizona and Texas fabrication clusters. EPA enforcement of Clean Air Act emissions thresholds is accelerating carbon dioxide recovery investments at Gulf Coast ammonia plants. The Texas-Louisiana pipeline corridor anchors bulk oxygen supply for chemical oxidation processes.
Canada
Health Canada coordinates with provincial regulators on medical gas purity standards that govern cross-border trade with US healthcare distributors. Alberta's hydrogen hub development is creating anchor demand for large-scale oxygen supply to electrolyzer operations. Ontario's automotive battery material plants are contracting on-site nitrogen generation to avoid pipeline dependency.
Mexico
Nearshoring of automotive and electronics assembly in Nuevo León and Baja California is outpacing local gas infrastructure capacity. The country's federal environmental regulator enforces emissions standards that indirectly stimulate carbon capture project economics. Monterrey's manufacturing corridor is attracting greenfield on-site generation investments from integrated gas suppliers.
North America Industrial Gases Market Competitive Landscape
On the supply side, the industry is consolidating around integrated operators capable of absorbing billion-dollar air separation unit investments against long-dated offtake agreements. Three strategic archetypes dominate: pipeline-network incumbents leveraging Gulf Coast density, on-site generation specialists securing semiconductor contracts, and regional cylinder distributors competing on delivery velocity. Competitive moves center on capacity expansion in Arizona and Texas fabrication corridors, plus strategic partnerships with hydrogen hub developers.
Within the integrated tier, Linde plc and Air Products and Chemicals, Inc. exemplify divergent positioning strategies. Linde anchors its presence through pipeline network density across chemical processing corridors, while Air Products secures captive supply relationships with hydrogen-heavy industrial users. Messer North America, Inc. occupies a distinct position competing on regional cylinder supply chain responsiveness rather than volume scale.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Messer North America, Inc. |
| Matheson Tri-Gas, Inc. |
| BASF SE |
| Universal Industrial Gases, Inc. |
| MESA Specialty Gases & Equipment |
| Airgas, Inc. |
| Others |
Value Network & Pricing Analysis
ERCOT electricity price volatility determines both the spread between on-site generation and merchant supply tiers and the geographic clustering of new air separation unit investments. This single input cost risk compresses margins for cryogenic producers while concentrating supply chain development around grid-interconnected industrial parks in Texas and Arizona.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the North America Industrial Gases Market. Three-tier pricing structure across premium, standard, and economy levels separates ultra-high purity semiconductor-grade nitrogen from industrial-grade oxygen and packaged cylinder supply. Cost compression in standard-tier bulk supply is intensifying because modular pressure swing adsorption systems collapse minimum efficient scale thresholds. Merchant cylinder distributors exhibit highest price sensitivity due to automated tracking compliance burdens, while semiconductor fabs with zero-tolerance interruption clauses show lowest sensitivity.
Supply Chain Analysis
Export-control restrictions on cryogenic turboexpander technology limit equipment sourcing to Germany, Japan, and the United States, constraining capacity expansion timelines for non-integrated entrants. The North America Industrial Gases Market draws from specialized steel alloys for cold-box fabrication, high-purity aluminum for heat exchangers, and rare earth elements for magnetic bearing systems. Single-source vulnerability concentrates in helium feedstock, where Bureau of Land Management reserve drawdowns and Qatar supply disruptions constrain MRI and semiconductor annealing applications. Distribution runs through pipeline networks along the Texas-Louisiana corridor, with tanker truck bulk delivery serving secondary markets and cylinder supply reaching fragmented end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Industrial Gases Market functions as a defensive-moat industry where regulatory entrenchment through OSHA compressed gas handling mandates and EPA emissions enforcement creates durable barriers against price-competitive challengers.
For Market Incumbents: Build pipeline network density moats through strategic compression station additions in the Texas-Louisiana corridor that preempt hydrogen hub anchor demand. Linde plc and Air Products and Chemicals, Inc. should accelerate backward integration into carbon capture infrastructure at Gulf Coast ammonia plants before 45Q credit structures shift. This defends against modular on-site generation entrants collapsing merchant bulk margins in semiconductor and battery material segments. For New Entrants and Emerging Players: Mexico manufacturing expansion in Nuevo León and Baja California offers the most penetrable white-space opportunity, as nearshoring automotive and electronics assembly outpaces local gas infrastructure capacity. Greenfield on-site generation partnerships with Monterrey manufacturing clusters bypass entrenched pipeline competition. Target food-grade carbon dioxide liquefaction from biogas upgrading installations, where landfill and dairy digester operators lack technical integration capabilities. For Investors and Strategic Acquirers: The market sits at a capital-commitment phase that favors integrated operators with balance sheet capacity for billion-dollar air separation unit investments against 15-20 year semiconductor offtake agreements. Long-term viability over the next decade hinges on positioning for hydrogen hub oxygen demand and carbon capture project economics. Watch CHIPS Act funding disbursement velocity as the inflection signal for contract award timing and regional demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | 15-20 year offtake contracts with Arizona and Texas semiconductor fabs lock in air separation unit returns. |
| Backward Integration | Captive carbon dioxide recovery from Gulf Coast ammonia plants secures merchant CO₂ supply under EPA enforcement. |
| Capacity Expansion | Greenfield on-site generation in Nuevo León addresses Mexico nearshoring demand outpacing local infrastructure. |
| Joint Venture | Partnerships with Department of Energy hydrogen hub developers anchor large-scale oxygen offtake for electrolyzer operations. |
| Green Manufacturing Transition | Biogas upgrading integration with membrane systems creates food-grade carbon dioxide for beverage and freezing applications. |
Research Methodology
Cross-validation between primary interviews with plant managers at air separation facilities and secondary analysis of SEC 10-K filings, customs trade data, and American Chemistry Council reports anchors the qualitative findings. Conversations with procurement leads at downstream chemical processors, distribution channel partners, and technical R&D directors at integrated gas suppliers informed operational cost structures and contract terms. Bottom-up capacity installation tracking and top-down end-use demand modeling triangulate market size estimates across the analysis window.
Calibration against historical air separation unit commissioning timelines and offtake contract disclosure patterns validates projection assumptions. The forecast framework segments by gas type, delivery mode, application, and end-user industry, with additional modeling of purity grade tiers from industrial to ultra-high purity specifications. CAGRs derive from installed capacity expansion announcements, CHIPS Act funding trajectories, and hydrogen hub development schedules. Key inputs include cryogenic power consumption benchmarks and semiconductor fabrication nitrogen intensity coefficients.
The forecast holds incumbent behavior within observed patterns; aggressive moves by modular technology specialists or cross-border pipeline investors would shift outcomes. Material shifts in EPA emissions enforcement stringency, helium reserve management policy, or ERCOT grid reliability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Fluorocarbon Gases Market
Industrial Gases
Europe Syngas Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
Global Helium Gas Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
3D Printing Gases Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Helium Market
Industrial Gases
Xenon Gas Market