
 Sugarless Chocolate Market | 2026-2036
Sugarless Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Sugarless Chocolate Market Analytics
Premium single-origin and high-cocoa-mass specification tiers is unwinding across the sugarless chocolate category as consumers trade up from mass-market alternatives. The Hershey Company leverages its North American manufacturing scale to anchor retail shelf presence in mainstream sugarless segments. Lindt & Sprüngli differentiates through Swiss heritage positioning and sustained R&D intensity in cocoa-butter equivalent formulations for reduced-calorie lines.
Sugarless chocolate denotes confectionery products formulated without sucrose, typically employing maltitol, erythritol, stevia, or allulose as bulk or high-intensity sweeteners while maintaining minimum cocoa solid thresholds for legal chocolate identity in major jurisdictions. Manufacturers achieve functional parity with conventional chocolate through controlled tempering curves and fat-phase structuring to replicate snap, gloss, and mouthfeel. Dark chocolate occupies the dominant value position within product type segmentation, driven by naturally lower baseline sugar and strong antioxidant health claims, while baking chocolate segments are expanding fastest among food manufacturer end users seeking clean-label dessert and pastry applications. Online retail channels are capturing disproportionate growth in distribution channel segmentation, particularly for subscription-based functional chocolate brands targeting ketogenic and diabetic consumer cohorts.
The FDA governs sugar-free labeling thresholds and sweetener safety profiles under Food Additives Regulations, while the EFSA reviews novel food approvals for emerging bulk sweeteners like allulose that shape European product development pipelines. BIS in India mandates cocoa content standards through packaged food regulations, influencing import specifications and local formulation requirements for multinational entrants. Stakeholders must monitor evolving sweetener approval timelines and front-of-pack labeling mandates to anticipate reformulation cycles and regional market access windows.
Market Dynamics
Sweetener approval timelines and front-of-pack labeling mandates are compressing product development cycles, forcing manufacturers to pre-position reformulation pipelines before regulatory windows open rather than responding to finalized rules.
Growth Catalysts
- FDA sugar-free labeling thresholds:The FDA's tightening enforcement of sugar-reduction claims redirects R&D budgets toward clean-label sweetener systems, accelerating maltitol and allulose adoption in US retail formulations.
- Industrial bakery procurement:German private-label health food chains and industrial bakeries are scaling sugarless chocolate volumes fastest, creating concentrated demand pull for high-cocoa-mass baking grades.
- Erythritol-stevia blending protocols:Advances in controlled tempering curves for these bulk sweeteners enable functional parity with conventional chocolate snap and gloss, unlocking mass-market accessibility.
Market Restraints
- Cocoa butter equivalent input volatility:Lindt & Sprüngli's sustained R&D intensity in reduced-calorie lines depends on specialty fat-phase inputs subject to tropical supply disruption and price spikes.
- EFSA novel food approval friction:Emerging bulk sweeteners like allulose face extended European review timelines, delaying product launches and freezing development budgets in regulatory limbo.
- Milk chocolate formulation barriers:Technical limitations in replicating dairy-mouthfeel without sucrose create persistent quality gaps that slow consumer acceptance outside dark chocolate segments.
Strategic Opportunities
- Subscription-based ketogenic channels:Online retail platforms targeting diabetic and ketogenic consumer cohorts offer disproportionate growth potential for functional chocolate brands with direct-to-consumer logistics.
- India cocoa content compliance:BIS packaged food regulations mandating minimum cocoa thresholds create import specification clarity that multinational entrants can leverage for first-mover positioning.
- Allulose-erythritol convergence:Blending these emerging bulk sweeteners with precision tempering technology enables clean-label dessert applications previously unreachable with single-sweetener systems.
Industry Challenges
- Food technologist specialization gaps:The intersection of confectionery science and sweetener chemistry requires rare hybrid expertise that outpaces current vocational training pipelines in major manufacturing hubs.
- Dual-jurisdiction certification complexity:Simultaneous FDA and EFSA approval pathways for novel formulations extend compliance timelines and fragment testing budgets across incompatible regulatory frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugarless Chocolate Market |
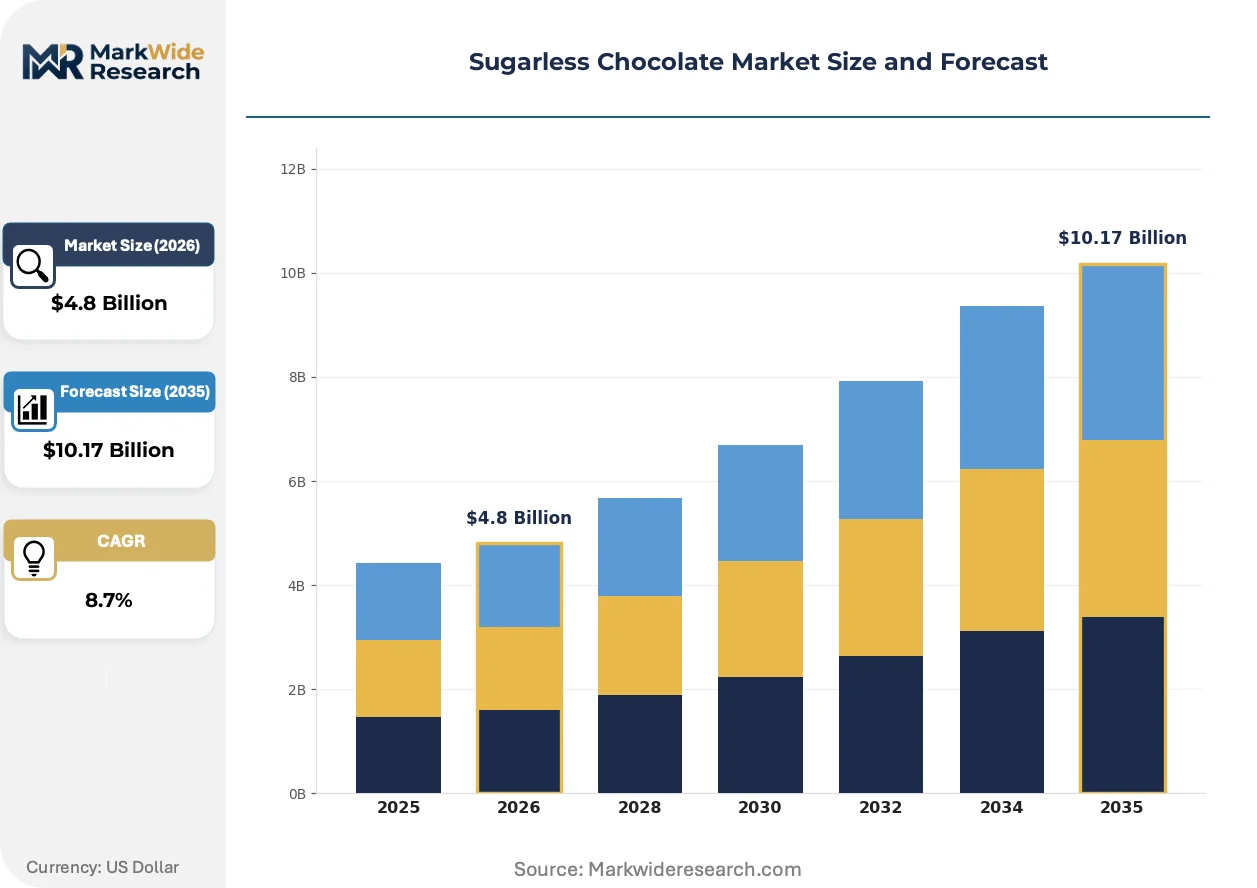
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Baking Chocolate End User: Retail Consumers, Food Manufacturers, Bakeries, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops Form: Bars, Chips, Coated Nuts, Baking Pieces |
| Companies Covered | The Hershey Company, Mars, Incorporated, Nestlé S.A., Mondelez International, Lindt & Sprüngli, Ferrero Group, Russell Stover Chocolates, Ghirardelli Chocolate Company, Barry Callebaut, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugarless Chocolate Market Evolving Landscape
Reformulation science and distribution infrastructure are diverging simultaneously, with manufacturing technology racing ahead of channel capacity to deliver temperature-stable, clean-label products at scale.
Allulose bulk sweetener technology is bifurcating the sugarless chocolate category between premium positioning and mass-market penetration. Ketogenic and diabetic consumer cohorts are adopting allulose formulations fastest through subscription channels. This technology is compressing the competitive window for legacy maltitol-dependent product lines while enabling new clean-label claims.
EFSA novel food approval protocols are reshaping European product development pipelines for emerging bulk sweeteners. Extended review timelines for substances like allulose freeze capital allocation and delay launch windows. Dark chocolate segments with naturally lower sugar baselines are responding fastest by pivoting to established sweetener systems rather than awaiting novel approvals.
Direct-to-consumer subscription models are displacing traditional retail distribution for functional chocolate brands targeting specific dietary cohorts. Specialty e-commerce platforms are capturing disproportionate growth by unbundling temperature-controlled logistics from conventional confectionery supply chains. Germany's private-label health food chains demonstrate this shift most visibly through vertically integrated procurement of industrial baking grades.
Sugarless Chocolate Market Segmentation
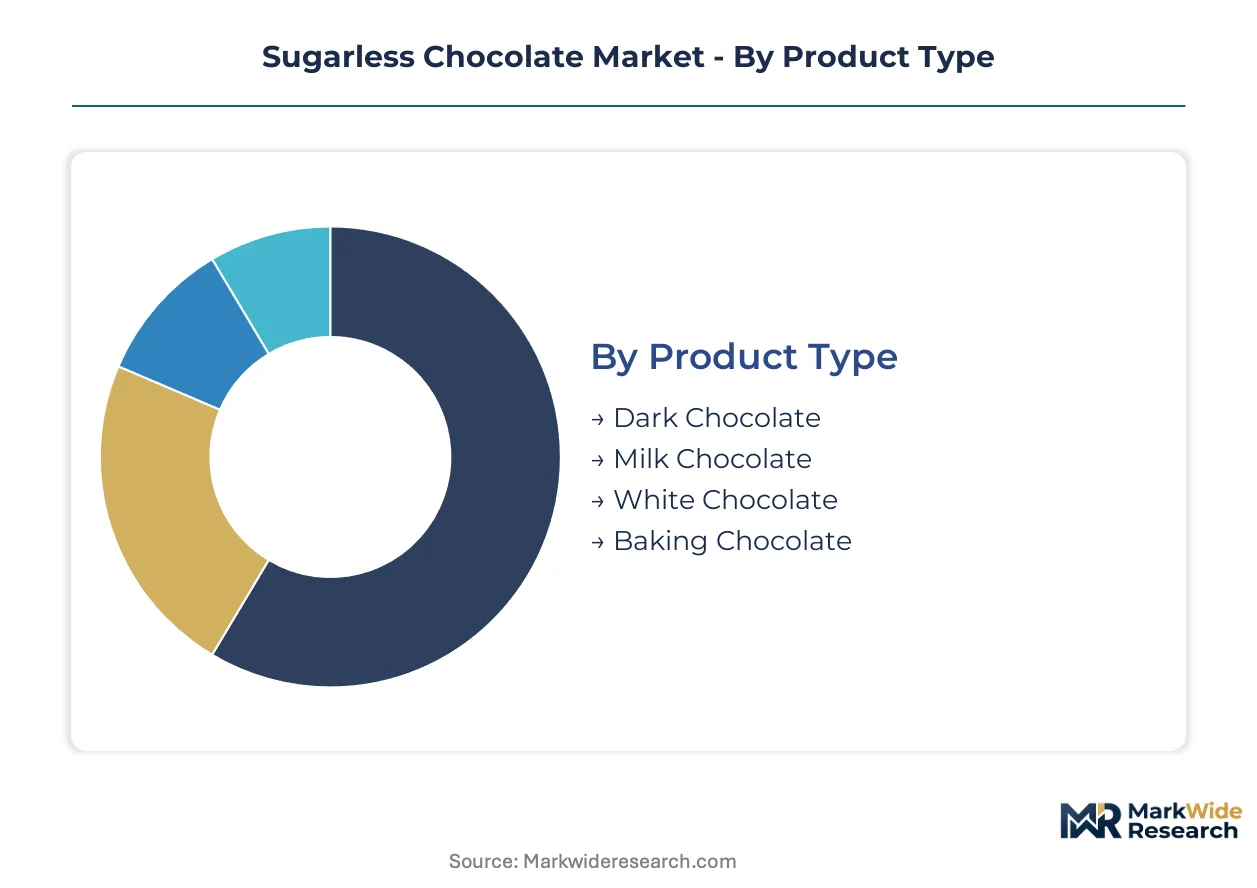
Sugarless chocolate segmentation reveals divergent technical requirements across consumer-facing and industrial applications. Product type and end-use specifications dictate sweetener selection, tempering protocols, and cocoa mass thresholds that manufacturers must navigate simultaneously.
Product Type:
Dark chocolate variants dominate export-led procurement from German industrial bakeries and Swiss confectionery exporters, while milk chocolate formulations concentrate in domestic North American retail channels constrained by FDA labeling thresholds.
- Dark Chocolate:Naturally lower baseline sugar content enables cleaner reformulation with erythritol-stevia blends. German private-label health food chains and industrial bakeries are scaling high-cocoa-mass grades fastest, driven by antioxidant health claims and established consumer acceptance of bittersweet flavor profiles.
- Baking Chocolate:Unsweetened cocoa mass specifications bypass sweetener complexity entirely for industrial dessert applications. Food manufacturers in the United States and Germany are redirecting procurement volumes toward these clean-label inputs as EFSA and FDA tighten sugar-reduction labeling requirements.
- Milk Chocolate:Technical barriers in replicating dairy-mouthfeel without sucrose limit penetration to premium positioning tiers.
- White Chocolate:Cocoa butter dependency creates formulation fragility when substituting bulk sweeteners for sucrose.
Dark chocolate holds the largest share; momentum sits with baking chocolate.
End User:
Volume concentration tilts toward industrial procurement channels where formulation consistency and scale economics override premium positioning.
- Food Manufacturers:Reformulated confectionery and functional snack lines drive bulk procurement of sugarless chocolate with standardized tempering specifications. German industrial bakeries represent the fastest-expanding demand cluster, pulling high-cocoa-mass baking grades through vertically integrated supply arrangements.
- Retail Consumers:Diabetic and ketogenic cohorts adopt subscription-based functional chocolate brands through direct-to-consumer channels, prioritizing clean-label sweetener systems over mass-market accessibility.
- Bakeries:Pastry applications require controlled snap and gloss replication that narrows viable sweetener options.
- Restaurants:Dessert menu reformulation lags retail adoption due to per-portion cost sensitivity and inventory complexity.
Food manufacturers command volume leadership; retail consumers are expanding most quickly.
Distribution Channel:
Temperature-controlled logistics requirements fragment channel economics between conventional retail and specialty e-commerce infrastructure.
- Online Retail:Subscription models targeting diabetic and ketogenic consumers bypass conventional confectionery supply chains through dedicated temperature-controlled fulfillment. This channel captures disproportionate growth for functional chocolate brands with direct logistics integration.
- Supermarkets:Mainstream shelf presence anchors mass-market accessibility, with The Hershey Company leveraging North American manufacturing scale for retail dominance.
- Specialty Stores:Swiss heritage positioning and premium single-origin tiers concentrate in this channel.
- Health Food Shops:German private-label chains demonstrate vertically integrated procurement of industrial baking grades alongside consumer-facing SKUs.
Supermarkets retain volume dominance; online retail shows steepest expansion trajectory.
Form:
Industrial input forms concentrate procurement in bulk formats while consumer convenience drives bar and chip innovation.
- Bars:Standardized tempering curves and fat-phase structuring enable functional parity with conventional chocolate in the dominant retail format. Lindt & Sprüngli's sustained R&D intensity in cocoa-butter equivalent formulations targets this segment for reduced-calorie positioning.
- Baking Pieces:Industrial dessert and pastry applications favor this form for clean-label reformulation, with German bakeries scaling volumes fastest among food manufacturer end users.
- Chips:Cookie and confectionery inclusions require precise melt-point engineering that constrains sweetener selection.
- Coated Nuts:Fat-phase adhesion complexity limits clean-label claims in this niche application.
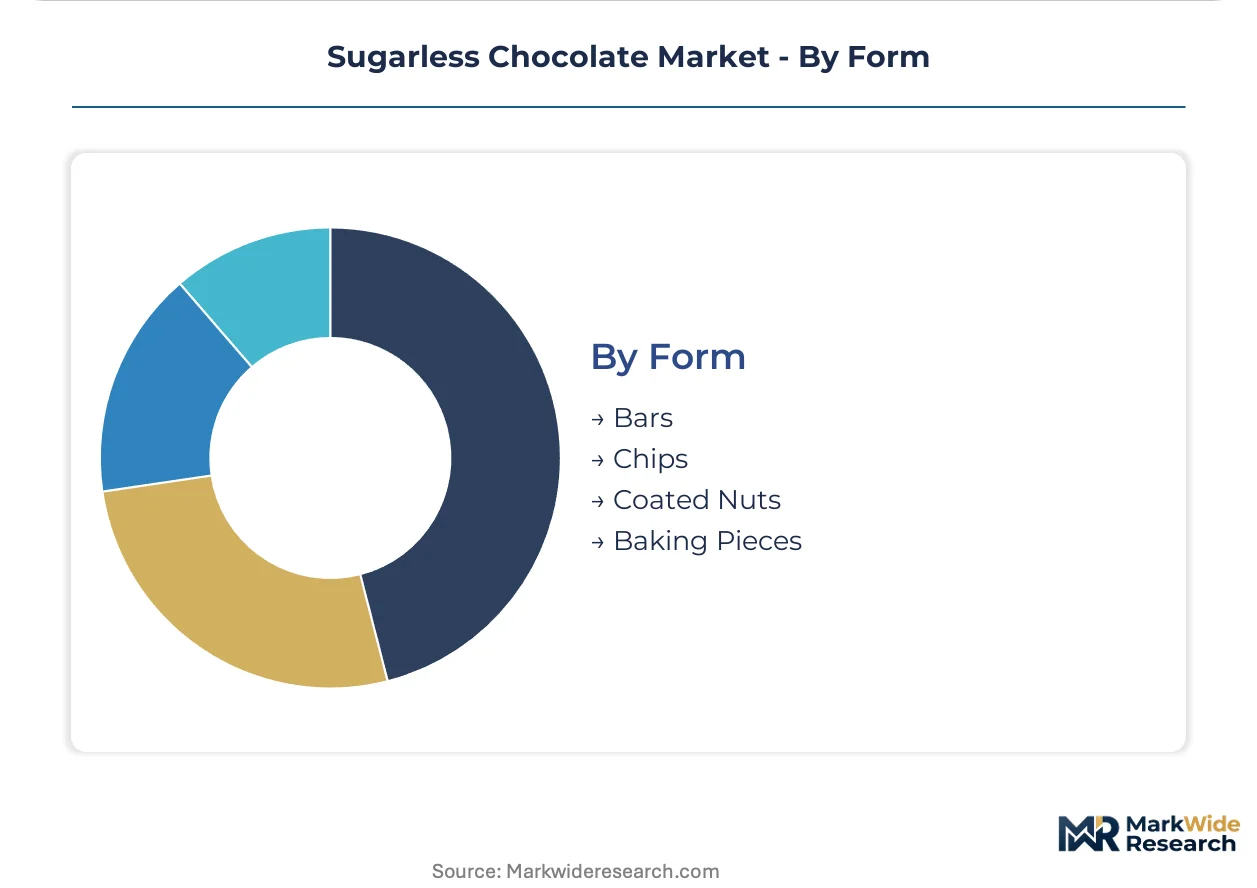
Bars maintain category leadership; baking pieces are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led supply from Swiss and German manufacturers meets import-dependent demand across Asia-Pacific and North American markets. Trade flows concentrate high-cocoa-mass industrial grades toward food manufacturing clusters while retail-ready formulations circulate through regional distribution hubs. Regulatory divergence between FDA and EFSA sweetener approvals fragments product availability across Atlantic markets.
United States
FDA sugar-free labeling thresholds redirect domestic R&D spending toward maltitol and allulose systems. The agency's Food Additives Regulations govern sweetener safety profiles that shape retail formulation pipelines. Pennsylvania-based manufacturing anchors North American supply for mainstream sugarless segments.
Germany
Private-label health food chains and industrial bakeries generate Europe's fastest-scaling demand pull for high-cocoa-mass baking grades. EFSA novel food approval timelines for emerging bulk sweeteners freeze capital allocation in regulatory review. Cologne and Hamburg clusters concentrate vertically integrated procurement of industrial chocolate inputs.
Switzerland
Swiss heritage positioning commands premium-tier pricing across export markets for reduced-calorie cocoa-butter equivalent formulations. Swissmedic oversees food safety standards that align with EU frameworks while preserving distinct national requirements. Zurich and Kilchberg centers sustain R&D intensity in tempering curve optimization.
India
BIS packaged food regulations mandating minimum cocoa content standards create import specification clarity for multinational entrants. FSSAI oversight of packaged confectionery builds compliance infrastructure that favors established international suppliers. Maharashtra and Gujarat industrial corridors attract reformulated chocolate manufacturing investments.
Japan
Functional food positioning drives consumer acceptance of sugarless chocolate through established health-claim frameworks. PMDA and Ministry of Health oversight of food additives maintains strict approval pathways for novel sweeteners. Tokyo-Osaka distribution networks prioritize temperature-stable logistics for premium confectionery segments.
Sugarless Chocolate Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and heritage positioning dimensions. The market exhibits tiered concentration with multinational conglomerates anchoring mass-market volume while private specialists capture premium positioning through origin narratives and formulation expertise. Three archetypes dominate: scale-driven retail giants, heritage-positioned European chocolatiers, and industrial ingredient suppliers. Competitive moves center on backward integration into cocoa sourcing and strategic partnerships with sweetener technology developers.
Within the heritage-positioned tier, Lindt & Sprüngli exemplifies sustained R&D investment in reduced-calorie fat-phase structuring. Among North American scale players, The Hershey Company occupies a position representing manufacturing footprint leverage for retail shelf dominance. Barry Callebaut sits within the industrial supply archetype, anchoring business-to-business procurement relationships with food manufacturers seeking standardized tempering specifications.
| Leading Market Players |
|---|
| The Hershey Company |
| Mars, Incorporated |
| Nestlé S.A. |
| Mondelez International |
| Lindt & Sprüngli |
| Ferrero Group |
| Russell Stover Chocolates |
| Ghirardelli Chocolate Company |
| Barry Callebaut |
| Others |
Value Network & Pricing Analysis
FDA sugar-free labeling thresholds gate both supplier qualification and price differentiation simultaneously, compressing development timelines while stratifying procurement costs across clean-label and legacy formulation tiers. Industrial buyers face tiered access to maltitol and allulose supply streams that separate premium positioning from mass-market penetration.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in sugarless chocolate procurement. Price differentiation separates Swiss heritage-positioned cocoa-butter equivalent formulations from commodity maltitol-dependent grades and emerging allulose clean-label tiers. Pricing pressure stems from EFSA novel food approval friction freezing capital in regulatory limbo for European launch windows. Food manufacturers exhibit highest price sensitivity due to volume scale and formulation consistency requirements, while subscription-based direct-to-consumer brands absorb premium positioning for diabetic and ketogenic cohorts.
Supply Chain Analysis
Container availability constraints on Hamburg-Rotterdam trade lanes amplify inbound logistics costs for cocoa butter equivalent inputs sourced from West African and Southeast Asian origins. Supply concentration centers on Switzerland for premium heritage manufacturing, Germany for industrial baking grade production, and the United States for mass-market retail formulation. Raw material dependencies span cocoa mass from Ghana and Côte d'Ivoire, specialty fat-phase inputs from Malaysia and Indonesia, and bulk sweetener supply from Chinese and Indian chemical processors. Single-source vulnerability in allulose production creates structural risk for clean-label product pipelines. Distribution runs through temperature-controlled logistics networks that unbundle conventional confectionery supply chains for functional chocolate brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sugarless chocolate sits in early-cycle expansion as ketogenic and diabetic consumer cohorts accelerate adoption through subscription channels ahead of mass-market penetration curves.
For Market Incumbents: Compound manufacturing scale advantages by anchoring retail shelf presence in mainstream segments while pre-positioning allulose formulation pipelines before regulatory windows open. Threats from emerging clean-label specialists with direct-to-consumer logistics demand backward integration into sweetener technology partnerships. Priority levers include captive supply of high-cocoa-mass baking grades for German industrial bakery procurement and certification investment for dual-jurisdiction FDA-EFSA approval pathways. For New Entrants and Emerging Players: FDA fast-track approval for novel bulk sweeteners enables first-mover positioning in subscription-based ketogenic channels where incumbent logistics integration lags. White-space targets concentrate in industrial baking grade supply to German private-label health food chains and allulose-erythritol convergence applications for clean-label dessert reformulation. The most penetrable segment is direct-to-consumer functional chocolate with temperature-controlled fulfillment unbundled from conventional retail distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clean-label sweetener technology development as EFSA review timelines extend and FDA enforcement tightens. Long-term viability over a 5-10 year window favors acquisition targets with hybrid confectionery science and sweetener chemistry expertise, established dual-jurisdiction certification infrastructure, and captive relationships with German industrial bakery demand clusters. The signal to watch is EFSA allulose approval timeline compression as an inflection indicator for European market access windows.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Sweetener Partnership | Allulose-erythritol blending protocols unlock mass-market accessibility ahead of regulatory approval windows. |
| Temperature-Controlled Logistics Buildout | Unbundled fulfillment networks capture disproportionate growth in ketogenic subscription channels. |
| Dual-Jurisdiction Certification Investment | Simultaneous FDA and EFSA approval pathways reduce compliance timeline fragmentation for novel formulations. |
| Industrial Baking Grade Capacity Expansion | Vertically integrated procurement relationships with German private-label chains concentrate volume leadership. |
| Cocoa-Butter Equivalent R&D Intensification | Controlled tempering curve optimization replicates snap and gloss parity with conventional chocolate. |
Research Methodology
A spread of perspectives from confectionery R&D directors, food manufacturer procurement leads, sweetener technology specialists, regulatory affairs consultants, and health food retail category buyers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA Food Additives Regulations filings, EFSA novel food approval databases, BIS packaged food standards documentation, customs trade data for cocoa mass and sweetener inputs, and SEC filings from listed confectionery manufacturers. Bottom-up demand modeling from end-use procurement patterns and top-down supply assessment from manufacturing capacity disclosures were triangulated for convergence.
Segmentation dimensions modeled span product type tiers, end-user procurement channels, distribution infrastructure formats, and cocoa mass specification grades across the analysis window. Analytical framework approach derives CAGRs from volume-weighted average growth trajectories calibrated to regulatory approval timelines and industrial procurement cycle data. Forecast inputs incorporate sweetener adoption curves by consumer dietary cohort, tempering technology maturity thresholds, and regional labeling mandate enforcement intensity.
Underlying assumptions cover EFSA novel food approval progression, FDA sugar-free labeling threshold stability, and cocoa supply chain continuity, with deviation risk concentrated in regulatory timeline extensions and tropical origin disruption. Recalibration cycles align with material shifts in sweetener approval protocols and front-of-pack labeling mandate implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Edible Glitter Market
Confectionery
UK Confectionery Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
UK Compound Chocolate Market
Confectionery
Global Mochi Market
Confectionery
Low-Calorie Jelly Market
Confectionery
South Africa Confectionery Market
Confectionery
China Chocolate Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Gum Base Candy Market
Confectionery
Crunchy Chocolate Market
Confectionery
Bangladesh Candy Market
Confectionery
Low-Fat Candy Market
Confectionery
Saudi Arabia Chocolate Market
Confectionery
India Chocolate Market