
 Edible Glitter Market | 2026-2036
Edible Glitter Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Glitter Market Foresight
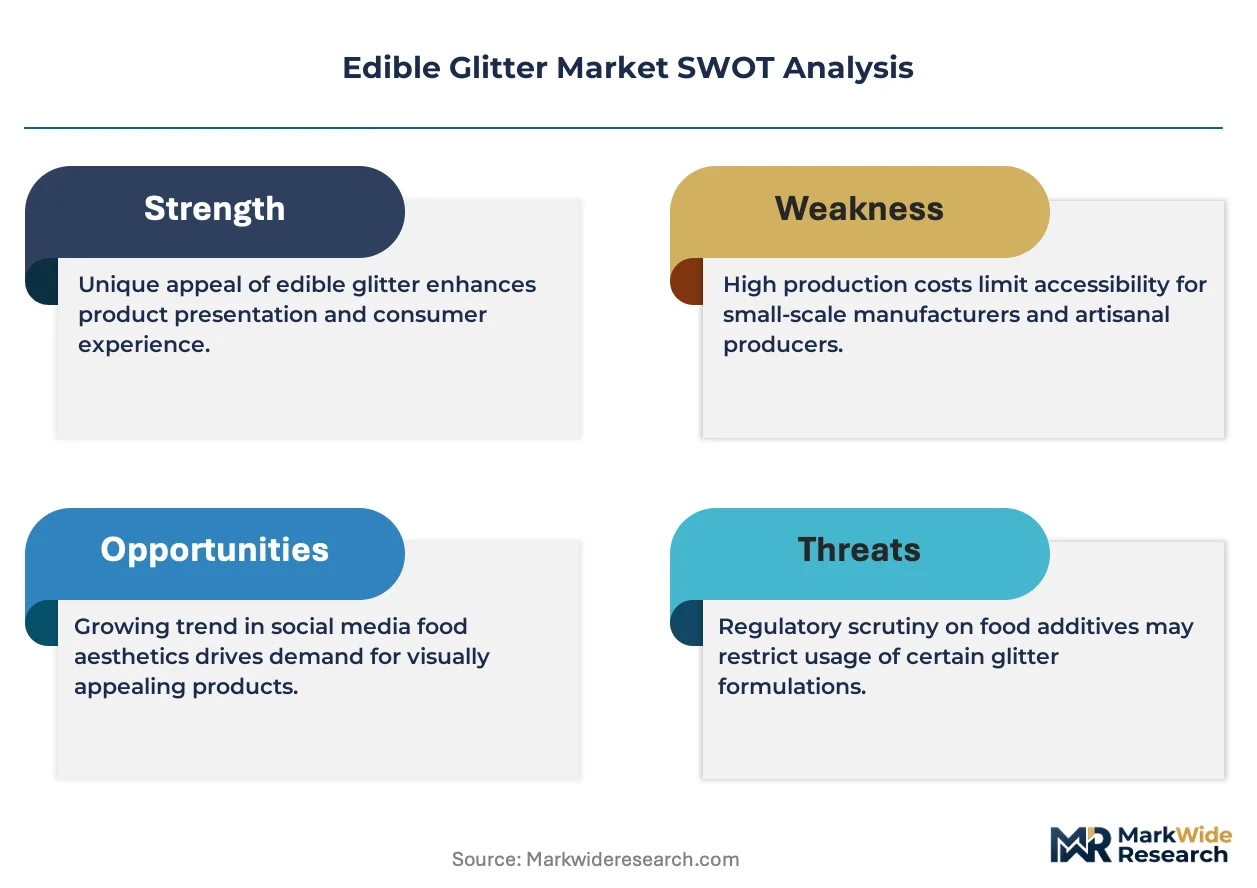
The edible glitter category is shifting along a sharp divide between artisan-grade mineral and plant-based formulations and mass-market synthetic dust. Wilton Brands leverages its retail shelf presence and decades of brand recognition to dominate the home-baking channel. Krebs Pigment anchors industrial supply relationships with European confectionery manufacturers seeking compliant mineral-derived shimmer. Meadowbrook Inventions specializes in thin-film flake technology that controls particle geometry for predictable light refraction in beverage applications.
Edible glitter comprises food-safe reflective particles, typically manufactured through precision milling of mineral substrates or controlled crystallization of plant-based starches, with particle sizes ranging from 50 to 400 microns to achieve specific visual density on coated surfaces. Its primary commercial purpose is to deliver decorative luminosity to consumable goods without altering flavor profiles or mouthfeel. The ingredient source dimension shows natural and plant-based categories capturing margin pools as clean-label requirements intensify across baking and confectionery segments, while synthetic formulations still occupy volume leadership in party supplies where cost sensitivity dominates purchasing decisions. Distribution through food service and wholesale channels sustains the fastest growth trajectory as commercial bakeries integrate shimmer into standard product specifications rather than treating it as seasonal novelty.
The FDA regulates edible glitter through its color additive program, requiring batch certification for synthetic dyes and pre-market approval for novel mineral sources, while the EU enforces EFSA safety evaluations and REACH compliance for non-food-contact processing aids. These frameworks elevate compliance costs for new entrants and favor established suppliers with dedicated regulatory affairs functions. Stakeholders must monitor evolving definitions of "natural" across jurisdictions, as classification disputes directly determine permissible ingredient lists and labeling claims.
Market Dynamics
Clean-label mandates from retail chains and food service distributors are forcing reformulation across the edible glitter supply base, compressing margins for synthetic mineral producers while opening margin pools for plant-based and mineral-derived alternatives that meet evolving natural claims standards.
Growth Catalysts
- EU REACH compliance evolution:ECHA's tightening scrutiny on microplastic additives in food contact materials is accelerating migration toward certified mineral and plant-based shimmer substrates.
- Beverage carbonation innovation:Hard seltzer and craft cocktail producers specify thin-film flake geometries for suspended visual effects in transparent liquids.
- Japan:METI's promotion of food export quality standards drives domestic manufacturers toward premium edible decoration for international confectionery markets.
Market Restraints
- Mica supply concentration:Cosmetic-grade mica processing clusters in India and Madagascar create single-source vulnerability for mineral-derived shimmer.
- FDA batch certification delays:Synthetic color additive lot approvals stretch 90-180 days, freezing inventory turns for new entrants.
- Technical particle size limits:Sub-50 micron milling achieves opacity but risks inhalation classification, capping visual density in dry applications.
Strategic Opportunities
- Germany:Artisan bakery cooperatives seek compliant shimmer for regional protected-designation pastries with export potential.
- Direct-to-baker subscription channels:Monthly formulation kits bypass distributor markups and build recurring revenue with home-baking enthusiasts.
- ISO 22000 certification convergence:Unified food safety standards reduce multi-market compliance duplication for exporters.
Industry Challenges
- Food technologist scarcity:Formulation chemists with dual expertise in optical physics and flavor masking command premium compensation, constraining R&D scaling.
- Legacy equipment retrofit costs:Existing confectionery coating lines require pneumatic system upgrades to handle low-density flake without static aggregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Glitter Market |
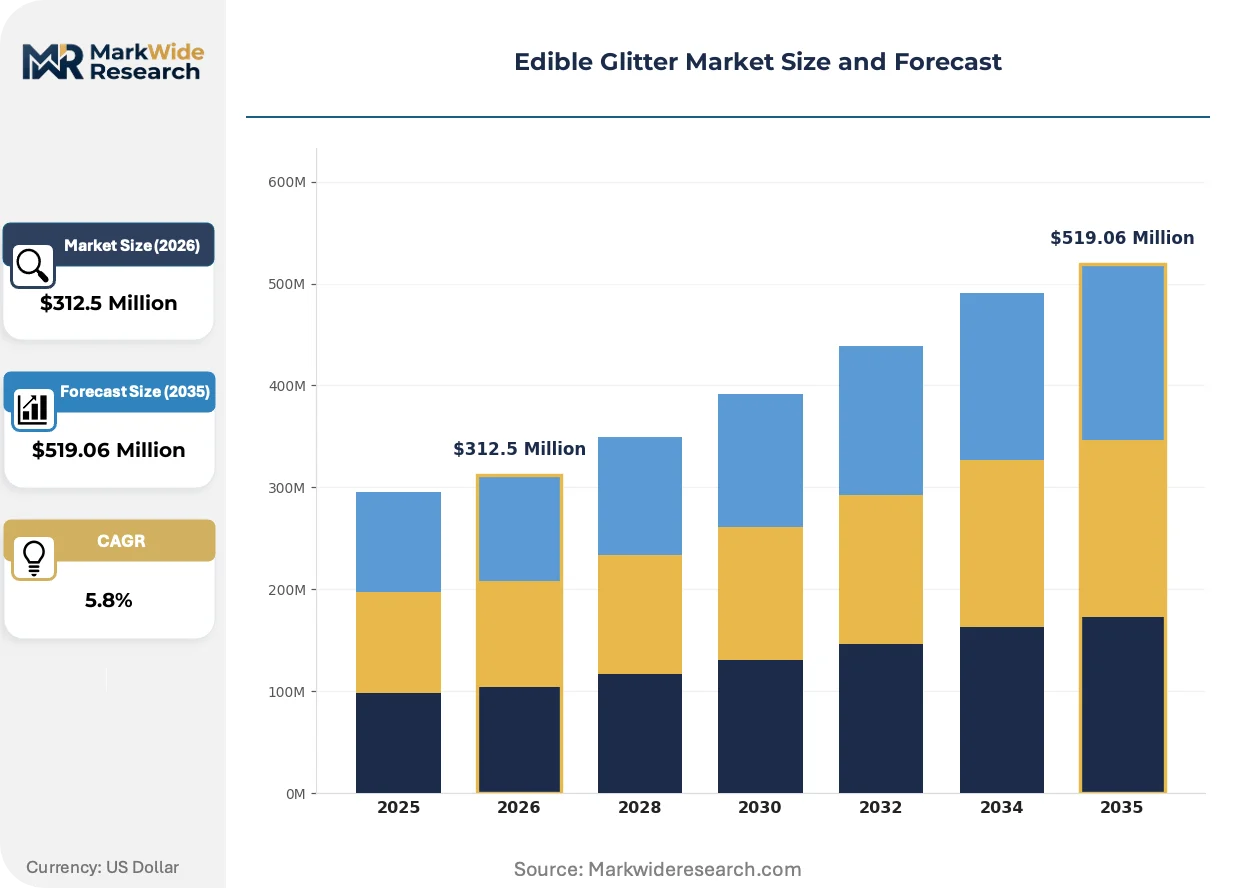
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprinkles, Dust, Gel, Flakes Application: Baking, Confectionery, Beverages, Party Supplies Ingredient Source: Natural, Synthetic, Plant-Based, Mineral Distribution Channel: Online, Retail Stores, Food Service, Wholesale |
| Companies Covered | Wilton Brands, Krebs Pigment, Callebaut, Meadowbrook Inventions, Brew Glitter, JDI Distribution, Sugarflair, AmeriColor, Duncan Hines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Glitter Market Shifts & Advancements
Formulation science and regulatory classification are diverging sharply, with optical performance standards now decoupled from legacy color-additive frameworks as novel substrates enter commercial testing.
Cellulose nanocrystal arrays derived from agricultural waste streams are decentralizing production geography by enabling regional milling facilities to substitute for concentrated mineral processing hubs. Artisan confectioners in the Pacific Northwest and Nordic clusters adopt these substrates for carbon-footprint reduction claims. The technology is decentralizing supply chain risk away from mica-dependent formulations concentrated in South Asian processing centers.
EFSA's 2023 re-evaluation of titanium dioxide as a food additive has triggered reformulation cascades across EU-licensed products, forcing manufacturers toward calcium carbonate and calcium phosphate alternatives with comparable refractive indices. Industrial bakeries in France and Italy face six-month reformulation windows to maintain distribution contracts. The policy shift most acutely affects white-base shimmer products where TiO2 provided opacity at low cost.
Buying committees at national bakery chains now consolidate specification authority previously held by regional procurement managers, compressing supplier lists to three approved vendors per substrate category. This concentration is displacing specialty distributors who previously carried 15-20 shimmer SKUs. The shift is most visible in the United States, where top-10 bakery chains account for rising share of food service channel volume.
Edible Glitter Market Segmentation
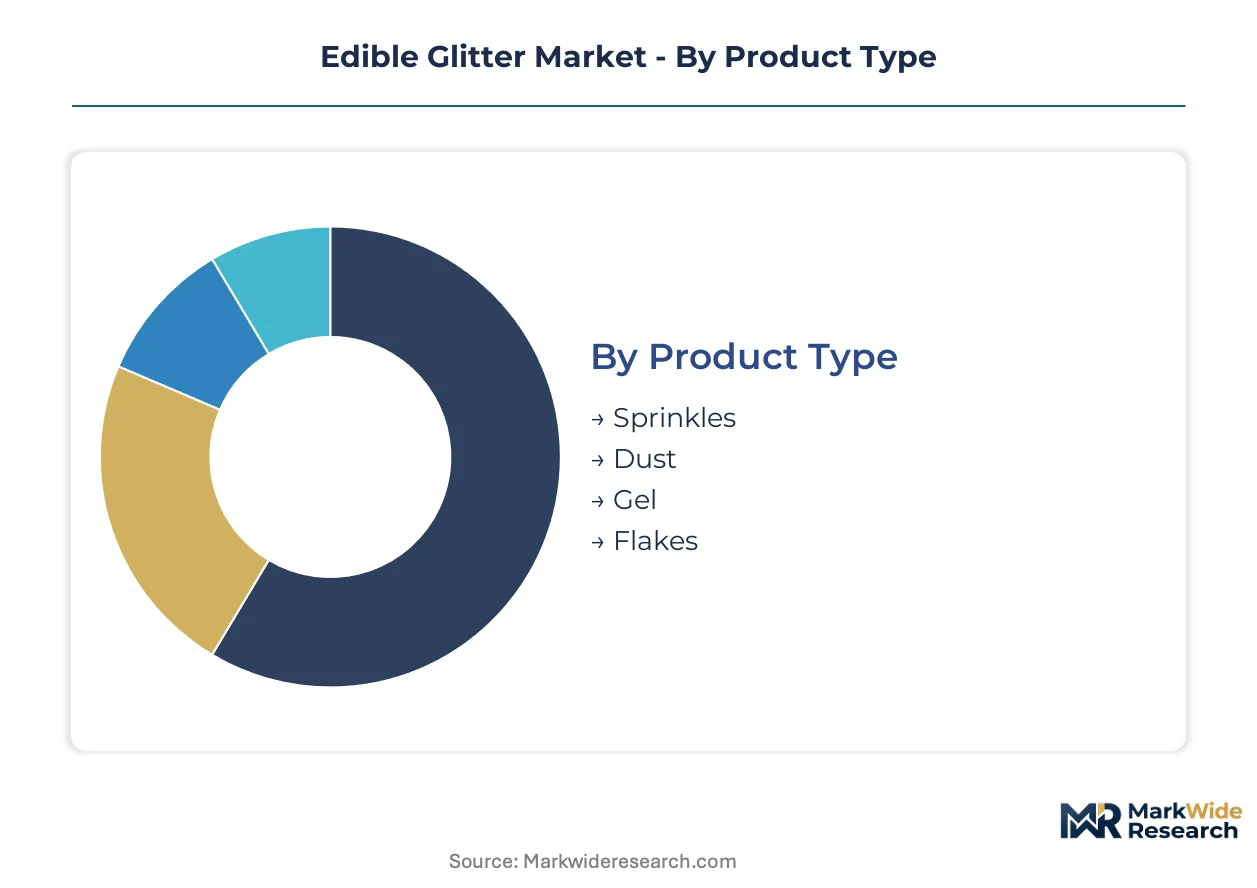
Edible glitter formulation varies sharply across physical formats and supply chain tiers, with particle geometry and substrate chemistry determining permissible applications and margin capture. Each segmentation axis reveals distinct competitive dynamics between mass-market volume plays and premium specification products.
Product Type:
Supply concentration in thin-film flake manufacturing clusters around specialized coating equipment in Germany and Japan, while dust and sprinkle production disperses across commodity food processing facilities.
- Flakes:Precision-rolled thin-film substrates deliver controlled light refraction through defined particle aspect ratios. Beverage carbonation brands in the United States and craft cocktail producers in Japan specify suspended flake geometries for transparent liquid visual effects, though static aggregation risks on legacy pneumatic lines constrain adoption.
- Dust:Finely milled mineral or starch particles achieve high surface coverage density at low application weights. Artisan confectioners in Germany and industrial bakeries in the United States absorb the bulk of food-grade dust volume, with FDA batch certification delays creating inventory friction for synthetic formulations.
- Sprinkles:Larger-diameter sugar-based particles with surface shimmer coating dominate home-baking retail channels. Wilton Brands controls shelf placement through decades of brand recognition.
- Gel:Pre-dispersed shimmer in hydrocolloid carriers eliminates airborne handling concerns and enables precise pattern application. Premium cake decorators specify gel formats for controlled placement on fondant surfaces.
Flakes absorb the bulk of installed capacity; gel is expanding most quickly.
Application:
Cost tier stratification separates commodity party supply volumes from premium bakery and beverage specifications where optical performance justifies ingredient premiums.
- Baking:Artisan and industrial bakeries integrate shimmer into standard product lines rather than seasonal novelty. Regional protected-designation pastry producers in Germany seek compliant mineral-derived shimmer for export-qualified goods.
- Beverages:Hard seltzer and craft cocktail producers drive thin-film flake demand for suspended visual effects in carbonated transparent liquids. METI's food export quality standards push Japanese manufacturers toward premium edible decoration for international confectionery markets.
- Confectionery:European manufacturers face EFSA-driven reformulation cascades away from titanium dioxide toward calcium carbonate alternatives with comparable refractive indices.
- Party Supplies:Synthetic formulations occupy volume leadership where cost sensitivity dominates purchasing decisions and regulatory scrutiny remains minimal.
Baking commands the deepest supplier relationships; beverages are climbing the fastest.
Ingredient Source:
Customer type bifurcation splits clean-label mandates from price-driven procurement, with retail chains and food service distributors forcing reformulation across the supply base.
- Plant-Based:Cellulose nanocrystal arrays derived from agricultural waste enable regional milling facilities to substitute for concentrated mineral processing hubs. Pacific Northwest and Nordic artisan confectioners adopt these substrates for carbon-footprint reduction claims.
- Mineral:Mica-derived shimmer from Indian and Madagascar processing clusters serves European confectionery manufacturers seeking REACH-compliant substrates. Single-source vulnerability constrains supply security.
- Natural:Clean-label requirements intensify across baking segments, opening margin pools for certified natural categories that meet evolving claims standards.
- Synthetic:FDA color additive batch certifications stretch 90-180 days, freezing inventory turns for new entrants while established suppliers with dedicated regulatory functions defend position.
Mineral absorbs the bulk of installed capacity; plant-based is gaining share fastest.
Distribution Channel:
Volume concentration shifts toward food service and wholesale as commercial bakeries integrate shimmer into standard specifications, compressing specialty distributor roles.
- Food Service:National bakery chains consolidate specification authority previously held by regional procurement managers, compressing approved vendor lists to three per substrate category.
- Wholesale:Industrial bakeries in France and Italy face six-month reformulation windows to maintain distribution contracts following EFSA titanium dioxide re-evaluation.
- Online:Direct-to-baker subscription channels bypass distributor markups and build recurring revenue with home-baking enthusiasts through monthly formulation kits.
- Retail Stores:Home-baking channel dominance by established brands with decades of shelf presence constrains new entrant access.
Food service absorbs the bulk of installed capacity; online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago's commercial bakery corridor drives North American formulation standards, while Stuttgart's precision coating equipment clusters anchor European thin-film flake production. Tokyo's confectionery export quality protocols shape premium specifications across Pacific markets.
United States
National bakery chains consolidate supplier lists to three approved vendors per substrate category, compressing specialty distributor roles. FDA color additive batch certifications stretch 90-180 days, freezing inventory turns for new entrants. Hard seltzer producers in the Pacific Northwest specify suspended flake geometries for carbonated transparent liquids.
Germany
Artisan bakery cooperatives in Bavaria seek REACH-compliant shimmer for regional protected-designation pastries with export potential. ECHA's tightening scrutiny on microplastic additives accelerates migration toward certified mineral and plant-based substrates. Stuttgart's specialized coating equipment manufacturers supply precision-rolling technology to European confectionery producers.
Japan
METI's promotion of food export quality standards drives domestic manufacturers toward premium edible decoration for international confectionery markets. Craft cocktail producers in Tokyo and Osaka specify thin-film flake geometries for suspended visual effects. Kanto region food technologists command premium compensation for dual expertise in optical physics and flavor masking.
United Kingdom
Clean-label mandates from retail chains force reformulation across the supply base, compressing margins for synthetic mineral producers. EFSA's titanium dioxide re-evaluation triggers reformulation cascades across licensed products, forcing six-month windows to maintain distribution contracts. London-based food service distributors consolidate specification authority previously held by regional procurement managers.
India
Cosmetic-grade mica processing clusters in Jharkhand and Rajasthan create single-source vulnerability for mineral-derived shimmer supply security. FSSAI's evolving food additive standards constrain permissible ingredient lists for export-qualified goods. Mumbai's industrial bakeries integrate shimmer into standard product lines rather than seasonal novelty specifications.
Edible Glitter Market Competitive Landscape
Premium-margin players sit above commodity-margin players across substrate certification tiers, with clean-label mineral and plant-based formulations capturing wider spreads than synthetic dust alternatives. The vendor base separates into three strategic archetypes: retail shelf dominants leveraging decades of brand recognition, industrial suppliers anchoring European confectionery relationships through compliant mineral sourcing, and thin-film technology specialists controlling particle geometry for beverage applications. Dominant competitive moves include backward integration into captive mica processing and ISO 22000 certification convergence to reduce multi-market compliance duplication.
Within the retail-channel archetype, Wilton Brands occupies a position exemplifying home-baking shelf presence, while Krebs Pigment sits within the industrial mineral-supply tier. Meadowbrook Inventions represents the thin-film specialization vector. These three anchors illustrate how geographic and technological positioning stratifies competitive access across food service, wholesale, and direct-to-consumer channels.
| Leading Market Players |
|---|
| Wilton Brands |
| Krebs Pigment |
| Callebaut |
| Meadowbrook Inventions |
| Brew Glitter |
| JDI Distribution |
| Sugarflair |
| AmeriColor |
| Duncan Hines |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between FDA-batch-certified synthetic formulations and REACH-compliant mineral substrates splits pricing power along compliance investment lines, with premium mineral and plant-based tiers commanding wider spreads while commodity synthetic dust faces margin compression from distributor consolidation and inventory friction.
Pricing Analysis
Yield-based pricing anchors value capture in beverage applications where suspended flake geometries command premiums tied to carbonation stability and visual density outcomes. Price differentiation separates ISO 22000-certified mineral substrates from uncertified synthetic dust, with brand premiums for established European suppliers and volume discounts for national bakery chain contracts. Pricing pressure stems from EFSA-driven reformulation costs compressing margins in white-base shimmer segments. Party supply distributors exhibit highest price sensitivity; premium cake decorators and craft cocktail producers show lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Chicago, and Tokyo coordinate hub-and-spoke patterns for thin-film flake and gel formats, while dust and sprinkles flow through dispersed commodity food processing nodes. Geographic supply concentration centers on India and Madagascar for cosmetic-grade mica, Germany and Japan for precision coating equipment, and the United States for home-baking retail shelf presence. Raw material dependencies include mineral mica substrates, agricultural cellulose feedstocks, and synthetic colorant precursors. Single-source vulnerability in South Asian mica processing creates supply security exposure. Distribution runs through consolidated food service vendor lists and direct-to-baker subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation is forcing consolidation as smaller synthetic producers lack capital for multi-jurisdiction certification investments.
For Market Incumbents: Deepen backward integration into captive mica processing in Jharkhand or Rajasthan to secure mineral substrate supply against single-source disruption. Expand ISO 22000 certification coverage across European and Asia-Pacific production facilities to reduce compliance duplication costs. Anchor industrial relationships through long-term offtake agreements with national bakery chains consolidating vendor lists to three approved suppliers per category. For New Entrants and Emerging Players: Enter via direct-to-baker subscription channels bypassing distributor markups and building recurring revenue with home-baking enthusiasts through monthly formulation kits. Target Pacific Northwest and Nordic artisan confectioner clusters adopting cellulose nanocrystal substrates for carbon-footprint reduction claims. Lead with plant-based certification narratives to capture clean-label margin pools as retail chains force reformulation across synthetic supply bases. For Investors and Strategic Acquirers: Re-rating potential sits with thin-film technology specialists controlling particle geometry for beverage applications given hard seltzer and craft cocktail demand acceleration. Long-term viability favors mineral and plant-based formulation platforms over synthetic dust exposed to FDA batch certification delays and EFSA microplastic scrutiny. Watch ECHA enforcement patterns on microplastic additives as inflection indicator for substrate migration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mica Processing | Secures mineral substrate supply against Indian and Madagascar processing concentration risks. |
| ISO 22000 Certification Convergence | Reduces multi-market compliance duplication for exporters serving EU, US, and Japan simultaneously. |
| Direct-to-Baker Subscription Launch | Bypasses consolidated food service distributor markups and builds recurring revenue streams. |
| Cellulose Nanocrystal Platform Development | Enables regional milling substitution for South Asian mica-dependent supply chains. |
| Long-Term Supply Agreement with National Bakery Chains | Locks in volume commitments as buying committees compress approved vendor lists. |
Research Methodology
Trade association filings, customs records, and regulatory submission databases formed the secondary backbone, supplemented by primary interviews with food technologists, bakery procurement managers, confectionery R&D directors, and food service distributor category buyers. Bottom-up volume modeling triangulated against top-down value estimates derived from channel shipment data and ingredient cost structures across synthetic, mineral, and plant-based substrate tiers.
Historical trendline analysis established baseline growth patterns across the projection horizon, with segmentation modeling spanning physical format, application end-use, ingredient source chemistry, and distribution channel. CAGRs were derived from elasticity-adjusted demand curves incorporating beverage carbonation innovation rates, clean-label mandate diffusion patterns, and regulatory approval timeline impacts. Forecast inputs included EFSA reformulation cascade timing, METI export quality standard adoption curves, and national bakery chain vendor consolidation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA microplastic enforcement acceleration or FDA color additive program restructuring. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Truffle Chocolate Market
Confectionery
Chocolate Couverture Market
Confectionery
Fruit Jellies Market
Confectionery
Gummy Candy Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Low-Calorie Candy Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
Sugar Free Mints Market
Confectionery
Japan Chocolate Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Mints Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Global Candy Market
Confectionery
Sugar-Free Confectionery Market