
 Global Mochi Market | 2026-2036
Global Mochi Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mochi Market Outlook
Flash-freezing and modified atmosphere packaging is reshaping how mochi products retain texture across extended supply chains. Yamazaki Baking leverages its bakery-distribution integration to sustain refrigerated mochi freshness in Japanese convenience channels. Mikawaya anchors the North American premium segment through specialized ice cream mochi production in California. Morinaga & Company dominates Japanese mass-market shelf-stable formats with process-controlled rice flour hydration systems.
Mochi is a Japanese glutinous rice cake produced by steaming short-grain japonica rice, pounding it into a cohesive paste, and forming it into shapes with moisture content typically between 40-50% by weight. Its primary commercial purpose spans ceremonial confectionery, dessert bases, and increasingly frozen novelties where the elastic starch matrix provides distinctive mouthfeel. Traditional mochi retains the largest volume share in East Asian ceremonial and seasonal markets, while ice cream mochi generates the fastest value growth in Western retail freezers due to premium positioning. Distribution through food service channels captures the highest margin pools in North America and Europe, where restaurant and cafe applications command markup over supermarket formats.
Japan's Ministry of Health, Labour and Welfare sets food additive and labeling standards that constrain flavoring and preservative use in traditional formulations. The US FDA and USDA jointly regulate mochi imports under dairy and grain product classifications, with ice cream mochi subject to frozen dessert standards. EU EFSA guidance on rice-based products shapes arsenic content thresholds that affect import sourcing from specific growing regions. Stakeholders must monitor how evolving frozen dessert regulations in target export markets will reshape formulation requirements and facility certification needs.
Market Dynamics
Flash-freezing infrastructure and modified atmosphere packaging are compressing shelf-life constraints that once limited mochi distribution to local markets, forcing capital reallocation toward cold-chain assets and process-controlled hydration systems.
Growth Catalysts
- Japan's F-Gas Regulation:Compliance mandates for frozen mochi logistics are accelerating cold-chain modernization investments across refrigerated transport networks.
- Premium dessert applications:North American food service channels are pulling mochi into high-margin restaurant and cafe placements.
- South Korean convenience retail:Lotte and CJ-led distribution networks dominate frozen snack placement, concentrating demand in 24-hour retail formats.
Market Restraints
- Glutinous rice input volatility:Japonica rice prices fluctuate with climate patterns in Thailand and Vietnam, squeezing margin predictability for mass-market producers.
- Arsenic content thresholds:EU EFSA guidance on rice-based products constrains sourcing from specific growing regions, limiting supplier pools.
- Technical limitation:Traditional mochi's 40-50% moisture content creates textural degradation beyond 72 hours without frozen stabilization, blocking ambient distribution expansion.
Strategic Opportunities
- Underpenetrated Western European retail:Germany and France show minimal frozen mochi shelf presence relative to ice cream novelty penetration rates.
- Regulatory tailwind:US FDA frozen dessert standards provide a compliance pathway that Japanese exporters can leverage against unregulated artisanal competitors.
- Technology convergence:Flash-freezing combined with modified atmosphere packaging enables ambient-thaw textures previously achievable only with fresh production.
Industry Challenges
- Skill gap in rice flour hydration:Process-controlled systems require technicians trained in moisture-content calibration, a competency scarce outside Japan.
- Facility certification timelines:US USDA dairy-grain dual classification for ice cream mochi extends approval cycles by 8-14 months for new entrants.
- Supply chain reconfiguration friction:Integrating flash-freezing capacity into existing bakery infrastructure demands workflow redesign and floor-space reallocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mochi Market |
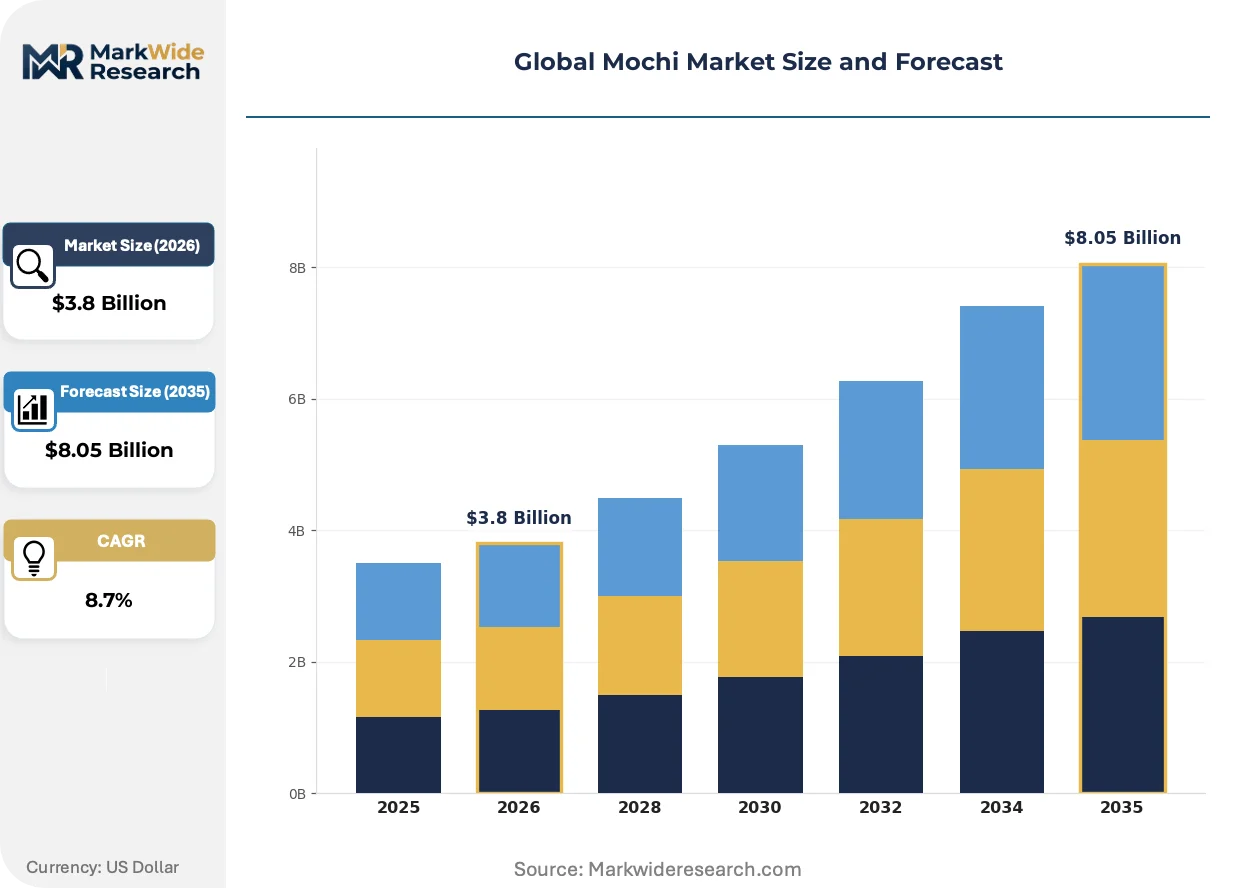
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Mochi, Ice Cream Mochi, Chocolate Mochi, Savory Mochi Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service Ingredient Type: Gluten-Free Flour, Rice Flour, Sweeteners, Natural Flavors Packaging Type: Flexible Pouches, Boxes, Vacuum Packs, Trays |
| Companies Covered | Yamazaki Baking, Mikawaya, Morinaga & Company, Maeda-en, Daifuku, Lotte Confectionery, Royal Family Food, Fugetsu-Do, Nissin Foods Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mochi Market Strategic Shifts
Texture-preservation technologies and regulatory compliance frameworks are converging to redefine competitive boundaries between artisanal producers and scaled manufacturers.
Flash-freezing technology paired with modified atmosphere packaging is virtualizing the freshness window that once tethered mochi production to immediate consumption. North American food service buyers are adopting these systems at accelerating rates to support extended distribution without quality degradation. The technology is virtualizing regional production advantages, allowing California-based facilities to serve East Coast markets with texture parity to local Japanese production.
EU F-Gas Regulation phase-down schedules are forcing refrigerant transitions across frozen mochi logistics networks. Industrial cold-chain operators must retrofit transport assets with lower-global-warming-potential alternatives, raising capital intensity for cross-border distribution. Ice cream mochi exporters to Germany and France face the steepest compliance curves as national implementations tighten ahead of baseline EU timelines.
Buyer concentration in South Korean convenience retail is compressing supplier negotiation leverage and accelerating private-label development. CJ and Lotte distribution networks now demand exclusive formulation variants, displacing open-market product specifications. This pattern is most visible in Seoul's 24-hour retail corridor, where frozen snack placement decisions centralize with a handful of category managers.
Global Mochi Market Segmentation
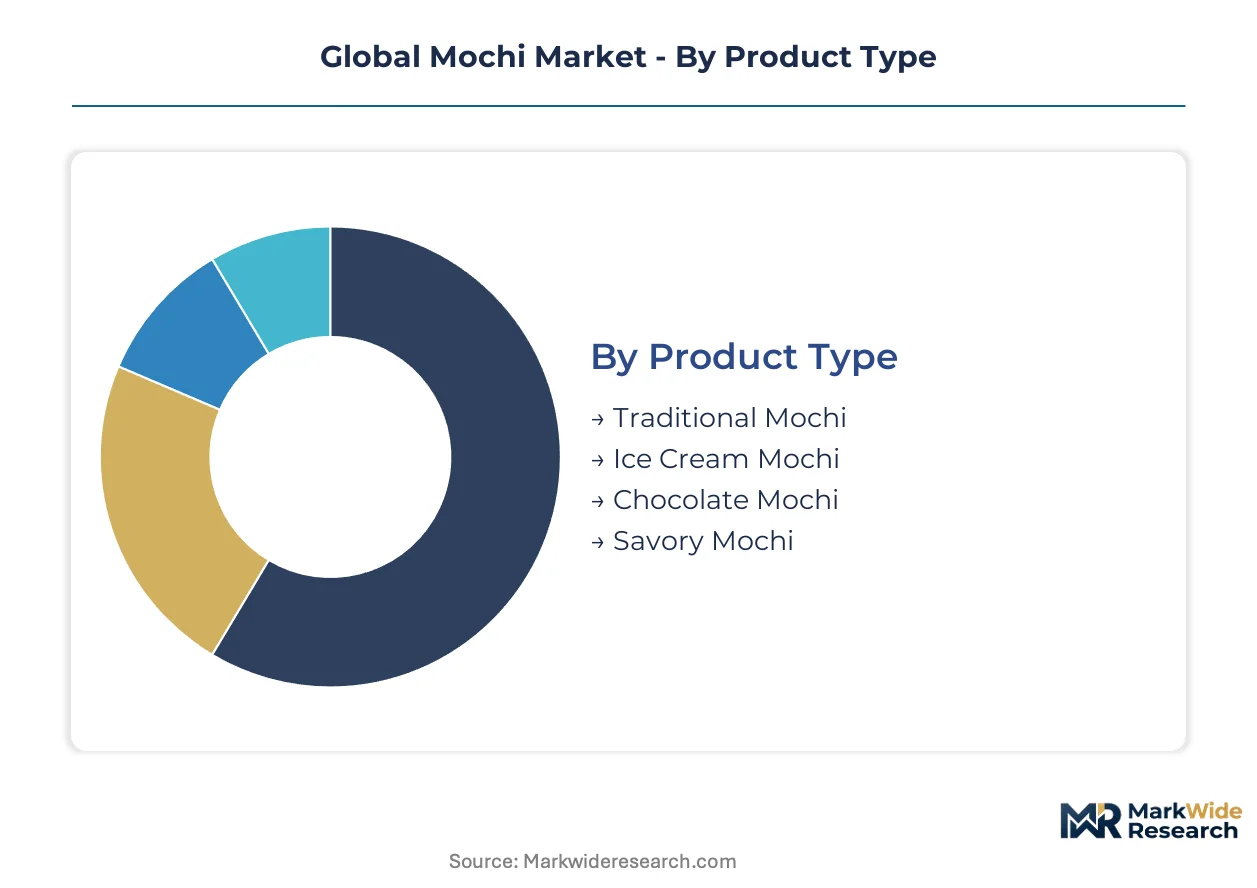
Mochi's commercial diversity spans ceremonial traditions, frozen novelties, and food service applications, each demanding distinct formulation, preservation, and distribution strategies. Segmentation reveals where capital concentrates and where regulatory or technical barriers create defensible positions.
Product Type:
Mature ceremonial formats coexist with emerging frozen and savory innovations that expand addressable occasions.
- Traditional Mochi:Steamed and pounded japonica rice with 40-50% moisture content serves seasonal ceremonies and gift markets across Japan, South Korea, and diaspora communities. Demand concentrates in East Asian metropolitan areas where ritual consumption persists, constrained by 72-hour ambient shelf life without frozen stabilization.
- Ice Cream Mochi:Mochi dough encasing frozen dairy cores leverages flash-freezing infrastructure to achieve nationwide US distribution from California production bases. North American food service channels pull this format into high-margin restaurant dessert programs.
- Chocolate Mochi:Cocoa-infused rice flour formulations target European retail novelty shelves with reduced sweetness profiles.
- Savory Mochi:Soy, sesame, and vegetable-based variants expand snacking occasions beyond dessert occasions in South Korean convenience retail.
Traditional mochi handles the majority of throughput; ice cream mochi is expanding most quickly on share.
Distribution Channel:
Channel economics separate volume scale from margin capture, with food service commanding premium positioning.
- Food Service:Restaurants, cafes, and dessert bars in North America and Western Europe apply mochi in plated presentations and beverage toppings, extracting markup multiples unavailable in retail. Procurement concentrates through specialty distributors serving metropolitan culinary clusters.
- Supermarkets:Frozen dessert aisles in US and Japanese mass retail move ice cream mochi at velocity, though slotting fees and promotional depth compress producer margins.
- Online Retail:Direct-to-consumer frozen shipping requires insulated packaging investments that limit viable product density.
- Specialty Stores:Asian grocery channels in Los Angeles, Vancouver, and Sydney serve diaspora demand for fresh and frozen traditional formats.
Food service captures the highest margin per unit; online retail is climbing the fastest on channel development investment.
Ingredient Type:
Input specifications divide between heritage authenticity and allergen-addressing reformulations.
- Rice Flour:Short-grain japonica milled to specific particle size distributions determines elasticity and mouthfeel in traditional production. Japanese and California sourcing dominates premium applications, with Thai and Vietnamese origins facing EU arsenic threshold scrutiny.
- Gluten-Free Flour:Tapioca and potato starch blends enable celiac-safe positioning in North American and European retail, though texture divergence from rice-based standards limits ceremonial acceptance.
- Sweeteners:Cane sugar, maltose, and monk fruit extracts balance cost and clean-label positioning across price tiers.
- Natural Flavors:Matcha, red bean, and yuzu extracts differentiate premium lines in Japanese and export markets.
Rice flour anchors formulation integrity; gluten-free alternatives are gaining share fastest on dietary restriction demand.
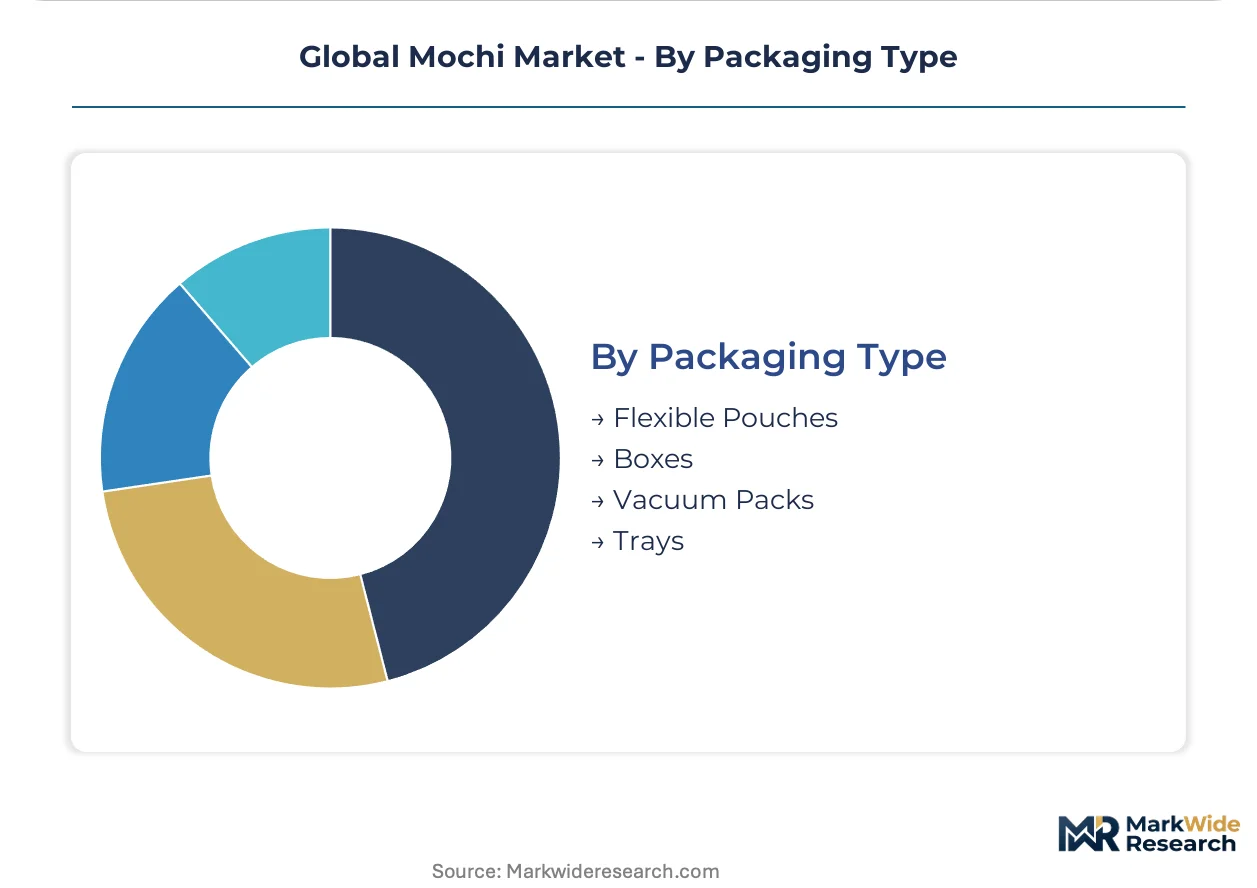
Packaging Type:
Barrier properties and presentation formats align with distribution distance and retail environment.
- Vacuum Packs:Oxygen exclusion extends refrigerated shelf life for fresh mochi in Japanese convenience channels, where Yamazaki Baking deploys bakery-distribution integration.
- Flexible Pouches:Multi-layer films with modified atmosphere capability support frozen mochi distribution across extended US supply chains without texture degradation.
- Boxes:Rigid presentation packaging serves gift markets and premium retail placements in Tokyo, Seoul, and Los Angeles.
- Trays:Thermoformed containers with lidding film enable food service portion control and grab-and-go retail formats.
Vacuum packs handle fresh product throughput; flexible pouches are expanding most quickly on frozen distribution scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese frozen mochi exports flow primarily into South Korean convenience retail and North American food service channels, with California-based production facilities increasingly serving US East Coast markets through flash-freezing infrastructure.
Japan
Domestic ceremonial demand and premium gift markets sustain traditional production in Tokyo and Osaka metropolitan clusters. METI enforces F-Gas Regulation compliance timelines that accelerate cold-chain refrigerant retrofits across frozen mochi logistics networks. Kanto region facilities concentrate process-controlled rice flour hydration systems that anchor mass-market shelf-stable output.
South Korea
24-hour convenience retail formats in Seoul drive frozen snack velocity through CJ and Lotte distribution networks. MFDS labeling requirements constrain additive use in rice-based formulations entering domestic channels. Busan-Ulsan corridor cold-storage capacity is expanding to handle rising import volumes from Japanese suppliers.
United States
Food service channels in Los Angeles and New York extract premium markups for plated mochi desserts and beverage applications. FDA frozen dessert standards provide compliance pathways that disadvantage unregulated artisanal competitors. California production bases leverage flash-freezing to achieve East Coast distribution parity with local Japanese output.
Germany
Minimal frozen mochi shelf presence in Berlin and Munich retail relative to ice cream novelty penetration rates signals underexploited demand. EU F-Gas Regulation phase-down schedules force refrigerant transitions in cross-border logistics earlier than baseline EU timelines. Bavaria-based cold-chain operators face steepest retrofit capital intensity for compliant transport assets.
France
Chocolate mochi formulations target Parisian retail novelty shelves with reduced sweetness profiles adapted to local preferences. EFSA arsenic content thresholds constrain rice sourcing from specific growing regions, limiting approved supplier pools. Île-de-France distribution clusters show accelerating placement trials in premium supermarket frozen aisles.
Global Mochi Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Japanese and South Korean conglomerates leverage integrated distribution networks to secure frozen placement in convenience retail, while California-based specialists anchor North American premium segments through localized production. Three archetypes dominate: bakery-distribution integrators, ice cream-mochi specialists, and mass-market shelf-stable producers. Competitive moves concentrate on cold-chain capacity expansion and exclusive formulation development for retail network partners.
Within the bakery-distribution integrator tier, Yamazaki Baking exemplifies vertical coordination between production and convenience channel placement. Mikawaya and Morinaga & Company occupy distinct positioning vectors—Mikawaya as the North American premium specialist anchored in California production, Morinaga as the mass-market shelf-stable leader with process-controlled hydration scale. These three entities represent the structural poles around which smaller regional fabricants and private-label suppliers organize competitive responses.
| Leading Market Players |
|---|
| Yamazaki Baking |
| Mikawaya |
| Morinaga & Company |
| Maeda-en |
| Daifuku |
| Lotte Confectionery |
| Royal Family Food |
| Fugetsu-Do |
| Nissin Foods Holdings |
| Others |
Value Chain & Pricing Dynamics
Thai and Vietnamese japonica rice cultivation clusters feed directly into margin compression dynamics for mass-market producers, where input volatility transfers downstream into pricing power asymmetries between commodity-grade and premium-positioned tiers.
Pricing Analysis
Fresh-production technology commands sustained premiums against flash-frozen alternatives, while next-generation modified-atmosphere systems are resetting cost baselines for national distribution reach. Three-tier pricing structure across artisanal ceremonial, premium frozen novelty, and mass-market shelf-stable levels segments buyers by occasion specificity and texture fidelity requirements. Cost compression in mass-market channels is intensifying because Thai and Vietnamese climate volatility feeds raw material unpredictability. Food service procurement shows lowest price sensitivity due to markup extraction capability, while supermarket slotting-fee structures render mass-market producers most exposed to margin erosion.
Supply Chain Analysis
Tariff exposure between Japanese production bases and South Korean import channels dominates supply chain risk calculus for regional frozen mochi flows. Manufacturing concentrates in Japan, California, and South Korea, with Thai and Vietnamese rice milling feeding upstream flour supply. Process-controlled hydration equipment and flash-freezing infrastructure draw from Japanese and South Korean fabrication sources. Single-source vulnerability in specialized rice flour particle-size distribution creates chokepoints for premium texture replication. Distribution runs through CJ and Lotte-controlled cold-chain networks in Seoul's 24-hour retail corridor, with Yamazaki Baking's bakery-distribution integration anchoring Japanese convenience channel placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story where F-Gas compliance timelines and USDA dairy-grain dual classification create certification moats that disadvantage unqualified entrants.
For Market Incumbents: Entrench position through backward integration into California rice flour milling and exclusive formulation development for CJ and Lotte network placement. Flash-freezing capacity expansion in Busan-Ulsan corridor cold-storage nodes captures South Korean import flow growth. Threat of private-label displacement by retailer-controlled networks demands preemptive slotting fee commitments and proprietary texture technology patent filing. For New Entrants and Emerging Players: German and French retail freezer aisles present the most penetrable white-space opportunity given minimal frozen mochi shelf presence relative to ice cream novelty saturation. Secondary target sits in North American food service dessert program supply, where FDA frozen dessert standards provide compliance differentiation against artisanal competitors. Go-to-market angle centers on certified-organic rice sourcing that clears EU EFSA arsenic thresholds for Paris and Berlin premium supermarket trials. For Investors and Strategic Acquirers: Secondary-cycle assets sit with California-based ice cream mochi specialists holding FDA-compliant production infrastructure and East Coast distribution reach. Long-term viability frames around flash-freezing technology depreciation cycles and regulatory compliance amortization across the analysis window. Acquisition target archetype: mid-cap producers with USDA dual-classification approval and existing Yamazaki-style bakery-channel relationships. Signal to watch is CJ and Lotte exclusive formulation contract announcements as concentration inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Flash-Freezing Capacity Expansion | California-based facilities achieve East Coast texture parity with Japanese production through infrastructure investment. |
| F-Gas Compliance Retrofit | EU refrigerant phase-down schedules force capital allocation toward lower-global-warming-potential transport assets. |
| Exclusive Formulation Development | CJ and Lotte network placement demands displace open-market specifications in Seoul's 24-hour retail corridor. |
| Backward Integration into Rice Milling | Captive japonica flour supply insulates margin predictability from Thai and Vietnamese climate volatility. |
| USDA Dual-Classification Investment | Frozen dessert standards compliance creates 8-14 month approval barriers against unregulated artisanal competitors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA frozen dessert filings, USDA dairy-grain classification records, EU EFSA rice product guidance, and Japanese METI F-Gas compliance timelines. Conversations with frozen dessert category managers, cold-chain logistics operators, rice flour procurement leads, and convenience retail buyers informed demand-side validation. Customs data on japonica rice trade flows and refrigerated transport asset registrations anchored supply-side triangulation. Bottom-up facility capacity assessments and top-down retail velocity estimates were cross-referenced for convergence.
Forecast inputs include flash-freezing technology adoption curves, F-Gas retrofit capital deployment schedules, and CJ-Lotte network expansion trajectories across the analysis window. Segmentation dimensions span product type, distribution channel, ingredient specification, and packaging format, with geographic regulatory cluster as an additional modeled layer. CAGRs derive from fitted growth curves against historical velocity data, adjusted for cold-chain infrastructure buildout assumptions and ceremonial demand seasonality patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed California production specialists or accelerated CJ-Lotte vertical integration would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Sugar Free Lollipops Market
Confectionery
Milk Chocolate Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Sugar Free Candy Market
Confectionery
Brain Mint Market
Confectionery
Jellies and Gummies Market
Confectionery
Sugar-Free Gummy Market
Confectionery
Low-Calorie Jelly Market
Confectionery
South America Compound Chocolate Market
Confectionery
Ruby Chocolate Market
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
White Chocolate Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
United States Chocolate Market