
 Low-Fat Dark Chocolate Market | 2026-2036
Low-Fat Dark Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Dark Chocolate Market Analytics
Multi-source cocoa procurement is shifting toward vertically integrated supply chains among premium confectioners. The Hershey Company leverages its North American bean-to-bar infrastructure to secure consistent alkalized cocoa supply. Lindt & Sprüngli anchors its European position through proprietary conching protocols that preserve polyphenol content during fat reduction. Mars Incorporated competes on manufacturing scale, operating multiple tempering lines dedicated to reduced-fat formulations.
Low-fat dark chocolate denotes cocoa mass containing elevated flavanol levels with fat content reduced below standard dark chocolate thresholds through mechanical pressing or alternative lipid substitution. Manufacturers employ cold-pressing techniques to retain antioxidant capacity while achieving sub-25% fat composition suitable for health-positioned retail placement. Bars dominate volume throughput in mainstream retail channels where single-serve formats command premium positioning against standard confectionery. Online retail represents the fastest-growing distribution vector as direct-to-consumer subscription models bypass traditional wholesale markups for specialty reduced-fat variants.
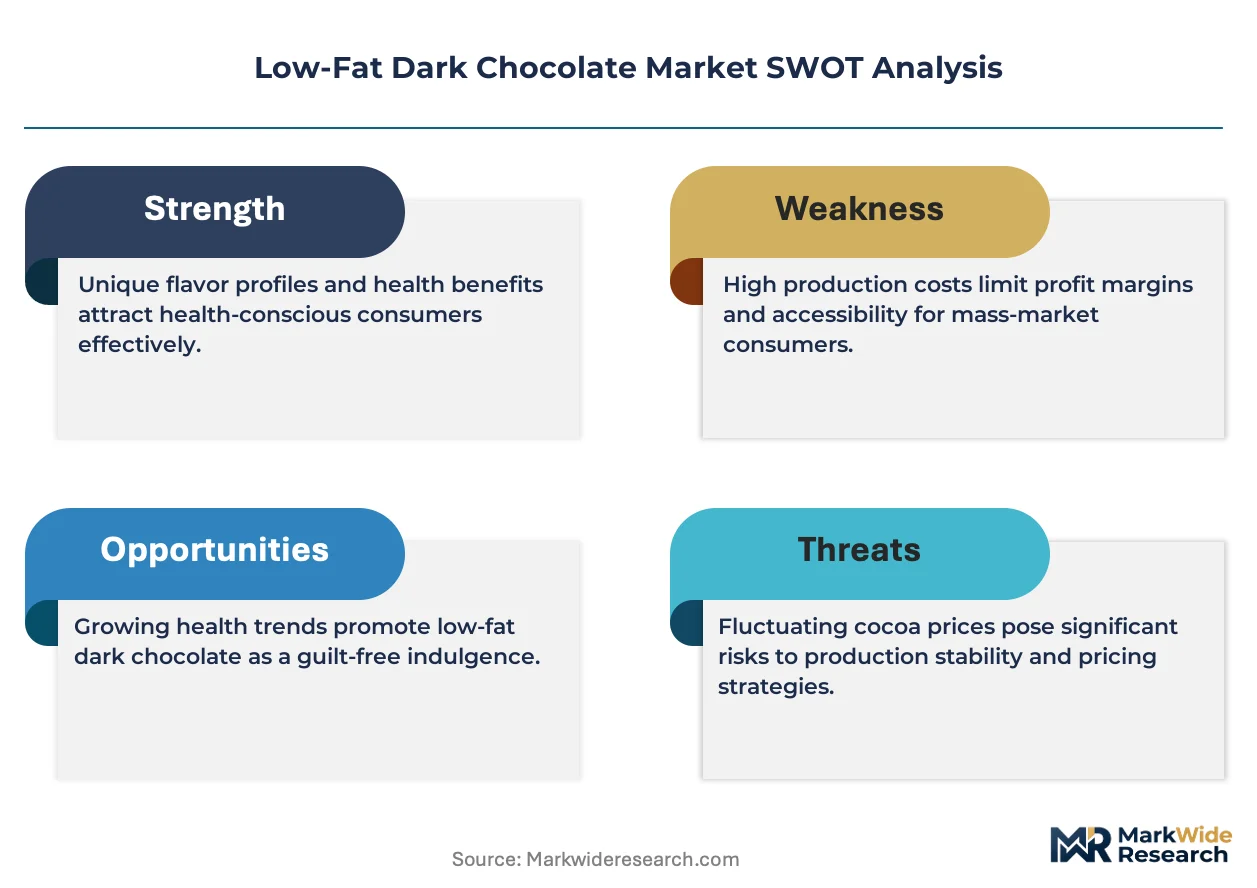
FDA nutrition labeling mandates and EFSA health claim frameworks collectively shape permissible marketing language around cocoa polyphenol benefits. The FDA's added sugars disclosure requirements are forcing reformulation transparency while EFSA's pending flavanol approval process determines whether European producers can deploy cardiovascular benefit claims. Stakeholders must monitor evolving cocoa sustainability regulations in origin countries alongside shifting retail certification standards for reduced-fat positioning.
Market Dynamics
Mechanical pressing technology is compressing production economics for reduced-fat cocoa formulations, forcing manufacturers to reconfigure alkalization protocols or risk margin erosion from polyphenol degradation.
Growth Catalysts
- FDA Added Sugars Disclosure:Mandates for transparent nutrition labeling are compelling confectioners to reformulate toward cleaner ingredient decks that highlight cocoa mass concentration.
- Functional Confectionery Retail:German supermarket chains have elevated reduced-fat dark chocolate to standard shelf placement, normalizing health-positioned snacking.
- Cold-Press Extraction:This mechanical process retains antioxidant capacity during fat reduction, enabling manufacturers to preserve cardiovascular benefit claims through EFSA review windows.
Market Restraints
- Cocoa Butter Price Volatility:West African supply concentration exposes manufacturers to weather-driven input cost spikes that compress already-thin reduced-fat margins.
- Polyphenol Retention Ceiling:Current pressing technologies hit structural limits around 25% fat floors before flavanol degradation accelerates.
- EFSA Claim Uncertainty:Pending cardiovascular health claim approvals create marketing language constraints that handicap European positioning against US competitors.
Strategic Opportunities
- Direct-to-Consumer Subscription:Online retail bypasses wholesale markups for specialty variants, capturing margin normally lost to distributor networks.
- India Urban Premium:Metropolises like Mumbai and Delhi show nascent demand for functional chocolate as FSSAI clean-label awareness campaigns penetrate affluent demographics.
- Bean-to-Bar Integration:Captive cocoa supply chains enable traceability certifications that command shelf placement premiums in sustainability-conscious retail.
Industry Challenges
- Conching Specialist Scarcity:Fat-reduction protocols require operators trained in extended refining cycles without standard lipid lubrication, creating hiring bottlenecks.
- Tempering Line Reconfiguration:Legacy equipment designed for 35-40% fat formulations demands capital-intensive retrofitting to handle sub-25% viscosities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Dark Chocolate Market |
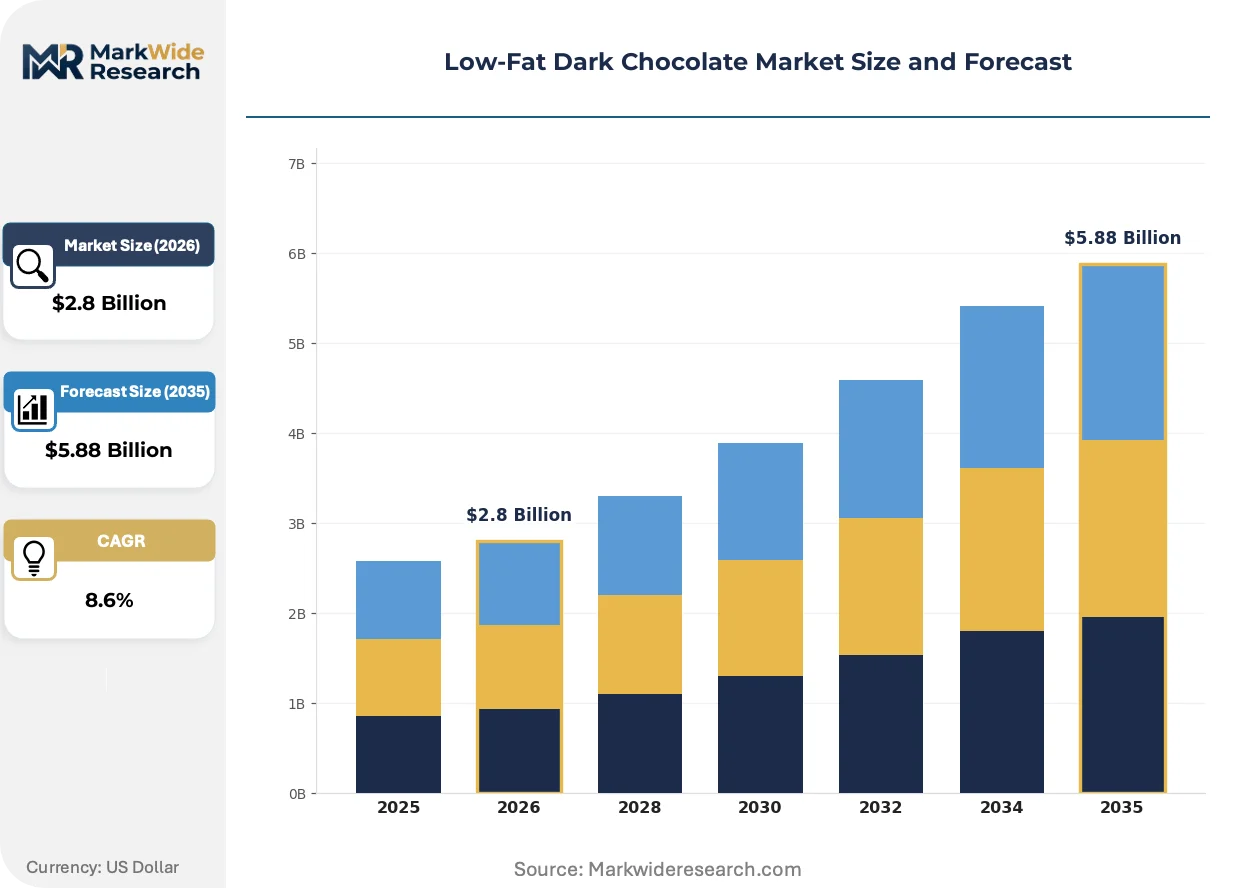
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Chips, Coated, Powder End User: Health Conscious Consumers, Bakers, Retailers, Food Manufacturers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Packaging Type: Bags, Boxes, Pouches, Bulk |
| Companies Covered | Godiva Chocolatier, The Margaret River Chocolate Company, The Hershey Company, Sweet-Switch, Lindt & Sprüngli, Lily's, Nestlé, Ghirardelli Chocolate, Mars Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Dark Chocolate Market Evolving Landscape
Clean-label pressure and supply chain traceability demands are converging to reshape how reduced-fat dark chocolate reaches health-conscious consumers.
Cold-pressing equipment is modularizing production layouts for mid-size confectioners. Premium bean-to-bar operators in Switzerland and Belgium are adopting skid-mounted pressing units that slot between roasting and conching stages. This technology is modularizing capital deployment, allowing producers to scale fat-reduction capacity without full facility reconfiguration.
EFSA's pending flavanol health claim framework is compressing European marketing timelines. Manufacturers await cardiovascular benefit approvals that would unlock explicit polyphenol positioning against standard confectionery. German and Swiss producers are most exposed, having already invested in clinical substantiation dossiers now stalled in regulatory review.
Subscription-based replenishment is displacing impulse purchasing in specialty reduced-fat segments. Direct-to-consumer platforms bypass traditional confectionery distributors, capturing data on consumption patterns that inform flavor development. This channel rotation is most visible in US metropolitan markets where health-positioned snacking has achieved habitual purchase behavior.
Low-Fat Dark Chocolate Market Segmentation
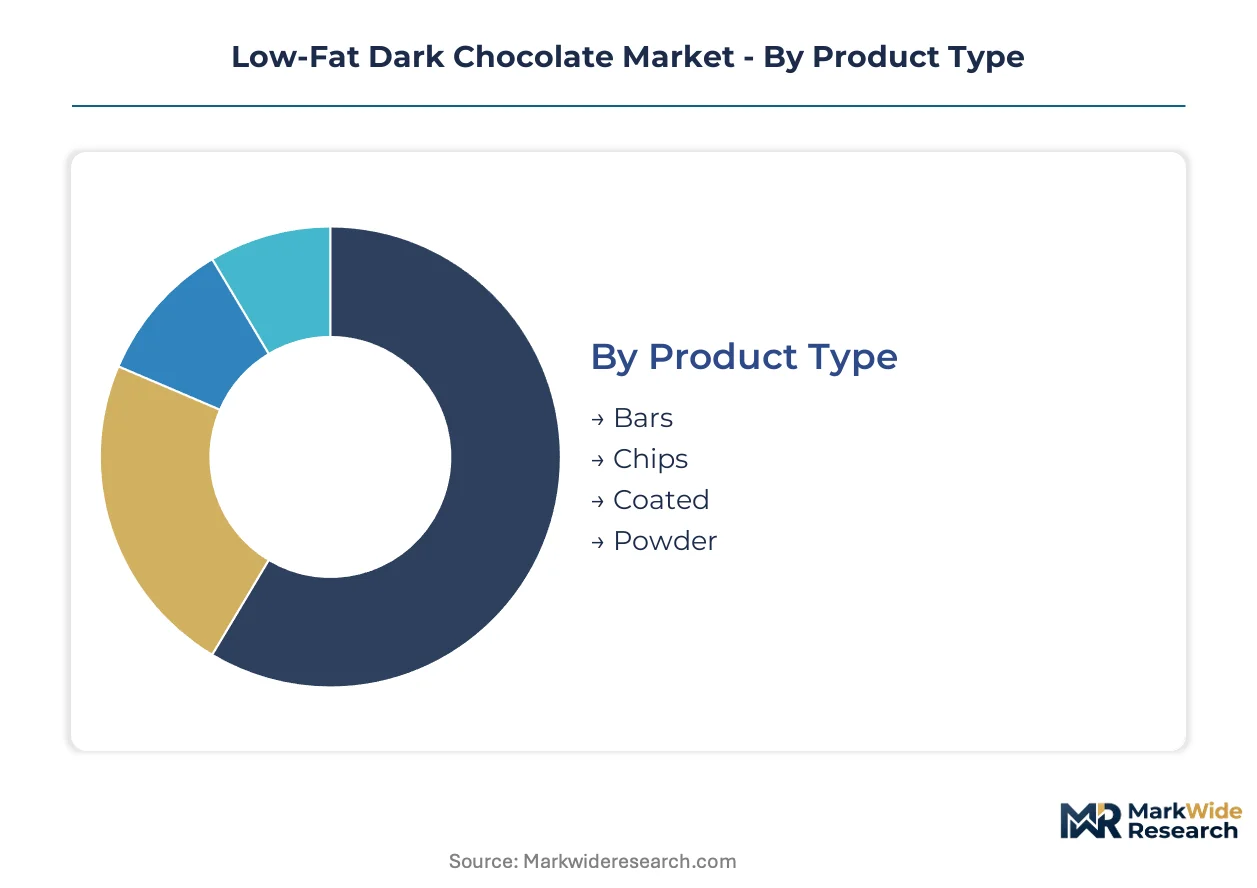
Segmentation in low-fat dark chocolate reveals how capital deployment, regulatory exposure, and channel economics fragment opportunity across distinct production and distribution configurations. Understanding these divisions exposes where margin concentrates and where volume expansion strains existing infrastructure.
Product Type:
Capital intensity varies sharply across formats, with pressing equipment requirements and tempering line configurations driving divergent upfront investment thresholds.
- Bars:Standard molded formats require dedicated tempering lines calibrated for sub-25% fat viscosities. German supermarket chains anchor volume demand as functional confectionery achieves mainstream retail placement alongside standard chocolate.
- Chips:Small-format baking inclusions demand precision depositing equipment with modified cooling tunnels to prevent fat bloom in reduced-lipid formulations. Bakers in US metropolitan markets drive procurement as clean-label ingredient substitution accelerates in commercial kitchens.
- Coated:Enrobed applications for nuts and dried fruits require specialized panning equipment with extended cycle times to compensate for reduced cocoa butter lubrication.
- Powder:Cocoa mass pressing yields defatted powder as co-product, with beverage and supplement manufacturers absorbing output for functional drink formulations.
Bars absorb the bulk of installed capacity; chips are expanding most quickly as commercial bakery reformulation accelerates.
End User:
Customer sophistication around polyphenol retention and clean-label certification determines pricing power and formulation complexity across user categories.
- Health Conscious Consumers:Direct purchasers prioritize EFSA-aligned cardiovascular benefit claims and single-origin traceability. Subscription models in US coastal cities capture recurring revenue from habituated functional snacking behavior.
- Bakers:Commercial and artisanal baking operations source reduced-fat chips and powders for clean-label dessert formulations. Professional kitchens in Mumbai and Delhi represent emerging demand clusters as FSSAI awareness campaigns penetrate affluent Indian demographics.
- Retailers:Supermarket and specialty store buyers negotiate shelf placement fees and promotional calendars, concentrating procurement power among German and Swiss retail cooperatives.
- Food Manufacturers:Industrial buyers integrate low-fat cocoa mass into RTE desserts and nutritional bars, demanding bulk packaging and consistent alkalization specifications.
Health conscious consumers command premium realization; food manufacturers drive volume scale through contract manufacturing arrangements.
Distribution Channel:
Channel selection determines margin capture versus customer data access, with wholesale markups and direct relationship economics creating divergent strategic imperatives.
- Supermarkets:Standard retail placement in Germany and Switzerland normalizes reduced-fat positioning alongside conventional confectionery. Slotting fees and promotional calendars compress margins for emerging brands.
- Online Retail:Direct-to-consumer platforms bypass distributor networks, capturing consumption pattern data that informs flavor development. Subscription replenishment models dominate in US metropolitan markets with habitual health-positioned purchasing.
- Specialty Stores:Bean-to-bar retailers and organic grocers command traceability premiums through captive supply chain certifications.
- Convenience Stores:Impulse-oriented single-serve formats face placement constraints as reduced-fat variants compete for limited shelf space against standard chocolate.
Supermarkets retain volume concentration; online retail climbs the fastest as subscription mechanics displace traditional wholesale dependency.
Packaging Type:
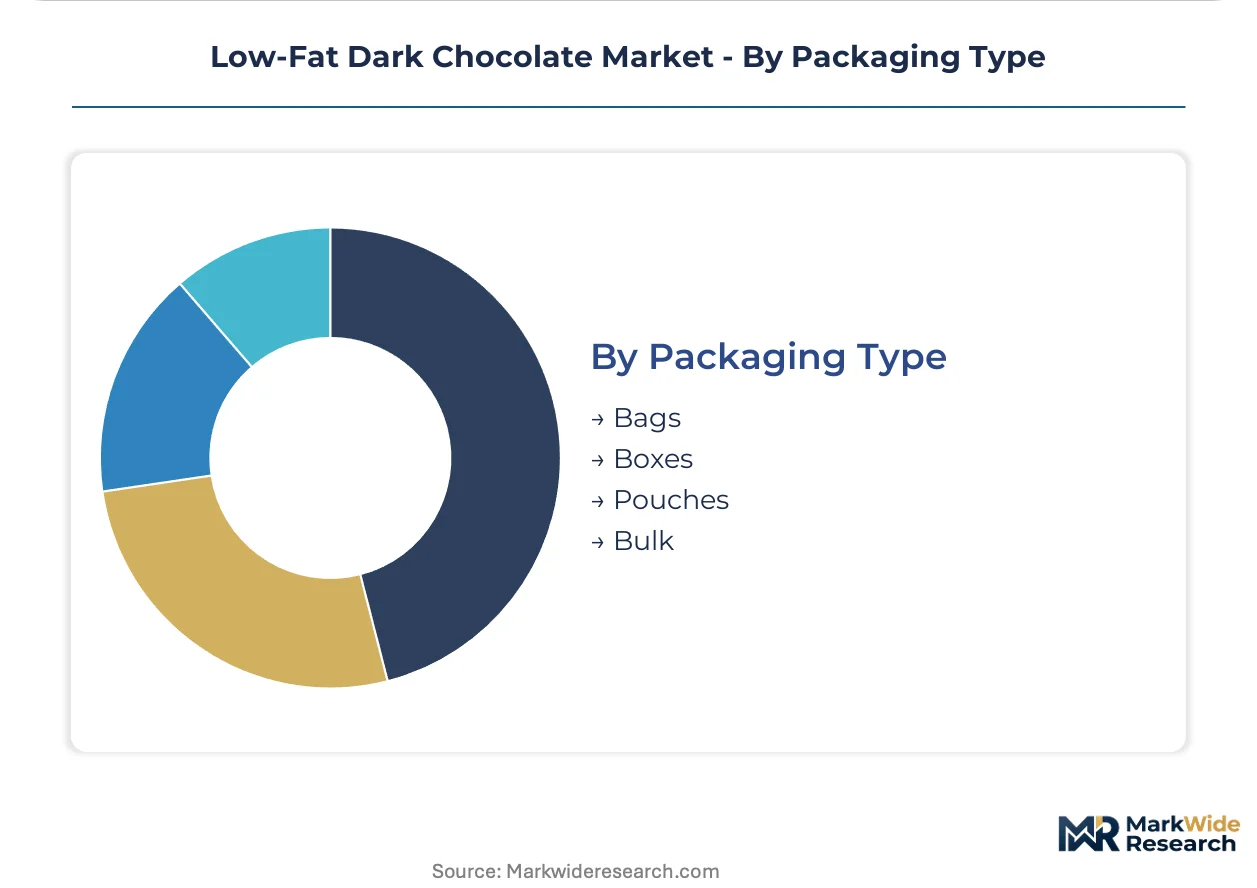
Packaging configuration aligns with customer scale and shelf-life requirements, from individual portion control to industrial bulk handling systems.
- Bags:Flexible retail packaging dominates supermarket and specialty store placement, with resealable formats supporting premium positioning for health-conscious snacking occasions.
- Boxes:Gift-oriented and subscription formats command shelf placement premiums through structural differentiation and premium unboxing experience.
- Pouches:Stand-up flexible formats serve single-serve and small-household segments with reduced material cost versus rigid alternatives.
- Bulk:Industrial totes and super-sacks supply food manufacturers and commercial bakers, minimizing per-unit packaging cost at volume scale.
Bulk packaging serves industrial concentration; bags gain share fastest as retail format diversification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional confectionery demand concentrates in Germany where supermarket chains have normalized reduced-fat dark chocolate placement alongside standard sweets. Health-positioned snacking achieves habitual purchase behavior in US coastal metropolitan markets. Clean-label awareness campaigns in Indian urban centers are catalyzing nascent premium demand.
Germany
Retail cooperatives anchor European volume through mainstream shelf placement of functional chocolate. EFSA's pending flavanol health claim framework determines whether cardiovascular benefit marketing receives regulatory clearance. Cologne and Hamburg host specialist confectionery clusters where cold-pressing equipment manufacturers serve mid-size bean-to-bar operators.
United States
Subscription-based replenishment models capture recurring revenue from habituated health-conscious consumers in metropolitan markets. FDA added sugars disclosure mandates compel reformulation transparency that elevates cocoa mass concentration labeling. Brooklyn and San Francisco anchor craft chocolate innovation clusters where direct-to-consumer platforms bypass traditional wholesale markups.
Switzerland
Proprietary conching protocols preserve polyphenol content during mechanical fat reduction, securing premium positioning. Swissmedic oversight of functional food claims intersects with EFSA review timelines for cardiovascular benefit approvals. Zurich and Vevey concentrate bean-to-bar infrastructure where vertically integrated supply chains enable traceability certifications.
India
FSSAI clean-label awareness campaigns penetrate affluent demographics in Mumbai and Delhi, generating demand for functional confectionery. Import tariff structures on alkalized cocoa mass influence landed cost economics for premium formulations. Maharashtra's food processing corridors attract contract manufacturing investment targeting domestic premium retail expansion.
Belgium
Traditional praline manufacturers diversify into reduced-fat dark chocolate bars as health positioning displaces pure indulgence marketing. REACH compliance requirements for food contact materials shape packaging specification standards. Brussels and Antwerp host equipment innovation clusters where modular cold-pressing units slot between roasting and conching stages.
Low-Fat Dark Chocolate Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit legacy tempering lines for sub-25% fat viscosities. The vendor base stratifies across three tiers: multinational confectioners with captive cocoa supply chains, mid-size European specialists with proprietary processing protocols, and emerging direct-to-consumer brands leveraging subscription mechanics. Two competitive moves define current positioning: backward integration into bean-to-bar infrastructure to secure traceability premiums, and geographic expansion into Indian urban premium segments as FSSAI awareness campaigns mature.
Within the multinational tier, The Hershey Company and Mars Incorporated occupy positions defined by manufacturing scale and North American distribution density. Lindt & Sprüngli exemplifies the European specialist archetype through Swiss and German market anchoring. Among emerging health-positioned challengers, Lily's represents the direct-to-consumer vector where sugar-alternative formulations intersect with reduced-fat positioning. Nestlé and Godiva Chocolatier span multiple archetypes through portfolio diversification across premium gifting and functional snacking occasions.
| Leading Market Players |
|---|
| Godiva Chocolatier |
| The Margaret River Chocolate Company |
| The Hershey Company |
| Sweet-Switch |
| Lindt & Sprüngli |
| Lily's |
| Nestlé |
| Ghirardelli Chocolate |
| Mars Incorporated |
| Others |
Value Network & Pricing Analysis
FDA added sugars disclosure mandates are compelling confectioners to reformulate toward cleaner ingredient decks that elevate cocoa mass concentration, forcing supply chains to source higher-grade alkalized cocoa and compressing margins for producers unable to secure premium bean-to-bar infrastructure.
Pricing Analysis
Volume throughput concentrates in supermarket channels where slotting fees compress emerging brand margins, while direct-to-consumer subscription models capture premium realization through bypassed wholesale markups. Three-tier pricing structure across premium, standard, and economy levels separates bean-to-bar traceability-certified variants from mass-market formulations and private-label alternatives. Price differentiation hinges on polyphenol retention certification and single-origin provenance documentation. Pricing pressure stems from cocoa butter price volatility as West African supply concentration exposes manufacturers to weather-driven input cost spikes.
Supply Chain Analysis
Certification gating through FDA nutrition labeling and EFSA health claim frameworks determines which manufacturers can deploy cardiovascular benefit marketing, creating compliance moats that favor established players with regulatory affairs infrastructure. Cocoa bean supply concentrates in Ivory Coast, Ghana, and Ecuador, with mid-size European confectioners drawing from vertically integrated origin partnerships to secure traceability premiums. Raw material dependencies span alkalized cocoa mass, cold-pressing equipment modules, and modified tempering line components. Single-source vulnerability in West African bean supply creates structural risk exposure to climate-driven harvest variability. Distribution runs through German supermarket cooperatives, US direct-to-consumer platforms, and Swiss specialty retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's pending flavanol health claim framework operates as a cost-of-compliance barrier, advantaging manufacturers with completed clinical substantiation dossiers against undercapitalized challengers awaiting regulatory clearance.
For Market Incumbents: Cement market position by retrofitting legacy tempering lines for sub-25% fat viscosities before equipment specialist scarcity intensifies hiring bottlenecks. Extend proprietary conching protocols into modular cold-pressing partnerships with mid-size bean-to-bar operators, converting process knowledge into licensing revenue streams. For New Entrants and Emerging Players: Begin with direct-to-consumer subscription mechanics in US metropolitan markets where habitual health-positioned purchasing behavior supports recurring revenue capture without slotting fee burdens. Target Indian urban premium segments in Mumbai and Delhi as FSSAI clean-label awareness campaigns mature, leveraging lower competitive density versus saturated European functional confectionery retail. For Investors and Strategic Acquirers: Re-rating potential sits with mid-size European specialists possessing EFSA-aligned cardiovascular claim dossiers given pending regulatory clearance catalysts. Long-term viability favors vertically integrated bean-to-bar operators with captive cocoa supply chains securing traceability premiums. The signal to watch is EFSA flavanol approval timing, which would unlock explicit polyphenol positioning and expand addressable market for substantiated health claims.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bean-to-Bar Infrastructure | Captive cocoa supply chains enable FDA-compliant traceability certifications that command shelf placement premiums. |
| Cold-Pressing Equipment Modularization | Skid-mounted pressing units allow mid-size confectioners to scale fat-reduction capacity without full facility reconfiguration. |
| Direct-to-Consumer Subscription Launch | Bypassing wholesale markups captures consumption pattern data that informs flavor development for health-conscious demographics. |
| EFSA Health Claim Dossier Investment | Clinical substantiation for cardiovascular benefits unlocks explicit polyphenol marketing against standard confectionery competitors. |
| Indian Urban Premium Expansion | FSSAI clean-label awareness campaigns in Mumbai and Delhi generate nascent demand for functional chocolate positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with confectionery R&D directors, supermarket category buyers, cold-pressing equipment manufacturers, and cocoa procurement specialists. Secondary sources encompassed FDA nutrition labeling guidance documents, EFSA health claim submission databases, FSSAI clean-label campaign materials, and bean-to-bar certification registry records. Bottom-up volume modeling across product formats triangulated against top-down category expenditure estimates.
Granularity-level modeling deployed separate analytical frameworks for bars, chips, coated applications, and powder co-products, with cross-segment calibration against end-user demand from health-conscious consumers, commercial bakers, and food manufacturers. CAGRs derived from regression analysis of historical volume trends, adjusted for regulatory inflection points and channel shift mechanics. Industry-specific forecast inputs included cocoa butter price volatility indices and EFSA approval timeline scenarios.
Underlying measurement precision varies by segment; bars and online retail channels carry tighter precision than emerging coated applications and convenience store distribution. Forecasts reflect assumptions regarding EFSA regulatory timelines, West African harvest stability, and cold-pressing technology adoption curves. A model refresh is warranted upon material change in EFSA flavanol health claim approval status or cocoa sustainability regulation enforcement in origin countries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Diet Candy Market
Confectionery
Milk Chocolate Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Europe Confectionery Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
Global Chocolate Market
Confectionery
Carob Chocolate Market
Confectionery
White Chocolate Market
Confectionery
Sugar Free Lollipops Market
Confectionery
India Industrial Chocolate Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
US Confectionery Market
Confectionery
Vegan Candies Market
Confectionery
Global Compound Chocolate Market
Confectionery
Fat Free Candy Market