
 China Chocolate Market | 2026-2036
China Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
China Chocolate Market Analysis
Young urban professionals is unwinding the historical dominance of family bulk purchasers as the core buyer archetype in China's chocolate trade. Mars Incorporated leverages its Snickers and Dove portfolios to sustain manufacturing scale across multiple provincial production hubs. Ferrero International SA anchors its premium positioning through the Rocher gift-box format, which dominates festival-season purchasing. Nestlé SA competes aggressively in the mid-range tier with localized flavor adaptations that navigate shifting provincial taste preferences.
Chocolate comprises a confectionery matrix of cocoa solids, cocoa butter, sugar, and emulsifiers, typically processed through conching and tempering to achieve defined viscosity and snap characteristics, serving both direct consumption and foodservice ingredient applications. Dark chocolate commands margin concentration among health-positioned offerings, while milk chocolate occupies volume leadership through mainstream retail penetration. Online retail channels are capturing the fastest growth trajectory, though supermarkets sustain the largest absolute transaction base across lower-tier cities.
China's national food safety regulator enforces GB standards for cocoa content labeling and additive limits, while the State Administration for Market Regulation monitors anti-competitive pricing in concentrated retail channels. These frameworks elevate compliance costs for imported brands while creating regulatory familiarity advantages for domestic producers. Stakeholders must monitor whether sugar-reduction mandates accelerate faster than formulation technology can deliver acceptable taste profiles.
Market Dynamics
China's National Health Commission sugar-reduction guidelines are forcing rapid reformulation across the entire chocolate category, compressing product development cycles while premium gifting formats absorb margin pressure from compliance investments.
Growth Catalysts
- Urban Millennial Gifting Norms:Specialty chocolate boutiques in Shanghai and Beijing cultivate ritualized premium purchases for festivals and relationship maintenance, displacing traditional bulk-buying patterns among older demographics.
- GB Standards Evolution:Clearer cocoa content labeling requirements under national food safety frameworks reduce information asymmetry, accelerating consumer education and willingness to pay for verified quality tiers.
- Café Culture Diffusion:Beverage-led consumption occasions in Guangzhou and tier-2 provincial capitals expand chocolate's addressable moments beyond conventional confectionery snacking.
Market Restraints
- Cocoa Butter Input Volatility:West African supply concentration exposes Chinese processors to weather-driven price swings that compress formulation flexibility for mid-tier products.
- Import Tariff Cascades:Cross-border e-commerce duty thresholds and evolving customs classifications create landed cost uncertainty for European premium brands.
- Functional Substitutes:Protein bars and nut-based energy snacks capture overlapping consumption occasions among health-conscious urban professionals in fitness-oriented segments.
Strategic Opportunities
- Lower-Tier City Penetration:Supermarket infrastructure expansion in provincial capitals like Chengdu and Wuhan creates first-mover positioning before specialty retail saturation.
- Sugar-Reduced Formulation Innovation:Allulose and monk fruit extract applications aligned with SAMR labeling guidance open premium positioning for compliant domestic producers.
- Corporate Gifting Channels:B2B procurement platforms serving state-owned enterprises and technology firms represent underdeveloped volume for festival-season premium formats.
Industry Challenges
- Confectionery Technologist Scarcity:Experienced formulators capable of balancing mouthfeel and sugar reduction are concentrated in coastal manufacturing hubs, constraining inland production scaling.
- Cold Chain Reconfiguration:Temperate-controlled distribution for cocoa butter stability demands capex-intensive warehouse upgrades across tier-3 and tier-4 city networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Chocolate Market |
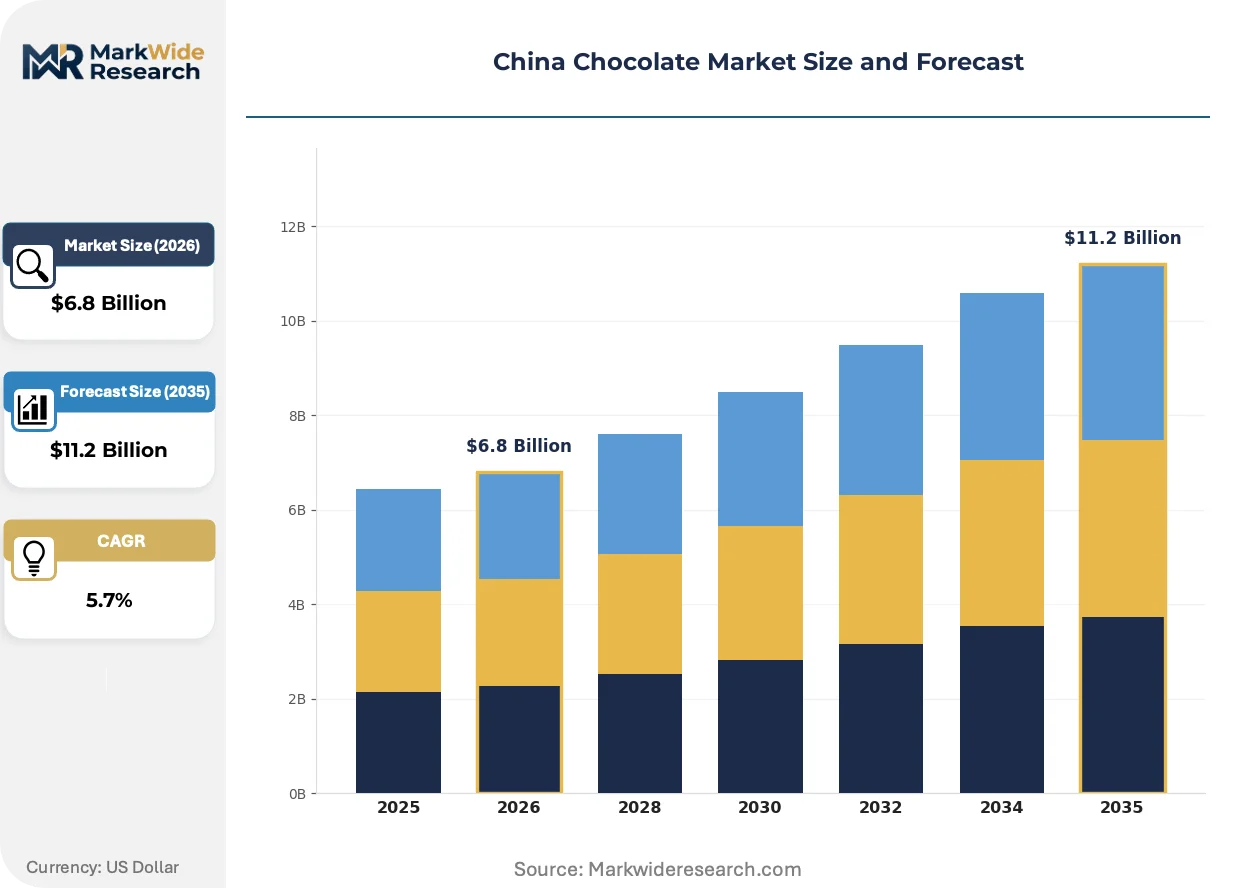
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End User: Retail Consumers, Bakeries, Cafés, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores Price Tier: Premium, Mid-Range, Economy, Value |
| Companies Covered | Ferrero International SA, Meiji Holdings Company Ltd, Nestlé SA, Want Want China Holding Ltd., Chocoladefabriken Lindt & Sprüngli AG, Mars Incorporated, The Hershey Company, Cargill Incorporated, Mondelēz International Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Chocolate Market Emerging Trajectories
Reformulation chemistry and channel architecture are the dominant axes of competitive differentiation, with regulatory pressure on sugar content intersecting with digital commerce infrastructure to reshape how chocolate reaches Chinese consumers.
Bean-to-bar traceability systems are supplanting conventional commodity sourcing for premium positioning. Artisanal producers in Yunnan and Hainan deploy blockchain-verified origin documentation to justify price premiums. Urban millennials in Shanghai and Beijing respond with measurable willingness-to-pay elevation for single-origin credentials.
SAMR's evolving enforcement posture on cross-border e-commerce food imports tightens documentation requirements for overseas brands. Domestic producers gain regulatory familiarity advantages in inspection timelines. Mid-range imported labels face extended customs clearance cycles that compress shelf-life windows.
Gifting behavior concentrates increasingly around designated e-commerce festivals rather than traditional lunar calendar occasions. Specialty chocolate brands redirect marketing spend toward live-streaming commerce platforms. Tier-1 city consumers demonstrate compressed decision cycles when influencer-endorsed limited editions drop during 618 and Double Eleven events.
China Chocolate Market Segmentation
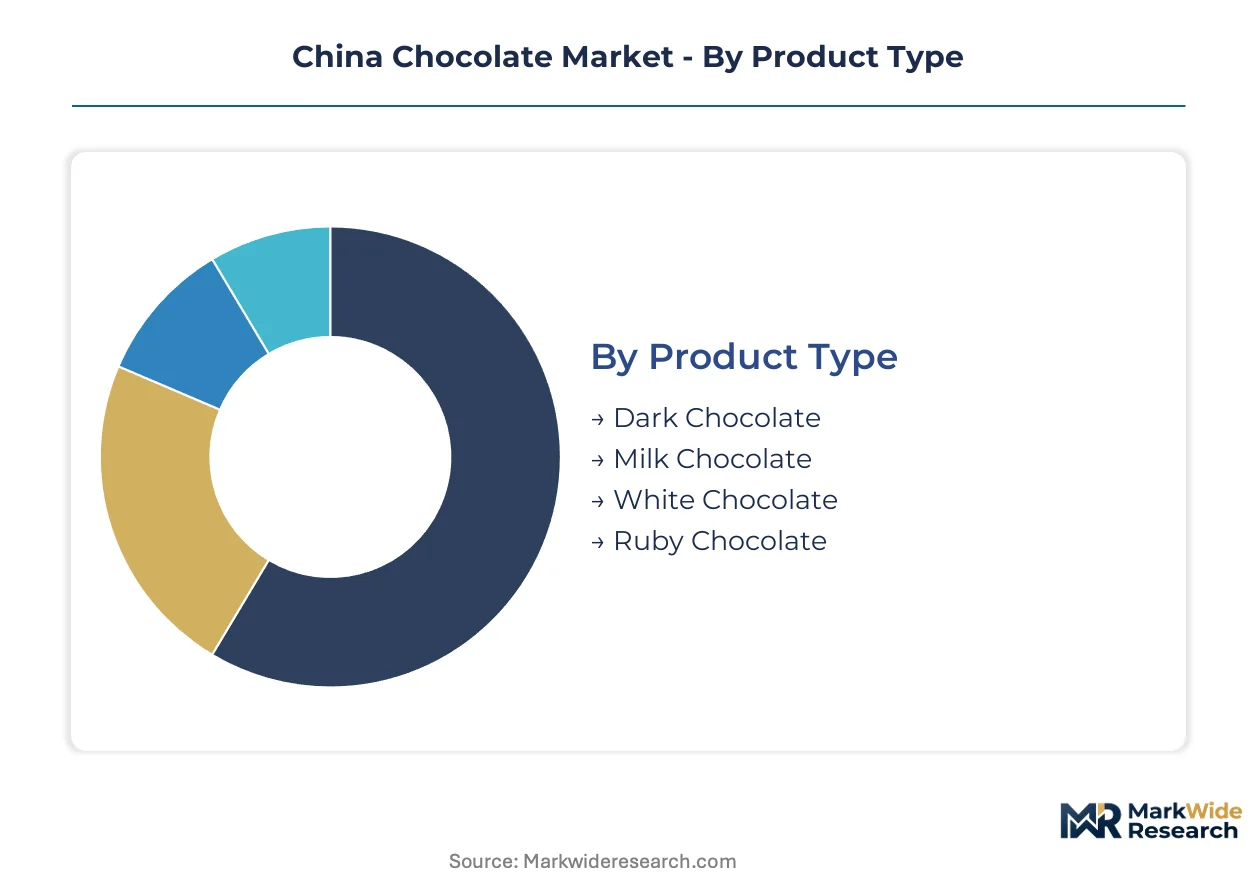
China's chocolate market stratifies across four intersecting dimensions that determine pricing power, channel access, and reformulation urgency. Each segmentation axis carries distinct regulatory exposure and margin architecture.
Product Type:
Channel-mix varies sharply by cocoa intensity, with dark variants commanding specialty retail premiums and milk chocolate sustaining supermarket volume throughput.
- Dark Chocolate:Cocoa solids exceed 50% by mass, delivering polyphenol positioning for health-conscious urban millennials. Concentrated demand in Shanghai and Beijing specialty boutiques, where single-origin credentials justify price elevation amid National Health Commission sugar-reduction pressure.
- Milk Chocolate:Combines cocoa liquor with condensed milk powder and elevated sugar content for mainstream palatability. Volume leadership through supermarket penetration in lower-tier cities, though reformulation timelines compress as GB standards tighten additive disclosure.
- White Chocolate:Cocoa butter base without cocoa solids, regulated under separate GB labeling thresholds for dairy content declaration.
- Ruby Chocolate:Ruby cocoa bean-derived pink hue, limited commercial presence pending SAMR novel food ingredient classification clarity.
Milk chocolate dominates installed base. Dark chocolate is where expansion concentrates.
End User:
Application context determines packaging format, with foodservice buyers demanding bulk couverture specifications distinct from retail gifting formats.
- Retail Consumers:Individual portion and gift-box purchases for direct consumption or festival exchange. E-commerce festivals displace traditional lunar calendar occasions in tier-1 cities, compressing decision cycles during 618 and Double Eleven drops.
- Bakeries:Industrial chocolate compounds for pastry lamination and enrobing, requiring viscosity stability across temperature fluctuations in provincial production environments.
- Cafés:Beverage-led consumption occasions expanding chocolate's addressable moments beyond conventional snacking in Guangzhou and tier-2 provincial capitals.
- Restaurants:Plated dessert and mole-style savory applications, concentrated in hotel chains and fine-dining establishments in Beijing and Shanghai.
Retail consumers anchor volume. Cafés are climbing the fastest as occasion expansion accelerates.
Distribution Channel:
Margin structure inverts between digital and physical channels, with online retail capturing growth trajectory while supermarkets sustain absolute transaction base.
- Online Retail:Live-streaming commerce platforms redirect marketing spend from traditional media, with influencer-endorsed limited editions driving compressed purchase cycles among urban millennials.
- Supermarkets:Infrastructure expansion in Chengdu and Wuhan creates first-mover positioning before specialty saturation, sustaining largest absolute transaction base across lower-tier cities.
- Specialty Stores:Bean-to-bar traceability systems deploy blockchain-verified origin documentation to justify price premiums in Shanghai and Beijing.
- Convenience Stores:Impulse-oriented single-serve formats, constrained by cold chain limitations in tier-3 and tier-4 networks.
Supermarkets dominate installed base. Online retail is gaining share fastest.
Price Tier:
Cost stratification aligns with cocoa content verification and origin documentation, with premium tiers absorbing compliance investment from sugar-reduction mandates.
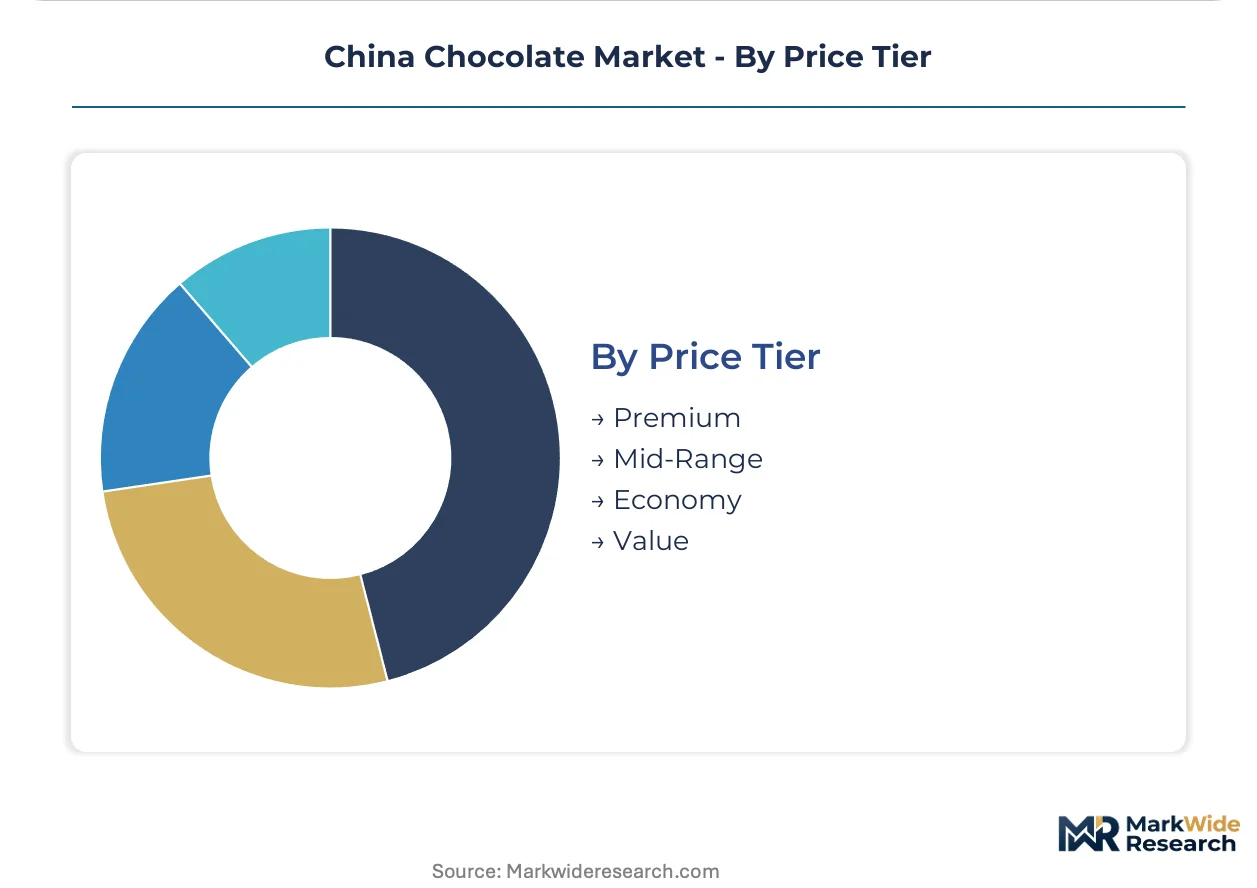
- Premium:Single-origin and artisanal positioning with full cocoa butter formulation, concentrated in festival-season gift-box formats and corporate procurement channels serving state-owned enterprises.
- Mid-Range:Localized flavor adaptations navigate shifting provincial taste preferences, facing margin pressure from SAMR labeling compliance and import tariff cascades for European labels.
- Economy:Compound chocolate with cocoa butter substitutes, volume-driven through mass retail in inland provinces with limited cold chain penetration.
- Value:Price-competitive positioning for rural market entry, constrained by formulation flexibility limitations under evolving GB standards.
Mid-range holds installed base. Premium is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African cocoa bean shipments flow predominantly into Shanghai and Shenzhen port complexes, where processing facilities convert raw inputs into chocolate liquor and cocoa butter for redistribution across domestic manufacturing networks.
Yangtze River Delta
Shanghai specialty boutiques and café culture drive per-capita consumption premiums among urban millennials seeking single-origin credentials. SAMR enforcement of GB standards for cocoa content labeling accelerates consumer education in this cluster. Artisanal producers in satellite Jiangsu and Zhejiang manufacturing zones deploy blockchain-verified traceability systems to justify price elevation.
Pearl River Delta
Guangzhou beverage-led consumption occasions expand chocolate's addressable moments beyond conventional snacking. National Health Commission sugar-reduction guidelines pressure local formulators toward allulose and monk fruit extract applications. Shenzhen cross-border e-commerce hubs face extended customs clearance cycles under evolving SAMR documentation requirements.
Beijing-Tianjin-Hebei
Festival-season gifting concentrates in corporate procurement channels serving state-owned enterprises and technology firms. GB standards evolution on additive disclosure tightens compliance timelines for imported European labels. Tianjin port infrastructure handles bulk cocoa butter shipments for redistribution to inland processing facilities.
Sichuan-Chongqing
Supermarket infrastructure expansion in Chengdu creates first-mover positioning before specialty retail saturation reaches coastal levels. Provincial taste preferences favor localized flavor adaptations from mid-range producers. Cold chain limitations in tier-3 city networks constrain tempering-sensitive product distribution.
Shandong Peninsula
Manufacturing scale advantages attract Mars Incorporated and domestic compound chocolate producers seeking volume throughput. MIIT industrial policy incentives support food processing cluster development in Qingdao. Cocoa butter substitute formulations dominate rural market entry given limited cold chain penetration.
China Chocolate Market Vendor Landscape
Player mix skews toward multinational confectionery conglomerates with diversified brand portfolios spanning premium gifting through mass-market penetration. Market structure exhibits tiered concentration, with festival-season gift-box formats commanding disproportionate margin capture relative to volume share. Strategic archetypes separate into premium-positioned European heritage brands, scale-driven American multinationals with provincial manufacturing hubs, and agile domestic specialists exploiting regulatory familiarity advantages. Dominant competitive moves center on sugar-reduction reformulation racing ahead of GB standards tightening and live-streaming commerce platform partnerships redirecting marketing spend from traditional media.
Within the multinational conglomerate tier, Ferrero International SA and Mars Incorporated exemplify divergent positioning strategies, with the former anchoring premium gifting through heritage European formats and the latter sustaining manufacturing scale across multiple provincial production hubs. Nestlé SA occupies a mid-range position characterized by localized flavor adaptations navigating shifting provincial taste preferences. Domestic specialists including Want Want China Holding Ltd. leverage regulatory familiarity advantages in SAMR inspection timelines and GB standards compliance.
| Leading Market Players |
|---|
| Ferrero International SA |
| Meiji Holdings Company Ltd |
| Nestlé SA |
| Want Want China Holding Ltd. |
| Chocoladefabriken Lindt & Sprüngli AG |
| Mars Incorporated |
| The Hershey Company |
| Cargill Incorporated |
| Mondelēz International Inc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for West African cocoa bean shipments lock in supply access for Chinese processors while providing partial insulation against weather-driven price swings that compress formulation flexibility. These contractual structures concentrate pricing power among established trading houses with established port relationships at Shanghai and Shenzhen, leaving smaller domestic formulators exposed to spot market volatility.
Pricing Analysis
Current-generation sugar-reduced formulations command meaningful premiums over legacy high-sugar variants as National Health Commission guidelines compress acceptable taste profiles. Three-tier pricing structure across premium, standard, and economy levels stratifies by cocoa butter purity and origin documentation, with single-origin dark chocolate from Yunnan and Hainan artisanal producers capturing the highest tier. Pricing pressure stems from GB standards compliance investments that mid-range imported labels struggle to absorb against domestic regulatory familiarity advantages. Supermarket buyers in lower-tier cities exhibit highest price sensitivity, while specialty boutique customers in Shanghai and Beijing demonstrate inelastic demand for verified provenance credentials.
Supply Chain Analysis
Inbound logistics costs from West African ports through Shanghai and Shenzhen complexes fluctuate with container availability on Asia-West Africa trade lanes, compressing landed margins for processors without dedicated shipping contracts. Côte d'Ivoire, Ghana, and Nigeria anchor raw bean supply concentration, with Chinese processors drawing from this triad for 80% plus of cocoa solids inputs. Cocoa butter, cocoa liquor, and emulsifier dependencies create formulation rigidity when any single input experiences commodity price spikes. Single-source vulnerability concentrates in West African bean supply given limited alternative origin infrastructure at comparable scale. Distribution runs through provincial manufacturing hubs with cold-chain-dependent redistribution to tier-3 and tier-4 city networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among e-commerce platform operators and supermarket chains with national footprints, fragmenting historical distributor influence and compressing margin capture for brands without direct channel access.
For Market Incumbents: Secure exclusive supply partnerships with Yunnan and Hainan bean-to-bar producers before specialty origin credentials become commoditized. Lock in cold chain infrastructure investments across Chengdu and Wuhan distribution nodes ahead of lower-tier city saturation. Sugar-reduction formulation R&D represents the critical capability lever against functional substitutes capturing fitness-oriented consumption occasions. For New Entrants and Emerging Players: Differentiate on blockchain-verified traceability systems that justify price elevation among urban millennials seeking ritualized gifting credentials. Target corporate procurement channels serving state-owned enterprises as the most penetrable white-space segment with underdeveloped premium chocolate penetration. Deploy live-streaming commerce platform partnerships as the primary go-to-market angle, redirecting marketing spend from traditional media toward influencer-endorsed limited edition drops. For Investors and Strategic Acquirers: Capital is best deployed toward domestic specialists with established SAMR regulatory familiarity and GB standards compliance infrastructure. Long-term viability over the coming decade hinges on sugar-reduced formulation capabilities that outpace National Health Commission mandate acceleration. Watch for inflection signals in allulose and monk fruit extract adoption rates among tier-1 city specialty boutiques as indicators of premium positioning sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Sugar-Reduced Formulation Investment | Aligns product portfolios with National Health Commission guidelines ahead of GB standards tightening. |
| Bean-to-Bar Traceability Integration | Blockchain-verified origin documentation justifies price premiums among Shanghai and Beijing urban millennials. |
| Lower-Tier City Distribution Expansion | Supermarket infrastructure in Chengdu and Wuhan creates first-mover positioning before specialty retail saturation. |
| Live-Streaming Commerce Partnership | Influencer-endorsed limited editions during 618 and Double Eleven compress decision cycles among digital-native buyers. |
| Cold Chain Infrastructure Upgrade | Temperate-controlled warehousing enables cocoa butter stability across tier-3 and tier-4 provincial networks. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with chocolate brand managers, SAMR regulatory affairs specialists, supermarket category buyers, and specialty boutique operators; alongside secondary validation through customs import records, National Health Commission policy filings, and GB standards documentation. Bottom-up demand modeling triangulated against top-down market sizing from production capacity disclosures and channel shipment data.
The forecasting boundary spans the full projection horizon with analytical frameworks segmenting by product type, end user application, distribution channel, and price tier positioning. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for regulatory intervention timelines and channel shift velocities. Cocoa butter input cost trajectories and e-commerce penetration curves served as industry-specific demand elasticity inputs.
Decision-makers should treat outputs as directional under assumptions of stable West African supply conditions and gradual GB standards evolution; material deviation through weather shocks or accelerated sugar-reduction mandates would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Milk Chocolate Market
Confectionery
Europe Confectionery Market
Confectionery
Buttercream Frosting Market
Confectionery
White Chocolate Market
Confectionery
Mints Market
Confectionery
Europe Premium Chocolate Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Chocolate Flavors Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market
Confectionery
Mooncake Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Ruby Chocolate Market
Confectionery
Confectionery Fillings Market
Confectionery
Asia-Pacific Confectionery Market