
 South Africa Confectionery Market | 2026-2036
South Africa Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Confectionery Market Insights
A capital-intensity divergence between automated production lines and artisan-scale equipment is rotating competitive advantage toward multinationals with centralized manufacturing. Tiger Brands Ltd leverages its domestic bakery and snack infrastructure to anchor confectionery distribution across mass retail channels. Mondelēz International Inc. sustains premium positioning through imported Cadbury and Toblerone portfolios stocked in major supermarket chains. Nestlé SA competes on volume scale, operating milky bar and KitKat production that reaches township spaza shops and rural wholesalers alike.
Confectionery comprises sugar-based or cocoa-derived food products formulated for sensory pleasure, typically containing sweeteners, fats, emulsifiers, and flavoring agents processed through conching, tempering, or depositing methods. Chocolate dominates value contribution, with cocoa butter content and bean origin defining price tiers from mass-market slabs to single-origin craft bars. Hard candies and gummy sweets occupy faster-turning, lower-margin shelf space in convenience stores and petrol station kiosks. Supermarkets and online retail channels are expanding fastest, while wholesale cash-and-carry routes still control township and rural penetration where brand loyalty runs thinnest.
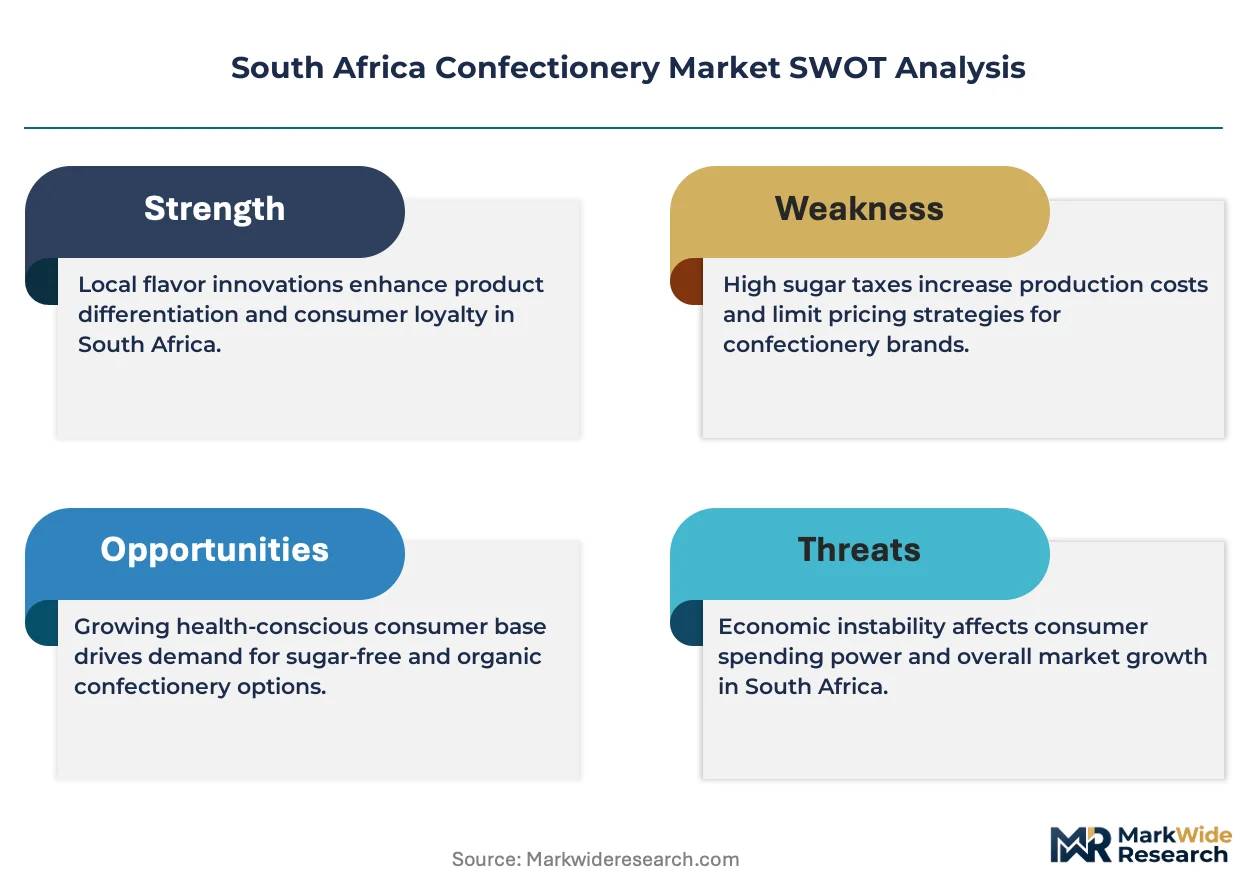
The Department of Health enforces sugar tax thresholds that reshape formulation strategies, forcing manufacturers to reformulate or absorb excise costs that compress economy-tier margins. BIS-equivalent food safety standards and FSSAI-aligned import regulations govern additive limits and labeling requirements for both domestic producers and incoming shipments. The National Regulator for Compulsory Specifications monitors cocoa product standards to prevent adulteration in budget segments. Stakeholders must monitor how sugar tax escalations and evolving front-of-pack warning labels will force portfolio restructuring between premium indulgence and permissible-treat positioning.
Market Dynamics
The Department of Health's sugar tax thresholds are compressing margin structures across mass-market tiers while supermarket private-label expansion reconfigures channel power toward retail-controlled supply chains.
Growth Catalysts
- Health and Wellness Taxation Framework:The Department of Health's sugar tax regulations are accelerating reformulation investments toward reduced-sugar and alternative-sweetener portfolios that command premium shelf positioning.
- Spaza Shop Distribution Density:Township informal retail networks create last-mile penetration advantages for volume-scaled manufacturers reaching underserved consumption clusters.
- Bean-to-Bar Traceability Systems:Blockchain-enabled cocoa provenance tracking is opening export certification pathways for South African processors targeting EU ethical sourcing mandates.
Market Restraints
- Cocoa Butter Price Volatility:West African supply disruptions and currency fluctuations in Côte d'Ivoire and Ghana input markets destabilize cost forecasting for chocolate manufacturers.
- Import Dependency Concentration:Refined sugar and cocoa mass supply chains route through Durban port infrastructure, creating single-point vulnerability for Gauteng-based production facilities.
- Sugar Tax Excise Compression:The Department of Health's tiered levy structure absorbs margin capacity in economy-tier segments where price elasticity constrains pass-through.
Strategic Opportunities
- Western Cape Wine Route Tourism Integration:Premium chocolate pairing experiences and factory tourism circuits tap high-spending international visitor flows through Cape Town and Stellenbosch corridors.
- E-Commerce Direct-to-Consumer Channels:Online subscription models for craft and single-origin products bypass supermarket listing fees while capturing data-rich customer relationships.
- Front-of-Pack Label Reform Tailwind:Anticipated Department of Health warning label mandates will advantage early reformulators with permissible-treat positioning ahead of compliance deadlines.
Industry Challenges
- Confectionery Technologist Talent Scarcity:Specialized expertise in reduced-sugar formulation and alternative protein integration remains concentrated in European and North American training institutions.
- Legacy Equipment Retrofit Complexity:Tempering and depositing lines engineered for sucrose-based matrices require capital-intensive reconfiguration to process polyol and fiber-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Confectionery Market |
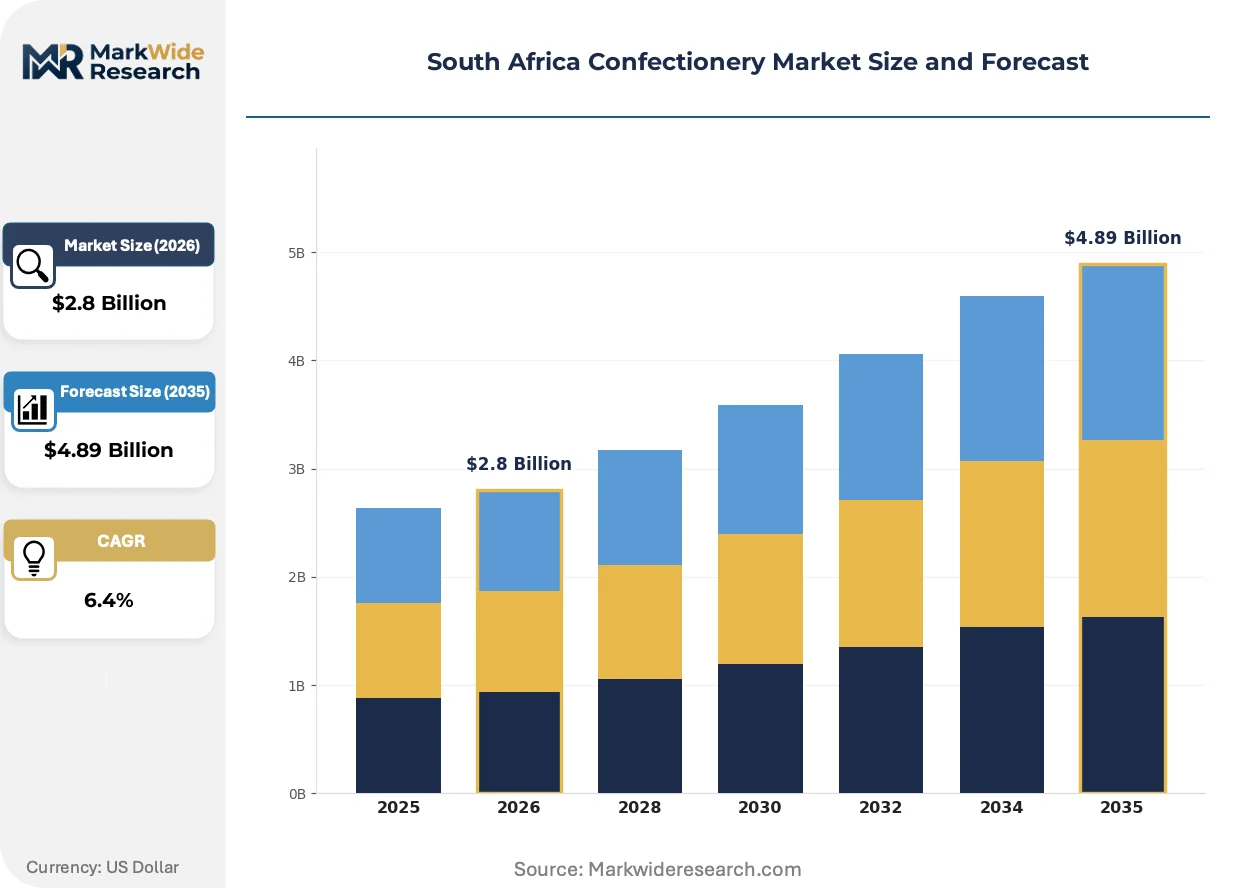
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Hard Candies, Gummy Sweets, Gum Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers End User: Children, Teenagers, Adults, Seniors Price Tier: Premium, Mid-Range, Economy, Value |
| Companies Covered | Tiger Brands Ltd, Mondelēz International Inc., Nestlé SA, Ferrero International SA, Mars Inc., Premier FMCG (Pty) Ltd, Richester Foods (Pty) Ltd, Sally Williams Fine Foods (Pty) Ltd, Lindt and Sprungli (South Africa) (Pty) Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Confectionery Market Trends and Innovations
Manufacturing technology and retail channel structures are diverging sharply between mass-scale automation and craft-scale flexibility, while regulatory pressure and shifting consumption occasions reshape portfolio architecture.
Clean-label emulsifier systems derived from sunflower lecithin and acacia gum are displacing synthetic alternatives in premium chocolate formulations. Artisan producers in the Western Cape and KwaZulu-Natal coastal corridors are adopting these inputs fastest, securing export eligibility for EU and UK ethical retail channels. The ingredient supply base is bifurcating between commodity-scale soy lecithin for mass market and identity-preserved botanical alternatives for certified segments.
The Department of Health's evolving front-of-pack warning label specifications are forcing accelerated reformulation timelines. Manufacturers must now balance sensory fidelity with nutrient profile thresholds or accept excise penalties and retail delisting risk. Premium indulgence portfolios with heritage brand equity absorb compliance costs most readily, while economy-tier private-label suppliers face existential margin compression.
Convenience-oriented consumption is fragmenting traditional gifting and seasonal purchase patterns into everyday permissible-treat occasions. Single-serve portion formats and petrol station kiosk placement are displacing large-format slab sales in urban commuter corridors. Gauteng's Johannesburg-Pretoria retail axis exhibits the sharpest channel rotation, with forecourt retail and app-based delivery platforms capturing impulse purchase occasions previously routed through supermarkets.
South Africa Confectionery Market Segmentation
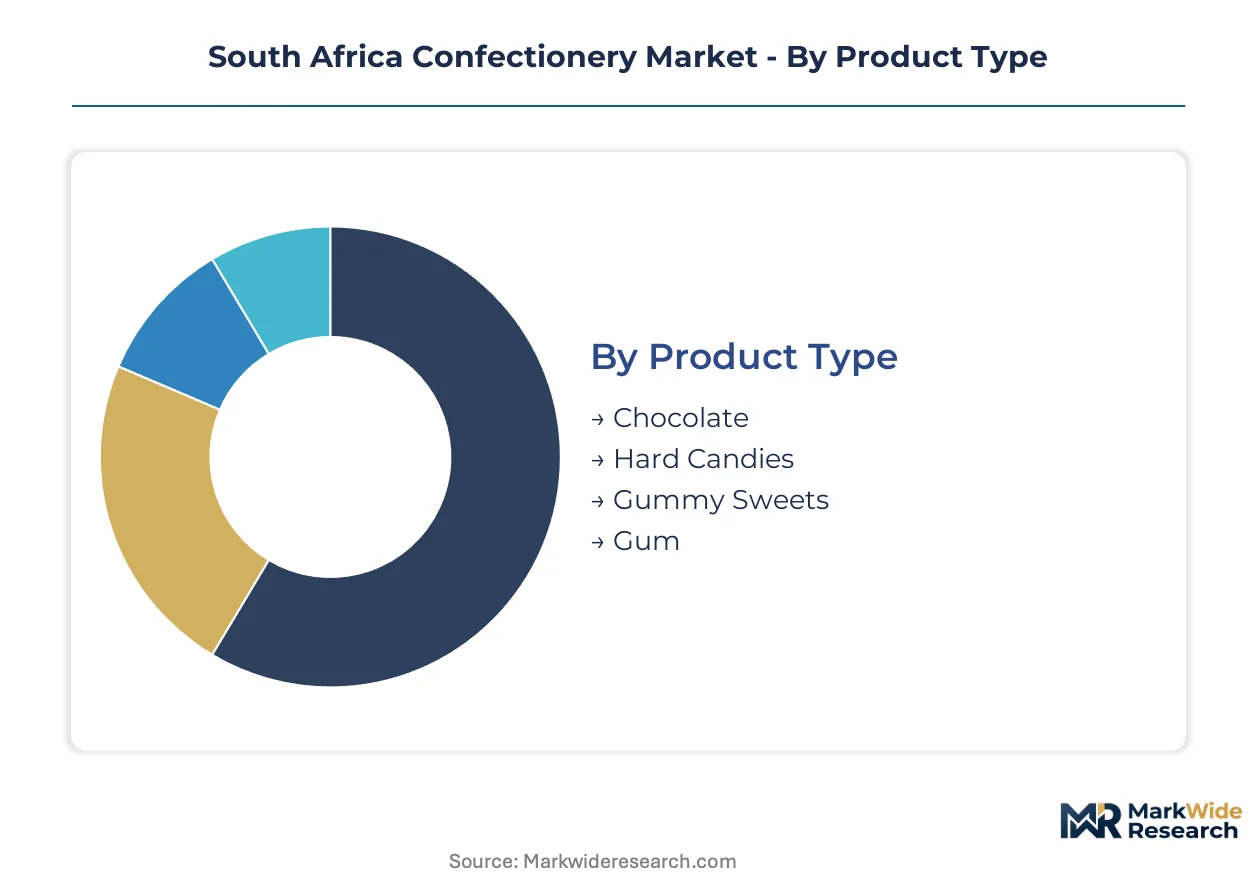
Segmentation in the South African confectionery market reveals how sugar tax pressures and channel fragmentation split demand across incompatible value propositions. Manufacturers must configure portfolios that serve township spaza networks and premium Gauteng retail corridors simultaneously.
Product Type:
Chocolate faces the sharpest substitution pressure from reduced-sugar alternatives as Department of Health excise thresholds force reformulation trade-offs.
- Chocolate:Cocoa butter-based formulations span mass-market slabs to single-origin craft bars, with bean origin and butter content defining price tiers. Gauteng's Johannesburg-Pretoria corridor concentrates premium chocolate demand through supermarket chains and imported Cadbury and Toblerone portfolios. Sugar tax compliance costs compress economy-tier margins while heritage brands absorb reformulation expenses.
- Hard Candies:Sugar-based or isomalt-based confections processed through depositing and cooling methods occupy high-velocity, low-margin shelf space. Petrol station kiosks and convenience stores in urban commuter corridors drive impulse purchase volumes for single-serve formats.
- Gummy Sweets:Gelatin or pectin-based chewy candies targeting permissible-treat occasions with portion-controlled packaging.
- Gum:Polyol-sweetened or sugar-based masticatory products positioned for breath-freshening and oral-care functional claims.
Chocolate anchors the volume base while hard candies gain share at the steepest rate through forecourt retail expansion.
Distribution Channel:
Channel economics diverge sharply between retail-controlled supply chains and informal township networks, with margin structures dictating portfolio allocation.
- Supermarkets:Formal retail chains expanding private-label confectionery aisles to capture budget-conscious shoppers, with listing fees and shelf-space negotiations favoring multinationals with centralized manufacturing. The Western Cape wine route tourism corridor drives premium chocolate pairing experiences through Cape Town and Stellenbosch retail nodes.
- Convenience Stores:High-frequency, small-format outlets capturing fragmented impulse occasions through single-serve placement and commuter corridor density.
- Online Retail:Direct-to-consumer subscription models for craft and single-origin products bypass supermarket listing fees while capturing data-rich customer relationships in Gauteng and Western Cape urban centers.
- Wholesalers:Cash-and-carry routes controlling township and rural penetration where brand loyalty runs thinnest and price elasticity constrains manufacturer margins.
Supermarkets dominate value capture while online retail climbs fastest as delivery platforms reshape urban purchase patterns.
End User:
Demographic targeting must reconcile permissibility concerns for younger consumers with indulgence positioning for adult segments.
- Children:Portion-controlled formats and front-of-pack label compliance shape formulation decisions, with parental gatekeeping intensifying scrutiny of additive content and sugar levels in Gauteng middle-income households.
- Teenagers:Social consumption and peer-influenced brand preferences drive impulse purchasing through forecourt retail and app-based delivery platforms in Johannesburg-Pretoria urban corridors.
- Adults:Permissible-treat occasions and premium indulgence positioning support higher-margin chocolate and craft product adoption.
- Seniors:Functional and reduced-sugar formulations addressing dietary restriction compliance and health-conscious consumption patterns.
Adults generate the revenue base while teenagers expand most quickly through digital channel engagement.
Price Tier:
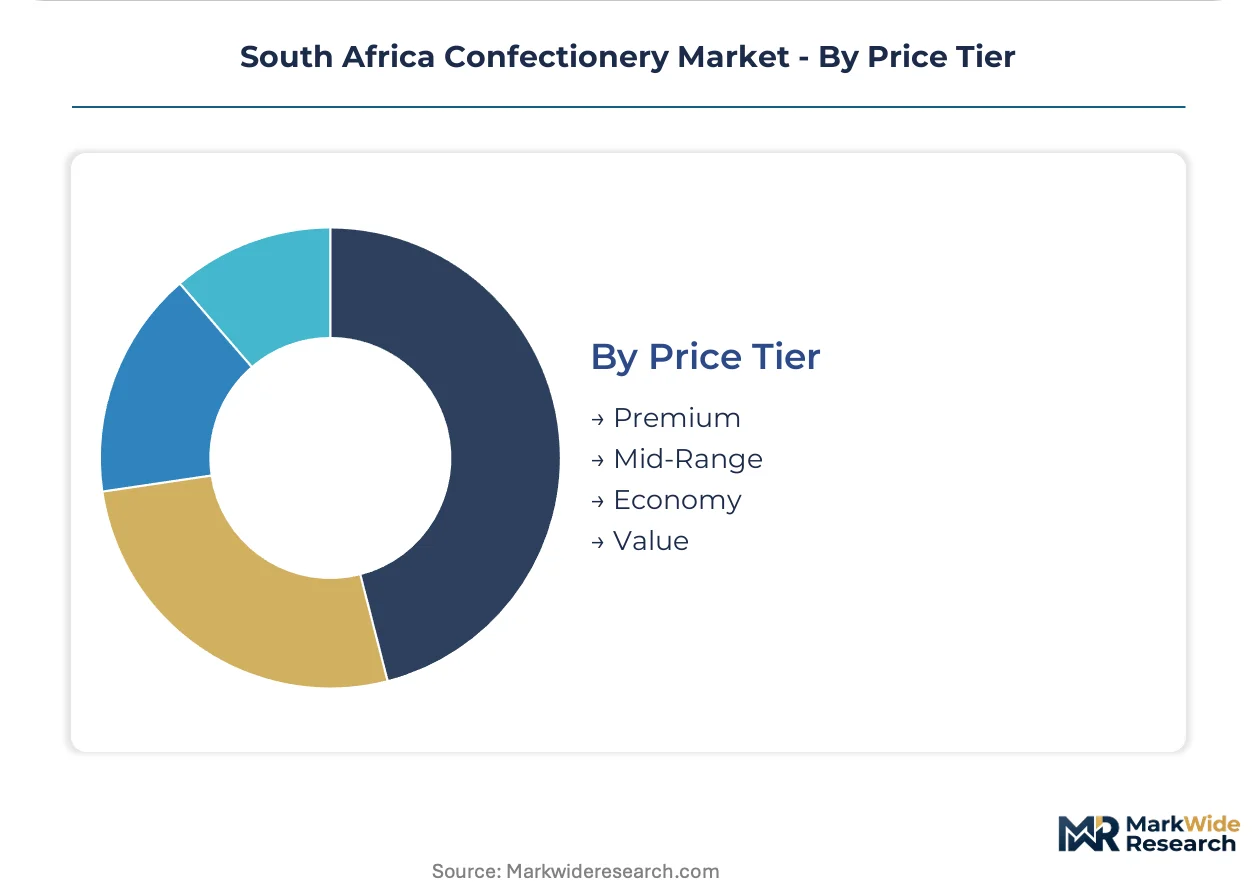
Three-tier pricing structure across premium, standard, and economy levels reflects divergent cost absorption capacities under sugar tax pressure.
- Premium:Heritage brand equity and imported portfolios command shelf positioning that absorbs compliance costs, with single-origin craft bars and ethical certification commanding price multiples in Western Cape tourism corridors.
- Mid-Range:Domestic manufacturing scale and supermarket chain partnerships balance quality perception with accessibility for Gauteng mass-market consumers.
- Economy:Private-label and township-focused products facing existential margin compression from excise pass-through limitations and price elasticity constraints.
- Value:Ultra-low-price segments dependent on wholesale cash-and-carry distribution and informal spaza shop networks in rural and township geographies.
Economy tier holds the volume foundation while premium tier expands most steeply through tourism and export channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity splits sharply across South Africa's economic geography. Gauteng's affluent corridors absorb premium price points with minimal volume sensitivity, while Eastern Cape and Limpopo townships exhibit extreme price elasticity that channels volume toward economy-tier private labels.
Gauteng
Johannesburg-Pretoria retail corridors concentrate premium chocolate and imported candy sales through formal supermarket chains. The Department of Health's sugar tax thresholds compress margins most severely here as heritage brands reformulate to maintain shelf positioning. Sandton and Rosebank nodes anchor single-origin craft chocolate distribution targeting high-income households.
Western Cape
Cape Town-Stellenbosch tourism circuits drive premium chocolate pairing experiences and factory tourism revenue streams. Cape Town's port infrastructure enables cocoa mass importation for processors targeting EU ethical sourcing mandates. The city's craft producer density exceeds any other South African metro.
KwaZulu-Natal
Durban's port concentration creates single-point vulnerability for refined sugar and cocoa mass supply chains routing to Gauteng production facilities. The coastal corridor's humidity challenges tempering operations, favoring hard candy and gummy formats over chocolate. Pietermaritzburg anchors mid-tier manufacturing scale.
Eastern Cape
Port Elizabeth-Gqeberha informal retail networks exhibit thinnest brand loyalty and highest price elasticity, channeling volume toward wholesale cash-and-carry distribution. The province's rural penetration depends on spaza shop density where economy-tier private labels dominate. Reformulation costs from sugar tax compliance pass through least effectively here.
Limpopo
Polokwane and rural nodes represent the most underpenetrated formal retail geography, with township spaza shops controlling virtually all confectionery access. Volume-scaled manufacturers leverage last-mile wholesale networks to reach consumption clusters bypassed by supermarket expansion. Price points cluster at the economy-value tier boundary.
South Africa Confectionery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational scale advantages separating clearly from domestic manufacturing concentration. The integrated tier commands centralized production infrastructure and supermarket listing fee capacity. Specialist tiers fragment across artisan craft producers, private-label suppliers, and township-focused wholesalers. Dominant competitive moves include portfolio diversification between premium indulgence and permissible-treat positioning, plus strategic partnerships with spaza shop wholesale networks.
Within the integrated multinational tier, Tiger Brands Ltd and Mondelēz International Inc. exemplify divergent strategic archetypes. Tiger Brands leverages domestic bakery and snack infrastructure to anchor mass retail distribution across Gauteng supermarket chains. Mondelēz sustains premium positioning through imported portfolio concentration. Nestlé SA occupies a scale-driven position reaching township spaza shops and rural wholesalers through volume manufacturing. These three entities represent the competitive structure's poles: domestic infrastructure leverage, import-dependent premium positioning, and volume-scale rural penetration.
| Leading Market Players |
|---|
| Tiger Brands Ltd |
| Mondelēz International Inc. |
| Nestlé SA |
| Ferrero International SA |
| Mars Inc. |
| Premier FMCG (Pty) Ltd |
| Richester Foods (Pty) Ltd |
| Sally Williams Fine Foods (Pty) Ltd |
| Lindt and Sprungli (South Africa) (Pty) Ltd |
| Others |
Pricing and Supply Chain Analysis
Centralized manufacturing scale at Tiger Brands and Nestlé SA facilities anchors cost floors across Gauteng production corridors, compressing margins for artisan competitors while creating tiered price bands that separate mass-market slabs from single-origin craft positioning.
Pricing Analysis
After-sales revenue through spaza shop wholesale networks and forecourt retail placement drives lifetime value more than initial product margin. Three-tier pricing structure across premium, standard, and economy levels reflects brand equity absorption capacity under Department of Health sugar tax thresholds. Price differentiation hinges on cocoa butter content certification and heritage brand positioning. Pricing pressure stems from excise pass-through limitations in economy tiers where price elasticity constrains recovery. Township spaza networks exhibit highest price sensitivity; Sandton-Rosebank corridors show lowest.
Supply Chain Analysis
Durban port infrastructure chokepoints underwrite Gauteng production vulnerability, with refined sugar and cocoa mass shipments routing through single maritime gateway. West African supply from Côte d'Ivoire and Ghana feeds cocoa butter inputs; Indian Ocean shipping lanes connect Southeast Asian emulsifier sources. Raw material dependency rests on cocoa mass, refined sugar, and sunflower lecithin alternatives. Single-point port concentration creates tariff exposure and logistics bottleneck risk. Distribution runs through supermarket chain controlled supply chains, wholesale cash-and-carry township networks, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reformulation service contracts and permissible-treat portfolio consulting represent faster-expanding recurring revenue layers than core confectionery manufacturing, as Department of Health compliance mandates deepen manufacturer advisory dependencies.
For Market Incumbents: Secure spaza shop wholesale network exclusivity through volume rebate structures and route-to-market infrastructure investment. Lock in Western Cape bean-to-bar traceability certification ahead of EU ethical sourcing mandate expansion. Counter Mondelēz International Inc. premium import positioning with domestic heritage brand reformulation speed-to-shelf. For New Entrants and Emerging Players: E-commerce subscription fulfillment gaps in single-origin craft chocolate represent incumbents' under-served service layer. Target Gauteng high-income households through direct-to-consumer platforms bypassing supermarket listing fee barriers. Lead with blockchain-enabled provenance storytelling and personalized portion-controlled subscription formats. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated tempering line operators with retrofit capacity for polyol-based matrices. Five-to-ten year viability hinges on reformulation R&D amortization across premium and permissible-treat portfolios. Acquire Western Cape craft producers with EU export certification infrastructure. Watch Department of Health front-of-pack warning label implementation timelines as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Reduced-Sugar Reformulation Investment | Department of Health excise thresholds force portfolio restructuring toward permissible-treat positioning ahead of compliance deadlines. |
| Spaza Shop Distribution Expansion | Township informal retail networks capture last-mile penetration advantages in under-served Eastern Cape and Limpopo consumption clusters. |
| Bean-to-Bar Traceability Certification | Blockchain-enabled cocoa provenance tracking opens EU ethical sourcing export pathways for Western Cape processors. |
| E-Commerce Direct-to-Consumer Launch | Online subscription models bypass supermarket listing fees while capturing data-rich customer relationships in Gauteng urban centers. |
| Clean-Label Emulsifier Transition | Sunflower lecithin and acacia gum systems displace synthetic alternatives for premium chocolate export eligibility to UK retail channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs records, Nielsen retail audit data, and Department of Health regulatory filings. Interviews with brand managers, category buyers at Pick n Pay and Shoprite, channel sales heads, and supply planners informed demand-side calibration. Secondary validation drew from BIS-equivalent food safety standards documentation, FSSAI-aligned import regulation records, and National Regulator for Compulsory Specifications cocoa product standards. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Segmentation dimensions modeled include product type, distribution channel, end user demographic, and price tier stratification across the analysis window. CAGRs derived from historical trajectory analysis adjusted for regulatory intervention impacts and channel shift elasticity. Industry-specific forecast inputs incorporated sugar tax escalation schedules and spaza shop network density mapping.
Forecasts assume regulatory continuity in Department of Health sugar tax thresholds and front-of-pack label specifications; material policy shifts would require re-modeling. Cocoa butter price volatility in West African supply markets and Durban port logistics disruptions represent primary revision risks. Practitioners should keep alternative scenarios live as EU ethical sourcing mandate timelines and e-commerce penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Middle East and Africa Confectionery Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Middle East Chocolate Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
Chocolate Confectionery Market
Confectionery
Dark Chocolate Market
Confectionery
North America Compound Chocolate Market
Confectionery
Confectionery Fats Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Chocolate Spread Market
Confectionery
North America Dark Chocolate Market
Confectionery
Europe Premium Chocolate Market
Confectionery
Sugar Free Mints Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
India Industrial Chocolate Market