
 Pop-Up Pourer Market | 2026-2036
Pop-Up Pourer Market Size, Share, and Industry Trends Forecast 2026-2036
Pop-Up Pourer Market Analytics
Supplier diversification from single-source Asian manufacturing to multi-continental sourcing is hardening as a defensive strategy among kitchenware distributors. OXO International Ltd. leverages its direct-to-consumer channel strength to sustain premium positioning, while Tablecraft Products Company anchors the North American foodservice supply chain through broad SKU coverage. Bormioli Rocco USA competes on European design heritage, and Prepara differentiates through specialized wine-accessory sub-categories.
A pop-up pourer is a mechanical dispensing device, typically constructed from food-grade silicone, stainless steel, or BPA-free polymer, that inserts into bottle necks to control liquid flow through a spring-activated or hinged aperture mechanism. The device serves commercial and residential users by preventing drips, enabling measured pouring, and preserving contents from oxidation. Plastic and silicone variants lead household volume due to cost accessibility, while metal pourers command higher margins in bars and restaurants where durability under commercial dishwashing cycles determines replacement frequency. Standard pourers dominate the product-type landscape, though decorative pourers are gaining traction in gift and specialty retail channels where visual differentiation commands shelf attention.
The FDA regulates food-contact substances under 21 CFR, while the EU enforces REACH and F-Gas Regulation compliance for polymer components and any associated aerosol dispensing variants. These frameworks elevate testing costs for new market entrants but also consolidate demand toward established suppliers with certified material traceability. Stakeholders must monitor evolving state-level plastic restrictions in California and New York, as these jurisdictions often prefigure broader North American material bans that would force rapid product-line adaptation.
Market Dynamics
Material certification requirements under the FDA's 21 CFR and the EU's REACH framework are fragmenting supplier bases, forcing kitchenware distributors to rebuild sourcing networks around traceable silicone and stainless-steel supply chains rather than cost-optimized polymer imports.
Growth Catalysts
- REACH chemical disclosure mandates:European hospitality procurement teams now require full material traceability, accelerating replacement cycles in Germany and France as bars discard non-compliant inventory.
- Front-of-house aesthetic investment:Premium restaurants in the United States are specifying brushed-metal pourers as tabletop design elements, expanding addressable unit value beyond functional utility.
- Silicone overmolding advances:Improved bonding techniques between stainless steel cores and silicone seals are extending dishwasher-cycle durability, reducing commercial replacement frequency.
Market Restraints
- Medical-grade silicone cost volatility:Input prices for platinum-cured silicone fluctuate with semiconductor industry demand, compressing margins on mid-tier product lines.
- Single-source Asian tooling concentration:Mold fabrication for complex spring mechanisms remains concentrated in Guangdong Province, exposing lead-time risk to regional logistics disruptions.
- Substitution by measured jigger systems:Precision bartending equipment with integrated flow control is capturing portion of the commercial volume previously served by pourer-plus-jigger combinations.
Strategic Opportunities
- Underpenetrated Australian craft distillery channel:Small-batch spirits producers lack dedicated accessory suppliers, creating white space for specialized pourer-cork combinations.
- EU F-Gas Regulation aerosol variant tailwind:Compliance-driven phase-out of fluorinated propellants is redirecting R&D investment toward mechanical dispensing alternatives.
- Direct-to-consumer subscription bundling:Wine club operators are testing pourer-plus-stopper kits as retention tools, opening recurring revenue models outside traditional retail.
Industry Challenges
- Food-contact certification timeline compression:FDA notification review periods for new polymer formulations now exceed typical product development cycles, delaying launches.
- Legacy ERP integration with traceability systems:Batch-level material tracking required by EU importers conflicts with distributor inventory management platforms designed for commodity SKUs.
- Spring mechanism fatigue testing standardization:Absence of unified cycle-count protocols between ISO and ASTM frameworks forces redundant validation spending.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pop-Up Pourer Market |
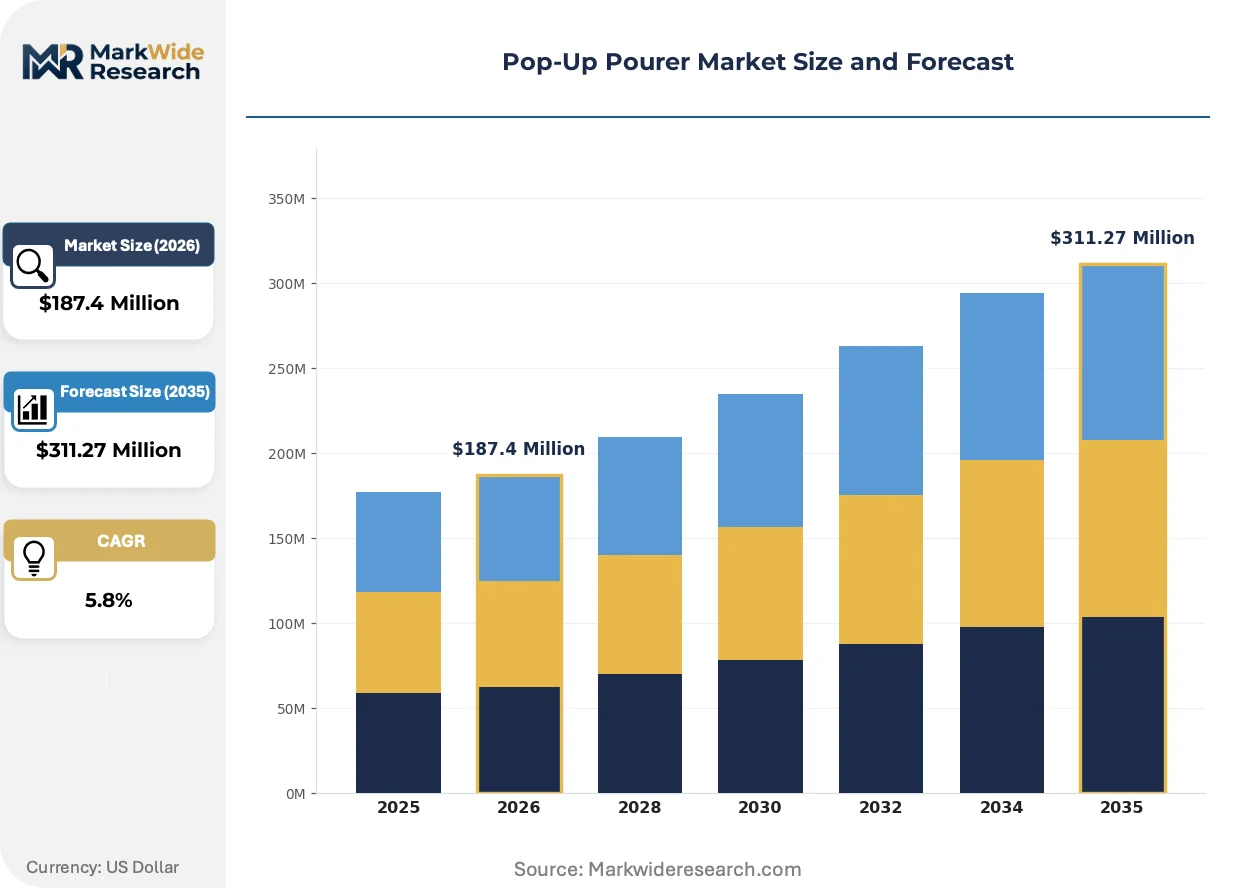
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pourer, Decorative Pourer, Funnel Pourer, Wine Pourer Material: Plastic, Metal, Silicone, Glass End User: Household, Restaurants, Bars, Catering Services Feature: Non-Spill, Easy Clean, Adjustable Flow, Multi-Use |
| Companies Covered | OXO International Ltd., Tablecraft Products Company, Libbey Inc., Bormioli Rocco USA, Prepara, Casabella, Emmeistar, Harold Import Co., Enriching Lifes Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pop-Up Pourer Market Evolving Landscape
Active materials science and regulatory disclosure requirements are converging to redefine what constitutes a premium pourer, with functional performance now inseparable from certified provenance and design-forward presentation.
Magnetic sealing mechanisms are integrating rare-earth components to create airtight closures that engage automatically upon bottle uprighting. Upscale hotel minibar programs in the United States are specifying these units to reduce housekeeping labor from recorking. The technology is integrating hospitality operational efficiency targets with residential wine preservation expectations, collapsing the feature gap between commercial and consumer tiers.
California's SB 54 extended producer responsibility framework is mandating recycled content thresholds for single-use food accessories, with draft rules capturing polymer pourers under packaging definitions. Manufacturers serving the state must now certify post-consumer resin percentages or face shelf-access restrictions. Foodservice distributors with California exposure are pre-emptively sourcing metal alternatives to avoid compliance complexity.
Bartender purchasing collectives are consolidating specification authority away from individual venue managers toward centralized procurement platforms. These groups negotiate direct manufacturer relationships, disintermediating traditional kitchenware distributors. The shift is most visible in metropolitan Texas and Florida markets where multi-unit bar groups command sufficient volume to justify private-label arrangements.
Pop-Up Pourer Market Segmentation
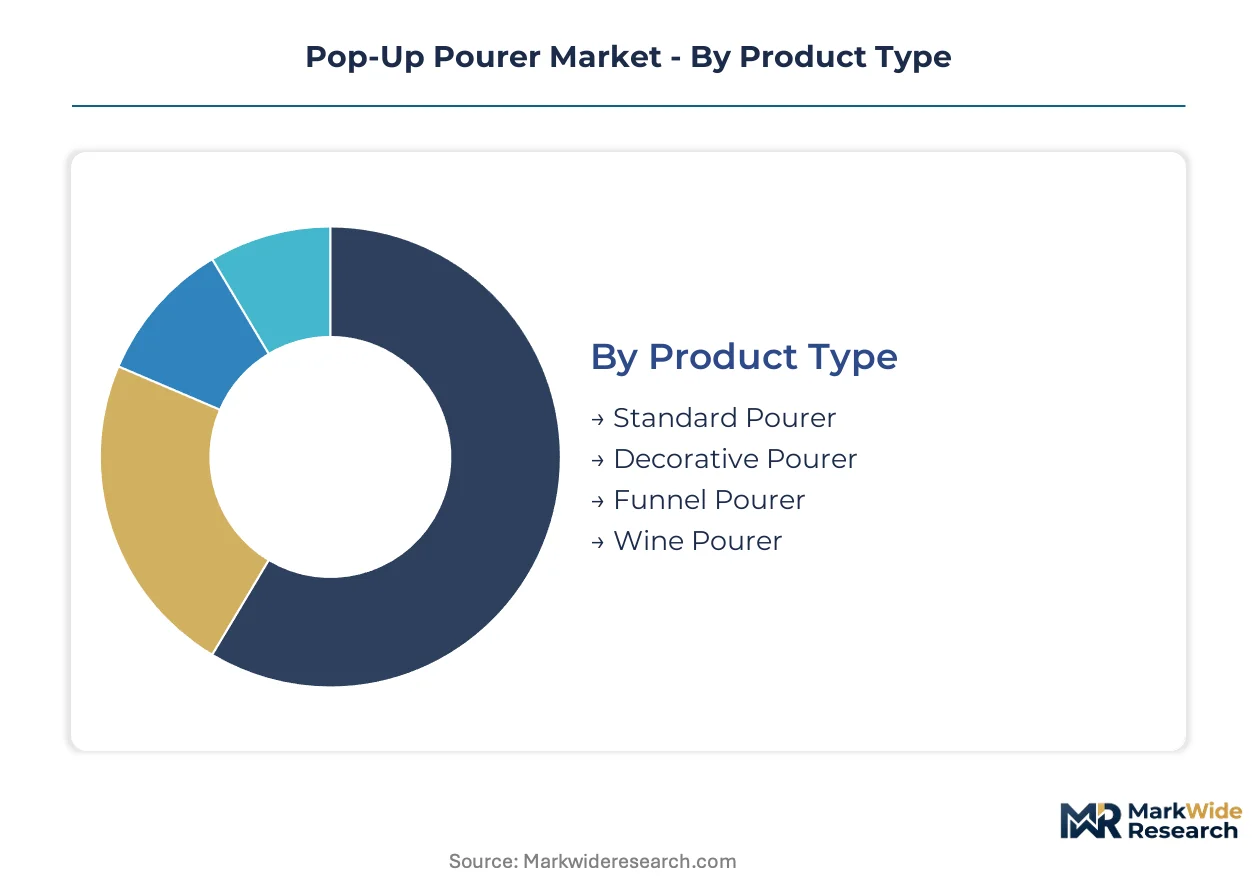
Pop-up pourer manufacturers configure production lines around material certification tiers and end-use durability requirements, with FDA and REACH compliance thresholds determining which segments absorb capital investment versus contract manufacturing. Understanding how demand fragments across these dimensions exposes where margin concentrates and where volume commoditizes.
Product Type:
Tooling investments for spring-activated mechanisms cluster with standard pourers, while decorative and specialized variants rely on shared mold platforms with shorter production runs.
- Standard Pourer:Constructed from food-grade silicone or stainless steel with spring-loaded aperture mechanisms, these units dominate commercial dishwashing environments. Bars in Germany and France specify certified units under REACH disclosure mandates, accelerating replacement of non-compliant inventory. Volume concentrates in North American foodservice distributors with broad SKU coverage.
- Decorative Pourer:Brushed-metal finishes and design-forward silhouettes serve front-of-house aesthetic requirements at premium restaurants. Hotels in the United States specify these for minibar and tabletop programs where visual differentiation supports brand positioning. Margin per unit exceeds functional equivalents by significant multiples.
- Funnel Pourer:Integrated wide-mouth designs target craft distillery bottling operations and home infusion enthusiasts. Small-batch producers in Australia lack dedicated accessory suppliers, creating white space for specialized configurations.
- Wine Pourer:Aeration-optimized geometries with drip-return channels serve oenophile retail channels and wine club subscription bundling. Direct-to-consumer operators test these as retention tools alongside stopper kits.
Standard pourers absorb the bulk of installed capacity; decorative pourers are expanding most quickly as front-of-house investment priorities shift.
Material:
Input cost volatility and regulatory certification timelines stratify supplier bases, with platinum-cured silicone and medical-grade polymers commanding qualification periods that exclude opportunistic entrants.
- Plastic:BPA-free polymer variants lead household volume through cost accessibility and color customization options. California's SB 54 extended producer responsibility framework mandates recycled content thresholds, forcing reformulation or shelf-access restrictions for non-compliant suppliers.
- Metal:Stainless steel pourers command higher margins in bars and restaurants where durability under commercial dishwashing cycles determines replacement frequency. Brushed and polished finishes support premium positioning in hospitality procurement.
- Silicone:Platinum-cured formulations with overmolded stainless steel cores extend dishwasher-cycle durability through improved bonding techniques. Input prices fluctuate with semiconductor industry demand, compressing margins on mid-tier product lines.
- Glass:Borosilicate and soda-lime variants serve gift and specialty retail where transparency and weight signal quality. Fragility limits commercial adoption despite aesthetic appeal.
Plastic holds the largest production footprint; silicone is climbing the fastest as REACH and FDA certification requirements reshape procurement specifications.
End User:
Purchasing authority consolidation and operational efficiency targets fragment demand patterns, with centralized procurement platforms displacing individual venue manager discretion in multi-unit operations.
- Household:Residential users prioritize cost accessibility and color variety over commercial durability metrics. E-commerce direct-to-consumer channels and kitchenware retailers serve this segment with polymer-dominant assortments.
- Restaurants:Front-of-house aesthetic investment drives specification of brushed-metal pourers as tabletop design elements. Premium establishments in the United States expand addressable unit value beyond functional utility.
- Bars:Commercial dishwashing compatibility and measured pouring accuracy determine replacement cycles. Bartender purchasing collectives in Texas and Florida metropolitan markets consolidate specification authority toward centralized platforms.
- Catering Services:High-turnover event environments demand disposable or rapid-replacement configurations with minimal capital commitment. Volume purchasing aligns with seasonal demand fluctuations.
Restaurants anchor material throughput; bars are gaining share fastest as purchasing collectives consolidate volume and disintermediate traditional distributors.
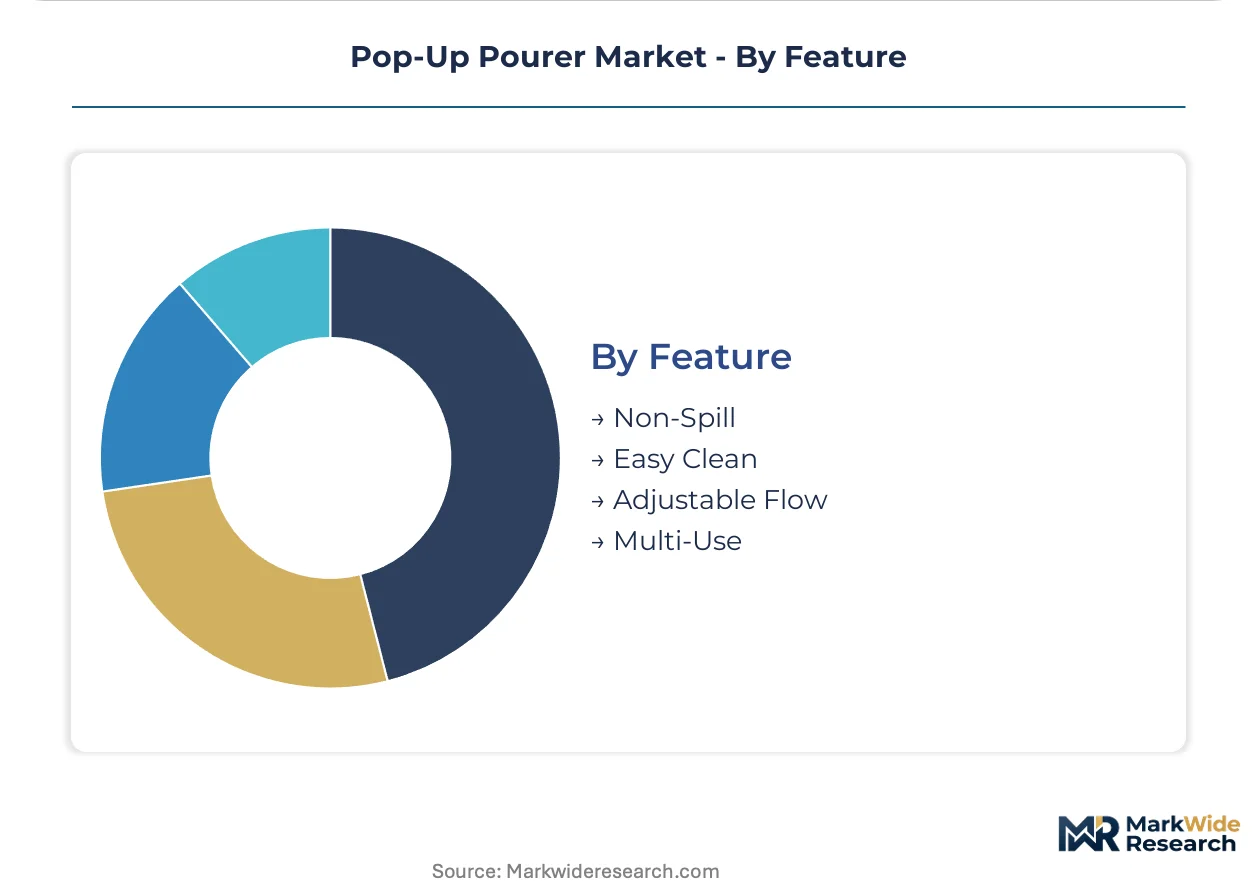
Feature:
Functional differentiation increasingly integrates with operational efficiency targets, collapsing the feature gap between commercial and consumer tiers through shared mechanism platforms.
- Non-Spill:Magnetic sealing mechanisms with rare-earth components create airtight closures that engage automatically upon bottle uprighting. Upscale hotel minibar programs in the United States specify these to reduce housekeeping labor.
- Easy Clean:Dishwasher-safe construction with minimal crevices supports commercial hygiene protocols and residential convenience expectations. Silicone overmolding advances improve seal integrity through repeated cycles.
- Adjustable Flow:Variable aperture mechanisms serve precision bartending requirements and controlled wine service. Substitution by measured jigger systems with integrated flow control captures portion of this functionality.
- Multi-Use:Modular designs accommodating oil, vinegar, spirits, and wine reduce SKU proliferation for distributors. Cross-category versatility supports inventory efficiency targets.
Non-spill features command premium positioning; easy clean specifications are expanding most quickly as dishwasher durability becomes a universal purchase criterion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum-cured silicone feedstock from Germany's chemical corridor anchors European supply chains, while Guangdong Province mold fabrication concentrates Asian tooling capacity for spring-activated mechanisms.
United States
Front-of-house aesthetic investment drives specification of brushed-metal pourers at premium restaurants and hotel minibar programs. California's SB 54 extended producer responsibility framework mandates recycled content thresholds for polymer accessories. Dallas and Houston bartender purchasing collectives consolidate procurement authority toward centralized platforms, disintermediating traditional kitchenware distributors.
Germany
REACH chemical disclosure mandates accelerate replacement cycles as hospitality procurement teams discard non-compliant inventory. The EU F-Gas Regulation redirects R&D investment toward mechanical dispensing alternatives away from fluorinated propellants. The Rhine-Ruhr industrial corridor hosts specialized silicone overmolding facilities serving certified stainless-steel core bonding for commercial dishwashing durability.
China
Cost-optimized polymer pourer production dominates household volume exports through BPA-free formulation flexibility. GB standards for food-contact materials enforce testing protocols that align with FDA 21 CFR notification requirements for export-bound shipments. Guangdong Province mold fabrication for complex spring mechanisms remains concentrated, exposing lead-time risk to regional logistics disruptions.
France
European design heritage positioning supports premium decorative pourer exports to North American gift and specialty retail channels. ECHA enforcement of REACH substance restrictions elevates material traceability requirements for imported silicone components. The Auvergne-Rhône-Alpes region clusters precision metal finishing operations that supply brushed and polished hospitality specifications.
Australia
Small-batch spirits producers in the craft distillery channel lack dedicated accessory suppliers, creating white space for specialized pourer-cork combinations. The country's national food-contact regulator enforces compliance testing that mirrors FDA and EU frameworks for import substitution. Melbourne and Sydney metropolitan markets concentrate wine club subscription testing of pourer-plus-stopper retention kits.
Pop-Up Pourer Market Competitive Landscape
Global majors compete with regional champions across material certification tiers and distribution channel access. The supplier base stratifies between direct-to-consumer operators, foodservice supply chain anchors, and design-forward specialty retailers. Three archetypes dominate: premium hospitality specifiers, mass-market kitchenware distributors, and niche wine-accessory specialists. Portfolio diversification toward multi-material certified lines and backward integration into platinum-cured silicone sourcing represent the dominant competitive moves.
Within the premium hospitality specifier tier, OXO International Ltd. and Bormioli Rocco USA exemplify divergent geographic anchoring strategies. Tablecraft Products Company occupies a position as a North American foodservice supply chain anchor with broad SKU coverage. Prepara represents the niche wine-accessory specialist archetype through focused sub-category concentration.
| Leading Market Players |
|---|
| OXO International Ltd. |
| Tablecraft Products Company |
| Libbey Inc. |
| Bormioli Rocco USA |
| Prepara |
| Casabella |
| Emmeistar |
| Harold Import Co. |
| Enriching Lifes Ltd |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Germany's Rhine-Ruhr corridor and Guangdong's mold fabrication clusters anchor supply discipline, translating REACH certification bottlenecks and platinum-cured silicone volatility into tiered pricing power across hospitality procurement tiers.
Pricing Analysis
Warranty and batch-traceability documentation are bundled with REACH-certified silicone pourers while unbundled from standard polymer variants, creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA notification tier and dishwasher-cycle durability certification, with hospitality specifiers least sensitive and household e-commerce buyers most responsive to unit cost. Pricing pressure stems from semiconductor-linked silicone feedstock volatility, compressing mid-tier margins as distributors absorb input spikes to maintain shelf placement.
Supply Chain Analysis
California's SB 54 recycled-content mandates and Germany's REACH disclosure requirements are reshaping sourcing toward traceable European silicone and North American metal finishing. Raw material dependencies center on platinum-cured silicone from Germany's chemical corridor, stainless steel feedstock from Italian mills, and rare-earth magnetic components processed in China. Single-source vulnerability concentrates in Guangdong Province mold fabrication for spring mechanisms. Distribution runs through foodservice supply chain anchors with broad SKU coverage and direct-to-consumer wine club operators testing subscription bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platinum-cured silicone certification timelines stretching beyond typical product development cycles constrain qualified supplier capacity, propping pricing discipline across REACH-compliant tiers.
For Market Incumbents: Anticipate bartender purchasing collectives consolidating procurement authority in Texas and Florida by deepening backward integration into platinum-cured silicone sourcing and accelerating magnetic sealing R&D to differentiate from precision jigger substitution threats. Preempt California SB 54 compliance complexity by expanding metal pourer SKUs before shelf-access restrictions crystallize.
For New Entrants and Emerging Players: Australian craft distilleries lack dedicated accessory suppliers, presenting white space for specialized pourer-cork combinations targeting small-batch spirits producers. Wine club subscription operators testing retention kits offer the most penetrable direct-to-consumer channel, accessible through co-development partnerships with established kit assemblers rather than retail distribution buildout.
For Investors and Strategic Acquirers: Distressed-cycle entries favor certified-material specialists with captive silicone supply in Germany or Italy, where REACH enforcement has stranded non-compliant inventory at legacy distributors. The inflection signal to monitor is FDA notification review period compression, which would accelerate consolidation toward pre-qualified suppliers with established material traceability systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Platinum-Cured Silicone | Captive supply from Germany's chemical corridor insulates margin from semiconductor-demand price spikes. |
| Magnetic Sealing Mechanism R&D | Rare-earth component integration addresses upscale hotel minibar labor reduction specifications. |
| REACH Certification Pre-Qualification | Accelerated ECHA substance disclosure compliance captures replacement cycles in France and Germany. |
| Direct-to-Consumer Subscription Bundling | Wine club operator partnerships open recurring revenue outside traditional kitchenware distributor channels. |
| Metal Pourer SKU Expansion | California SB 54 recycled-content mandate avoidance preserves shelf access as polymer restrictions tighten. |
Research Methodology
Independent corroboration across hospitality procurement directors, silicone compounders, and foodservice distributor category managers underwrites the qualitative findings, cross-checked against FDA 21 CFR notification databases, ECHA REACH substance restriction updates, and customs trade flow records for platinum-cured silicone and stainless steel pourer shipments. Bottom-up facility capacity assessments and top-down channel revenue estimates were reconciled to anchor segmentation splits.
Rate-of-change decomposition across the analysis window modeled product type, material certification tier, end-use durability requirement, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted volume projections incorporating REACH replacement cycle acceleration, silicone feedstock price volatility bands, and bartender collective procurement consolidation patterns in metropolitan Texas and Florida markets.
Revisions become necessary when FDA notification review periods extend beyond product development cycles, when California SB 54 enforcement thresholds tighten, or when Guangdong logistics disruptions persist beyond seasonal patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
Drink Can Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Foamer Bottle Market