
 Plastic Bottles and Containers Market | 2026-2036
Plastic Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Bottles and Containers Market Outlook
The EU Green Deal is realigning virgin plastic demand toward post-consumer recycled content across European beverage supply chains. Amcor plc leverages its integrated recycling infrastructure to secure rPET feedstock at scale across multiple continents. Berry Global anchors North American food packaging through its network of regional blow-molding facilities. ALPLA Group dominates European pharmaceutical and cosmetics container production with specialized barrier technology.
Plastic bottles and containers comprise hollow-formed polymer vessels typically manufactured through extrusion blow molding, injection stretch blow molding, or thermoforming, with wall thicknesses engineered between 0.25 mm and 1.5 mm depending on barrier requirements and mechanical load specifications. PET Containers lead global volume due to their clarity, gas barrier properties, and established recycling infrastructure across major economies. Biodegradable Containers represent the fastest-expanding product category as brand owners face mounting pressure to eliminate fossil-derived packaging from premium personal care lines. The Food & Beverage end-user segment commands the largest share of polymer consumption, though Pharmaceuticals generates superior per-unit margins through stringent USP and EU pharmacopeia compliance requirements.
FDA enforces food-contact notification rules that determine which resin grades and additives qualify for beverage and food packaging in the United States, while EMA and national EU regulators impose migration limits through REACH and the Packaging and Packaging Waste Regulation. China's SAMR and GB standards govern plastic food container safety, creating a fragmented compliance landscape for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility schemes and chemical recycling certification protocols as these frameworks increasingly determine market access and cost structures.
Market Dynamics
EU Green Deal mandates are forcing beverage bottlers to reconfigure virgin plastic sourcing toward post-consumer recycled content, compressing traditional resin supply chains while elevating rPET infrastructure investments across European production networks.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds for beverage containers are redirecting capital toward rPET expansion in Germany, France, and Italy.
- Lightweighting technology:Pharmaceutical and personal care brands in India and Brazil are adopting thin-wall injection stretch blow molding to reduce polymer consumption per unit.
- Barrier co-injection systems:Oxygen and UV barrier layers are extending shelf life for sensitive nutraceuticals, opening premium positioning in North American functional beverage segments.
Market Restraints
- rPET feedstock scarcity:Collection infrastructure gaps in Eastern Europe and Southeast Asia constrain post-consumer flake availability, inflating spot prices for food-grade recycled resin.
- Propylene and ethylene volatility:Naphtha-linked virgin polymer costs swing with crude oil benchmarks, eroding margin predictability for commodity blow-molders serving mass-market water brands.
- Mechanical recycling limitations:Contamination and degradation cycles cap rPET inclusion rates at 30-50% for carbonated beverage bottles without chemical recycling intervention.
Strategic Opportunities
- Chemical recycling certification:Advanced recycling output qualifying for food-contact approval under EFSA and FDA frameworks commands premium offtake from multinational beverage conglomerates.
- Pharmaceutical serialization integration:Track-and-trace compliance mandates in the EU and US are creating demand for blow-molders with in-mold labeling and digital watermarking capabilities.
- Refill infrastructure partnerships:Personal care brands in Germany and the Netherlands are piloting concentrated product formats requiring durable, returnable PET containers with enhanced chemical resistance.
Industry Challenges
- Blow-molding technician shortage:Specialized expertise in multilayer parison programming and barrier validation is scarce across Midwestern US manufacturing clusters.
- Extended producer responsibility compliance:Fragmented national reporting systems in Europe require dedicated regulatory affairs capacity that mid-tier converters struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Bottles and Containers Market |
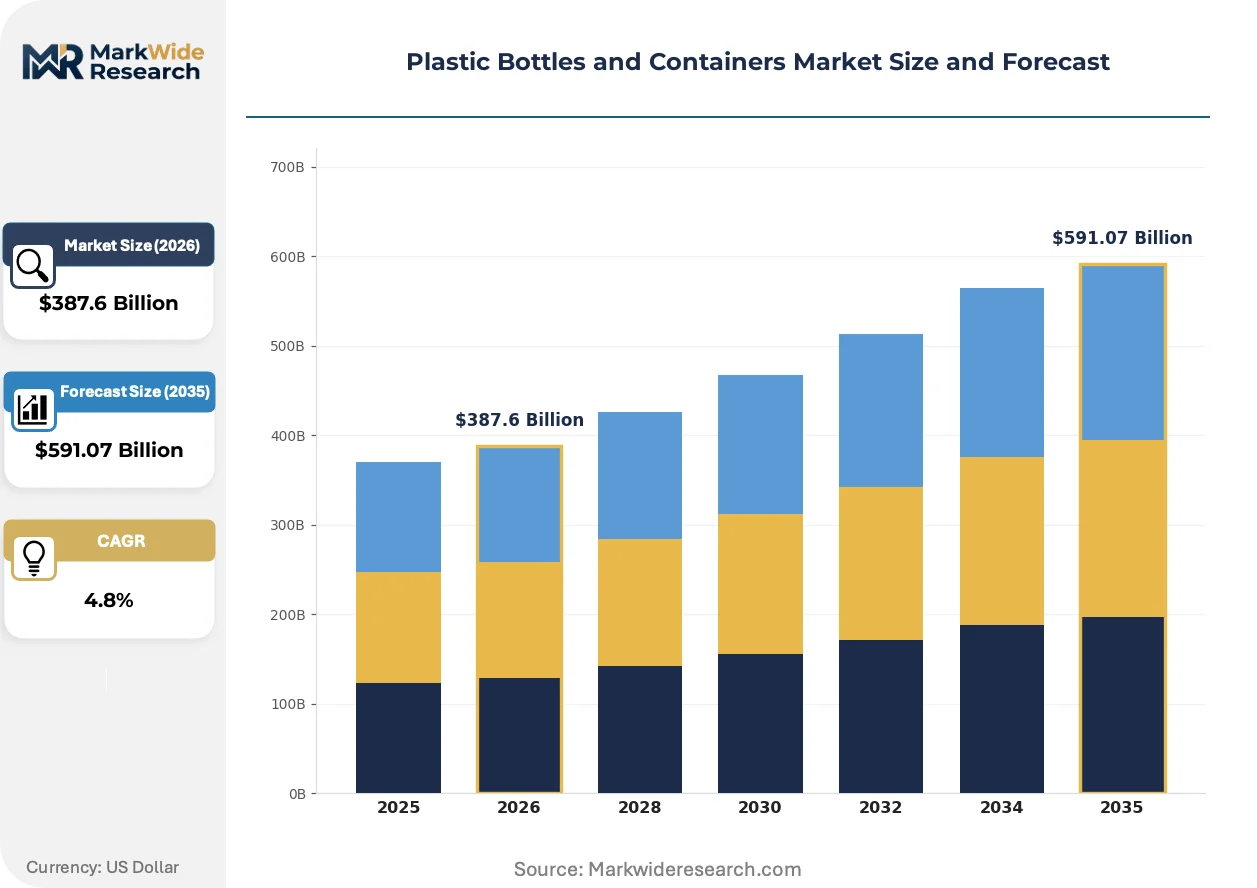
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recyclable Bottles, PET Containers, Multi-Layer Bottles, Biodegradable Containers End User: Food & Beverage, Personal Care, Household Chemicals, Pharmaceuticals Size: Small Bottles, Medium Containers, Large Bottles, Bulk Containers Closure Type: Screw Caps, Flip Tops, Snap-On Caps, Tamper-Evident Caps |
| Companies Covered | Amcor plc, Berry Global, ALPLA Group, Silgan Holdings, Graham Packaging, Plastipak Holdings, Gerresheimer AG, Huhtamaki, Alpha Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Bottles and Containers Market Strategic Shifts
Active and intelligent packaging integration is converging with mechanical recycling stream compatibility, forcing equipment suppliers and resin formulators to coordinate development roadmaps around dual performance criteria.
Mono-material barrier structures are consolidating multilayer bottle constructions into single-polymer formats compatible with existing PET recycling infrastructure. Beverage brands in Scandinavia and California are specifying these formats for premium water and juice lines. This consolidation is compressing demand for incompatible multilayer films that previously contaminated mechanical recycling streams.
REACH SVHC disclosure requirements are expanding compliance documentation burdens for additive packages and colorants used in cosmetic containers. ECHA's candidate list updates are triggering reformulation cycles among European compounders serving personal care brands. Pharmaceutical packaging converters are responding by pre-qualifying resin grades against both USP and evolving EU pharmacopeia standards to maintain dual-market eligibility.
Direct-to-retail e-commerce fulfillment is fragmenting traditional palletized distribution for personal care and specialty beverage containers. Amazon and regional grocery delivery platforms in the UK and South Korea are demanding right-sized secondary packaging with enhanced drop-test performance. This channel expansion is favoring blow-molders with agile format changeover capabilities and regional fulfillment proximity over centralized mass-production assets.
Plastic Bottles and Containers Market Segmentation
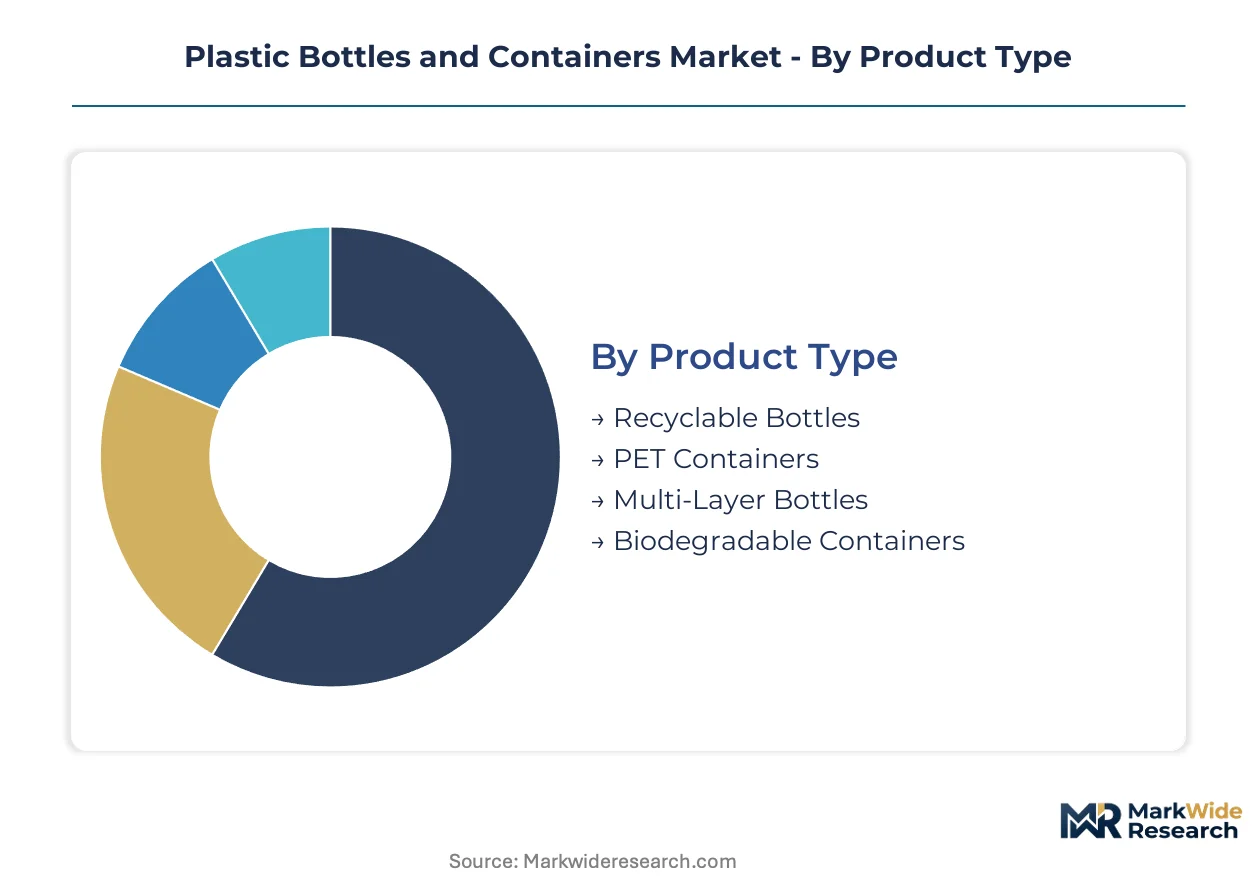
Segmentation in plastic bottles and containers reveals how resin selection, barrier engineering, and closure mechanics align with distinct regulatory and performance requirements across end-use applications. Buyers prioritize fundamentally different attributes: pharmaceutical converters demand USP-compliant traceability, while beverage brands optimize for recycling stream compatibility and lightweighting economics.
Product Type:
Buyers in this category differentiate primarily by recycling infrastructure maturity and regulatory approval pathways for food-contact or pharmaceutical applications.
- PET Containers:Injection stretch blow-molded vessels with intrinsic viscosity engineered between 0.72 and 0.82 dL/g deliver clarity and CO2 barrier performance for carbonated beverages. Demand concentrates in Germany and France where EU Green Deal mandates enforce minimum recycled content thresholds, forcing bottlers to secure rPET flake through long-term offtake agreements.
- Biodegradable Containers:PLA and PHA-based vessels degrade under industrial composting conditions per EN 13432 certification, though limited anaerobic digestion infrastructure constrains end-of-life pathways. Personal care brands in California and the Netherlands specify these for premium skincare lines where fossil-free positioning commands shelf price premiums.
- Recyclable Bottles:Mono-material HDPE and PP formats compatible with existing mechanical recycling streams serve mass-market water and dairy applications.
- Multi-Layer Bottles:EVOH or nylon barrier layers extend oxygen transmission resistance for sensitive nutraceuticals and functional beverages.
Volume sits with PET Containers; growth tilts toward Biodegradable Containers.
End User:
Margin structures diverge sharply across this category, with pharmaceutical and personal care applications capturing per-unit premiums that commodity food packaging cannot approach.
- Food & Beverage:Carbonated soft drink, bottled water, and ready-to-drink tea applications consume polymer volumes at scale, with lightweighting programs reducing average bottle weights from 21 grams to sub-15 gram formats. FDA food-contact notification requirements and EFSA migration limits govern resin additive packages, creating compliance friction for multinational suppliers.
- Pharmaceuticals:Blow-fill-seal and conventional blow-molded containers for oral solids and liquids must satisfy USP <661> and EU pharmacopeia extractables testing, with serialization mandates in the EU and US driving demand for in-mold labeling integration. Per-unit margins exceed commodity packaging by factors of three to five due to validation documentation and change-control rigor.
- Personal Care:Shampoo, conditioner, and skincare vessels prioritize aesthetic differentiation through custom colorants and surface finishes.
- Household Chemicals:Bleach, detergent, and disinfectant containers require chemical resistance against aggressive surfactants and oxidizers.
Revenue concentrates in Pharmaceuticals; volume expansion is steepest in Personal Care.
Size:
Distribution economics and retail channel requirements shape procurement patterns, with e-commerce fulfillment fragmenting traditional palletized logistics toward right-sized secondary packaging.
- Small Bottles:Sub-100ml formats for pharmaceuticals, travel-size personal care, and sample packaging employ thin-wall injection stretch blow molding with wall thicknesses below 0.4 mm. Amazon and UK grocery delivery platforms demand enhanced drop-test performance for direct-to-consumer shipment, favoring regional blow-molders with agile format changeover capabilities.
- Large Bottles:1-5 liter formats for household chemicals and value-oriented beverages concentrate production in Brazil and India where local resin supply and labor arbitrage support cost positioning.
- Medium Containers:100ml-1 liter formats dominate standard beverage and personal care applications.
- Bulk Containers:5-20 liter formats serve institutional food service and industrial chemical distribution.
Procurement clusters around Medium Containers; format innovation accelerates in Small Bottles.
Closure Type:
Tamper evidence and child-resistance mandates from FDA and EU regulators drive specification divergence, with pharmaceutical applications requiring functionality that commodity beverage closures cannot satisfy.
- Tamper-Evident Caps:Break-ring or shrink-band mechanisms provide visible evidence of prior opening, mandatory for over-the-counter pharmaceuticals and increasingly specified for premium beverages. India's CDSCO and Brazil's ANVISA enforce comparable requirements, creating harmonized specification opportunities for multinational closure suppliers.
- Screw Caps:Standard 28mm PCO finishes dominate carbonated and still beverage applications, with lightweighting programs reducing closure mass from 2.5 grams toward 1.8 gram targets.
- Flip Tops:Hinged dispensing closures concentrate in personal care and condiment applications where single-handed operation drives consumer preference.
- Snap-On Caps:Press-fit closures serve wet wipe canisters and certain dairy applications where resealability is secondary to manufacturing throughput.
Deployment is broadest for Screw Caps; specification intensity peaks with Tamper-Evident Caps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and the United States while consumption growth accelerates in India and Brazil. This geographic split creates trade flows of rPET flake and virgin resin across Atlantic and Pacific corridors. Regulatory divergence between EU Green Deal mandates and FDA food-contact rules shapes regional competitive positioning.
Germany
Beverage bottlers in Bavaria and North Rhine-Westphalia are retrofitting extrusion blow-molding lines to process 30-50% rPET content. The EU Packaging and Packaging Waste Regulation enforces mandatory recycled content thresholds that compress virgin resin demand. Cologne anchors pharmaceutical container production where Gerresheimer AG operates specialized barrier technology facilities for USP-compliant packaging.
United States
Midwestern manufacturing clusters around Ohio and Illinois serve mass-market water brands with lightweight PET formats. FDA food-contact notification rules determine which resin grades qualify for beverage applications, creating compliance friction for imported materials. Berry Global's regional blow-molding network dominates North American food packaging procurement.
India
Pharmaceutical and personal care brands in Maharashtra and Gujarat are adopting thin-wall injection stretch blow molding to reduce polymer consumption per unit. CDSCO mandates tamper-evident closures for over-the-counter medicines, harmonizing specification requirements with Brazil's ANVISA. Mumbai-Pune corridor concentrates demand for small-format containers serving direct-to-retail e-commerce channels.
Brazil
Local resin supply and labor arbitrage support cost positioning for 1-5 liter household chemical and value beverage formats. ANVISA enforces pharmaceutical serialization requirements that drive demand for in-mold labeling capabilities. São Paulo state anchors production networks serving Mercosur distribution.
China
SAMR and GB standards govern plastic food container safety, creating a fragmented compliance landscape for multinational suppliers. Yangtze River Delta manufacturing bases export mono-material barrier structures compatible with European recycling infrastructure. Shanghai-based converters are piloting chemical recycling certification protocols for food-contact approval.
Plastic Bottles and Containers Market Competitive Environment
The competitive structure tilts toward integrated converters with captive recycling infrastructure. Tier-one players command premium offtake through long-term rPET supply agreements with multinational beverage conglomerates. Three archetypes dominate: vertically integrated resin-to-container specialists, regional blow-molding networks, and pharmaceutical-grade barrier technology providers. Capacity expansion and chemical recycling certification partnerships constitute the dominant competitive moves.
Within the integrated converter tier, Amcor plc and Berry Global represent archetypal positions. ALPLA Group anchors European pharmaceutical and cosmetics specialization. These three entities exemplify how geographic footprint breadth and recycling infrastructure depth determine procurement eligibility under tightening EU and FDA frameworks.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| ALPLA Group |
| Silgan Holdings |
| Graham Packaging |
| Plastipak Holdings |
| Gerresheimer AG |
| Huhtamaki |
| Alpha Packaging |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up converters across the US Midwest and European heartland have consolidated fragmented blow-molding capacity, tightening pricing discipline while extending payment terms to resin suppliers. This ownership pattern concentrates supply-side leverage among three to five integrated players capable of enforcing long-term rPET offtake contracts that smaller competitors cannot match.
Pricing Analysis
Cost-down pressure on commodity beverage bottles accelerates because mass-market water brands in the United States and Germany are consolidating procurement volumes toward fewer approved suppliers. Three-tier pricing structure across premium barrier-enhanced, standard food-grade, and economy non-food formats separates pharmaceutical serialization-ready containers from basic dairy jugs. Certification tier under FDA food-contact notification rules and EU EFSA migration limits commands 15-25% premiums over uncertified alternatives. Brand owners in carbonated beverages exhibit highest price sensitivity, while pharmaceutical converters absorbing USP validation costs tolerate elevated per-unit pricing.
Supply Chain Analysis
Blow-molding technician shortages across Ohio, Illinois, and Bavarian manufacturing clusters constrain capacity expansion despite strong order backlogs. Resin supply concentrates in Germany, the United States, and China where naphtha-linked virgin polymer production and mechanical recycling infrastructure coexist. Feedstock dependencies on rPET flake, EVOH barrier resins, and high-IV PET chips expose converters to collection infrastructure gaps in Eastern Europe and Southeast Asia. Single-source vulnerability for food-grade recycled resin inflates spot pricing during quarterly demand spikes. Distribution runs through regional blow-molding facilities serving 300-500 kilometer radiuses to minimize freight costs on lightweight empty containers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a materials-transition phase as mono-material barrier structures displace incompatible multilayer constructions that previously contaminated mechanical recycling streams.
For Market Incumbents: Hedge virgin resin exposure by securing chemical recycling certification partnerships before EFSA and FDA food-contact approval pathways mature. Lock in 5-7 year rPET flake supply agreements with collection consortiums in Germany and California to defend margin position against feedstock scarcity. Accelerate in-mold labeling and digital watermarking capabilities to capture pharmaceutical serialization mandates from EU and US regulators. For New Entrants and Emerging Players: The mid-tier price-point gap between premium pharmaceutical barrier containers and economy beverage formats offers white-space entry for specialized nutraceutical packaging. Target thin-wall injection stretch blow molding for personal care brands in India and Brazil where lightweighting programs outpace incumbent converter capacity. Pursue refill infrastructure partnerships with concentrated product formats in the Netherlands and Germany requiring durable returnable PET with enhanced chemical resistance. For Investors and Strategic Acquirers: EFSA food-contact approval for chemically recycled output is the leading indicator that premium offtake pricing will sustain across European beverage supply chains. Focus acquisition screening on regional blow-molders with captive mechanical recycling assets and existing pharmaceutical USP validation documentation. Watch for CDSCO and ANVISA harmonization on tamper-evident closure mandates as the signal that Indian and Brazilian pharmaceutical packaging consolidation will accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Certification | EFSA and FDA food-contact approval unlocks premium offtake from Coca-Cola and PepsiCo supply chains. |
| rPET Supply Agreement | Long-term flake offtake with German collection consortiums secures feedstock against Eastern European infrastructure gaps. |
| In-Mold Labeling Integration | Serialization compliance for EU FMD and US DSCSA mandates captures pharmaceutical margin premiums. |
| Mono-Material Barrier Development | Scandinavian beverage brand specifications for premium water lines eliminate multilayer recycling contamination. |
| Regional Capacity Expansion | Maharashtra and Gujarat facilities serve Indian pharmaceutical and personal care lightweighting demand. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with blow-molding plant managers, resin procurement leads at multinational beverage bottlers, pharmaceutical packaging engineers, and retail category buyers validated demand assumptions. FDA food-contact notifications, EMA pharmaceutical packaging guidelines, and EU Packaging and Packaging Waste Regulation impact assessments provided compliance benchmarking. Bottom-up capacity modeling across extrusion and injection stretch blow-molding facilities triangulated against top-down polymer consumption estimates from national trade associations.
Reconciliation of production capacity databases with import-export customs flows established baseline volume estimates across the projection horizon. Segmentation modeling incorporated resin type, barrier technology tier, end-use application, and geographic regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand projections reflecting EU Green Deal recycled content mandates and lightweighting adoption curves. Industry-specific inputs included rPET collection infrastructure buildout schedules and pharmaceutical serialization compliance deadlines.
Underlying measurement precision varies by segment; PET container volumes carry tighter precision than emerging biodegradable formats where composting infrastructure data remains sparse. Forecasts reflect assumptions about mechanical recycling contamination rates and chemical recycling scale-up timelines. Material deviation in EFSA food-contact approval timelines or crude oil price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
Sugarcane Based PET Bottles Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
Plastic Battery Containers Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
United States Plastic Packaging Films Market