
 Middle East and Africa Food Sweetener Market | 2026-2036
Middle East and Africa Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Food Sweetener Market Foresight
Clean-label fermentation and enzymatic conversion is tilting formulation strategies across the Middle East and Africa sweetener supply base. Tate & Lyle PLC leverages its specialty ingredient portfolio to anchor premium positioning in Gulf beverage contracts. Cargill, Incorporated sustains regional grain-to-sweetener infrastructure that competes on bulk supply reliability. Ingredion specializes in texture-modified sweetener systems for bakery applications, occupying a technical niche that differentiates its offering from commodity suppliers.
Food sweeteners comprise caloric and non-caloric substances added to confer sweetness, encompassing carbohydrates such as sucrose and fructose, high-intensity compounds including aspartame, and plant-derived extracts like steviol glycosides, with functional parameters measured by relative sweetness intensity, thermal stability, and glycemic response index. These ingredients serve primarily to enhance palatability, control moisture, and manage energy content in processed foods and beverages. Sucrose retains volume leadership across Middle East and Africa due to entrenched cane supply chains and established confectionery demand, while stevia extracts capture accelerated growth through clean-label positioning in Gulf retail channels. Aspartame competes in diet beverage segments where cost-per-unit-sweetness advantages sustain formulation share despite persistent label scrutiny.
Saudi Food and Drug Authority standards and South African National Health Laboratory Service guidelines shape permissible additive thresholds and labeling declarations across the region's two largest economies. Egypt's food safety authority and UAE's Ministry of Industry and Advanced Technology enforce parallel compliance frameworks that raise reformulation costs for imported sweetener blends. Stakeholders must monitor divergent regulatory timelines between Gulf harmonization initiatives and sub-Saharan national standards when allocating R&D and registration budgets.
Market Dynamics
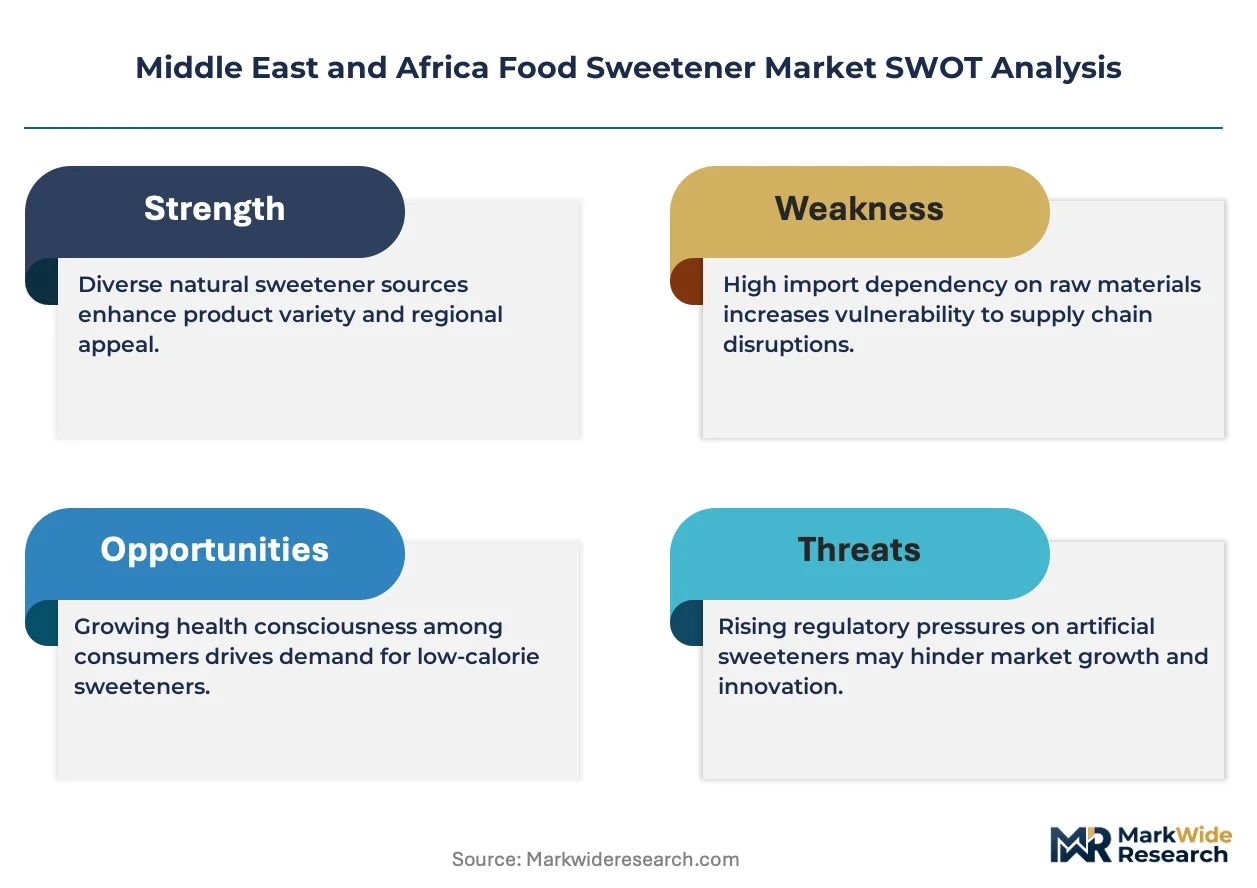
South Africa's sugar tax and Gulf state reformulation mandates are compressing traditional caloric sweetener volumes while accelerating enzymatic conversion investments across the regional supply base.
Growth Catalysts
- South African National Health Laboratory Service guidelines:These standards tighten permissible additive thresholds, forcing beverage manufacturers toward high-intensity alternatives and expanding addressable market for steviol glycoside suppliers.
- Urban food processing corridors:Nigeria's Lagos-Kano manufacturing belt and Egypt's Cairo-Alexandria packaged goods axis concentrate demand for bulk sweetener procurement at industrial scale.
- Fermentation-based enzymatic conversion:Clean-label bioprocessing methods reduce glycemic index credentials in finished products, aligning with Gulf retail channel clean-label positioning requirements.
Market Restraints
- Cane supply chain concentration:Sucrose volume leadership depends on entrenched Egyptian and Sudanese cane cultivation belts vulnerable to irrigation water access constraints.
- Reformulation cost escalation:Egypt's food safety authority and UAE's Ministry of Industry and Advanced Technology impose divergent compliance timelines that fragment R&D allocation across registration budgets.
- High-intensity sweetness ceiling:Aspartame's cost-per-unit-sweetness advantage confronts persistent label scrutiny that limits brand deployment in premium positioned Gulf retail channels.
Strategic Opportunities
- Ethiopia's underpenetrated beverage sector:Addis Ababa's emerging packaged goods manufacturing cluster lacks established sweetener supplier relationships, creating first-mover positioning for texture-modified systems.
- Direct-to-manufacturer digital procurement platforms:Industrial ingredient marketplaces bypass traditional distributor markups in Kenya's Nairobi-Mombasa food processing corridor.
- Gulf Cooperation Council harmonization initiatives:Pending Saudi Food and Drug Authority alignment with UAE standards promises consolidated registration pathways reducing multi-jurisdiction compliance overhead.
Industry Challenges
- Specialized fermentation technologist scarcity:Clean-label bioprocessing scale-up requires enzymatic conversion expertise concentrated in European and Asian technical centers, not regional labor pools.
- Dual certification timeline compression:Parallel Gulf state and sub-Saharan national standard approval processes extend product launch windows by 18-24 months against working capital constraints.
- Legacy moisture-control formulation integration:Texture-modified sweetener systems demand re-engineering of established bakery production lines originally configured for sucrose crystallization behavior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Food Sweetener Market |
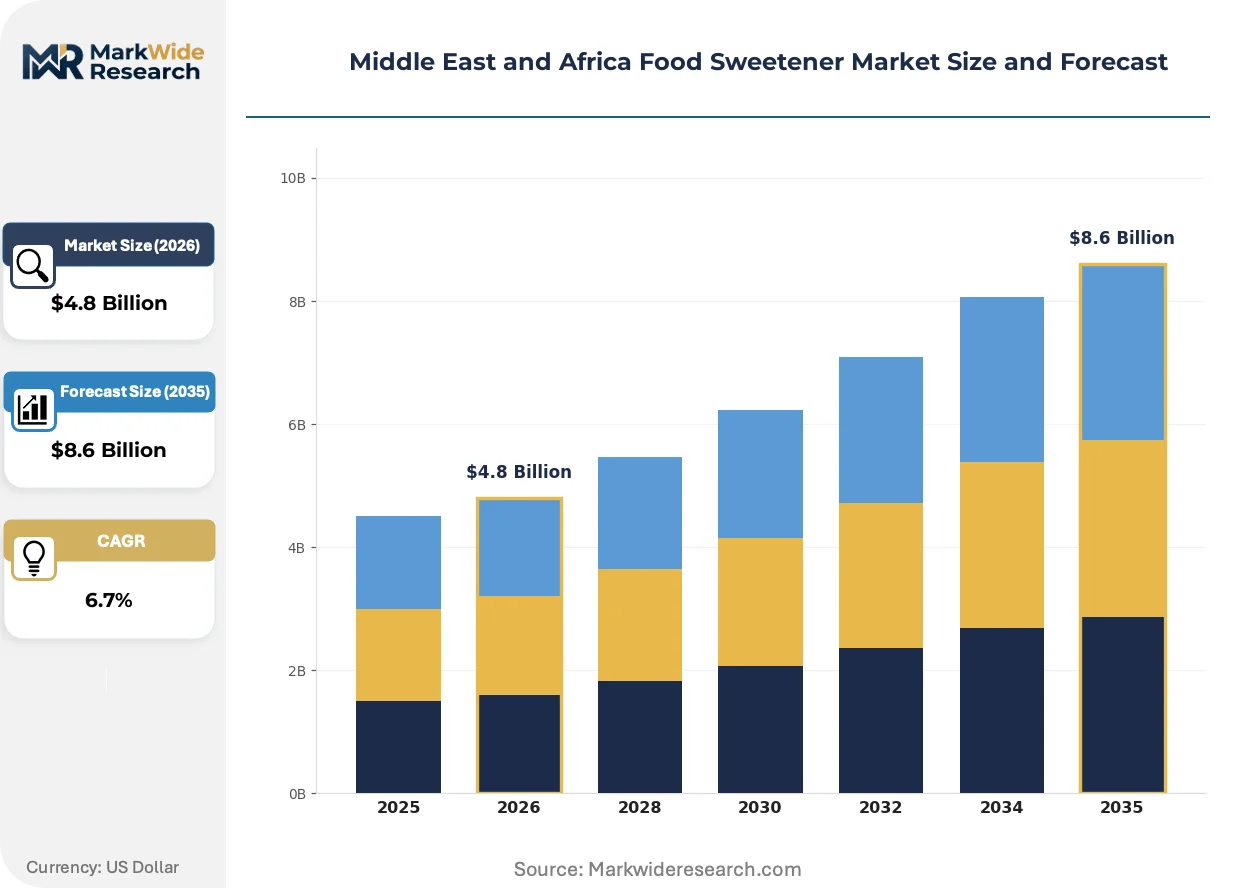
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Fructose, Aspartame, Stevia Application: Beverages, Bakery, Confectionery, Dairy Insulin Response: Low Glycemic, High Glycemic, Natural, Artificial End User: Food Industry, Beverage Industry, Home Cooking, Restaurants |
| Companies Covered | Tate & Lyle PLC, International Flavors & Fragrances Inc., Cargill, Incorporated, Roquette Frères, ADM, Ingredion, Kerry Group, Foodchem International Corporation, Ajinomoto Co., Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Food Sweetener Market Shifts & Advancements
Enzymatic bioconversion and clean-label extraction methods are collapsing cost differentials between synthetic and plant-derived high-intensity sweeteners across Gulf beverage manufacturing.
Steviol glycoside extraction through fermentation-based bioprocessing is collapsing the traditional cost premium that separated plant-derived from synthetic high-intensity alternatives. Saudi beverage manufacturers are adopting these systems at accelerated pace to meet Saudi Food and Drug Authority clean-label thresholds. The technology is collapsing formulation cost structures that previously locked Gulf producers into aspartame-dependent diet product lines.
South Africa's sugar tax regulations and Egypt's evolving food safety authority standards are tightening permissible caloric sweetener thresholds in processed foods. Industrial consequence includes forced reformulation of established confectionery and bakery product lines serving North African export markets. Egypt's packaged goods sector is responding through accelerated stevia extract qualification programs to maintain Gulf Cooperation Council market access.
Beverage procurement in the Gulf is consolidating toward long-term supply contracts with integrated ingredient systems providers rather than commodity spot purchasing. Industrial buyers in Dubai's Jebel Ali free zone are displacing traditional distributor relationships with direct technical partnership models. This pattern is most visible in UAE's functional beverage segment where texture-modified sweetener systems require co-development with formulation laboratories.
Middle East and Africa Food Sweetener Market Segmentation
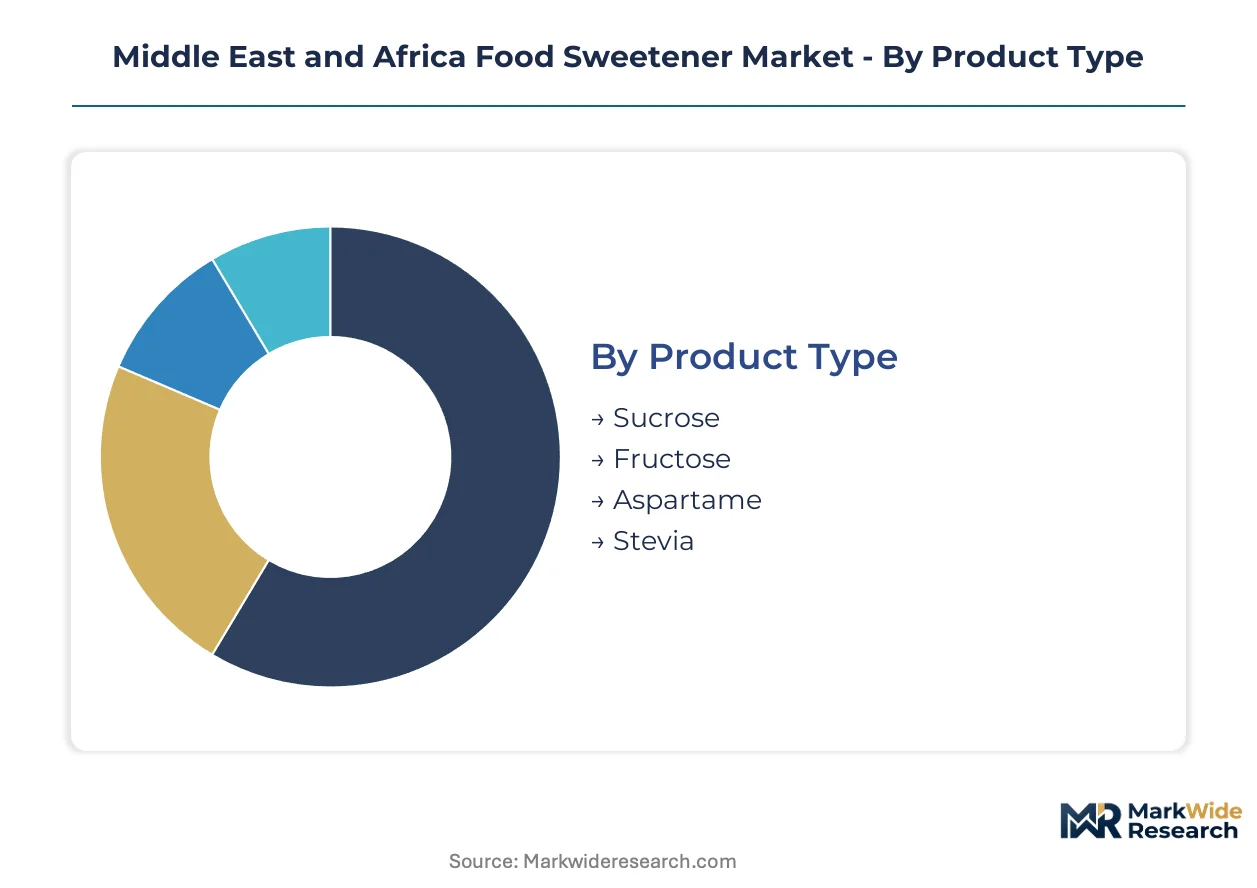
Segmentation in the Middle East and Africa food sweetener market reveals how formulation requirements diverge across regulatory environments and end-use specifications. Each dimension carries distinct service intensity profiles that shape supplier relationships and procurement patterns.
Product Type:
After-sales technical support intensity varies sharply across sweetener categories, with enzymatic and fermentation-derived products demanding sustained formulation assistance.
- Sucrose:Crystalline sucrose from Egyptian and Sudanese cane belts retains entrenched volume leadership through established moisture-control functionality in confectionery applications. Saudi beverage manufacturers maintain long-term supply contracts with integrated cane processors serving Gulf retail channels, though irrigation water access constraints threaten supply reliability.
- Stevia:Steviol glycoside extracts from fermentation-based bioprocessing are collapsing cost premiums against synthetic alternatives while meeting Saudi Food and Drug Authority clean-label thresholds. UAE functional beverage producers are displacing traditional distributor relationships with direct technical partnerships for texture-modified stevia systems.
- Fructose:High-fructose syrup systems serve North African bakery corridors where moisture retention specifications differ from Gulf state requirements.
- Aspartame:Synthetic high-intensity compound maintains diet beverage share through cost-per-unit-sweetness advantages despite persistent label scrutiny limiting premium Gulf deployment.
Sucrose holds the largest share; momentum sits with stevia extracts.
Application:
Application-driven segmentation tracks how reformulation mandates reshape procurement concentration across manufacturing corridors.
- Beverages:Gulf Cooperation Council beverage manufacturers are expanding reformulated product lines to meet consumer preference shifts, with Jebel Ali free zone buyers consolidating toward long-term supply contracts with integrated ingredient systems providers.
- Bakery:Texture-modified sweetener systems demand re-engineering of established production lines originally configured for sucrose crystallization behavior, creating technical partnership opportunities for specialty ingredient suppliers.
- Confectionery:Egypt's packaged goods sector accelerates stevia extract qualification programs to maintain Gulf market access amid tightening caloric thresholds.
- Dairy:South Africa's sugar tax regulations force reformulation of flavored dairy products toward high-intensity alternatives qualifying under National Health Laboratory Service guidelines.
Beverages command procurement scale; bakery applications are climbing the fastest as texture-modified systems penetrate industrial accounts.
Insulin Response:
Insulin response classification determines regulatory pathway complexity and label claim permissibility across divergent national standards.
- Low Glycemic:Enzymatic conversion technologies reduce glycemic index credentials in finished products, aligning with Gulf retail channel positioning requirements and South African sugar tax compliance.
- Natural:Plant-derived extracts capture accelerated growth through clean-label positioning, though dual certification timelines between Gulf harmonization initiatives and sub-Saharan standards extend launch windows.
- High Glycemic:Traditional caloric sweeteners face compressed volumes from reformulation mandates while maintaining cost advantages in price-sensitive North African markets.
- Artificial:Synthetic compounds confront persistent label scrutiny that limits brand deployment in premium positioned Gulf retail channels despite formulation cost efficiency.
Low glycemic options anchor regulatory compliance investment; natural category claims are expanding most quickly through fermentation cost reductions.
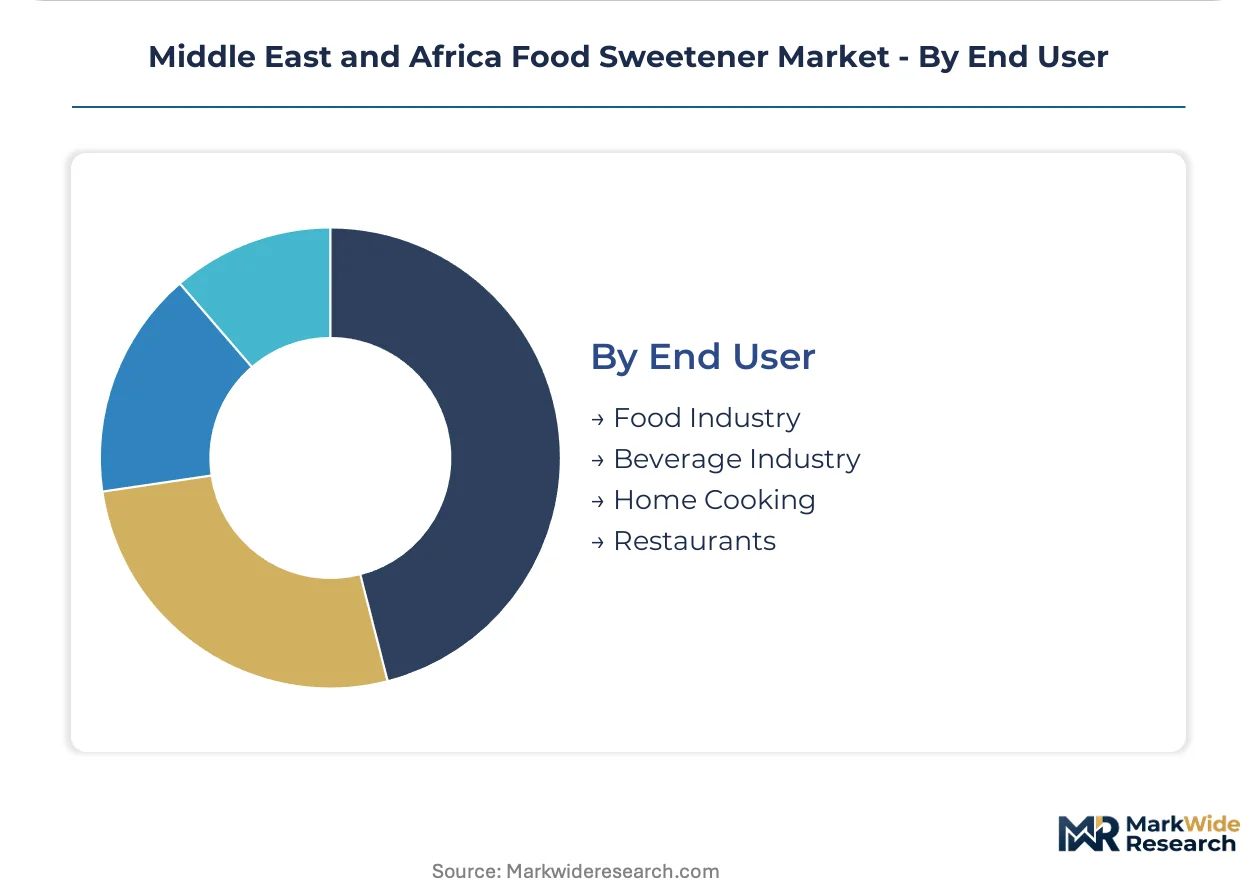
End User:
End user segmentation reveals divergent procurement sophistication between industrial scale buyers and fragmented food service accounts.
- Food Industry:Nigeria's Lagos-Kano manufacturing belt concentrates demand for bulk sweetener procurement at industrial scale, with direct-to-manufacturer digital platforms bypassing traditional distributor markups.
- Beverage Industry:Integrated ingredient systems providers capture long-term technical partnerships through co-development of texture-modified formulations requiring laboratory collaboration.
- Restaurants:Food service procurement remains fragmented across independent operators with limited formulation expertise, creating distributor margin retention.
- Home Cooking:Retail channel penetration varies sharply between Gulf supermarket consolidation and sub-Saharan informal market structures.
Food industry procurement dominates volume; beverage industry accounts show the steepest expansion trajectory through technical partnership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in the Gulf Cooperation Council dominate procurement scale, while Nigerian and Egyptian manufacturing corridors anchor sub-Saharan volume concentration. Divergent regulatory timelines between Saudi Food and Drug Authority harmonization initiatives and South African National Health Laboratory Service standards fragment supplier registration strategies.
Saudi Arabia
Beverage manufacturers in Riyadh and Jeddah are accelerating reformulation programs to meet Saudi Food and Drug Authority clean-label thresholds. The authority's tightening additive declarations are displacing traditional distributor relationships with direct technical partnerships. Jeddah's industrial corridor concentrates integrated ingredient systems procurement for functional beverage co-development.
United Arab Emirates
Dubai's Jebel Ali free zone buyers are consolidating procurement toward long-term supply contracts with laboratory-capable suppliers. MOHAP standards enforce parallel compliance frameworks that raise reformulation costs for imported sweetener blends. The emirate's functional beverage segment leads Gulf adoption of texture-modified stevia systems requiring formulation collaboration.
South Africa
National Health Laboratory Service guidelines are compressing traditional caloric sweetener volumes in flavored dairy and confectionery applications. The country's sugar tax regulations force industrial-scale reformulation toward high-intensity alternatives. Cape Town's beverage manufacturing cluster is qualifying steviol glycoside suppliers for export market compliance.
Egypt
The country's food safety authority is evolving standards that tighten permissible caloric thresholds in processed foods serving North African export markets. Cairo-Alexandria packaged goods manufacturers are accelerating stevia extract qualification programs to maintain Gulf Cooperation Council market access. Egypt's cane cultivation belt retains entrenched sucrose supply relationships despite irrigation water access constraints.
Nigeria
Lagos-Kano manufacturing belt demand concentrates bulk sweetener procurement at industrial scale for urban food processing corridors. Direct-to-manufacturer digital procurement platforms are bypassing traditional distributor markups in the Nairobi-Mombasa corridor. Local formulation expertise scarcity limits clean-label bioprocessing adoption despite retail channel preference shifts.
Middle East and Africa Food Sweetener Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent service intensity profiles. The supplier base organizes around three strategic archetypes: integrated grain processors with captive supply infrastructure, specialty ingredient laboratories with formulation partnership capabilities, and commodity distributors with regional logistics networks. Competitive moves concentrate on technical co-development contracts and registration pathway consolidation across multi-jurisdiction compliance frameworks.
Within the specialty ingredient tier, Tate & Lyle PLC and Ingredion occupy positions anchored by texture-modified system capabilities. Cargill, Incorporated represents the integrated processor archetype with regional grain-to-sweetener infrastructure. These three entities exemplify the competitive tension between formulation-technical differentiation and bulk supply reliability that shapes procurement decisions in Gulf beverage manufacturing.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| International Flavors & Fragrances Inc. |
| Cargill, Incorporated |
| Roquette Frères |
| ADM |
| Ingredion |
| Kerry Group |
| Foodchem International Corporation |
| Ajinomoto Co., Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in Egyptian cane processing facilities drives Gulf buyers toward long-term contract structures with indexed pricing clauses, compressing spot market liquidity and elevating supplier bargaining power across reformulation-driven procurement cycles.
Pricing Analysis
Cost-plus contracts with sucrose indexation dominate bulk procurement between Egyptian cane processors and Saudi beverage manufacturers, embedding raw material volatility into buyer cost structures. Price differentiation rests on fermentation-derived certification tiers and Gulf Cooperation Council registration status, with clean-label steviol glycosides commanding premium positioning over synthetic alternatives. Pricing pressure intensifies in standard-grade sucrose segments as South African sugar tax regulations redirect volume toward high-intensity alternatives. Industrial-scale food manufacturers exhibit lowest price sensitivity, while fragmented food service operators retain distributor markups.
Supply Chain Analysis
Tariff exposure between Sudan and Egypt dominates regional supply chain risk calculations for crystalline sucrose procurement. Raw material flows concentrate in Egyptian and Sudanese cane cultivation belts, with fermentation feedstocks drawing from South African grain corridors and UAE refined sugar re-exports. Distribution runs through Jebel Ali free zone consolidation hubs serving Gulf beverage manufacturers, with Lagos-Kano and Cairo-Alexandria corridors anchoring sub-Saharan bulk movements. Single-source vulnerability in enzymatic conversion technology licensing amplifies reformulation timeline risk for stevia extract suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa food sweetener market functions as a service-attach opportunity where formulation technical support contracts expand faster than commodity ingredient volumes, rewarding laboratory-capable suppliers with recurring revenue streams.
For Market Incumbents: Harden Gulf Cooperation Council registration portfolios against pending Saudi Food and Drug Authority harmonization timelines, consolidating multi-jurisdiction compliance overhead into unified technical dossiers. Deepen backward integration into fermentation capacity within UAE free zones to capture texture-modified system margins threatened by European ingredient laboratories. Prioritize captive steviol glycoside extraction facilities over spot market procurement. For New Entrants and Emerging Players: Ethiopia's underpenetrated beverage sector offers first-mover positioning for integrated ingredient systems providers lacking established distributor relationships in Addis Ababa's emerging packaged goods cluster. Target direct-to-manufacturer digital procurement platforms in Kenya's Nairobi-Mombasa corridor to bypass traditional markup structures. Deploy technical partnership models emphasizing co-development laboratory capabilities over commodity spot supply. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty ingredient laboratories with formulation partnership capabilities, generating multi-year technical service contracts alongside ingredient supply. Long-term viability across the analysis window favors acquisition targets with Saudi Food and Drug Authority registration pathways and UAE Ministry of Industry and Advanced Technology compliance infrastructure. Monitor Gulf harmonization initiative implementation velocity as inflection signal for registration cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Jebel Ali free zone buyers consolidate procurement toward laboratory-capable partners reducing distributor dependence. |
| Backward Integration | Fermentation capacity addition in UAE free zones captures margins from European enzymatic conversion technology licensors. |
| Geographic Expansion | Addis Ababa manufacturing cluster penetration exploits absence of established sweetener supplier relationships. |
| Regulatory Approval Pathway | Saudi Food and Drug Authority registration consolidation reduces multi-jurisdiction compliance overhead for reformulation timelines. |
| Strategic Partnership | Technical co-development contracts with Dubai functional beverage producers embed recurring formulation service revenue. |
Research Methodology
Initial hypotheses were tested against primary input from beverage formulation directors, food safety authority regulatory leads, cane processing plant managers, and industrial procurement officers at packaged goods manufacturers, then refined through secondary validation against Saudi Food and Drug Authority filings, Egyptian customs trade data, South African National Health Laboratory Service guideline publications, and Gulf Cooperation Council harmonization initiative documentation. Bottom-up volume estimates from individual manufacturing corridor capacity assessments were triangulated against top-down market sizing derived from import flow analysis.
Demand-supply-balance modeling across the projection horizon incorporated product type segmentation by enzymatic versus extraction-derived origin, application-driven procurement concentration in beverage versus bakery end-uses, and insulin response classification by glycemic index tier. CAGRs were derived from regression analysis of historical volume movements adjusted for regulatory intervention effects, with forecast inputs including irrigation water access constraints on Egyptian cane supply and fermentation technology licensing availability for steviol glycoside production.
Practitioners should monitor Gulf harmonization initiative implementation delays and South African sugar tax threshold adjustments for early signals of reformulation timeline compression. Forecasts embed assumptions regarding regulatory pathway convergence and bioprocessing technology transfer rates that could shift with European supplier licensing decisions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Global Starch Sweetener Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Sugar Substitutes Market
Sweeteners
Allulose Market
Sweeteners
Europe Stevia Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Polyol Sweeteners Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Aspartame Market
Sweeteners
Global Alternative Sweeteners Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
Cassava Syrup Market
Sweeteners
Polyphenol Sweetener Market