
 Aspartame Market | 2026-2036
Aspartame Market Size, Share, and Industry Trends Forecast 2026-2036
Aspartame Market Analysis
Single-serve sachet and stick-pack bundling is realigning how foodservice buyers procure tabletop sweeteners across institutional channels. Ajinomoto Group leverages its integrated fermentation infrastructure to sustain cost leadership in bulk powder supply. NutraSweet Company anchors its competitive stance through specialized pharmaceutical-grade certifications that command premium positioning. Niutang Chemical Ltd dominates volume supply to mid-market beverage co-packers across Asia through manufacturing scale advantages.
Aspartame constitutes a dipeptide methyl ester composed of L-aspartic acid and L-phenylalanine, synthesized via enzymatic coupling and chemical esterification to achieve roughly 200 times the sweetness intensity of sucrose at comparable usage levels. The molecule functions primarily as a caloric reduction agent in formulated foods and beverages where thermal stability below 86°C permits incorporation into dry mixes and cold-process liquids. Beverage applications lead segment value due to concentrated demand from carbonated soft drink and ready-to-drink tea formulators seeking label-friendly sugar reduction. Pharmaceutical applications represent the fastest-expanding category as tablet binders and excipient-grade sweetener specifications tighten. Powder form commands the largest volume share while liquid concentrate formats gain traction in automated beverage production lines.
FDA food additive regulations and EFSA's systematic re-evaluation of sweetener acceptable daily intakes shape product formulation thresholds and labeling requirements across major supply corridors. China's SAMR implements GB standards for aspartame purity and maximum usage levels that directly determine export eligibility for domestic manufacturers. India's FSSAI maintains distinct additive approval schedules that create separate compliance pathways for regional market entry. Stakeholders must monitor pending regulatory classification shifts that could restructure permissible application categories and reformulation timelines.
Market Dynamics
Reformulation mandates across beverage portfolios are compressing procurement cycles for high-intensity sweeteners as manufacturers race to meet sugar-reduction targets ahead of labeling deadline pressures.
Growth Catalysts
- EFSA Re-evaluation Protocols:Systematic safety reviews of artificial sweetener acceptable daily intakes are prompting manufacturers to secure aspartame supply contracts ahead of potential classification adjustments.
- China Beverage Production:Domestic carbonated soft drink and ready-to-drink tea formulators are expanding aspartame offtake to serve label-conscious urban consumers.
- Enzymatic Coupling Efficiency:Advances in biocatalytic synthesis routes are lowering fermentation-derived phenylalanine input requirements and tightening cost structures for bulk powder producers.
Market Restraints
- Phenylalanine Feedstock Volatility:Amino acid supply concentration among specialized fermentation houses creates input cost exposure during agricultural commodity fluctuations.
- Thermal Degradation Ceiling:The molecule's instability above 86°C restricts incorporation into heat-processed baked goods and hot-fill beverage applications.
- Stevia-Monk Fruit Substitution:Plant-derived high-intensity alternatives are capturing share in premium beverage segments where clean-label positioning commands price premiums.
Strategic Opportunities
- Pharmaceutical Excipient Specifications:Tablet binder and orally disintegrating formulation applications present untapped volume potential as pharmacopeial standards tighten.
- India FSSAI Additive Pathways:Distinct approval schedules for food additive categories create first-mover positioning for suppliers establishing local technical dossiers.
- Liquid Concentrate Automation:Automated beverage production lines favor pumpable sweetener formats that reduce handling labor and dosing variability.
Industry Challenges
- Cross-Regulatory Dossier Management:Simultaneous compliance with FDA food additive regulations, EFSA scientific opinions, and China's GB standards strains technical affairs staffing.
- Batch-to-Batch Purity Certification:Pharmaceutical-grade specifications require dedicated analytical validation protocols that extend quality control timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aspartame Market |
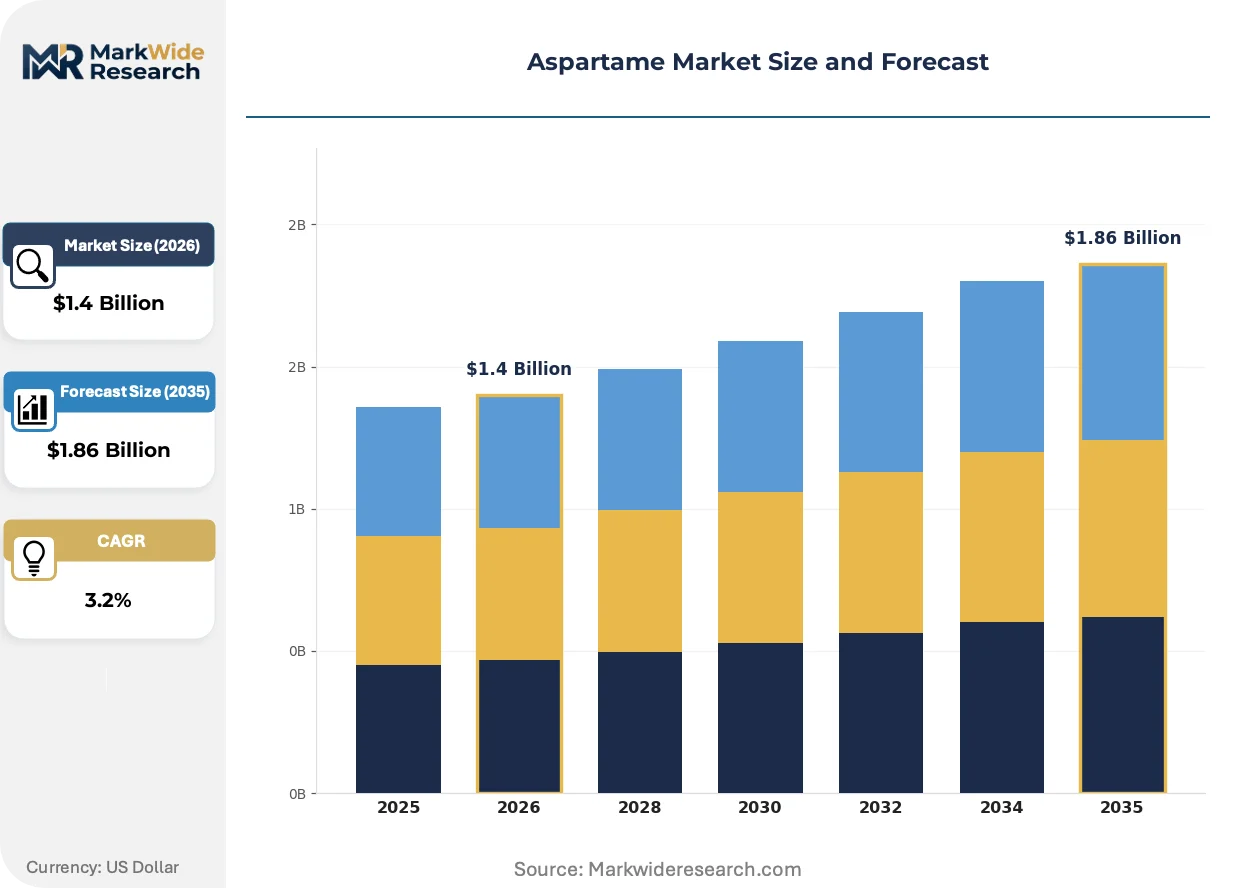
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $1.86 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Sweeteners, Beverages, Dairy Products, Bakery Items Form: Powder, Liquid, Granule, Tablet End User: Food & Beverage Industry, Healthcare Sector, Retail Consumers, Pharmaceutical Applications Application: Dietary Supplements, Sugar Substitutes, Confectionery Products, Meal Replacement |
| Companies Covered | Ajinomoto Group, NutraSweet Company, Hermes Sweeteners Ltd, Nantong Changhai Food Additive Co. Ltd, Foodchem International Corporation, HYET Sweet, Niutang Chemical Ltd, Vitasweet Co. Ltd, Changmao Biochemical Engineering Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aspartame Market Emerging Trajectories
Continuous processing technologies and regulatory science advances are compressing the gap between laboratory-scale synthesis and commercial-grade supply assurance.
Enzymatic biocatalysis platforms are rewriting production economics for aspartame manufacturers. Ajinomoto Group and specialized fermentation houses have deployed engineered transaminase systems that reduce phenylalanine precursor consumption by streamlining the coupling reaction. Beverage co-packers across Asia-Pacific are securing supply from these retrofitted facilities. The technology is rewriting cost curves for mid-market powder grades that previously relied on conventional chemical esterification routes.
EFSA's systematic re-evaluation of sweetener acceptable daily intakes is forcing portfolio diversification among formulators. The regulatory body has accelerated its scientific opinion timeline for dipeptide-based high-intensity sweeteners. Carbonated soft drink manufacturers in Europe are hedging exposure by qualifying multiple high-intensity alternatives in parallel formulation pipelines.
Foodservice procurement is consolidating around single-serve stick-pack formats that reduce tabletop waste and simplify inventory management. Institutional buyers in healthcare and corporate catering channels are displacing bulk canister arrangements with pre-portioned sachet supply contracts. China and Southeast Asian markets exhibit the fastest channel rotation toward bundled portion-controlled packaging.
Aspartame Market Segmentation
Segmentation in aspartame markets reveals how regulatory thresholds and thermal stability constraints reshape procurement patterns across formulation categories. Manufacturers align product specifications with end-use thermal profiles and pharmacopeial certification tiers to secure channel placement.
Product Type:
Certification burdens vary sharply across product type segments, with pharmaceutical and infant-adjacent applications triggering FDA food additive petitions and EFSA novel food dossiers that tabletop sweeteners bypass entirely.
- Beverages:Cold-process liquid formulations dominate procurement volumes, with carbonated soft drink manufacturers specifying USP-grade purity to meet FDA food additive regulations for high-volume production. China's carbonated drink producers anchor regional demand as domestic reformulation accelerates.
- Tabletop Sweeteners:Single-serve sachet and stick-pack formats concentrate foodservice procurement, with institutional buyers in healthcare and corporate channels displacing bulk canister arrangements. SAMR's GB standards for purity directly determine export eligibility for Chinese manufacturers supplying this segment.
- Dairy Products:Fermented dairy applications require cold-incorporation protocols due to thermal degradation constraints below pasteurization thresholds.
- Bakery Items:Heat-processed applications face incorporation ceilings at 86°C, restricting aspartame to post-bake surface treatments and cold-fill icings.
Beverages sits at the top of the volume ranking, with pharmaceutical applications climbing the fastest as tablet binder specifications tighten.
Form:
Cost tiers stratify sharply across physical forms, with liquid concentrates commanding automation-linked premiums while powder grades compete on fermentation input efficiency.
- Powder:Bulk powder supply dominates volume economics, with Ajinomoto Group's integrated fermentation infrastructure sustaining cost leadership through enzymatic coupling efficiency that reduces phenylalanine precursor consumption.
- Liquid:Pumpable concentrates gain traction in automated beverage production lines across Asia-Pacific co-packing facilities, reducing handling labor and dosing variability for high-throughput carbonated soft drink operations.
- Granule:Free-flowing granule formats serve tabletop blending applications where uniform dispersion in dry mixes matters.
- Tablet:Direct-compression tablet grades require dedicated analytical validation protocols that extend quality control timelines for pharmaceutical excipient specifications.
Powder retains the dominant volume position, with liquid concentrates expanding most quickly as production line automation spreads.
End User:
Application-specific purity tiers separate end user segments, with pharmaceutical and healthcare procurement mandating USP-NF and EP pharmacopeial certifications that food-grade buyers rarely require.
- Food & Beverage Industry:Beverage co-packers across China and Southeast Asia drive bulk powder offtake, with reformulation mandates compressing procurement cycles as manufacturers race to meet sugar-reduction targets ahead of labeling deadlines.
- Pharmaceutical Applications:Tablet binder and orally disintegrating formulation specifications present steepest expansion trajectory as pharmacopeial standards tighten, with excipient-grade sweeteners requiring batch-to-batch purity certification.
- Healthcare Sector:Institutional procurement in diabetes management and weight-control protocols favors single-serve portion control.
- Retail Consumers:Direct-to-consumer tabletop sweetener purchases concentrate in urban China's label-conscious demographic segments.
Food & Beverage Industry commands the volume base, with pharmaceutical applications gaining share fastest as excipient specifications proliferate.
Application:
Customer type and channel concentration differentiate application segments, with institutional healthcare procurement favoring bundled formats while retail sugar substitutes compete on shelf-stable convenience.
- Sugar Substitutes:Direct sugar replacement in home and foodservice channels concentrates demand in China's domestic sweetener consumption growth, with urban consumers driving tabletop sweetener rotation toward portion-controlled packaging.
- Dietary Supplements:Powder and tablet formats serve sports nutrition and weight-management formulations where caloric reduction aligns with protein-fortified positioning.
- Confectionery Products:Cold-process candy and chewing gum applications leverage aspartame's heat-limited stability for sustained-release sweetness.
- Meal Replacement:Ready-to-drink and powdered shake formulations incorporate aspartame for flavor masking in vitamin-fortified bases.
Sugar Substitutes holds the volume lead, with dietary supplements expanding most quickly as sports nutrition formulation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ajinomoto Group pioneered industrial-scale aspartame production in Japan during the 1980s, establishing fermentation-based synthesis protocols that subsequently diffused to Chinese and European manufacturing bases. This historical lineage shapes contemporary supply geography.
China
Domestic carbonated soft drink and ready-to-drink tea formulators drive aspartame offtake as urban consumers prioritize label-conscious sugar reduction. SAMR's GB standards for purity and maximum usage levels directly determine export eligibility for manufacturers serving foodservice and tabletop segments. Manufacturing clusters in Jiangsu and Zhejiang provinces host fermentation facilities supplying mid-market beverage co-packers across Asia-Pacific.
United States
FDA food additive regulations govern high-volume beverage applications, with carbonated soft drink manufacturers specifying USP-grade purity for cold-process liquid formulations. The agency's ongoing safety review protocols create compliance complexity as manufacturers secure supply contracts ahead of potential classification adjustments. Production infrastructure concentrates in Midwestern fermentation corridors serving North American beverage portfolios.
Germany
EFSA's systematic re-evaluation of sweetener acceptable daily intakes shapes formulation thresholds across European beverage and pharmaceutical applications. German pharmaceutical excipient manufacturers leverage tightening pharmacopeial standards to capture premium positioning in tablet binder specifications. Industrial sweetener processing facilities in North Rhine-Westphalia serve continental reformulation mandates.
India
FSSAI maintains distinct additive approval schedules that create separate compliance pathways for regional market entry, with domestic beverage formulators accelerating sugar-reduction timelines ahead of labeling deadlines. Maharashtra-based food additive distributors are establishing technical dossiers to secure first-mover positioning. Mumbai-Pune industrial corridors concentrate import handling and secondary formulation activities.
Japan
METI oversees industrial fermentation infrastructure where Ajinomoto Group's integrated production systems sustain cost leadership through enzymatic coupling efficiency. Domestic pharmaceutical manufacturers specify excipient-grade sweeteners for orally disintegrating tablet formulations. Kanto region facilities anchor supply security for Asia-Pacific pharmaceutical and beverage channels.
Aspartame Market Vendor Landscape
The competitive structure tilts toward fermentation-integrated specialists commanding cost advantages through backward control over amino acid precursors. Tiered positioning separates pharmaceutical-grade certifiers from commodity powder suppliers. Three archetypes dominate: integrated fermentation houses with captive phenylalanine supply, pharmaceutical-grade specialists capturing premium excipient positioning, and volume-focused chemical processors serving mid-market beverage co-packers. Capacity expansion and enzymatic technology licensing represent the dominant competitive moves as producers retrofit facilities for biocatalytic efficiency.
Within the integrated fermentation tier, Ajinomoto Group exemplifies cost leadership through enzymatic coupling infrastructure that reduces precursor consumption. NutraSweet Company occupies a position among pharmaceutical-grade specialists leveraging certification premiums. Niutang Chemical Ltd anchors the volume-driven segment supplying Asia-Pacific beverage co-packers through manufacturing scale advantages.
| Leading Market Players |
|---|
| Ajinomoto Group |
| NutraSweet Company |
| Hermes Sweeteners Ltd |
| Nantong Changhai Food Additive Co. Ltd |
| Foodchem International Corporation |
| HYET Sweet |
| Niutang Chemical Ltd |
| Vitasweet Co. Ltd |
| Changmao Biochemical Engineering Company Limited |
| Others |
Supply Flow & Price Mechanics
Mid-market beverage co-packers across Asia-Pacific anchor procurement volumes and enforce contract-based long-term offtake structures that compress spot market premiums. These buyers leverage manufacturing scale advantages to secure volume-tier discounts while tolerating longer qualification timelines for pharmaceutical-grade alternatives.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels dominates transaction structures, with USP-NF and EP pharmacopeial certifications commanding substantial premiums over standard food additive specifications. Price differentiation stems from batch-to-batch purity certification burdens and enzymatic coupling efficiency that lowers phenylalanine input costs for integrated producers. Pricing pressure stems from stevia-monk fruit substitution in premium beverage segments where clean-label positioning commands buyer preference. Mid-market beverage co-packers exhibit highest price sensitivity, while pharmaceutical excipient manufacturers accept premium positioning for tablet binder specifications.
Supply Chain Analysis
Dual-sourcing requirements from major beverage manufacturers mandate multi-supplier qualification across Chinese, Japanese, and German production bases to mitigate single-source vulnerability. Phenylalanine feedstock draws from specialized fermentation houses concentrated in Jiangsu province and Kanto region facilities, with enzymatic biocatalysis platforms tightening cost structures for bulk powder grades. Tariff exposure on amino acid imports from agricultural commodity fluctuations presents structural supply chain risk. Distribution runs through regional food additive distributors in Mumbai-Pune and North Rhine-Westphalia corridors serving secondary formulation activities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aspartame markets constitute a late-cycle quality story as pharmaceutical excipient specifications tighten and tablet binder applications displace commodity powder offtake. This demand-shift toward premium pharmacopeial certifications rewards backward-integrated fermentation specialists with dedicated analytical validation protocols.
For Market Incumbents: Extend certification breadth into excipient-grade specifications for orally disintegrating tablet formulations before pharmacopeial standards tighten further. Deepen backward integration into phenylalanine precursor supply through enzymatic coupling efficiency investments that reduce input cost exposure during agricultural commodity fluctuations. Secure long-term offtake contracts with mid-market beverage co-packers facing reformulation deadline pressures. For New Entrants and Emerging Players: Regional pharmaceutical manufacturers in India present the most penetrable buyer archetype, with FSSAI's distinct additive approval schedules creating first-mover positioning for suppliers establishing local technical dossiers. Target Maharashtra-based food additive distributors seeking qualified secondary suppliers for Mumbai-Pune industrial corridors. Lead with liquid concentrate automation compatibility to differentiate from incumbent powder-centric supply arrangements. For Investors and Strategic Acquirers: Fermentation-integrated specialists with captive amino acid supply are the most active acquirer in this space, consolidating enzymatic technology licensing positions across Asia-Pacific manufacturing bases. Long-term viability hinges on portfolio diversification into pharmaceutical excipient applications as EFSA's systematic re-evaluation of sweetener acceptable daily intakes threatens beverage-only exposure. Monitor pending regulatory classification shifts as the primary inflection indicator for asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Technology Licensing | Retrofitted biocatalysis platforms reduce phenylalanine consumption for Ajinomoto Group's integrated fermentation infrastructure. |
| Pharmaceutical-Grade Certification Investment | USP-NF and EP pharmacopeial standards tighten quality control timelines for tablet binder specifications. |
| Backward Integration into Phenylalanine Supply | Captive amino acid precursor production insulates against agricultural commodity price volatility. |
| Liquid Concentrate Format Expansion | Pumpable sweetener formats reduce handling labor for automated beverage production lines across Asia-Pacific. |
| Regional Technical Dossier Establishment | FSSAI additive approval schedules in India create first-mover positioning for qualified suppliers. |
Methodological Framework
Bottom-up beverage and pharmaceutical application modeling reconciled against top-down fermentation capacity tracking forms the analytical core. Primary interviews with plant managers at integrated production facilities, procurement leads at carbonated soft drink manufacturers, regulatory affairs specialists navigating FDA food additive petitions, and technical R&D directors at enzymatic biocatalysis platforms combined with secondary validation. Trade data from customs records, SEC filings from listed food additive distributors, EFSA scientific opinion databases, and SAMR GB standard publications triangulate supply-side and demand-side estimates.
Input-output matrices map phenylalanine precursor flows through enzymatic coupling stages to finished powder and liquid concentrate outputs across the projection horizon. Segmentation dimensions include product type, physical form, end-use industry, and application category, with pharmacopeial certification tiers and thermal stability profiles as industry-specific cross-cuts. CAGRs derive from trend extrapolation of reformulation mandates and regulatory review timelines, calibrated against historical capacity utilization rates and amino acid feedstock cost movements.
Underlying measurement precision varies by segment; pharmaceutical applications carry tighter precision than tabletop sweeteners due to stricter batch certification requirements. Forecasts reflect assumptions about EFSA re-evaluation timelines, SAMR export eligibility enforcement, and enzymatic technology diffusion rates. Deviation in regulatory classification outcomes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Smoked Sugar Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Sanding Sugar Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
China Food Sweetener Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Dextrates Market
Sweeteners
Japan Allulose Market
Sweeteners
Liquid Sugar Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Allulose Powder Market
Sweeteners
Corn Sweeteners Market