
 Dental Suction Systems Market | 2026-2036
Dental Suction Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Suction Systems Market Intelligence
Group dental practices and dental service organizations are reorganizing procurement priorities around centralized suction infrastructure. Dürr Dental leverages its German engineering heritage to dominate high-throughput wet suction installations across European clinic chains. Danaher Corporation competes through its KaVo dental platform, which anchors integrated electromechanical suction within broader operatory workflows. Midmark Corporation specializes in compact portable units designed for mobile dentistry and satellite clinic formats.
Dental suction systems are vacuum-generating devices that remove fluids, debris, and aerosols from the oral cavity during procedures, typically operating at negative pressures between 12 and 25 kPa depending on application intensity. Wet suction systems employ water-ring vacuum pumps that handle both liquid and solid waste streams, while dry suction configurations use regenerative blowers or rotary vane pumps with separator tanks for moisture extraction. Dry suction is displacing wet systems in new construction due to lower water consumption and reduced biofilm risk, though wet suction retains margin strength in high-volume oral surgery settings. Electromechanical technology leads unit shipments, but integrated systems that combine suction with air compression and scavenging functions command premium positioning in hospital-affiliated dental departments.
The FDA regulates dental suction devices as Class II medical devices under 21 CFR 872.5470, requiring substantial equivalence demonstrations for market entry, while ISO 7494 sets international performance benchmarks for dental unit waterline and suction hygiene. OSHA's Bloodborne Pathogens Standard compels clinics to select suction systems with adequate flow rates for aerosol suppression during ultrasonic scaling and high-speed handpiece use. Dental clinic operators must weigh capital deployment against evolving infection control mandates and the operational flexibility demanded by multi-specialty group practice expansion.
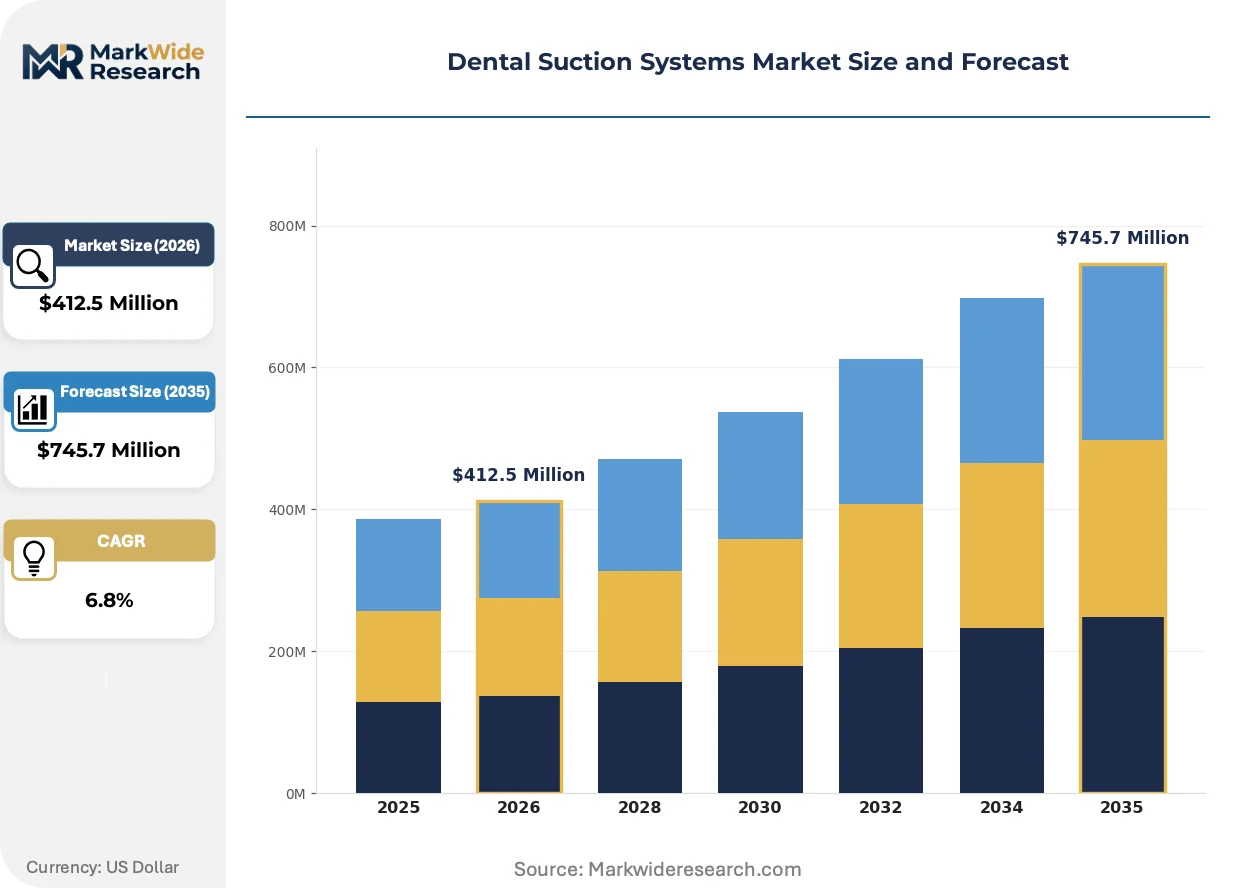
Market Dynamics
The transition from wet to dry suction architectures is compressing capital deployment timelines for dental clinic operators while simultaneously elevating performance specifications demanded by infection control mandates.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Mandated aerosol suppression protocols during ultrasonic scaling procedures compel clinics to upgrade suction flow rates, accelerating replacement cycles for legacy installations.
- Dental service organization consolidation:Centralized procurement by multi-clinic networks favors standardized suction infrastructure that supports scalable infection control across distributed sites.
- Dry suction technology maturation:Water-ring vacuum pump alternatives using regenerative blowers eliminate water consumption and reduce biofilm colonization risks in new construction projects.
Market Restraints
- Copper and electrical motor input volatility:Electromechanical suction unit manufacturing faces margin pressure from commodity price swings in winding materials and pump components.
- Wet suction installed base inertia:Oral surgery centers with substantial capital sunk into water-ring infrastructure resist full-system replacement despite operational disadvantages.
- FDA 510(k) substantial equivalence pathway:Class II medical device clearance timelines extend product development cycles and deter rapid iteration for novel suction architectures.
Strategic Opportunities
- Mobile dentistry satellite formats:Compact portable suction units address underserved rural and institutional care settings where permanent infrastructure is uneconomical.
- ISO 7494 hygiene benchmark elevation:International standard revisions create upgrade demand among export-oriented dental equipment manufacturers seeking competitive differentiation.
- Integrated operatory workflows:Convergence of suction with air compression and nitrous oxide scavenging commands premium positioning in hospital-affiliated dental departments.
Industry Challenges
- Vacuum pump technician scarcity:Specialized maintenance expertise for regenerative blower and rotary vane configurations limits service network expansion for dry suction deployments.
- Legacy waterline integration complexity:Retrofitting dry suction into clinics with existing dental unit waterline configurations requires coordinated plumbing and electrical rework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Suction Systems Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Suction, Dry Suction, Portable Suction, Central Suction Application: Oral Surgery, Restorative Dentistry, Orthodontics, Endodontics End User: Dental Clinics, Hospitals, Research Laboratories, Dental Schools Technology: Electromechanical, Pneumatic, Manual, Integrated Systems |
| Companies Covered | Dürr Dental, Midmark Corporation, Danaher Corporation, NSK Ltd., DentalEZ, A-dec, Cattani, Planmeca, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Suction Systems Market Strategic Shifts & Innovations
Dental suction technology is fragmenting along performance-tier lines as infection control standards harden and clinic operating models diversify across fixed, mobile, and surgical formats.
Regenerative blower dry suction is decomposing the historical wet suction monopoly in new clinic construction. Mid-sized group practices in Germany and the United States are specifying blower-based systems for water conservation and biofilm risk reduction. This technology shift is decomposing the traditional equipment specification hierarchy that favored water-ring pumps for high-volume applications.
EU MDR recalibration is elevating clinical evidence requirements for suction devices marketed as surgical-grade. Manufacturers must now compile post-market surveillance data demonstrating sustained negative pressure performance under continuous oral surgery loads. Hospital-affiliated dental departments in France and Italy are responding by consolidating vendor relationships with firms holding comprehensive technical documentation.
Leasing and subscription arrangements for suction infrastructure are displacing outright capital purchase among emerging dental service organizations. Equipment financing firms are capturing recurring revenue streams previously retained by manufacturers. This financing pivot is most pronounced in the United Kingdom and Spain where clinic roll-up activity concentrates buying power.
Dental Suction Systems Market Segmentation
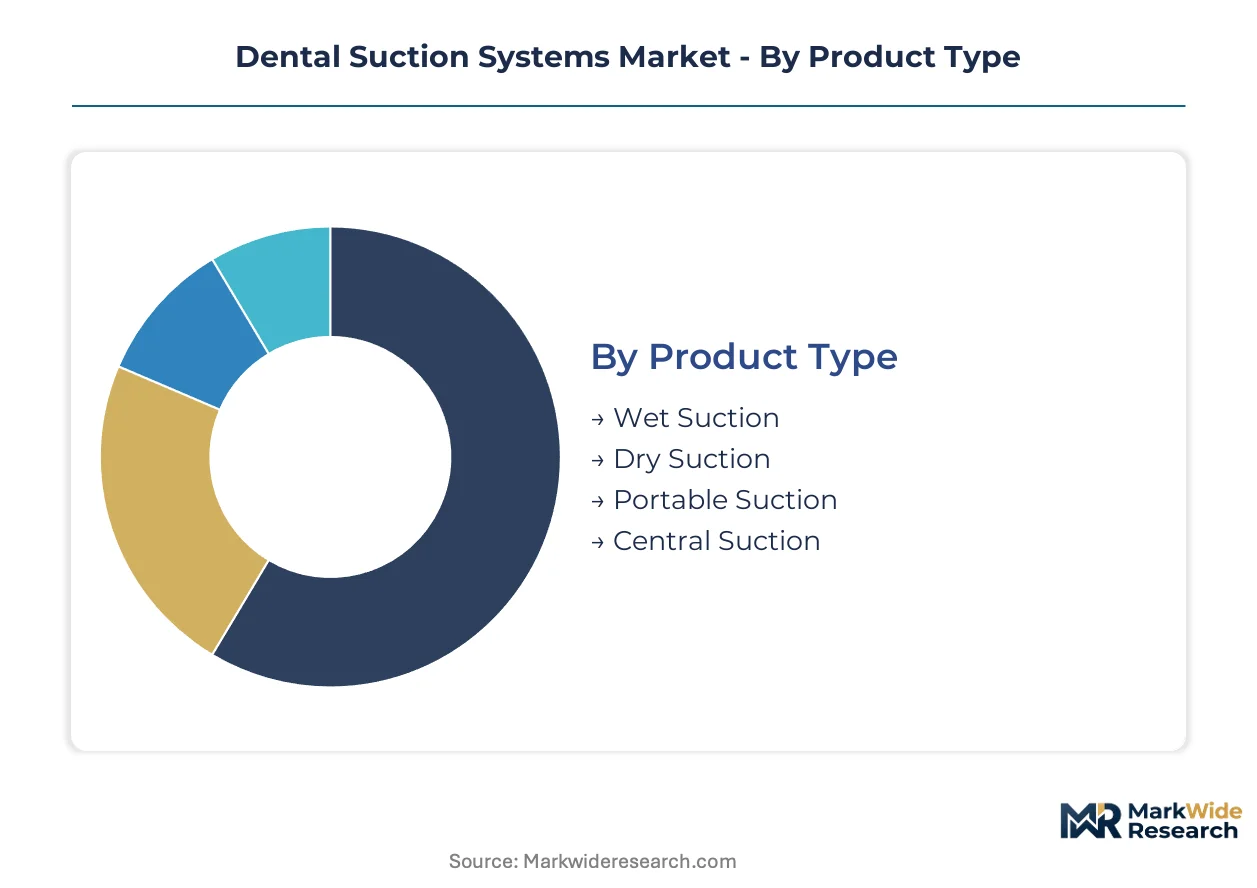
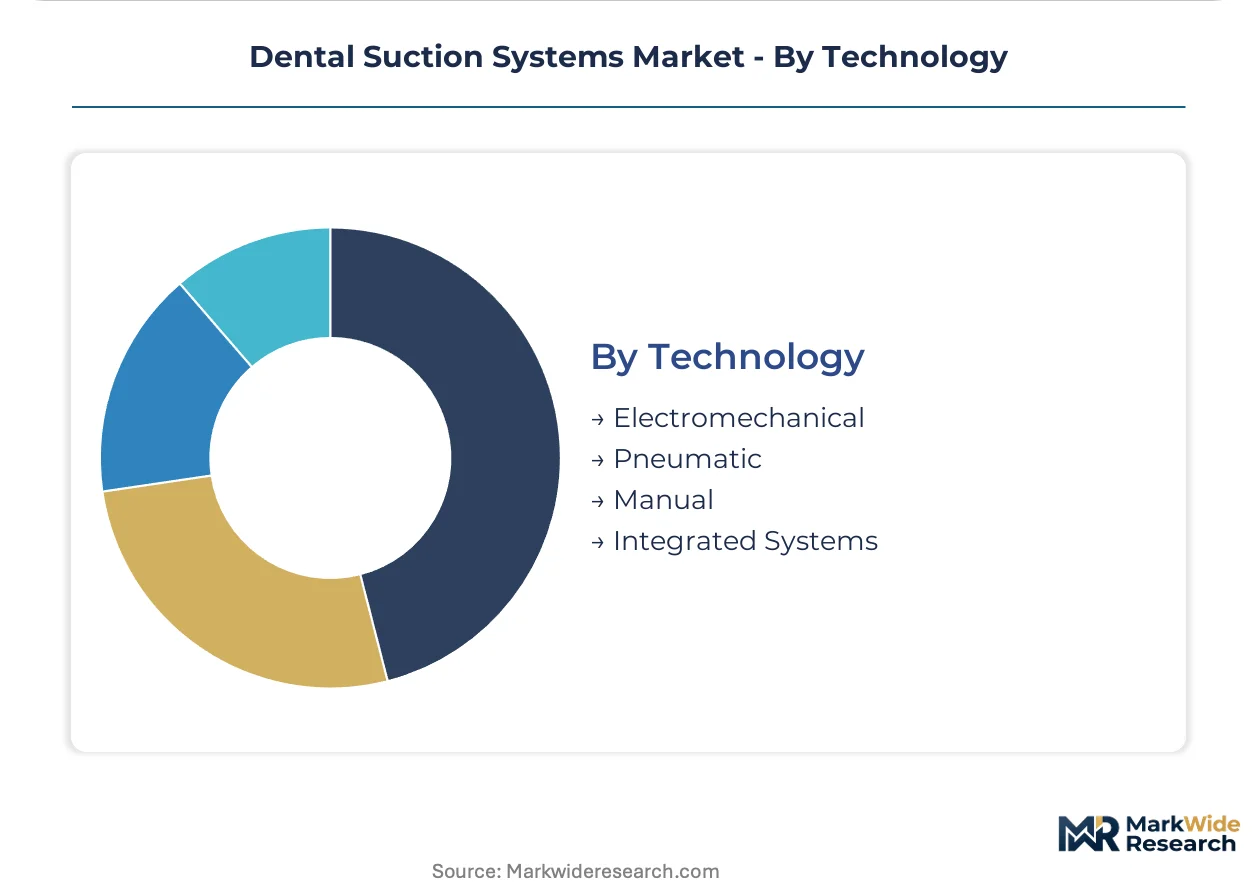
Dental suction infrastructure fragments across four critical dimensions that determine capital deployment patterns and regulatory compliance pathways. Product architecture and application intensity drive specification tiers, while end-user scale and technology integration depth shape procurement economics.
Product Type:
FDA 21 CFR 872.5470 and ISO 7494 establish divergent compliance burdens across wet versus dry architectures, with water-ring systems facing heightened biofilm documentation requirements.
- Wet Suction:Water-ring vacuum pumps handle simultaneous liquid and solid waste streams through continuous water circulation, operating at negative pressures up to 25 kPa for high-volume oral surgery. Oral surgery centers in the United States retain this infrastructure despite water consumption penalties, constrained by sunk capital and continuous-duty reliability under ultrasonic scaling loads.
- Dry Suction:Regenerative blowers and rotary vane pumps with separator tanks eliminate water consumption and reduce biofilm colonization risks. New clinic construction across Germany and the United States specifies dry architectures to satisfy EU MDR post-market surveillance demands and OSHA aerosol suppression mandates.
- Portable Suction:Compact battery-powered or compressor-driven units serve mobile dentistry and satellite clinic formats where permanent infrastructure is uneconomical.
- Central Suction:Multi-operatory vacuum plants serve dental service organization networks with standardized infection control across distributed sites.
Established volume favors wet suction; emerging adoption favors dry suction.
Application:
Procedure intensity determines flow rate specifications and replacement cycle velocity, with surgical applications demanding sustained negative pressure performance.
- Oral Surgery:Third molar extractions and implant placements require continuous 18-25 kPa suction to maintain operative fields under irrigation and bleeding loads.
- Restorative Dentistry:High-speed handpiece aerosol suppression during crown preparations and composite placements drives mid-tier flow rate specifications.
- Orthodontics:Debonding and bracket placement generate intermittent debris loads with lower sustained vacuum demands.
- Endodontics:Root canal irrigation and apical surgery require precise fluid control with minimal tissue displacement.
Volume concentrates in restorative applications; steepest expansion trajectory appears in oral surgery.
End User:
Capital scale and procurement centralization separate institutional buyers from independent operators.
- Dental Clinics:Independent practices and small group formats dominate unit shipments but face fragmented upgrade decisions.
- Hospitals:Hospital-affiliated dental departments command integrated systems combining suction with air compression and nitrous oxide scavenging.
- Research Laboratories:Specialized suction for dental materials testing and biocompatibility studies requires precision vacuum control.
- Dental Schools:Training institutions prioritize durability and standardization across multiple student operatory stations.
Procurement volume clusters in dental clinics; premium positioning concentrates in hospitals.
Technology:
Electromechanical reliability separates volume leaders from niche pneumatic and manual alternatives.
- Electromechanical:Motor-driven vacuum pumps dominate unit shipments across all product architectures.
- Pneumatic:Compressed-air-driven systems serve environments with limited electrical infrastructure or explosion-sensitive requirements.
- Manual:Hand-operated aspirators persist in emergency backup and ultra-low-resource settings.
- Integrated Systems:Converged suction-air compression-scavenging platforms capture premium positioning in hospital-affiliated deployments.
Electromechanical systems anchor current volume; integrated platforms gain share fastest in institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental equipment manufacturers export regenerative blower systems to United States clinic chains expanding ambulatory surgical capacity. Trade corridors concentrate high-specification suction infrastructure between European engineering centers and North American dental service organization networks.
United States
Ambulatory surgical center expansion and dental service organization consolidation drive centralized suction procurement. OSHA's Bloodborne Pathogens Standard mandates aerosol suppression protocols that accelerate replacement cycles for legacy wet suction installations. Clinic chains in Texas and Florida deploy standardized dry suction infrastructure across multi-site networks.
Germany
EU MDR recalibration elevates clinical evidence requirements for surgical-grade suction devices. Dürr Dental anchors high-throughput wet suction production in Bietigheim-Bissingen while mid-sized group practices specify regenerative blower systems for water conservation compliance. Bavarian engineering clusters supply blower-based architectures to domestic clinic construction.
United Kingdom
Equipment financing firms capture recurring revenue through leasing arrangements displacing capital purchase among emerging dental service organizations. NHS procurement frameworks influence private clinic specification standards for infection control infrastructure. London and Southeast England concentrate clinic roll-up activity driving centralized procurement volume.
France
Hospital-affiliated dental departments consolidate vendor relationships with firms holding comprehensive EU MDR technical documentation. ANSM post-market surveillance requirements shape suction system selection for surgical applications. Paris and Lyon metropolitan areas concentrate integrated operatory workflow deployments combining suction with nitrous oxide scavenging.
Japan
PMDA medical device registration requirements extend product development timelines for novel suction architectures entering the market. METI industrial standards influence dental equipment specification in institutional settings. Tokyo and Osaka dental schools prioritize durability and standardization across multiple student operatory stations.
Dental Suction Systems Market Key Industry Players
Listed leaders compete with private specialists across technology integration depth and geographic coverage breadth. Market structure tiers around engineering heritage, scale economies, and mobile format specialization. Three archetypes dominate: German precision engineering houses, diversified healthcare conglomerates with dental platforms, and compact equipment specialists serving satellite formats. Competitive moves concentrate on M&A for clinic network access and strategic partnerships for integrated workflow convergence.
Within the precision engineering tier, Dürr Dental GmbH & Co. KG exemplifies German heritage in high-throughput wet suction installations. Among diversified healthcare platforms, Danaher Corporation occupies a position anchoring integrated electromechanical suction within broader operatory workflows through its KaVo dental platform. On the compact format vector, Midmark Corporation represents specialization in portable units designed for mobile dentistry and satellite clinic configurations.
| Leading Market Players |
|---|
| Dürr Dental |
| Midmark Corporation |
| Danaher Corporation |
| NSK Ltd. |
| DentalEZ |
| A-dec |
| Cattani |
| Planmeca |
| Dentsply Sirona |
| Others |
Cost & Logistics Intelligence
Ninety-to-120-day lead times for regenerative blower motors from Bavarian suppliers concentrate pricing power among German engineering houses serving North American dental service organization networks. This inventory compression forces clinic operators toward premium dry suction configurations while copper winding commodity swings erode margins for electromechanical unit assemblers.
Pricing Analysis
Current-generation regenerative blower dry suction commands a 40-50% premium over prior-generation water-ring wet suction, while next-generation integrated suction-air compression platforms stratify above both. Pricing separates FDA-cleared surgical-grade systems from standard clinic configurations, with ISO 7494 hygiene certification tiering creating additional differentiation. Cost compression in mid-tier wet suction is intensifying because dental service organizations negotiate volume contracts for standardized fleet deployments. Independent single-site clinics exhibit highest price sensitivity; hospital-affiliated dental departments show lowest sensitivity due to capital budget insulation.
Supply Chain Analysis
Strategic stockpiling of copper windings and rare-earth motor magnets characterizes electromechanical suction manufacturing, contrasting with just-in-timed separator tank components from domestic metal fabrication. Supply concentrates in Germany for precision blower engineering, China for motor assembly and wound components, and the United States for final system integration and FDA compliance. Manufacturing rests on copper electrical grade, neodymium permanent magnets, and corrosion-resistant stainless steel separator vessels. Single-source vulnerability sits with specialized regenerative blower impeller casting from Bavarian suppliers. Distribution runs through dental equipment distributors serving group practice networks, with direct OEM relationships capturing hospital-affiliated volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental service organization consolidation has shifted procurement leverage toward centralized buyers commanding standardized fleet pricing across multi-site networks. This buyer-power concentration rewards scale suppliers while squeezing margin for fragmented component vendors.
For Market Incumbents: Secure service network density in dry suction maintenance before technician scarcity hardens into structural bottleneck. Incumbent wet suction specialists must defend installed base relationships against regenerative blower substitution by embedding long-term service contracts with oral surgery centers. Certification investment in EU MDR technical documentation anchors hospital-affiliated vendor consolidation in France and Italy.
For New Entrants and Emerging Players: Lead with portable suction unit development targeting mobile dentistry satellites in rural United States markets where permanent infrastructure economics fail. The penetrable white space sits in battery-powered compact formats for institutional care settings. A direct-to-clinic leasing model bypasses entrenched distributor relationships that incumbent OEMs control.
For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle consolidation play because infection control mandate acceleration compresses equipment refresh timelines regardless of macroeconomic conditions. Acquisition targets should display EU MDR technical file completeness and established service technician training programs. The signal to watch is OSHA guideline revision frequency for aerosol suppression protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Post-market surveillance compliance secures hospital-affiliated vendor consolidation in France and Italy. |
| Service Technician Training Program Expansion | Vacuum pump specialist scarcity limits dry suction deployment velocity across distributed clinic networks. |
| Leasing and Subscription Model Development | Equipment financing firms capture recurring revenue from dental service organization procurement centralization. |
| Integrated Operatory Workflow Convergence | Suction-air compression-scavenging platforms command premium positioning in hospital-affiliated dental departments. |
| Mobile Format Battery Technology Advancement | Compact portable units address satellite clinic formats where permanent suction infrastructure remains uneconomical. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dental clinic operators, biomedical equipment procurement managers, GPO contracts specialists, and vacuum pump service technicians. Secondary validation drew from FDA 510(k) clearance databases, ISO 7494 standard revision records, OSHA enforcement activity reports, and dental equipment customs trade data. Bottom-up installation base modeling and top-down expenditure flow analysis were triangulated to reconcile volume estimates.
Across the analysis window, the forecasting framework modeled dental suction demand through product architecture transitions, application intensity tiers, end-user capital scale, and technology integration depth. CAGRs were derived from replacement cycle velocity analysis under evolving infection control mandates, with input assumptions including OSHA aerosol suppression compliance timelines, EU MDR post-market surveillance documentation requirements, and dental service organization clinic roll-up activity.
Forecasts assume regulatory continuity in FDA Class II medical device pathways and EU MDR clinical evidence requirements; material policy shifts would require re-modeling of product development cycle assumptions and hospital procurement qualification timelines. Revision becomes warranted when OSHA guideline stringency for ultrasonic scaling aerosol suppression crosses implementation thresholds that accelerate legacy wet suction replacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Splints Market
Dental Devices
Orthodontic Wax Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Global Periodontal Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Root Canal Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
Global Dental Burs Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Prophy Dental Handpiece Market