
 Global Reciprocating Pumps Market | 2026-2036
Global Reciprocating Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Reciprocating Pumps Market Foresight
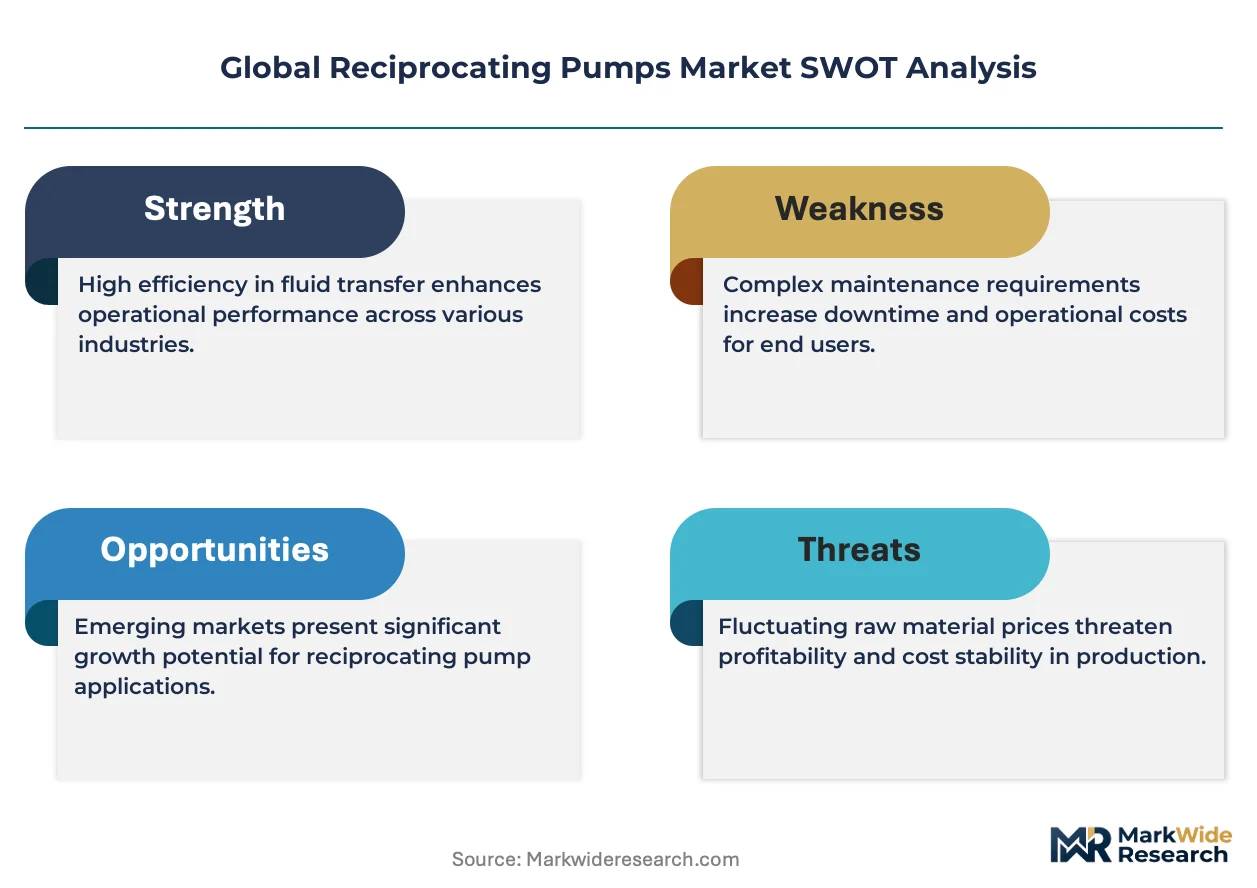
Aftermarket service contracts and predictive maintenance subscriptions is consolidating revenue streams around uptime guarantees rather than unit sales alone. Flowserve Corporation leverages its global service network to anchor long-term contracts with downstream operators. PSG Dover sustains competitive differentiation through specialized seal technologies and chemical compatibility expertise. Peroni Pompe SPA dominates niche high-pressure applications in European refining corridors.
Reciprocating pumps are positive-displacement machines that transfer fluid through cyclic suction and discharge strokes driven by crankshafts, plungers, or pistons, typically achieving pressures exceeding 1,000 bar in industrial configurations. These systems serve critical functions in hydrocarbon extraction, chemical injection, and boiler feed circuits where precise volumetric control and high-pressure capability outweigh centrifugal alternatives. Double-acting configurations capture margin pools in continuous-duty petrochemical service, while triplex designs lead growth in hydraulic fracturing and waterflooding operations where pulsation dampening and flow uniformity command premium positioning. Electric-drive technology is displacing pneumatic alternatives in emissions-sensitive installations, particularly within European utilities and North American power generation retrofits.
EPA emissions guidelines and OSHA process safety management standards govern pump sealing and leak detection requirements across United States industrial facilities, while REACH and the EU F-Gas Regulation restrict fluoropolymer seal chemistries and mandate material traceability in European supply chains. China's MEE enforces discharge permits and efficiency benchmarks for rotating equipment in heavy process industries, creating compliance-driven replacement cycles. Stakeholders must monitor regulatory divergence between Atlantic and Pacific basin standards when configuring global product platforms and local certification strategies.
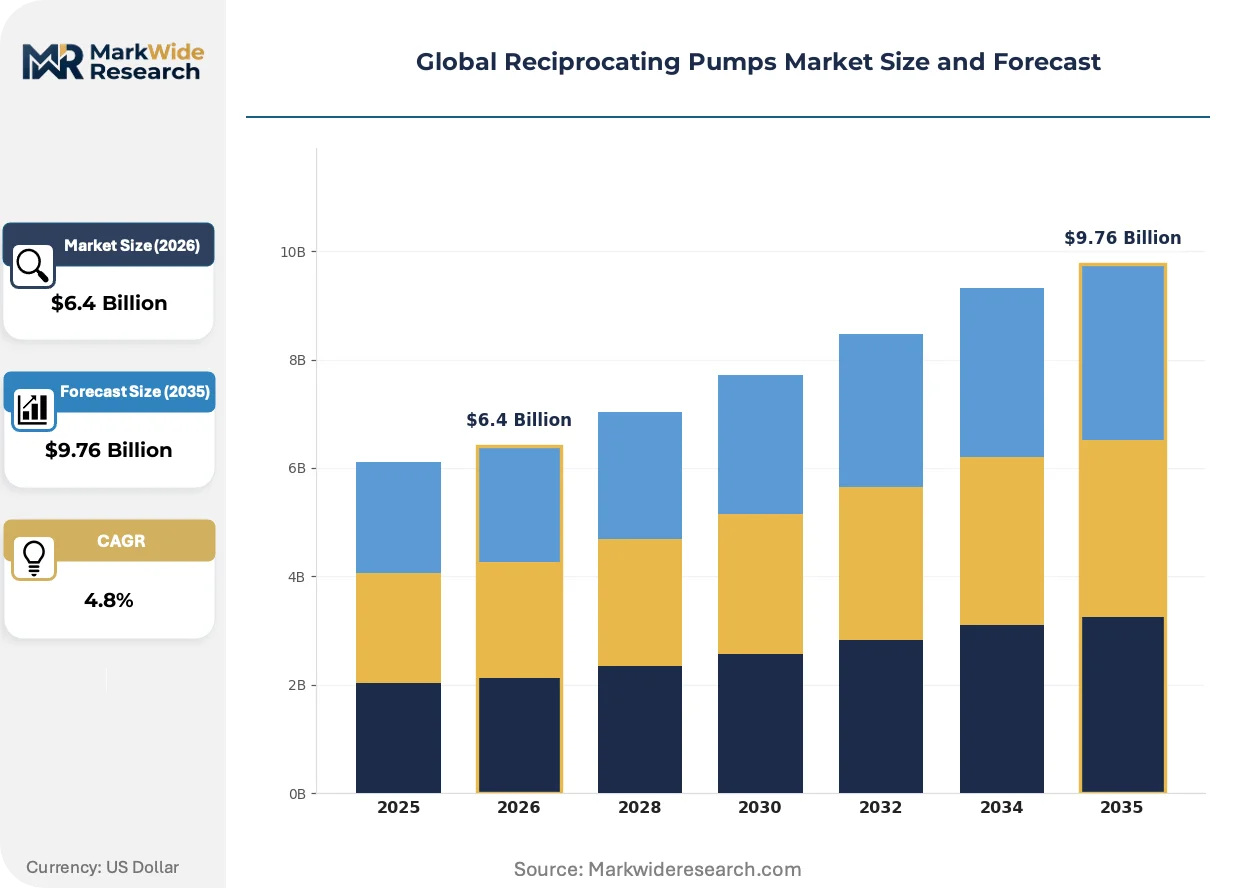
Market Dynamics
Electric-drive reciprocating pump systems are displacing pneumatic alternatives across emissions-sensitive installations, compressing the competitive window for legacy compressor-dependent architectures while elevating lifecycle service contracts as the primary revenue anchor.
Growth Catalysts
- Hydraulic fracturing intensity:North American shale operators are deploying triplex pump configurations for high-pressure waterflooding operations. Continuous-duty specifications in Permian and Bakken formations drive replacement cycles above historical baselines.
- EU F-Gas Regulation:Tightening fluoropolymer restrictions are forcing seal chemistry upgrades across European refining corridors. Compliance-driven retrofits expand addressable service revenue for pump OEMs with certified material traceability.
- Enhanced oil recovery mandates:China's MEE discharge permit requirements are accelerating high-pressure injection system deployments in Sinopec and PetroChina fields. Efficiency benchmarks for rotating equipment compress replacement timelines.
Market Restraints
- Specialized alloy input costs:Duplex stainless steel and Inconel price volatility constrains margin flexibility for high-pressure plunger manufacturers. Foundry capacity concentration in Germany and Japan amplifies supply risk.
- Centrifugal substitution in mid-pressure ranges:Multistage centrifugal pumps capture boiler feed applications below 150 bar. Reciprocating architectures retreat to niche high-pressure, low-flow segments.
- REACH material traceability burdens:European chemical compatibility documentation requirements extend procurement cycles by four to eight weeks. Small and mid-size process operators delay capital commitments.
Strategic Opportunities
- Carbon capture injection infrastructure:Saline aquifer sequestration projects in the United States and Norway require CO2-compatible high-pressure pumps. API 674 compliance positions vendors for early procurement waves.
- Predictive maintenance platform convergence:Vibration monitoring and digital twin analytics integrate with legacy pump installations. Downstream operators in Rotterdam and Singapore pay premium subscriptions for uptime guarantees.
- India petrochemical expansion:Reliance Industries and Indian Oil Corporation are commissioning ethylene crackers requiring boiler feed and chemical injection pumps. Domestic manufacturing incentives lower import dependency.
Industry Challenges
- API 674 and ISO 13709 certification timelines:Third-party witness testing for reciprocating pump packages extends project delivery by twelve to sixteen weeks. Engineering resource constraints at notified bodies create bottlenecks.
- Legacy control system integration:Electric-drive pump retrofits must interface with existing DCS architectures in 1990s-era refineries. Protocol translation and safety interlock reprogramming inflate commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Reciprocating Pumps Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Acting, Double-Acting, Triplex, Duplex, Quintuplex Technology: Hydraulic, Pneumatic, Electric, Steam-Driven, Air-Operated Application: Petrochemical, Water Treatment, Mining, Power Generation, Pulp & Paper End User: Oil & Gas Operators, Chemical Processors, Utilities, Manufacturing Facilities, Marine Contractors |
| Companies Covered | Flowserve Corporation, PSG Dover, Peroni Pompe SPA, DMW Corporation, Ram Pumps Ltd., Celeros Flow Technology, Cat Pumps, TEIKOKU MACHINERY WORKS, LTD, Atlas Copco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Reciprocating Pumps Market Shifts & Advancements
Digital instrumentation and advanced materials are compressing maintenance intervals while expanding the addressable range of reciprocating pump applications beyond traditional hydrocarbon boundaries.
Ceramic-coated plungers and tungsten carbide valve components are expanding into abrasive service applications previously dominated by progressive cavity pumps. Mining slurry and geothermal brine operators in Chile and Indonesia are piloting these configurations for twelve-month mean-time-between-failures targets. The technology is expanding into price-sensitive mid-market segments by reducing seal replacement frequency and extending overhaul intervals.
REACH authorization requirements for per- and polyfluoroalkyl substances are restricting conventional PTFE seal chemistries in European process industries. Pump OEMs are accelerating fluoroelastomer and thermoplastic polyurethane qualification programs to maintain chemical resistance portfolios. German chemical clusters along the Rhine corridor are demanding full material disclosure documentation, compressing supplier qualification timelines and elevating certified vendors.
Service contract unbundling is fragmenting traditional procurement relationships between pump OEMs and downstream operators. Major refining complexes in Texas and Louisiana are separating hardware acquisition from maintenance execution, awarding predictive analytics and spare parts logistics to specialized third-party providers. This pattern concentrates margin pressure on original equipment manufacturers while elevating independent service network scale advantages.
Global Reciprocating Pumps Market Segmentation
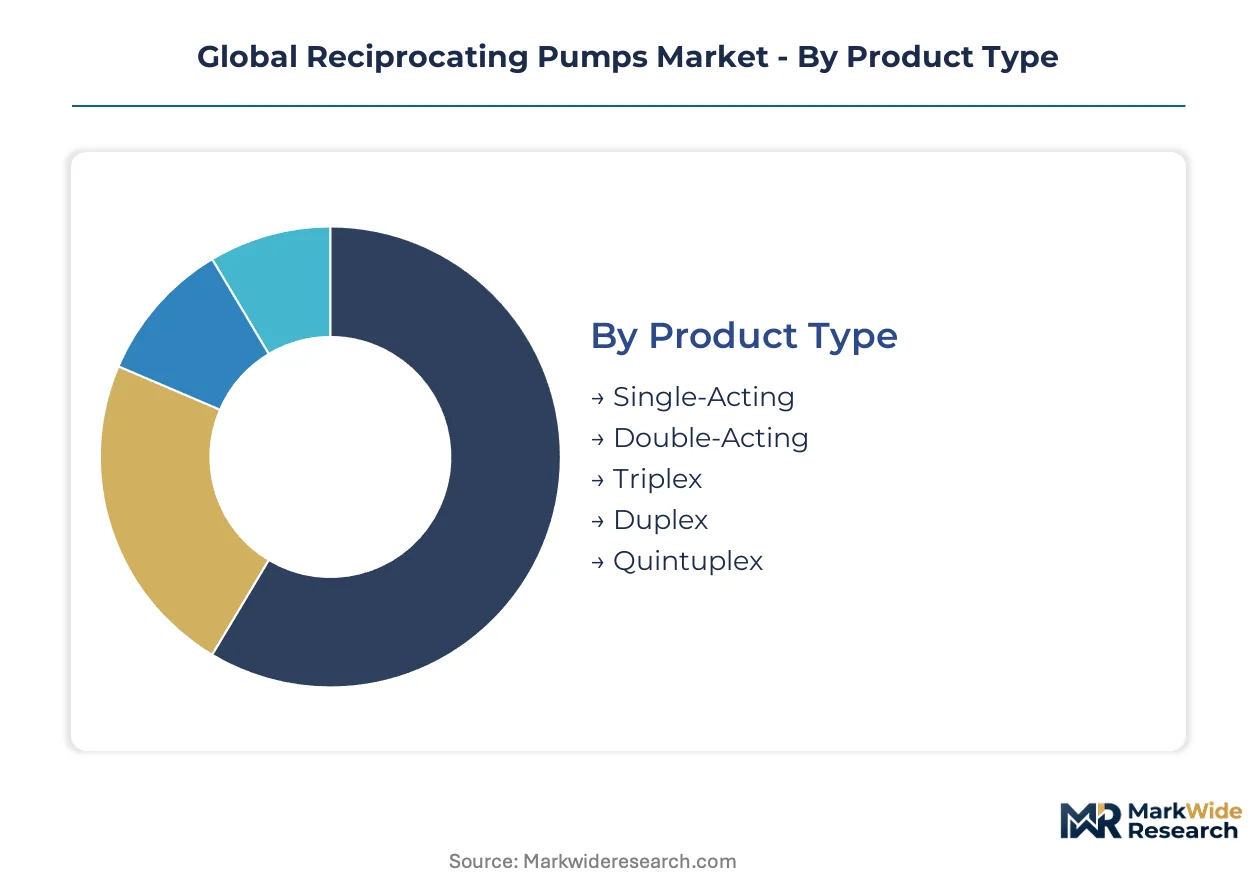
Reciprocating pump architectures span a wide specification range, from standardized single-acting units for general industrial service to highly engineered quintuplex systems for extreme-pressure hydrocarbon extraction. Segmentation discipline separates commoditized replacement demand from premium new-build opportunities where material certification and pulsation control command pricing power.
Product Type:
Customization intensity varies sharply across this category, with simplex and duplex configurations offering catalog-standard solutions while multiplex designs require application-specific engineering.
- Single-Acting:One suction and one discharge stroke per crankshaft revolution delivers intermittent flow suitable for batch chemical processing and low-duty water transfer. Demand concentrates in German chemical clusters and US Midwest manufacturing facilities where capital budgets favor standardized equipment over performance optimization.
- Double-Acting:Simultaneous suction and discharge on both sides of the piston achieves near-continuous flow for boiler feed and high-pressure injection service. Petrochemical expansions along the US Gulf Coast and Rotterdam refining corridors drive specification volumes, with API 674 compliance mandatory for project acceptance.
- Triplex:Three plungers operating 120 degrees out of phase minimize pulsation amplitude for hydraulic fracturing and waterflooding operations.
- Duplex:Two-cylinder configurations balance cost and flow uniformity in mid-pressure chemical injection applications.
- Quintuplex:Five-plunger designs serve ultra-high-pressure CO2 injection and specialty gas compression where pulsation tolerance approaches zero.
Leading the category by volume: Double-Acting. Expanding most quickly: Triplex.
Technology:
Drive mechanism selection traces directly to site infrastructure availability and emissions compliance posture, creating divergent cost structures across installation types.
- Electric:Variable-frequency drive systems achieve precise flow control with zero direct emissions, displacing pneumatic alternatives in European utilities and North American power generation retrofits subject to EPA and EU F-Gas Regulation constraints. Siemens and ABB motor packages dominate specification sheets for projects above 500 kW.
- Hydraulic:Fluid power transmission isolates the pump from electrical ignition hazards in offshore platforms and underground mining operations. Norwegian North Sea installations and Chilean copper mines specify these configurations for intrinsic safety in explosive atmospheres.
- Pneumatic:Compressed air drive persists in remote locations lacking grid infrastructure or where portability outweighs efficiency penalties.
- Steam-Driven:Waste heat recovery applications in pulp mills and refineries leverage existing boiler infrastructure.
- Air-Operated:Diaphragm variants handle shear-sensitive fluids in pharmaceutical and food processing where product integrity overrides energy costs.
Dominant by installed base: Electric. Gaining share fastest: Hydraulic in hazardous environment deployments.
Application:
End-use severity determines material specification and service contract structure, with hydrocarbon applications demanding full lifecycle support versus discrete equipment sales in water handling.
- Petrochemical:High-pressure injection and process transfer duties require Inconel-plunger and tungsten carbide-valve configurations for sour service compatibility. Sinopec and Reliance Industries expansions in China and India anchor procurement volumes for continuous-duty specifications.
- Power Generation:Boiler feed pump reliability directly impacts plant availability, elevating predictive maintenance subscriptions over transactional spare parts sales. US independent power producers and German municipal utilities drive retrofit demand for electric-drive replacements of legacy steam turbine pumps.
- Water Treatment:Reverse osmosis and desalination plants specify corrosion-resistant duplex stainless steel for seawater exposure.
- Mining:Abrasive slurry service tests ceramic coating durability in Chilean copper and Indonesian nickel operations.
- Pulp & Paper:Black liquor and bleach chemical handling demands specialized seal chemistries for fiber recovery processes.
Highest value concentration: Petrochemical. Steepest expansion trajectory: Power Generation electrification retrofits.
End User:
Procurement sophistication separates integrated operators with centralized engineering standards from fragmented buyers relying on distributor specification support.
- Oil & Gas Operators:Majors and national oil companies enforce API 674 and ISO 13709 compliance with mandatory third-party witness testing, compressing qualified vendor pools. Permian Basin independents and Saudi Aramco upstream divisions drive triplex pump demand for unconventional production.
- Chemical Processors:REACH documentation requirements and material traceability mandates extend procurement cycles for European chlor-alkali and specialty chemical producers along the Rhine and US Gulf Coast corridors.
- Utilities:Rate-regulated returns favor lifecycle cost optimization over first-cost minimization in pump selection.
- Manufacturing Facilities:General industrial buyers prioritize local service response and spare parts availability.
- Marine Contractors:Offshore support vessel specifications emphasize weight reduction and space efficiency for deck-mounted pumping systems.
Largest procurement scale: Oil & Gas Operators. Fastest contract sophistication advance: Chemical Processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors global reciprocating pump procurement through its concentration of Permian Basin operators and Gulf Coast petrochemical complexes. The city's engineering procurement offices coordinate specification standards for high-pressure injection systems across North American shale formations. Rotterdam and Singapore serve as secondary coordination nodes for Atlantic and Pacific basin project logistics.
United States
Permian Basin independents and Bakken operators deploy triplex configurations for hydraulic fracturing intensity above historical baselines. EPA emissions guidelines and OSHA process safety management standards govern pump sealing requirements across Texas and Louisiana refining corridors. Houston-Galveston petrochemical complexes anchor procurement volumes for API 674-compliant continuous-duty specifications.
Germany
Rhine corridor chemical clusters demand full material disclosure documentation for REACH-compliant seal chemistries. EU F-Gas Regulation restrictions on fluoropolymer compounds force retrofit cycles across Baden-Württemberg and North Rhine-Westphalia process industries. Ludwigshafen and Leverkusen engineering centers specify certified material traceability for high-pressure plunger applications.
China
Sinopec and PetroChina upstream divisions accelerate high-pressure injection system deployments under MEE discharge permit requirements. Efficiency benchmarks for rotating equipment compress replacement timelines across Sichuan-Chongqing shale gas fields. Yangtze River Delta refineries anchor domestic manufacturing incentives for boiler feed and chemical injection pump procurement.
India
Reliance Industries and Indian Oil Corporation commission ethylene crackers requiring continuous-duty pump specifications for boiler feed service. CEA efficiency mandates and domestic manufacturing incentives lower import dependency for process equipment. Gujarat and Maharashtra petrochemical corridors concentrate specification engineering for high-pressure injection applications.
Norway
Equinor-operated saline aquifer sequestration projects require CO2-compatible high-pressure pumps for carbon capture injection infrastructure. North Sea offshore platforms specify hydraulic-drive configurations for intrinsic safety in explosive atmospheres. Stavanger engineering clusters coordinate API 674 compliance for early procurement waves in European CCS developments.
Global Reciprocating Pumps Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the reciprocating pump supply base, with foundry-dependent manufacturers facing margin pressure from specialized assembly houses. The vendor structure concentrates around three tiers: integrated multinationals with global service networks, regional specialists with certified material expertise, and commodity assemblers serving replacement demand. Strategic archetypes include full-lifecycle service integrators, seal-technology specialists, and niche high-pressure engineers. Competitive moves center on predictive maintenance platform convergence and aftermarket contract unbundling.
Among integrated service providers, Flowserve Corporation anchors the full-lifecycle archetype through global network scale. PSG Dover exemplifies the specialized technology tier through seal chemistry and chemical compatibility positioning. Peroni Pompe SPA occupies the niche engineering segment for ultra-high-pressure European refining applications. These three represent divergent competitive vectors rather than direct substitution rivals.
| Leading Market Players |
|---|
| Flowserve Corporation |
| PSG Dover |
| Peroni Pompe SPA |
| DMW Corporation |
| Ram Pumps Ltd. |
| Celeros Flow Technology |
| Cat Pumps |
| TEIKOKU MACHINERY WORKS, LTD |
| Atlas Copco |
| Others |
Supply & Pricing Matrix
Family-owned German foundries and Japanese precision manufacturers anchor high-pressure plunger supply, translating concentrated metallurgical expertise into pricing power for duplex stainless and Inconel components. Their ownership structures resist short-term margin compression, forcing buyers into longer contract horizons or premium spot-market exposure.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and throughput performance dominates API 674-compliant project awards. Pricing stratifies across premium certified tiers, mid-market standard specifications, and economy replacement units differentiated by material traceability depth and pulsation control engineering. Cost compression in the economy tier intensifies as Chinese domestic manufacturers expand export capacity for simplex and duplex configurations. Petrochemical majors exhibit lowest price sensitivity, prioritizing lifecycle reliability over first-cost minimization, while general industrial buyers in water treatment and manufacturing facilities drive aggressive procurement negotiations.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore coordinate hub-and-spoke logistics for aftermarket parts and emergency replacement units. Foundry capacity concentrates in Germany, Japan, and China, with specialized Inconel and duplex stainless forging dependent on concentrated metallurgical expertise. Single-source vulnerability runs through German precision machining for high-pressure valve components. Distribution runs through OEM-direct channels for project business and authorized distributor networks for maintenance, repair, and operations demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric-drive systems are displacing pneumatic and steam-turbine alternatives across emissions-sensitive installations, compressing the competitive window for legacy architectures and elevating predictive maintenance platforms as the primary value capture mechanism.
For Market Incumbents: Lock in long-term service contracts with Permian Basin independents and Sinopec upstream divisions before electric-drive retrofit cycles peak. Deepen backward integration into ceramic coating and tungsten carbide valve component production to defend margin position against specialized assembly houses. Prioritize API 674 and ISO 13709 certification investment to compress qualified vendor pools and elevate switching costs. For New Entrants and Emerging Players: Enter via predictive analytics and spare parts logistics specialization, unbundling from hardware acquisition to capture margin pools concentrated in Texas and Louisiana refining complexes. Target carbon capture injection infrastructure in Norway and the United States where API 674 compliance requirements and early procurement waves favor nimble specialists. Pursue white-label manufacturing partnerships with Indian domestic producers serving Reliance Industries and Indian Oil Corporation expansions. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light designers with certified material traceability expertise in European refining corridors, where REACH documentation burdens and F-Gas Regulation retrofit cycles compress small-operator margins. Long-term viability hinges on predictive maintenance platform convergence and aftermarket contract unbundling trajectories. Monitor MEE discharge permit enforcement intensity in China as inflection indicator for high-pressure injection system replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Rotterdam and Singapore downstream operators pay premium subscriptions for uptime guarantees tied to vibration monitoring. |
| Ceramic Coating Technology Licensing | Chilean copper and Indonesian nickel mines pilot tungsten carbide configurations for abrasive slurry service expansion. |
| REACH-Compliant Seal Chemistry Qualification | German Rhine corridor chemical clusters demand full material disclosure documentation, elevating certified vendors. |
| Electric-Drive Retrofit Partnership | US independent power producers and German municipal utilities replace legacy steam turbine pumps under EPA and EU F-Gas Regulation constraints. |
| Carbon Capture Injection System Certification | Equinor-operated saline aquifer projects in Norway require CO2-compatible high-pressure pumps with API 674 compliance. |
Research Methodology
Trade association filings, customs and import-export records, and SEC 10-K disclosures formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with maintenance directors at Permian Basin operators, plant engineers at Rotterdam and Singapore refining complexes, aftermarket service heads at Flowserve and PSG Dover, and procurement leads at Sinopec and Reliance Industries validated demand patterns and pricing dynamics. Bottom-up unit shipment estimates triangulated against top-down value projections derived from petrochemical capacity expansion databases.
Historical trendline analysis of replacement cycles, retrofit penetration rates, and regulatory compliance timelines informed projection assumptions across the analysis window. Segmentation modeling incorporated product type, drive technology, application severity, and end-user procurement sophistication dimensions. CAGRs derived from weighted average growth across shale field development intensity, EU F-Gas Regulation retrofit mandates, and MEE discharge permit enforcement trajectories. Forecast inputs included foundry capacity utilization rates, alloy price volatility indices, and third-party certification backlog durations at notified bodies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH authorization changes or German-Japanese foundry supply disruptions. Outputs reflect documented assumptions regarding electric-drive substitution velocity and carbon capture infrastructure procurement timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Electric Submersible Pump (ESP) in Oil and Gas Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market