
 Fuel Feed Pumps Market | 2026-2036
Fuel Feed Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Feed Pumps Market Foresight
Capital-intensity divergence between integrated manufacturers and component assemblers is redrawing competitive boundaries in fuel feed pump supply. Robert Bosch GmbH leverages captive semiconductor and precision-machining operations to control cost structures across electric pump portfolios. DENSO Corporation anchors its position through thermal-management integration, bundling feed pumps with fuel-injection modules for Asian OEM programs. Continental AG competes on mechatronics scale, extending actuator and sensor expertise into smart pump architectures with embedded diagnostics.
A fuel feed pump is a precision fluid-handling device that transfers fuel from storage tanks to engine injection systems at controlled pressures, typically operating between 3 bar and 10 bar for conventional applications and exceeding 150 bar in common-rail diesel configurations. Its primary commercial purpose is to ensure consistent fuel delivery across varying engine loads, ambient temperatures, and altitude conditions while preventing cavitation and vapor lock. Electric pumps now lead product-type segmentation as port- and direct-injection gasoline engines displace mechanical lift pumps in passenger and light-commercial vehicles. Positive-displacement technology dominates high-pressure diesel applications where precise metering trumps flow volume, while centrifugal designs occupy auxiliary and transfer duties in marine and generator-set installations. Diaphragm pumps sustain niche positions in small-engine and agricultural machinery segments where cost minimization outweighs efficiency optimization.
EPA tailpipe standards, EU Stage V emission frameworks, and China's GB VI regulations collectively mandate tighter fuel-system tolerances, pressuring suppliers to certify pumps for particulate-filter compatibility and low-sulfur fuel resilience. The US NHTSA and EU type-approval bodies are integrating fuel-pump durability into broader powertrain compliance audits, raising barriers for unvalidated entrants. Stakeholders must monitor regulatory harmonization gaps between emission zones and assess whether dual-certification investments justify access to fragmented national markets.
Market Dynamics
High-pressure common-rail diesel architectures and port-injection gasoline systems are forcing simultaneous pump redesigns, splitting supplier development resources between 150-bar precision metering and 5-bar electric lift applications.
Growth Catalysts
- EPA Tier 4 Final:Off-highway equipment manufacturers in North America must retrofit fuel systems with particulate-filter-compatible pumps, opening replacement demand across construction and agricultural fleets.
- Electric pump technology:Brushless DC motor designs are displacing mechanical lift pumps in light-commercial vehicles, driven by start-stop system compatibility requirements.
- China GB VI:Domestic OEM localization mandates are pulling pump production capacity toward Sichuan and Shandong manufacturing clusters.
Market Restraints
- Semiconductor input volatility:Electric pump motor controllers depend on automotive-grade MOSFET supply concentrated in Taiwanese foundries.
- Precision-machining concentration:High-pressure pump housing production clusters in southern Germany, creating single-source vulnerability for Tier 2 suppliers.
- Common-rail substitution ceiling:Battery-electric powertrains in urban delivery vans are eliminating mechanical fuel systems entirely from certain duty cycles.
Strategic Opportunities
- India commercial vehicle localization:PLI scheme incentives for component manufacturing are opening pump supply contracts for domestic bus and truck platforms.
- Hydrogen dual-fuel retrofits:H2-diesel blending systems require modified feed pump architectures with elastomer compatibility for hydrogen permeation.
- Marine genset electrification:IMO 2020 low-sulfur compliance is driving electric pump adoption in auxiliary power units for container shipping.
Industry Challenges
- Embedded software certification:Smart pumps with diagnostic firmware face extended validation timelines under UN ECE R155 cybersecurity requirements.
- High-pressure testing infrastructure:Common-rail pump validation requires capital-intensive test benches capable of 200-bar continuous operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Feed Pumps Market |
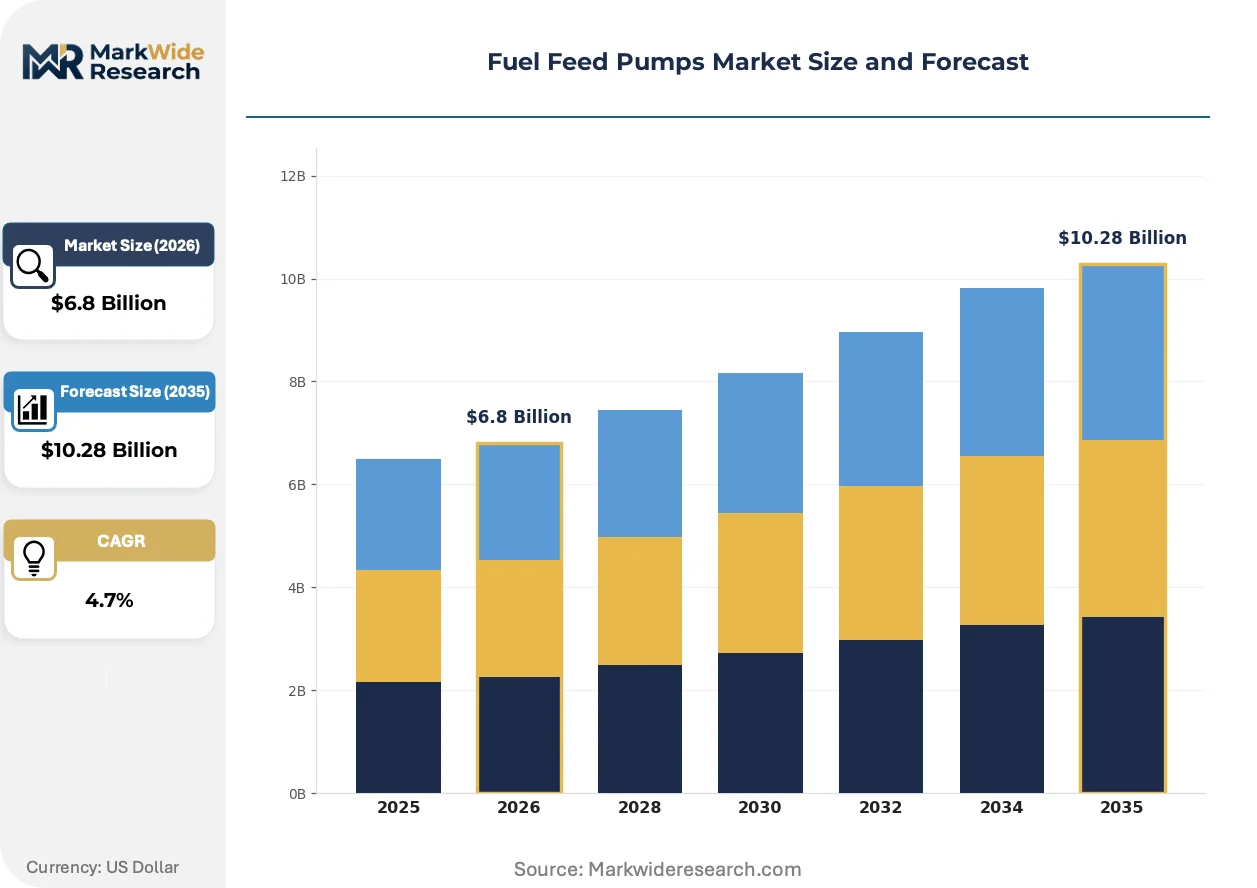
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Mechanical, Diaphragm, Rotary, Piston, Gear Technology: Positive Displacement, Centrifugal, Vacuum, Pressure, Magnetic Drive, Hydraulic Application: Marine Vessels, Agricultural Machinery, Construction Equipment, Aerospace Propulsion, Generator Sets, Locomotives End User: OEMs, Aftermarket Suppliers, Maintenance Workshops, Fuel Stations |
| Companies Covered | Robert Bosch GmbH, DENSO Corporation, Continental AG, BorgWarner, Flowserve, Grundfos, Hitachi Automotive Systems, Marelli Holdings, MAHLE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Feed Pumps Market Shifts & Advancements
Electrification of fuel delivery architectures is fragmenting the supplier base between legacy mechanical specialists and mechatronics integrators, while emission compliance timelines compress development cycles.
Brushless DC electric feed pumps are bifurcating the passenger vehicle segment between premium platforms demanding variable-speed pressure control and economy segments accepting fixed-output designs. European OEMs are specifying intelligent pumps with LIN-bus communication for start-stop optimization. This technology compression is squeezing single-function mechanical suppliers from mid-market contracts.
EU Stage V emission frameworks are mandating sealed fuel systems with evaporative emission controls, forcing pump manufacturers to redesign sealing architectures and materials. The industrial consequence is extended type-approval timelines for non-road mobile machinery. Off-highway equipment in Germany and France faces the tightest compliance windows, pushing suppliers toward modular pump families certifiable across multiple power classes.
Fleet operators are unbundling pump replacement from full fuel system service contracts, creating direct aftermarket procurement channels bypassing traditional distributor networks. Independent repair shops in the United States are sourcing remanufactured electric pumps through e-commerce platforms. This channel disruption is most visible in Class 3-6 commercial vehicle segments where vehicle age exceeds seven years.
Fuel Feed Pumps Market Segmentation
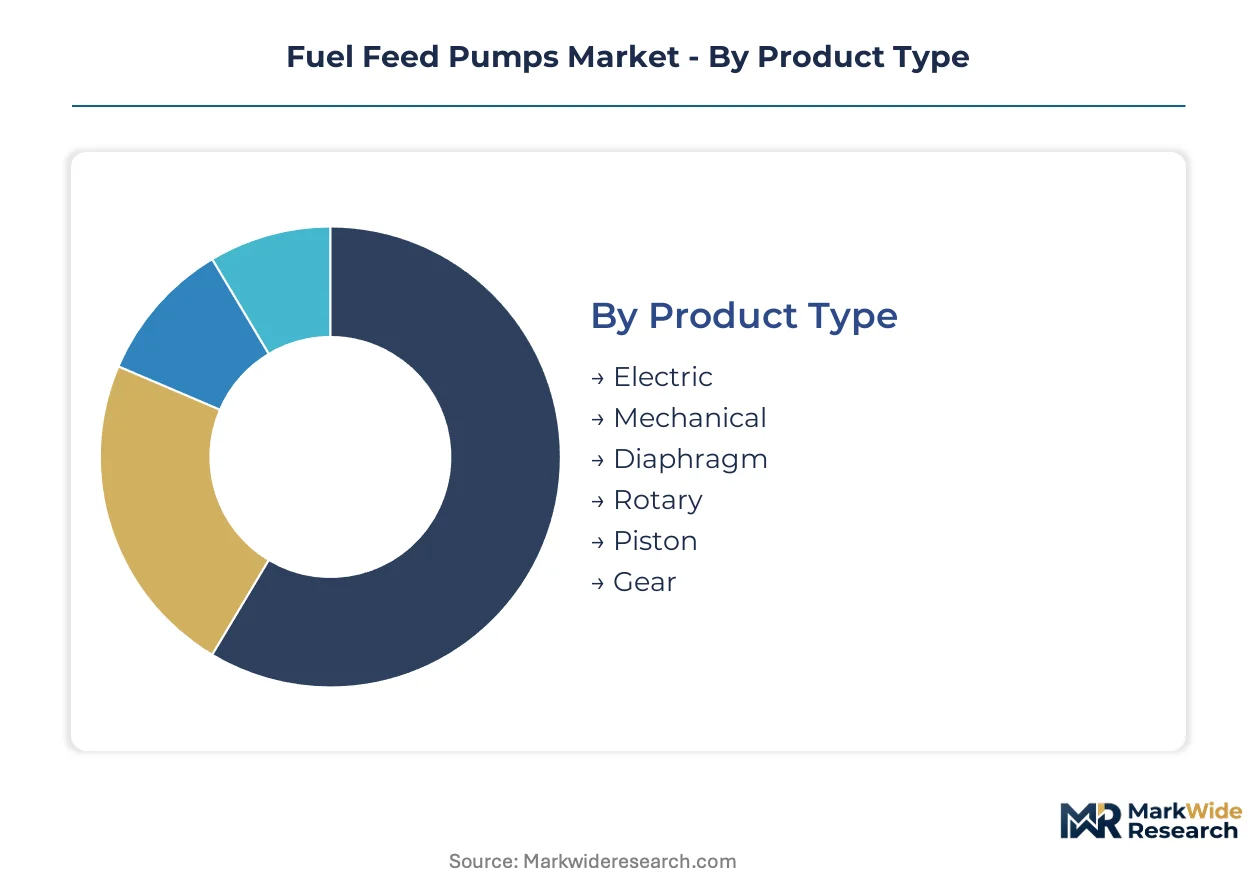
Fuel feed pump architectures fragment across powertrain electrification timelines and emission compliance tiers. Suppliers configure product portfolios around pressure specifications, duty cycles, and regional certification requirements rather than pursuing universal platforms.
Product Type:
Domestic production clusters in China and India concentrate on electric and mechanical variants for local OEM supply, while diaphragm and rotary pumps flow primarily from European export hubs serving marine and industrial niches.
- Electric:Brushless DC motor architectures dominate passenger vehicle fitments with start-stop compatibility. Demand concentrates in Chinese domestic OEM programs as GB VI compliance tightens fuel-system tolerances for light-commercial platforms.
- Mechanical:Camshaft-driven lift pumps persist in cost-optimized small-engine and agricultural applications. Procurement runs through Indian and Brazilian tractor manufacturers seeking minimal electronic complexity for emerging-market price points.
- Diaphragm:Elastomer-actuated designs serve small-engine and auxiliary fuel transfer duties where pressure requirements stay below 3 bar.
- Rotary:Vane-cell configurations occupy marine genset and stationary engine segments requiring continuous duty operation.
- Piston:High-pressure metering pumps anchor common-rail diesel architectures exceeding 150 bar for construction equipment.
- Gear:External and internal gear pumps handle viscous fuels and lubrication transfer in industrial process applications.
Electric pumps command the established base. The steepest expansion runs through piston architectures for off-highway common-rail retrofits.
Technology:
Cost tiers separate precision-machined positive displacement systems from stamped-housing centrifugal alternatives, with magnetic drive and hydraulic variants occupying premium corrosion-resistant niches.
- Positive Displacement:Reciprocating and rotary mechanisms deliver fixed fuel volumes per cycle for precise metering. German and Japanese machining clusters supply high-pressure diesel applications where 200-bar validation requirements filter out lower-tier competitors.
- Centrifugal:Impeller-driven flow suits transfer and circulation duties with minimal pressure head. Marine auxiliary systems in Rotterdam and Singapore bunkering hubs drive specification requirements for low-sulfur fuel compatibility.
- Vacuum:Suction-lift configurations serve small-engine gravity-feed conversions and emergency transfer equipment.
- Pressure:Demand-actuated delivery systems integrate with electronic engine management for variable flow optimization.
- Magnetic Drive:Sealless architectures prevent leakage in hydrogen-diesel dual-fuel pilots and chemical-handling environments.
- Hydraulic:Fluid-power actuation provides explosion-proof operation for mining and offshore platform fuel handling.
Positive displacement technology anchors revenue concentration. Magnetic drive architectures are gaining share fastest on hydrogen compatibility testing.
Application:
Volume scale clusters in construction equipment and agricultural machinery, while aerospace and marine applications concentrate margin in low-volume, high-certification segments.
- Construction Equipment:EPA Tier 4 Final retrofit cycles drive replacement demand across North American excavator and loader fleets. Fleet operators in Texas and Alberta unbundle pump procurement from full system service contracts.
- Agricultural Machinery:Tractor and combine manufacturers in India and Brazil specify mechanical lift pumps for price-sensitive emerging-market platforms. EU Stage V compliance is forcing sealed-system redesigns for European export models.
- Marine Vessels:IMO 2020 low-sulfur mandates require electric pump retrofits for auxiliary gensets in container shipping.
- Aerospace Propulsion:Turbine fuel pumps face FAA and EASA certification timelines exceeding thirty-six months for new platform introductions.
- Generator Sets:Stationary and mobile power units span diesel, natural gas, and dual-fuel configurations with varying pressure requirements.
- Locomotives:Rail freight operators in Russia and India specify heavy-duty mechanical pumps for extreme temperature and vibration environments.
Construction equipment commands the established base. Marine genset electrification represents the steepest expansion trajectory.
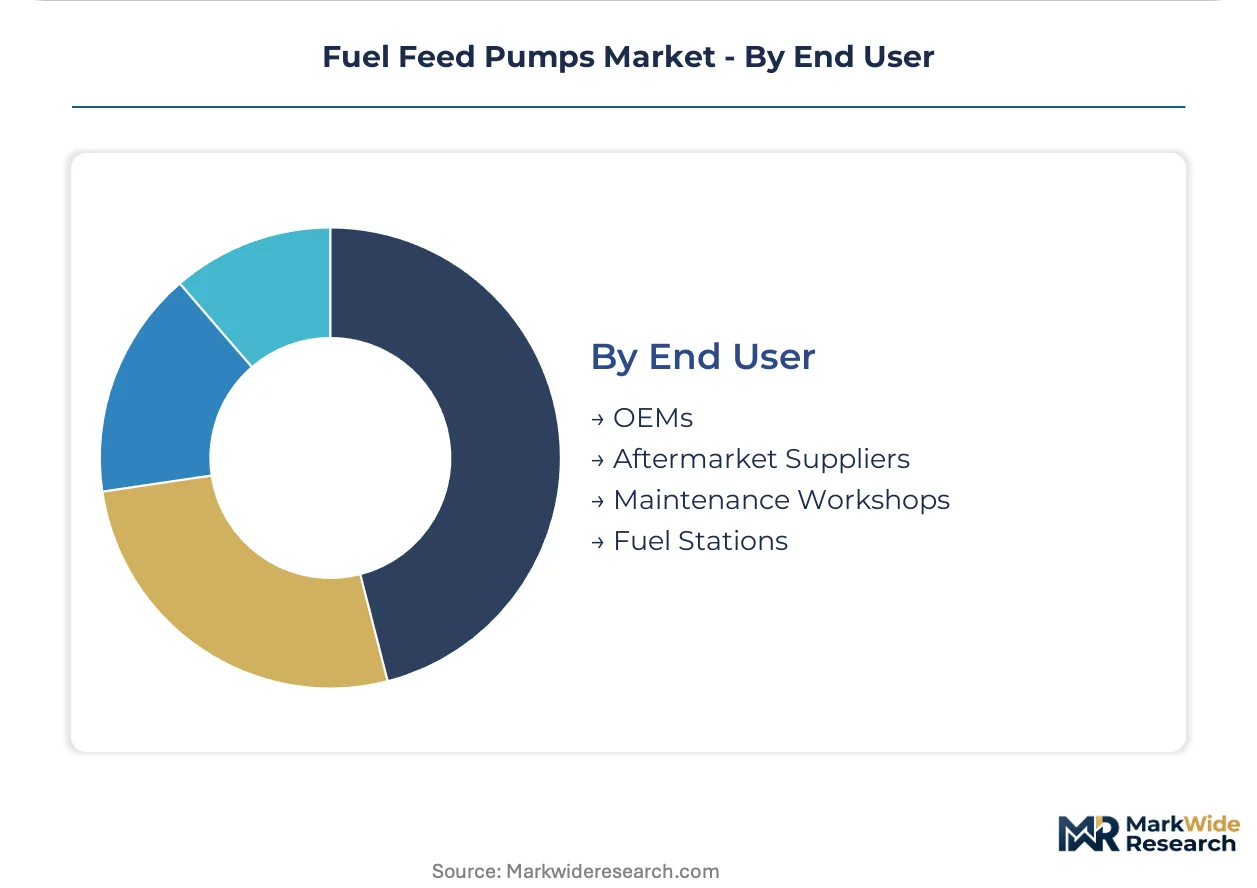
End User:
Customer type determines certification burden and channel structure, with OEMs demanding full system integration and aftermarket buyers prioritizing interchangeability and availability.
- OEMs:Vehicle and equipment manufacturers specify pump-fuel injection module bundles with embedded diagnostics. Chinese OEMs in Sichuan and Shandong provinces are localizing supply chains under domestic content mandates.
- Aftermarket Suppliers:Distributors and remanufacturers serve aging fleet replacement cycles through e-commerce platforms. Independent repair shops in the United States source Class 3-6 commercial vehicle pumps outside traditional dealer networks.
- Maintenance Workshops:Service bay operations require rapid-install cartridge designs minimizing labor time for field repairs.
- Fuel Stations:Underground storage tank transfer and dispenser supply pumps face EPA spill prevention and vapor recovery regulations.
OEMs command the established base. Direct aftermarket procurement channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian commercial vehicle buyers exhibit acute price sensitivity, driving mechanical pump procurement for cost-optimized platforms, while German OEMs absorb premium electric pump costs to meet EU Stage V mandates with minimal electronic complexity trade-offs.
United States
EPA Tier 4 Final retrofit cycles drive replacement demand across construction and agricultural fleets in Texas and the Midwest. Fleet operators unbundle pump procurement from full system service contracts, creating direct aftermarket channels. Precision-machining clusters in Michigan supply high-pressure diesel components for domestic OEM programs.
Germany
EU Stage V emission frameworks mandate sealed fuel systems with evaporative emission controls, forcing pump architecture redesigns. KBA type-approval audits integrate fuel-pump durability into broader powertrain compliance checks. Stuttgart and southern German machining clusters concentrate high-pressure pump housing production for common-rail diesel applications.
China
GB VI regulations tighten fuel-system tolerances for light-commercial platforms, pulling electric pump demand toward domestic OEM programs. MIIT localization mandates shift production capacity to Sichuan and Shandong manufacturing clusters. Domestic suppliers capture share from import-dependent architectures through backward integration into precision-machining operations.
India
PLI scheme incentives for component manufacturing open pump supply contracts for domestic bus and truck platforms. BIS certification requirements filter out unvalidated entrants from aftermarket channels. Maharashtra and Gujarat tractor manufacturers specify mechanical lift pumps for price-sensitive emerging-market price points.
Japan
METI efficiency standards accelerate brushless DC motor adoption in passenger vehicle start-stop systems. JIS certification timelines for smart pumps with diagnostic firmware extend under UN ECE R155 cybersecurity requirements. Kanto and Nagoya industrial corridors anchor fuel-injection module bundling strategies for Asian OEM programs.
Fuel Feed Pumps Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where precision-machining specialists coexist with high-volume electric pump assemblers. The vendor base fragments across three strategic groupings: integrated mechatronics conglomerates with captive semiconductor supply, regional mechanical pump fabricators serving price-sensitive agricultural markets, and emerging Asian suppliers leveraging domestic content mandates. Dominant competitive moves include backward integration into precision-machining operations and geographic expansion through joint ventures with local OEMs in China and India.
Among German-based integrated manufacturers, Robert Bosch GmbH and Continental AG occupy positions exemplifying the mechatronics conglomerate archetype, while DENSO Corporation represents the Asia-Pacific technology bundling model through thermal-management integration strategies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| DENSO Corporation |
| Continental AG |
| BorgWarner |
| Flowserve |
| Grundfos |
| Hitachi Automotive Systems |
| Marelli Holdings |
| MAHLE GmbH |
| Others |
Supply & Pricing Matrix
EU Stage V emission frameworks gate both supplier qualification and price differentiation simultaneously, as sealed-system certification requirements filter out unvalidated entrants while OEMs absorb premium costs for evaporative-control-compatible architectures. Tier 1 manufacturers bundle pump-fuel injection modules at fixed contract rates, while independent aftermarket channels face compressed margins on remanufactured electric units.
Pricing Analysis
Aftermarket parts and service contracts drive lifetime value in fuel feed pump commercialization. Three-tier pricing structure across premium, standard, and economy levels segments the market: premium tiers capture OEM bundled modules with embedded diagnostics, standard tiers serve replacement cycles through authorized distributors, and economy tiers flow through e-commerce platforms to independent repair shops. Price differentiation stems from certification grade—EPA Tier 4 Final and EU Stage V compliance tiers carry material premiums—and volume scale, with fleet procurement commanding 15-20 point discounts over single-unit aftermarket purchases. Pricing pressure stems from semiconductor input volatility concentrated in Taiwanese foundries, which is squeezing electric pump controller margins. Fleet operators in North American construction segments exhibit acute price sensitivity, while German OEMs absorb premium electric pump costs with minimal negotiation.
Supply Chain Analysis
Taiwan Strait semiconductor transit underwrites controller availability for brushless DC motor architectures, creating chokepoint exposure for electric pump production. Geographic supply concentrates in Germany for high-pressure precision-machined housings, China for electric pump final assembly serving domestic OEM programs, and Japan for fuel-injection module bundling. Raw material dependencies draw from automotive-grade MOSFETs, hardened steel alloys for piston architectures, and fluorocarbon elastomers for hydrogen-diesel compatibility testing. Single-source vulnerability runs through southern German machining clusters, where 200-bar validation capacity filters out Tier 2 competitors. Distribution runs through OEM direct procurement for new platforms, authorized distributor networks for replacement cycles, and emerging e-commerce channels for aging fleet segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across North American construction and agricultural segments is shifting buyer power toward direct procurement channels, unbundling pump replacement from full system service contracts and compressing distributor margins.
For Market Incumbents: Shield common-rail certification portfolios by deepening backward integration into precision-machining operations in southern Germany and Stuttgart industrial corridors, capturing margin that would otherwise flow to single-source housing suppliers. Reinforce channel control through exclusive service contracts with OEMs bundling pump-fuel injection modules, as fleet unbundling threatens aftermarket revenue concentration. Prioritize R&D investment in hydrogen-diesel dual-fuel elastomer compatibility to preempt substitution by magnetic drive architectures in marine genset retrofits. For New Entrants and Emerging Players: BIS certification fast-tracks for Indian commercial vehicle platforms open white-space supply contracts under PLI scheme incentives, as Maharashtra and Gujarat tractor manufacturers seek mechanical lift pump alternatives to incumbent import dependencies. Target marine genset electrification segments in Rotterdam and Singapore bunkering hubs, where IMO 2020 low-sulfur mandates drive electric pump adoption without entrenched supplier relationships. Penetrate through joint venture structures with Sichuan and Shandong manufacturing clusters, leveraging MIIT localization mandates to bypass import tariff exposure. For Investors and Strategic Acquirers: GB VI implementation reshapes the acquisition landscape by pulling production capacity toward Chinese domestic OEM programs and filtering out import-dependent architectures. Long-term viability across the analysis window favors targets with captive semiconductor supply and precision-machining backward integration, as input volatility and single-source vulnerability concentrate margin in vertically integrated mechatronics conglomerates. Watch hydrogen dual-fuel pilot scale-up as the inflection signal—elastomer compatibility testing volumes will indicate whether magnetic drive architectures displace conventional sealing systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Captures margin from southern German housing clusters while filtering Tier 2 competitors through 200-bar validation requirements. |
| Joint Venture with Chinese Domestic OEMs | Secures MIIT-mandated localization access in Sichuan and Shandong manufacturing corridors. |
| Hydrogen-Diesel Dual-Fuel Compatibility Certification | Preempts magnetic drive substitution in IMO 2020 marine genset retrofit cycles. |
| Aftermarket E-Commerce Channel Development | Captures fleet unbundling demand in Class 3-6 commercial vehicle segments outside traditional distributor networks. |
| Fuel-Injection Module Bundling Expansion | Locks OEM relationships through embedded diagnostics and thermal-management integration for Asian platform programs. |
Research Methodology
The analysis maps electric, mechanical, diaphragm, rotary, piston, and gear pump architectures, each validated through OEM procurement directors, aftermarket distributor operations managers, and fleet maintenance supervisors. Primary interviews with Tier 1 supplier engineering leads, precision-machining plant managers, and fuel-system compliance officers combined with secondary validation against EPA certification databases, EU type-approval registries, MIIT localization filings, and customs trade flow records. Bottom-up unit economics triangulated against top-down OEM production forecasts.
Consistency checks against vehicle production databases and off-highway equipment registration data anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, pressure specification tier, application duty cycle, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating fleet replacement cycles, emission compliance phase-in schedules, and powertrain electrification substitution rates. Industry-specific inputs span common-rail pump validation timelines and brushless DC motor adoption curves in start-stop systems.
The analysis sits within stated boundaries; outcomes outside EPA Tier 4 Final, EU Stage V, and GB VI compliance trajectories would require recalibration. Forecasts reflect assumptions on semiconductor supply normalization, precision-machining capacity expansion, and hydrogen dual-fuel pilot commercialization timelines. Practitioners should keep alternative scenarios live as battery-electric powertrain penetration in urban delivery segments and regulatory harmonization gaps between emission zones evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Dry Vacuum Pumps Market
Pumps and Control Devices
Double Diaphragm Pump Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market