
 Virtual Reality Camera Market | 2026-2036
Virtual Reality Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality Camera Market Intelligence
The bundling of VR cameras with proprietary stitching and editing software is rebalancing buyer choice away from hardware-only specifications. This integrated ecosystem approach allows companies like Insta360 to build customer loyalty. GoPro, Inc. differentiates through its focus on rugged, action-oriented 360-degree cameras. Meanwhile, Sony Corporation leverages its extensive optical engineering expertise to compete on sensor performance and image fidelity in professional segments.
A virtual reality camera is an imaging device with multiple lenses or sensors designed to capture a complete 360-degree spherical field of view. These devices stitch together footage from several image sensors to create seamless content for VR headsets and interactive platforms. Within product types, stereoscopic cameras are gaining traction for their ability to deliver true 3D depth perception. For end users, real estate firms and entertainment studios represent major demand centers for virtual tours and cinematic experiences.
The regulatory environment is shaped by data privacy rules like Europe's GDPR, which governs the collection of personal images in public spaces. In the United States, devices with wireless capabilities must comply with FCC regulations for radio frequency emissions. Intellectual property frameworks also dictate how 360-degree content can be created and monetized. Stakeholders must now decide whether to prioritize hardware innovation or invest in building comprehensive software ecosystems.
Market Dynamics
The market's primary structural force is the bifurcation between integrated software-hardware ecosystems and open hardware platforms competing on imaging specifications, creating distinct competitive arenas.
Growth Catalysts
- Sensor Fusion Advancement:Improved sensor fusion enhances image stabilization and positional tracking, enabling smoother, more immersive VR experiences.
- Corporate Training Adoption:Enterprises use VR cameras for realistic training simulations, reducing physical training costs and risks in manufacturing and aviation.
- Digital Infrastructure in South Korea:The country's hyper-connectivity and entertainment industry create concentrated demand for high-fidelity 360-degree content and cameras.
Market Restraints
- High Stereoscopic Camera Cost:The price of professional stereoscopic cameras limits their adoption to well-funded studios, hindering broader market access.
- Data Processing Overhead:High-resolution 360-degree video generates massive files, requiring substantial computing power and storage, a barrier for smaller creators.
- GDPR Compliance Friction:Europe's GDPR complicates capturing identifiable individuals in public spaces, creating legal hurdles for street and event videography.
Strategic Opportunities
- Telemedicine Applications:Specialized VR cameras for medical education can enable remote observation and training for complex surgical procedures.
- AI-Powered Content Analysis:Integrating AI with VR capture automates object recognition within footage, creating value for commercial and security applications.
- Real Estate Market Penetration:Expanding virtual tour tools beyond high-end listings to the broader rental market represents a significant growth vector.
Industry Challenges
- Stitching Algorithm Complexity:Achieving seamless, artifact-free stitching from multiple lenses, especially with moving subjects, remains a computational hurdle.
- Content Format Standardization:A lack of universal standards for 360-degree video causes compatibility issues between devices, software, and headsets.
- Specialized Talent Scarcity:A shortage of professionals skilled in 360-degree cinematography and its unique post-production workflows limits industry capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality Camera Market |
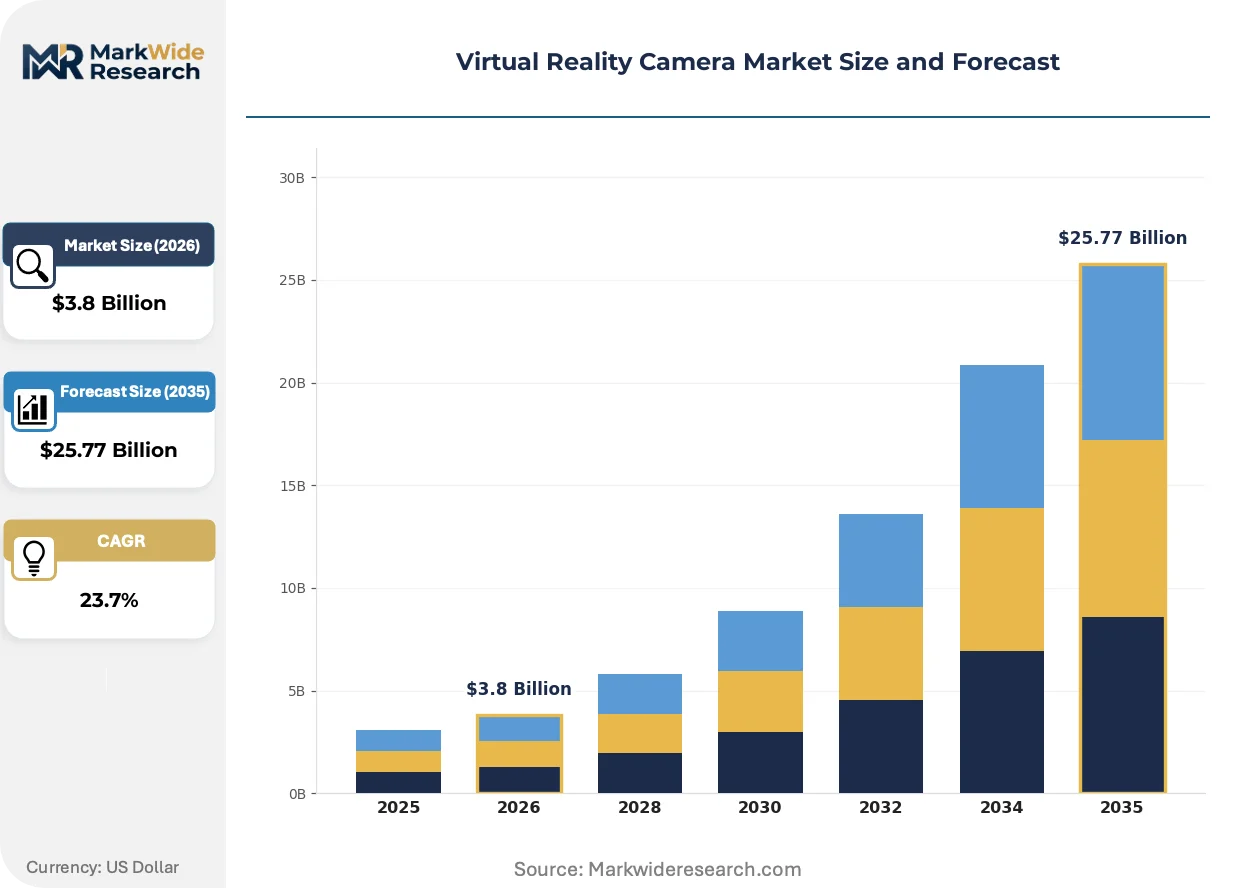
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $25.77 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoscopic Cameras, Stereoscopic Cameras, Omnidirectional Cameras, Multi-Lens Cameras Technology: Optical Tracking, Inertial Measurement Unit, Sensor Fusion, Simultaneous Localization and Mapping, Depth Sensing Use Case: Immersive Gaming, Virtual Tours, Architectural Visualization, Remote Collaboration, Training Simulations End User: Entertainment Studios, Educational Institutions, Real Estate Firms, Corporate Training Departments, Research Laboratories |
| Companies Covered | Insta360, GoPro, Inc., Canon Inc., Sony Corporation, The Ricoh Company, Ltd., Panocam3d, Eastman Kodak Co., Garmin Ltd., Nokia OZO technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality Camera Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from hardware specifications toward software-driven capabilities and cloud-based workflows. This transition changes the economics of content creation and distribution for immersive media.
On-device processing is being integrated into VR cameras for real-time stitching. Professional creators and live event producers adopt this to reduce latency and simplify on-site production. This shift is decentralizing the content workflow, reducing dependency on centralized post-production computing.
The US Federal Communications Commission (FCC) mandates compliance for radio frequency emissions from wireless VR cameras. This regulation forces manufacturers to manage signal interference, influencing hardware design and component selection. It primarily affects models with Wi-Fi or 5G sold in the US market.
Buyer behavior is moving from one-time content purchases toward subscription-based access for immersive experiences. This alters procurement for studios, which now seek camera systems supporting continuous content pipelines. This model is most advanced within entertainment and corporate training in North America.
Virtual Reality Camera Market Segmentation
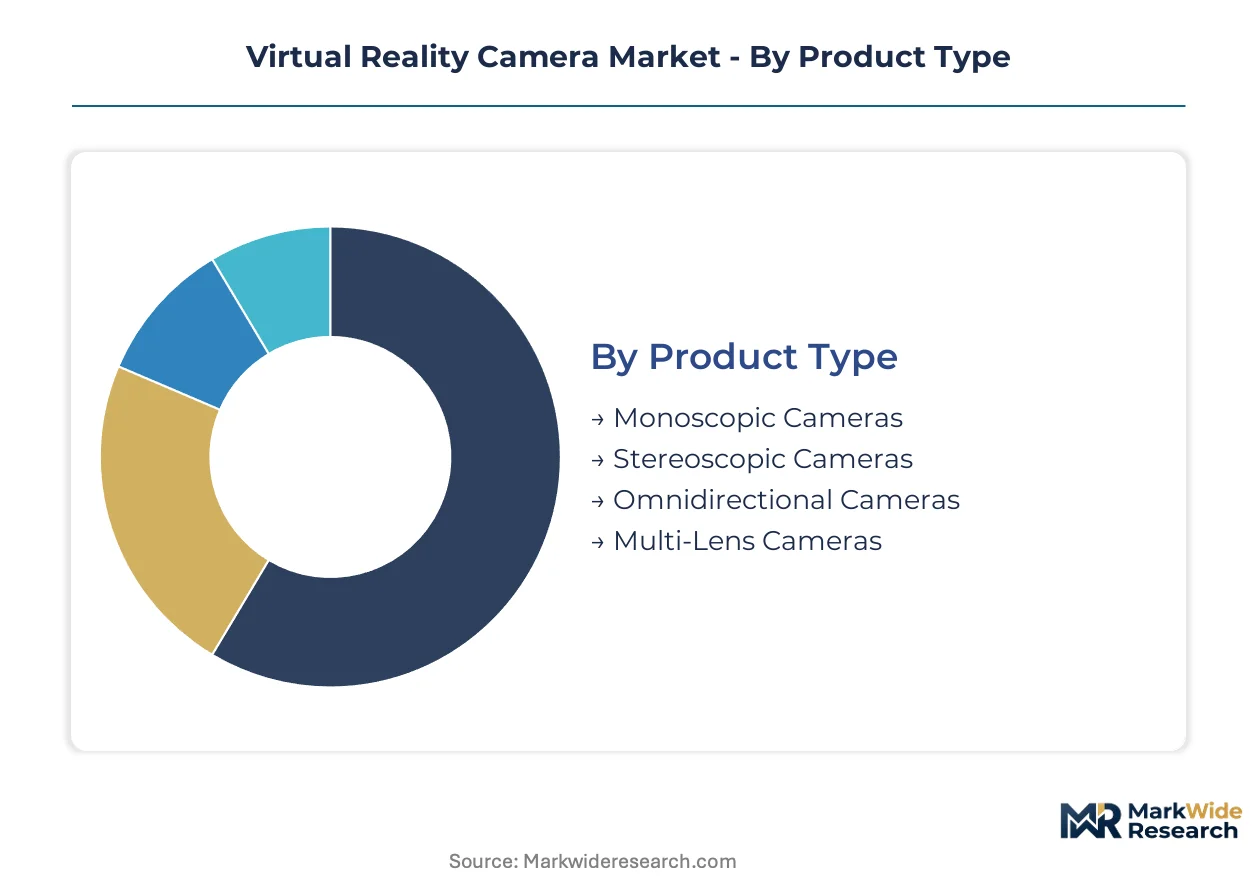
The virtual reality camera market segments across distinct product types, underlying technologies, diverse use cases, and varied end-user groups. Understanding these classifications reveals how specialized features and performance attributes cater to specific market demands and content creation workflows.
Product Type:
The product type segmentation highlights the spectrum from standardized capture solutions to highly customized multi-sensor arrays. Each type offers distinct capabilities for capturing immersive content.
- Stereoscopic Cameras:These cameras employ two lenses to simulate human binocular vision, capturing separate images for each eye to create true 3D depth perception. Demand for stereoscopic cameras concentrates in entertainment studios for cinematic VR experiences, driven by the need for enhanced realism and immersion.
- Multi-Lens Cameras:Integrating an array of individual camera modules, multi-lens cameras capture multiple overlapping fields of view that are then stitched together into a seamless 360-degree sphere. These systems are prominent in professional broadcasting and live event production, where high resolution and comprehensive coverage are paramount.
- Monoscopic Cameras:Capturing a single 360-degree image or video stream, monoscopic cameras provide a flat, spherical view without depth information. These devices are widely adopted for casual virtual tours and social media content due to their simplicity and lower cost.
- Omnidirectional Cameras:Designed to capture a full 360-degree view around a single point, omnidirectional cameras often use a single lens with a wide-angle or fisheye design. They find application in surveillance and basic immersive content creation.
Leading the category by volume: Monoscopic Cameras. Growing fastest: Stereoscopic Cameras.
Technology:
This category delineates the core technical approaches that enable VR cameras to capture, stabilize, and map their environment, directly influencing output quality and user experience.
- Sensor Fusion:This technology combines data from multiple sensors, such as gyroscopes, accelerometers, and magnetometers, to improve image stabilization and positional accuracy. Sensor fusion enhances the smoothness of VR experiences, particularly for dynamic content capture in sports and action videography.
- Simultaneous Localization and Mapping (SLAM):SLAM algorithms allow VR cameras to construct a map of an unknown environment while simultaneously tracking their own position within that map. This advanced technology is critical for creating interactive virtual environments and autonomous drone navigation.
- Optical Tracking:Optical tracking systems use visual data from cameras to determine the position and orientation of objects or the camera itself within a defined space. This technology is fundamental for precise motion capture and augmented reality overlays.
- Inertial Measurement Unit (IMU):An IMU contains accelerometers and gyroscopes to measure orientation, angular velocity, and linear acceleration. IMUs provide essential data for basic image stabilization and head tracking in VR applications.
- Depth Sensing:Depth sensing technologies, such as LiDAR or structured light, measure the distance to objects in a scene, creating a 3D point cloud. This capability is vital for realistic object interaction and environmental reconstruction in VR applications.
The evolution of camera capabilities strongly depends on advancements in Sensor Fusion and Simultaneous Localization and Mapping. These technologies enable more sophisticated and immersive virtual content creation.
Use Case:
The use case segmentation illustrates the diverse applications driving demand for VR cameras, from entertainment to professional training and visualization.
- Training Simulations:VR cameras create realistic immersive environments for corporate training, allowing employees to practice complex procedures in a safe, virtual setting. This application reduces physical training costs and risks in sectors like manufacturing and aviation.
- Virtual Tours:These applications utilize VR camera footage to provide immersive walkthroughs of physical spaces, enabling remote exploration. Real estate firms widely employ virtual tours for property showcases, enhancing buyer engagement.
- Immersive Gaming:VR cameras contribute to immersive gaming by capturing real-world environments or creating 360-degree video backdrops for interactive experiences. This enhances player presence and engagement within virtual worlds.
- Architectural Visualization:Architects and designers use VR cameras to create interactive 360-degree renderings of future buildings or spaces. This allows clients to experience designs before construction begins, aiding in decision-making.
- Remote Collaboration:VR cameras facilitate remote collaboration by capturing meeting spaces or work environments for virtual presence. This enables geographically dispersed teams to interact in a shared virtual space.
Demand for Training Simulations drives innovation, while Virtual Tours applications expand market reach, particularly within the real estate sector.
End User:
This segment categorizes the primary industries and organizations that leverage VR camera technology, each with unique requirements and content objectives.
- Real Estate Firms:These firms utilize VR cameras extensively for creating virtual property tours, allowing potential buyers to explore listings remotely. Virtual tours enhance client engagement and streamline the property viewing process.
- Corporate Training Departments:Corporate training departments adopt VR cameras to develop realistic simulations for employee skill development and safety protocols. This reduces the need for expensive physical training facilities and instructors.
- Entertainment Studios:Entertainment studios employ VR cameras for producing immersive cinematic experiences, 360-degree films, and interactive narratives. They require high-fidelity cameras capable of capturing complex scenes with professional-grade quality.
- Educational Institutions:Educational institutions use VR cameras to create virtual field trips, interactive learning modules, and immersive historical reconstructions. This technology provides engaging and accessible learning experiences for students.
- Research Laboratories:Research laboratories integrate VR cameras for various scientific applications, including documenting experiments, creating immersive data visualizations, and simulating complex phenomena. These cameras often require specialized optical configurations.
Real Estate Firms and Corporate Training Departments represent the largest revenue segments, with Educational Institutions demonstrating significant future potential for VR camera adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's advanced digital infrastructure, acting as a de facto innovation zone, significantly drives demand for virtual reality cameras. This concentration supports both content creation and technological advancement. Other key regions also exhibit strong growth patterns.
South Korea
South Korea's hyper-connectivity fuels demand for high-fidelity 360-degree content and cameras within its entertainment industry. The country's strong data privacy regulations, enforced by the MFDS, influence content capture practices. Seoul's entertainment industry and tech hubs concentrate significant VR camera development and adoption.
United States
Corporate training departments and entertainment studios in the United States drive substantial VR camera demand for simulations and cinematic experiences. Wireless VR cameras must comply with FCC regulations for radio frequency emissions before market entry. California's tech and media centers, particularly Silicon Valley, foster innovation in immersive content creation.
Japan
Japan's optical engineering expertise and robust gaming industry create demand for high-fidelity VR cameras and related technologies. METI guidelines for industrial product safety and performance apply to VR device manufacturing. Tokyo's vibrant entertainment sector and research laboratories represent significant end-user concentrations.
Germany
German corporate training departments in manufacturing and aviation utilize VR cameras for realistic simulations, reducing physical training costs. European GDPR compliance significantly impacts public space capture for German businesses and content creators. Bavaria's strong industrial base and research institutions foster advanced VR camera applications.
China
China's vast digital infrastructure and expanding entertainment sector generate substantial VR camera adoption across various applications. MIIT policies guide the development and deployment of advanced digital imaging technologies and network infrastructure. The Yangtze River Delta region, with its tech manufacturing hubs, drives both production and consumption.
Virtual Reality Camera Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a bifurcated market structure in virtual reality cameras. The market exhibits a clear split between companies emphasizing comprehensive software-hardware ecosystems and those competing on imaging specifications alone. Strategic archetypes include optical engineering powerhouses, action camera specialists, and integrated ecosystem providers. Dominant competitive moves involve strategic partnerships to expand content pipelines and continuous investment in sensor technology to improve performance.
Specialists in integrated ecosystems, such as Insta360, exemplify a strategy focused on bundling virtual reality cameras with proprietary stitching and editing software, building customer loyalty through seamless content creation workflows. GoPro, Inc., a United States-based corporation, represents the action-oriented segment, emphasizing ruggedness and portability for dynamic content capture in extreme environments. Sony Corporation, a Japanese optical engineering powerhouse, anchors the professional segment with its extensive expertise in sensor performance and image fidelity, catering to high-end cinematic and broadcast applications. These distinct approaches highlight the varied competitive vectors within the VR camera market.
| Leading Market Players |
|---|
| Insta360 |
| GoPro, Inc. |
| Canon Inc. |
| Sony Corporation |
| The Ricoh Company, Ltd. |
| Panocam3d |
| Eastman Kodak Co. |
| Garmin Ltd. |
| Nokia OZO technologies |
| Others |
Cost & Logistics Intelligence
US FCC regulations, mandating compliance for wireless VR cameras, gate qualified supply and access to premium pricing tiers. These regulations influence hardware design and component selection.
Pricing Analysis
Cost-down pressure on monoscopic cameras accelerates because of widespread adoption and increased competition. Pricing stratifies across professional stereoscopic systems, standard multi-lens cameras, and economy monoscopic devices. Sensor performance, image fidelity, and integrated software ecosystems drive significant price differentiation. Casual users of monoscopic cameras exhibit the highest price sensitivity, while entertainment studios prioritize advanced features and quality.
Supply Chain Analysis
Optical lens and image sensor supply for VR cameras rests heavily on East Asian manufacturing hubs. Japan, with its optical engineering expertise, and China, with its vast tech manufacturing, represent significant supply concentrations for critical components like specialized image sensors and high-precision optical lenses. Single-source vulnerability for advanced sensor technology poses a structural risk. Distribution runs through a mix of direct-to-consumer online channels and B2B integrators for professional systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virtual reality camera market is undergoing a technology-transition phase, with software-driven capabilities and cloud-based workflows displacing traditional hardware-centric approaches. This shift redefines content creation and distribution economics for immersive media.
For Market Incumbents: Anchor market share by deepening investment in proprietary software ecosystems and advanced sensor technology. Continuous R&D in sensor fusion and SLAM capabilities will counter emerging pure-play specialists. Consolidate professional segments through strategic partnerships with content platforms and post-production houses. This approach mitigates the threat of content format standardization issues.
For New Entrants and Emerging Players: The price-point gap between high-end stereoscopic cameras and entry-level monoscopic devices presents a market entry opportunity. Target underpenetrated segments like the broader real estate rental market and educational institutions with cost-effective, user-friendly solutions. Develop specialized VR cameras for telemedicine applications or AI-powered content analysis to create distinct value propositions. A subscription-based access model for immersive experiences can lower initial buyer friction.
For Investors and Strategic Acquirers: Broadening adoption rates of stereoscopic content in mainstream entertainment is the leading indicator that the market is maturing beyond niche applications. The virtual reality camera market exhibits strong long-term viability over the next decade, driven by expanding enterprise and consumer use cases. Prioritize acquisition targets that are integrated ecosystem providers or specialists in AI-powered content analysis and SLAM technologies. Monitor content format standardization efforts as a key inflection point for broader market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Proprietary Software Ecosystems | This initiative builds customer loyalty through seamless content creation workflows and enhances user retention. |
| Develop AI-Powered Content Analysis | Automates object recognition within captured footage, creating significant value for commercial and security applications. |
| Expand into Telemedicine Applications | Enables remote observation and training for complex surgical procedures, creating a high-value specialized niche. |
| Secure Key Component Supply Agreements | Mitigates single-source vulnerability for critical image sensors and optical lenses from East Asian manufacturers. |
| Promote Content Format Standardization | Addresses compatibility issues between devices, software, and headsets, fostering broader market adoption. |
Research Approach
Document review covered industry reports, company financial filings, and technology journals, complemented by interviews with industry stakeholders. Primary research included discussions with VR camera manufacturers, content creators, enterprise training managers, and real estate firms. This primary input was validated against secondary data sources and regulatory body publications from the FCC and GDPR. A bottom-up approach for market sizing was triangulated with top-down validation of market forecasts.
Historical market performance was cross-referenced with expert panel input to establish baseline figures and growth trajectories. The analytical framework modeled market dynamics across the analysis window, segmenting by Product Type, Technology, Use Case, End User, and Regional Adoption. Compound Annual Growth Rates were derived from an assessment of advancements in sensor fusion and corporate training adoption rates. This provided a robust projection for the virtual reality camera market.
Inputs from publicly available financial reports and regulatory filings were available through the study window; gaps in specific regional adoption data introduce uncertainty bands. Forecasts reflect assumptions concerning future regulatory shifts like GDPR and FCC, and the pace of technological obsolescence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Chemiluminescence Imaging Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
3D Sensing and Imaging Market
Imaging
Video Processing Solutions Market
Imaging
Global Computed Radiography Market
Imaging
Printed Image Sensors Market
Imaging
Document Imaging Market
Imaging
Acoustic Microscopy Market
Imaging
Infrared Imaging Software Market
Imaging
High Dynamic Range Market
Imaging
Europe Machine Vision Systems Market
Imaging
Europe IP Camera Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
Digitizer Market
Imaging
Japan Digital X-Ray Market
Imaging
Global Mobile Image Sensor Market