
 Canada Student Loan Market | 2026-2036
Canada Student Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Student Loan Market Insights
Professional students and graduate degree candidates is rotating toward larger principal balances as undergraduate dependency on federal grants stabilizes. RBC Bank leverages its integrated wealth management platform to cross-sell repayment products alongside disbursement. Scotiabank anchors its position through dedicated healthcare and law student lending programs. Nelnet Canada sustains market presence via servicing contracts with provincial loan authorities.
A student loan constitutes a term credit instrument extended to enrolled post-secondary learners, carrying fixed or floating interest rates tied to prime benchmarks, with amortization typically spanning ten years and provisions for interest-free grace periods during study. The instrument finances tuition, instructional materials, and living expenses for credential-seeking borrowers across Canadian universities, colleges, and technical institutes. Federal loans dominate origination volume given capped interest rates and income-contingent repayment flexibility, while private loans from bank lenders command wider spreads among borrowers exceeding federal caps. Income-based repayment plans are expanding fastest among servicing portfolios as borrowers prioritize cash flow management over accelerated amortization.
Health Canada and the Canada Revenue Agency shape borrower behavior through tax treatment of interest deductions and verification of enrollment status for in-study interest subsidies. Provincial regulators including Ontario's Ministry of Colleges and Universities and British Columbia's Ministry of Post-Secondary Education set tuition policy that directly inflates principal requirements. Stakeholders must monitor whether federal deficit reduction pressures trigger tightening of repayment assistance thresholds or interest subsidy phase-outs.
Market Dynamics
The Canada Student Loan Market is experiencing structural pressure from provincial tuition policy divergence, where Ontario and British Columbia's above-inflation fee trajectories are expanding borrower principal requirements faster than federal grant adjustments can offset.
Growth Catalysts
- Canada Student Financial Assistance Act:Federal income-contingent repayment provisions reduce default risk and sustain origination volumes among moderate-income borrowers.
- Healthcare and law degree seekers:Professional program enrollment in Ontario and Quebec is driving demand for supplemental private credit beyond federal caps.
- Integrated servicing platforms:Digital enrollment verification and automated repayment scheduling are reducing administrative friction for provincial loan authorities.
Market Restraints
- Federal interest subsidy costs:Parliamentary deficit reduction committees are reviewing in-study interest waiver expenditures, creating policy uncertainty for future borrowers.
- Provincial tuition coordination gaps:Ontario's Ministry of Colleges and Universities sets fee schedules without binding alignment to federal loan maximums, generating funding shortfalls.
- Private credit substitution limits:Bank lending to students without co-signers faces OSFI capital reserve requirements that constrain unsecured principal advances.
Strategic Opportunities
- Manitoba and Saskatchewan enrollment:Post-secondary participation rates in these provinces trail national averages, indicating origination growth potential as regional campuses expand capacity.
- Tax deduction optimization tools:Canada Revenue Agency interest deduction rules create white space for fintech-enabled repayment planning services.
- Blockchain credential verification:Distributed ledger technology for enrollment status confirmation could reduce provincial servicing costs and accelerate disbursement timelines.
Industry Challenges
- Repayment assistance eligibility determination:Provincial authorities operate divergent income thresholds and family size calculations, complicating national servicing standardization.
- Legacy mainframe integration:Federal and provincial loan systems operate on incompatible data architectures, obstructing real-time balance consolidation for borrowers with multi-jurisdictional debt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Student Loan Market |
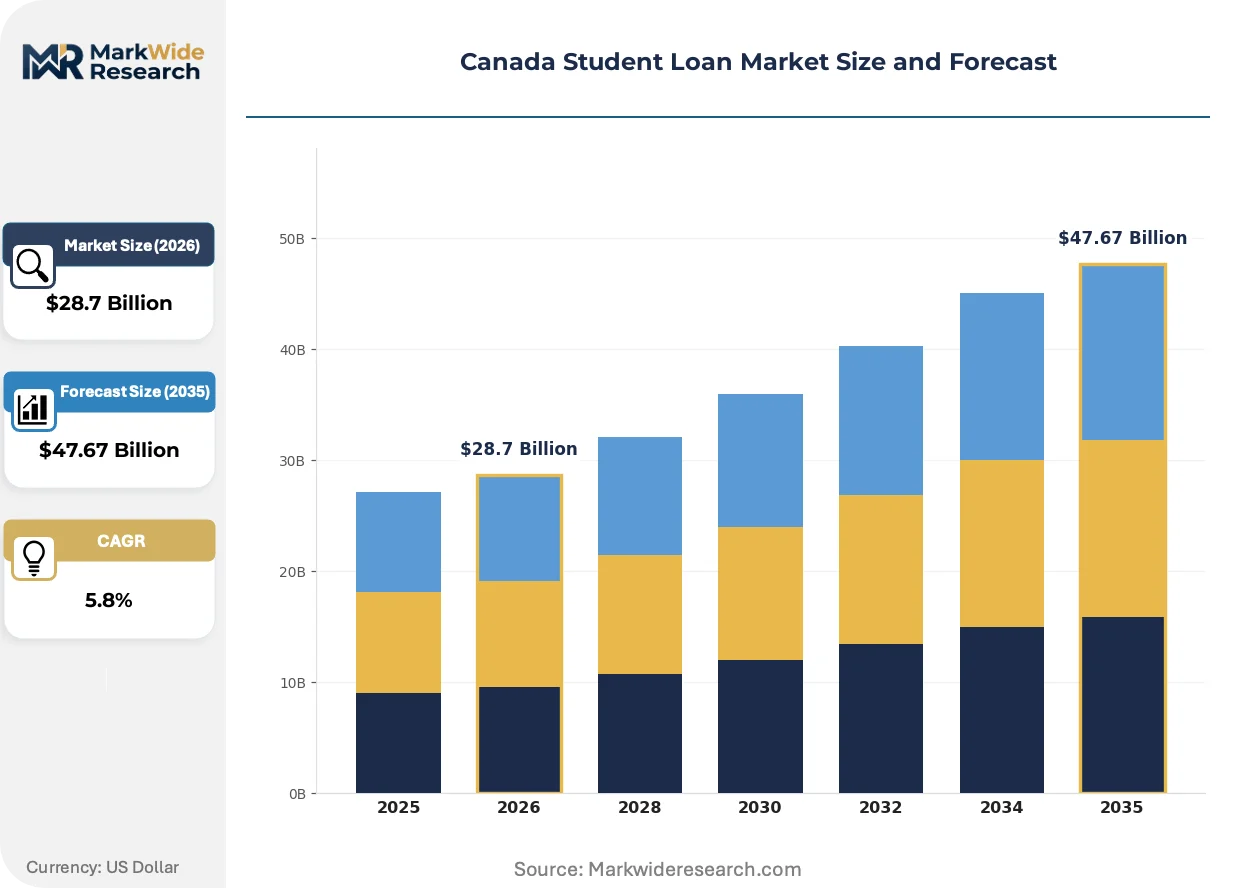
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $47.67 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Federal Loans, Provincial Loans, Private Loans, Hybrid Loans Repayment Plan: Income-Based Repayment, Standard Repayment, Deferred Repayment, Fixed Repayment Borrower Type: Undergraduate Students, Graduate Students, Professional Students, Part-Time Students Funding Source: Government Grants, Bank Loans, Credit Unions, Individual Sponsors |
| Companies Covered | RBC Bank, Scotiabank, Loans Canada, Nelnet Canada, TD Bank, CIBC Bank, HSBC Bank, Ontario Student Assistance Program, BMO Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Student Loan Market Trends and Innovations
Digital servicing infrastructure and borrower-facing financial wellness tools are displacing traditional call-center repayment management across Canadian provincial loan portfolios.
Artificial intelligence-powered default risk scoring is fragmenting traditional cohort-based repayment assistance allocation. Servicers including provincial authorities are deploying machine learning models that segment borrowers by predicted income trajectory rather than current balance or program type. This technology is fragmenting standardized repayment timelines into individualized schedules that compress traditional ten-year amortization for high-earning graduates while extending subsidized periods for others.
Health Canada and the Canada Revenue Agency are tightening enrollment verification protocols for in-study interest subsidy eligibility. The regulatory consequence is a documentation burden shift onto post-secondary registrars, who must now submit term-by-term confirmation through standardized electronic data interchange formats. Ontario and British Columbia institutions are responding fastest due to prior investments in student information system modernization, while Atlantic Canada campuses face compliance delays.
Borrower behavior is rotating toward income-driven repayment election at the expense of accelerated principal reduction. Federal loan recipients are prioritizing cash flow preservation over amortization speed, particularly in high-cost metropolitan markets where housing expenditures consume disposable income. This pattern concentrates among Toronto and Vancouver borrowers with professional degree credentials and delayed labor market entry.
Canada Student Loan Market Segmentation
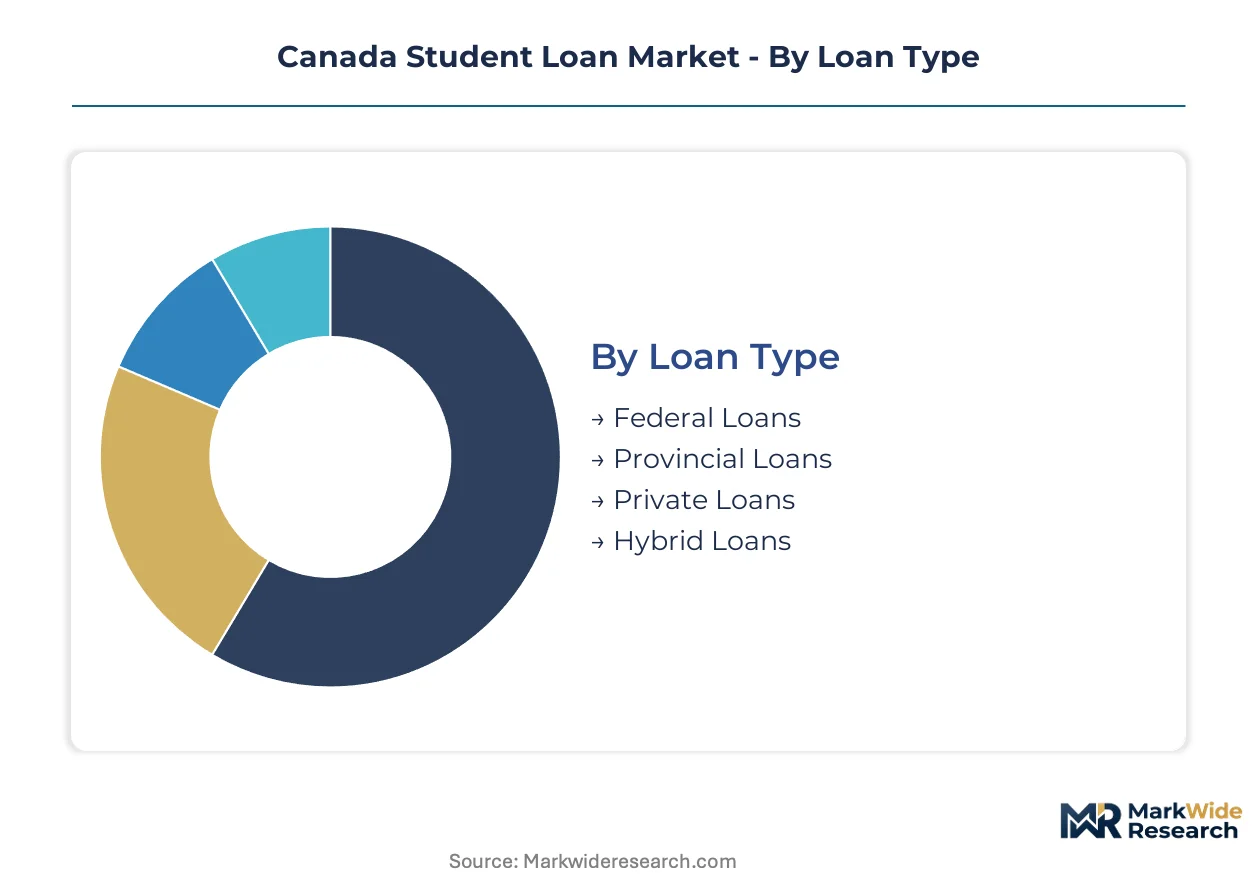
Segmentation in the Canada Student Loan Market reveals how capital flows concentrate across origination channels and borrower profiles. Understanding these divisions exposes where servicing costs escalate and where policy intervention reshapes eligibility.
Loan Type:
Federal loans capture the widest margin pools through interest subsidy mechanisms and volume-based servicing contracts with provincial authorities.
- Federal Loans:These instruments carry prime-linked floating rates with in-study interest waivers and income-contingent repayment provisions. Demand concentrates in Ontario and Quebec where enrollment density outstrips provincial funding capacity, driving borrowers toward federal caps.
- Provincial Loans:Administered by provincial finance authorities with jurisdiction-specific eligibility thresholds and repayment assistance frameworks. British Columbia and Ontario deploy the largest portfolios, though servicing costs run higher due to fragmented legacy systems.
- Private Loans:Bank-originated credit filling gaps above federal maximums, typically requiring co-signers or professional program enrollment.
- Hybrid Loans:Structured products combining federal disbursement with private supplemental tranches for professional degree candidates.
Federal loans hold installed capacity. Private loans are rotating up the share rankings.
Repayment Plan:
Plan selection patterns trace directly to post-graduation income trajectories and metropolitan cost-of-living pressures.
- Income-Based Repayment:Monthly obligations scale to borrower income thresholds with forgiveness provisions after defined periods. Toronto and Vancouver graduates with delayed professional licensure elect this option at elevated rates.
- Standard Repayment:Fixed amortization across ten-year schedules with predictable principal reduction. Alberta and Saskatchewan borrowers favor this structure due to lower housing costs preserving disposable income.
- Deferred Repayment:Principal and interest postponement during additional credential pursuit or economic hardship.
- Fixed Repayment:Locked monthly obligations regardless of income fluctuation, appealing to borrowers with stable public sector employment.
Standard repayment holds installed capacity. Income-based repayment is rotating up the share rankings.
Borrower Type:
Risk-adjusted returns vary sharply across credential levels, with professional programs commanding larger principal balances but exhibiting lower default frequency.
- Undergraduate Students:Federal grant dependency has stabilized among this cohort as Canada Student Grants expand coverage for moderate-income families. Ontario and British Columbia campuses generate the highest origination volumes.
- Graduate Students:Research-based and thesis-stream candidates accessing federal programs with extended interest-free periods. Quebec universities attract disproportionate enrollment in this category.
- Professional Students:Law, medicine, and dentistry candidates requiring supplemental private credit beyond federal maximums.
- Part-Time Students:Eligible for reduced federal disbursements with pro-rated repayment assistance thresholds.
Undergraduate students hold installed capacity. Professional students are rotating up the share rankings.
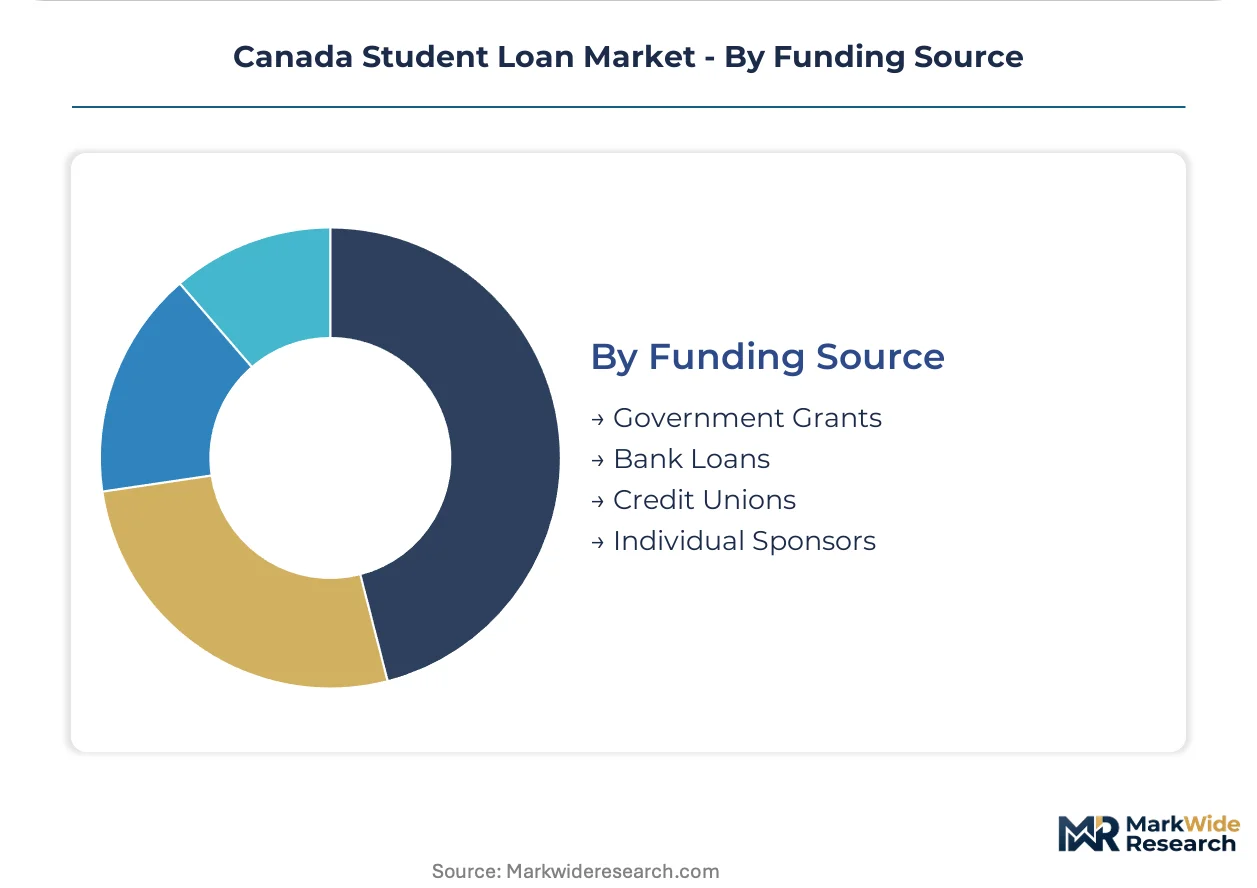
Funding Source:
Capital origination channels determine servicing economics and borrower flexibility throughout the repayment lifecycle.
- Government Grants:Non-repayable assistance disbursed through the Canada Student Financial Assistance Program. British Columbia and Ontario students receive the largest aggregate allocations.
- Bank Loans:Chartered bank credit products with wider interest spreads and stricter underwriting criteria. RBC and Scotiabank dominate professional program lending.
- Credit Unions:Member-owned institutions offering competitive rates in Manitoba and Saskatchewan where branch density supports relationship-based underwriting.
- Individual Sponsors:Family-arranged financing outside formal lending channels, common among international students ineligible for federal programs.
Bank loans hold installed capacity. Government grants are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital flows from federal disbursement centers in Ottawa toward provincial servicing authorities in Ontario and British Columbia, creating a trade-flow corridor that concentrates origination volume in high-tuition jurisdictions.
Ontario
The Ministry of Colleges and Universities sets fee schedules that outpace federal loan maximums, forcing borrowers toward supplemental private credit. The Ontario Student Assistance Program administers provincial disbursements alongside federal integration. Toronto's university corridor generates the densest concentration of professional degree lending in Canada.
British Columbia
Post-secondary enrollment density in Metro Vancouver drives demand for income-contingent repayment election. The Ministry of Post-Secondary Education coordinates with federal authorities on repayment assistance thresholds. Vancouver and Victoria campuses anchor the province's origination volume.
Quebec
Distinct provincial loan administration under the Aide financière aux études program maintains lower tuition trajectories than Ontario. The Ministère de l'Éducation et de l'Enseignement supérieur sets eligibility distinct from federal frameworks. Montreal's research-intensive universities attract disproportionate graduate student enrollment.
Alberta
Lower metropolitan housing costs relative to Toronto and Vancouver preserve disposable income for standard repayment election. Alberta Student Aid coordinates disbursement with federal integration. Calgary and Edmonton's technical institutes generate steady undergraduate origination flow.
Atlantic Canada
Post-secondary participation rates trail national averages, indicating origination growth potential as regional campuses expand capacity. Provincial loan authorities in Nova Scotia and New Brunswick operate legacy servicing systems requiring modernization. Halifax anchors the region's enrollment concentration.
Canada Student Loan Market Competitive Landscape
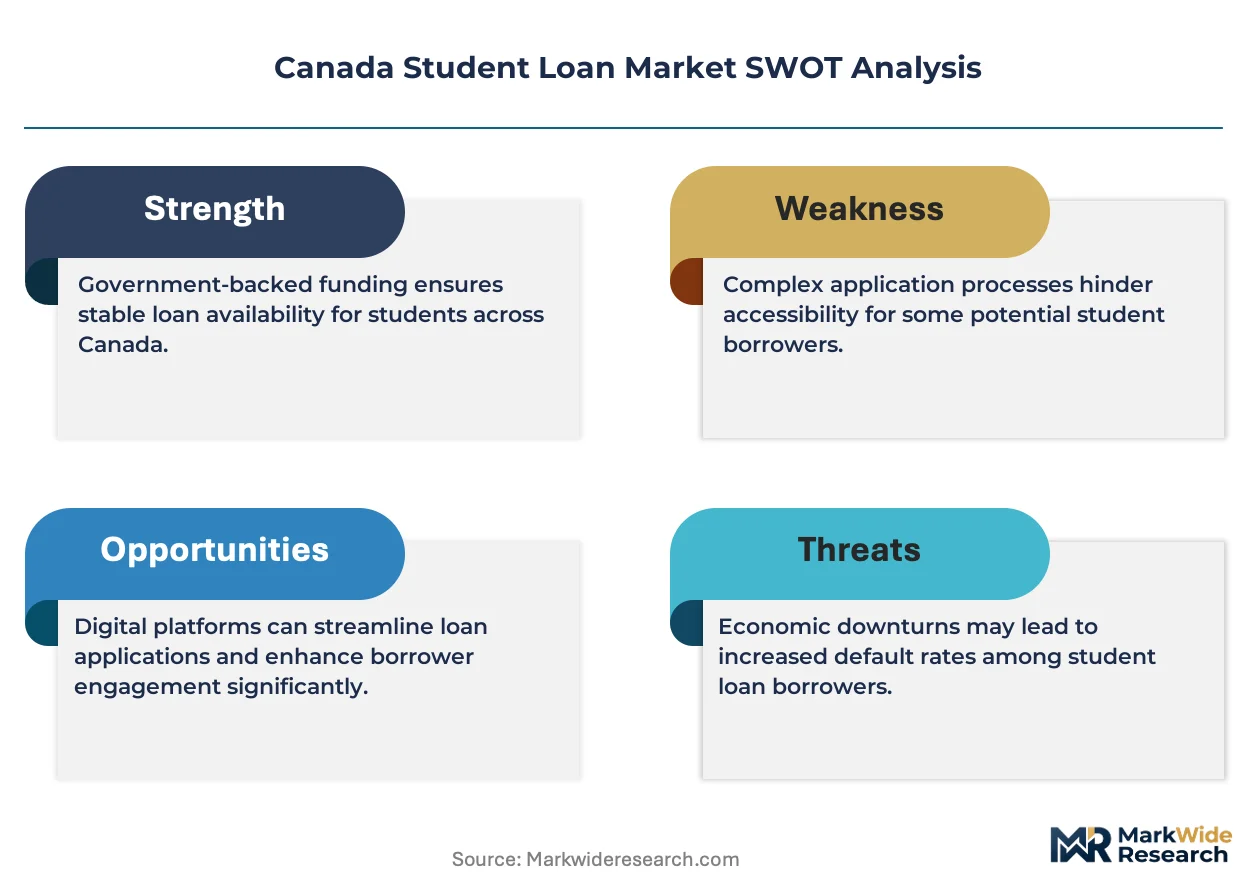
Listed leaders compete with private specialists across servicing contract allocation and direct lending origination. The market structures around chartered bank dominance in supplemental private credit and specialized servicers holding provincial administration contracts. Three archetypes prevail: integrated banking platforms, dedicated student lending specialists, and government-contracted servicers. Competitive moves concentrate on cross-selling wealth management products and securing multi-year provincial servicing agreements.
Within the integrated banking tier, RBC Bank and Scotiabank exemplify lenders leveraging full-service platforms to anchor borrower relationships beyond disbursement. Nelnet Canada occupies a position representing the government-contracted servicing archetype, maintaining presence through provincial authority partnerships. These three entities illustrate how market position derives from either balance sheet scale or administrative specialization rather than product differentiation alone.
| Leading Market Players |
|---|
| RBC Bank |
| Scotiabank |
| Loans Canada |
| Nelnet Canada |
| TD Bank |
| CIBC Bank |
| HSBC Bank |
| Ontario Student Assistance Program |
| BMO Bank |
| Others |
Pricing and Supply Chain Analysis
The Canada Student Financial Assistance Act gates both lender qualification and borrower-facing price differentiation, as federal interest-rate caps and in-study subsidy eligibility create tiered access that simultaneously constrains supply-side participation and segments pricing power across origination channels.
Pricing Analysis
Fixed-rate legacy loans versus prime-linked floating instruments versus next-generation income-contingent products define a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on borrower credit profile and co-signer backing, with professional program candidates commanding narrower spreads. Pricing pressure stems from federal deficit committees reviewing in-study interest waivers. Undergraduate borrowers in Ontario exhibit highest price sensitivity, while healthcare degree seekers demonstrate lowest.
Supply Chain Analysis
Provincial-federal data interchange chokepoints constrain disbursement velocity across Ontario, British Columbia, and Quebec servicing authorities. Capital origination draws from chartered bank balance sheets, Canada Mortgage and Housing Corporation securitization programs, and provincial treasury issuances. Single-source vulnerability concentrates in Nelnet Canada's servicing contracts with multiple provincial authorities. Distribution runs through integrated enrollment verification platforms linking post-secondary registrars to federal disbursement centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is expanding as borrower demand splinters across income-contingent repayment election, professional program supplemental credit, and fintech-enabled repayment planning tools.
For Market Incumbents: Compound defensible positioning through backward integration into proprietary enrollment verification technology and captive servicing capacity in Ontario and British Columbia. RBC Bank and Scotiabank face emerging fintech repayment optimizers eroding cross-sell margins. Priority lever rests on securing multi-year provincial servicing contract renewals before federal integration mandates accelerate. For New Entrants and Emerging Players: Anchor in Manitoba and Saskatchewan origination white space where post-secondary participation rates trail national benchmarks. Credit union branch density in these provinces supports relationship-based underwriting with lower customer acquisition costs than metropolitan bank channels. Go-to-market angle centers on tax deduction optimization tools targeting Canada Revenue Agency interest deduction complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital servicing infrastructure as provincial authorities accelerate mainframe modernization procurement. Long-term viability favors servicers with scalable cloud-native platforms over legacy system operators. Acquisition target archetype: fintech-enabled repayment planning specialists with Health Canada enrollment verification integration. Signal to watch is federal procurement announcements for integrated national servicing platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Provincial Servicing Contract Renewal | Multi-year agreements with Ontario Student Assistance Program secure revenue visibility against federal integration mandates. |
| Digital Enrollment Verification Platform | Health Canada-mandated electronic data interchange compliance reduces documentation friction for post-secondary registrars. |
| Income-Contingent Repayment Product Launch | Federal Canada Student Financial Assistance Program provisions expand addressable market among moderate-income borrowers. |
| Tax Optimization Tool Development | Canada Revenue Agency interest deduction rules create white space for borrower-facing fintech services. |
| Blockchain Credential Verification Pilot | Distributed ledger technology for enrollment status confirmation reduces provincial servicing costs and accelerates disbursement. |
Research Methodology
A standing panel of provincial loan authority administrators, chartered bank student lending product managers, post-secondary registrar enrollment officers, and fintech repayment platform developers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against Canada Student Financial Assistance Program disbursement data, provincial treasury borrowing reports, and Canada Revenue Agency tax expenditure publications. Bottom-up origination volume modeling and top-down macroeconomic triangulation anchored forecast consistency.
Outputs were validated against external benchmarks including Statistics Canada post-secondary enrollment projections and parliamentary budget officer expenditure forecasts. The analytical framework segmented across loan type, repayment plan structure, borrower credential level, and funding source throughout the projection horizon. CAGRs were derived from regression analysis of historical origination volumes against tuition cost trajectories and enrollment participation rates. Industry-specific forecast inputs incorporated federal grant expansion assumptions and provincial tuition policy divergence scenarios.
Decision-makers should treat outputs as directional under stable federal subsidy commitment and provincial tuition coordination assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as parliamentary deficit reduction committee recommendations and Health Canada enrollment verification protocol changes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
China Home Loan Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
Japan Mortgage/Loan Brokers Market
Loans and Leasing
Finance Lease Market