
 France Mortgage/Loan Brokers Market | 2026-2036
France Mortgage/Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
France Mortgage/Loan Brokers Market Insights
Buyer concentration among first-time homebuyers is pivoting toward digital-native millennials seeking streamlined approval pathways. Meilleurtaux leverages proprietary rate-comparison algorithms to sustain customer acquisition efficiency across urban centers. Empruntis anchors its position through extensive branch networks in secondary French cities. Pretto competes via fully automated pre-qualification workflows that reduce documentation friction.
A mortgage or loan broker functions as an intermediary that matches borrowers with suitable lending products while managing documentation, rate negotiation, and compliance verification across multiple financial institutions. The role requires certification under French banking regulations, with brokers obligated to maintain professional liability insurance and adhere to duty-of-care standards when advising clients. Residential loans occupy the largest service-type segment, reflecting sustained housing demand in metropolitan France and the persistent preference for fixed-rate stability among risk-averse borrowers. Online brokers represent the fastest-expanding broker model, capitalizing on consumer comfort with digital financial services and the operational cost advantages of automated underwriting platforms.
The Autorité de Contrôle Prudentiel et de Résolution (ACPR) supervises broker licensing and conduct standards, while the European Central Bank's interest rate decisions directly shape product affordability and origination volumes. French consumer protection statutes, including the Loi Lagarde provisions on broker fee transparency, constrain pricing flexibility and mandate clear disclosure of lender remuneration arrangements. Stakeholders must monitor regulatory proposals around digital identity verification and open-banking integration that could reshape client onboarding economics.
Market Dynamics
The European Central Bank's interest rate trajectory compresses origination margins while simultaneously triggering refinancing waves that reshape broker revenue mix toward rate-comparison services.
Growth Catalysts
- First-time buyer subsidies:French government schemes targeting young professionals in the Île-de-France region sustain elevated inquiry volumes for mortgage intermediation services.
- Open banking APIs:PSD2-mandated data sharing protocols enable automated income verification that slashes documentation timelines for loan applicants.
- Digital identity frameworks:France Connect integration is expanding into broker onboarding workflows, reducing KYC friction and abandonment rates.
Market Restraints
- ECB policy volatility:Rapid interest rate adjustments create product-pricing mismatches that erode broker commission predictability.
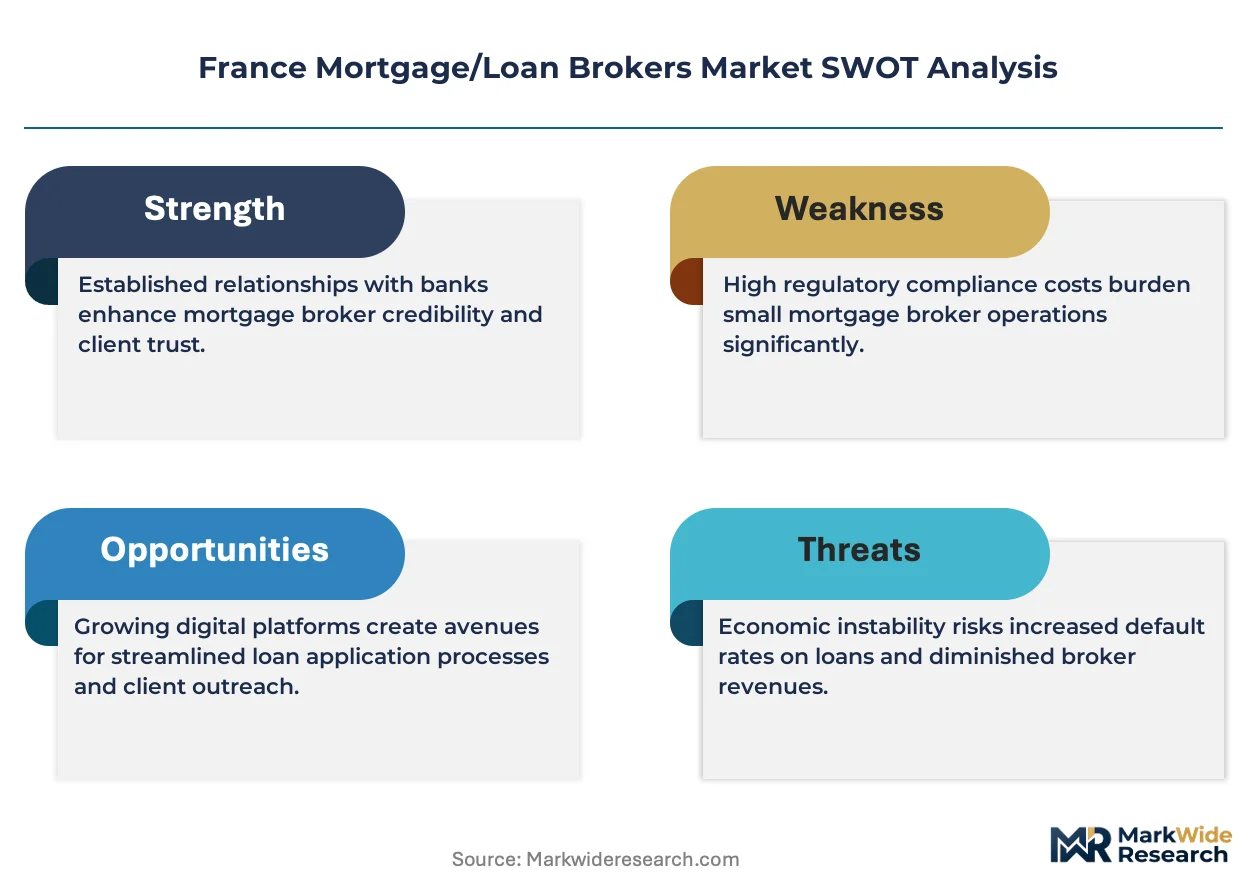
- Branch network fixed costs:Traditional broker models carrying physical locations in secondary cities face margin compression against digital-only competitors.
- Regulatory disclosure mandates:Loi Lagarde fee-transparency requirements constrain pricing flexibility and compress revenue per transaction.
Strategic Opportunities
- Secondary city digitization:Broker platforms that automate pre-qualification capture underserved demand in Lyon, Marseille, and Toulouse metropolitan zones.
- Green mortgage products:Energy-efficiency renovation loans tied to MaPrimeRénov incentives open specialized advisory revenue streams.
- Embedded finance partnerships:API integrations with property listing platforms and notary services create distribution channels beyond traditional search.
Industry Challenges
- Certification bottlenecks:ACPR licensing requirements and continuing education obligations limit talent pool expansion during demand surges.
- Legacy system interoperability:Bank-specific submission portals fragment broker workflow automation and elevate operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Mortgage/Loan Brokers Market |
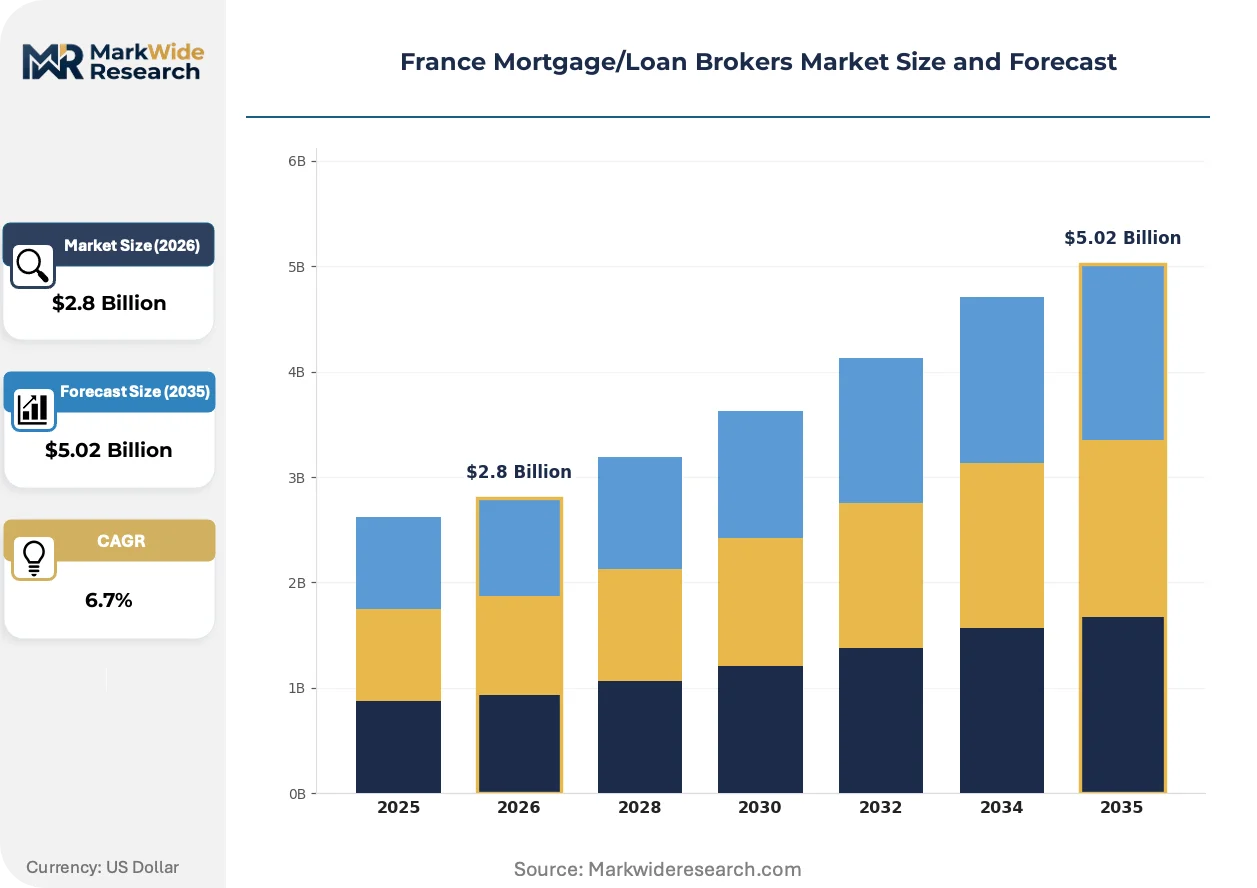
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Loans, Commercial Loans, Refinancing, First-Time Buyer Programs Client Type: Individual Borrowers, Real Estate Investors, Corporations, Financial Institutions Loan Type: Fixed-Rate Mortgages, Variable-Rate Mortgages, Interest-Only Loans, FHA Loans Broker Model: Independent Brokers, Bank-Sponsored Brokers, Online Brokers, Franchise Brokers |
| Companies Covered | Meilleurtaux, Empruntis, CAFPI, Pretto, Vousfinancer, AB Courtage, Immoprêt, Monemprunt.com, BoursedesCrédits, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Mortgage/Loan Brokers Market Trends and Innovations
Digital-native intermediation models are compressing traditional branch-based broker economics while regulatory data-sharing mandates unlock new automation layers across the French lending ecosystem.
Automated underwriting engines powered by open-banking data feeds are expanding into the pre-qualification phase of residential mortgage origination. Young professional borrowers in Paris and Lyon metropolitan areas adopt these platforms at accelerating rates. This technology is expanding into secondary markets previously served only by face-to-face advisory relationships.
France's transposition of EU Digital Operational Resilience Act (DORA) requirements imposes cybersecurity and third-party risk standards on financial intermediaries. Broker platforms must now certify cloud infrastructure and API vendor resilience before ACPR licensing renewal. Smaller digital brokers face disproportionate compliance costs relative to scaled competitors.
Subscription-based advisory models are displacing traditional success-fee structures among affluent borrower segments seeking ongoing rate-monitoring services. Wealth management divisions of retail banks and independent fintech platforms capture this demand through annual retainers. This shift concentrates in the Île-de-France region where property transaction frequency supports recurring revenue economics.
France Mortgage/Loan Brokers Market Segmentation
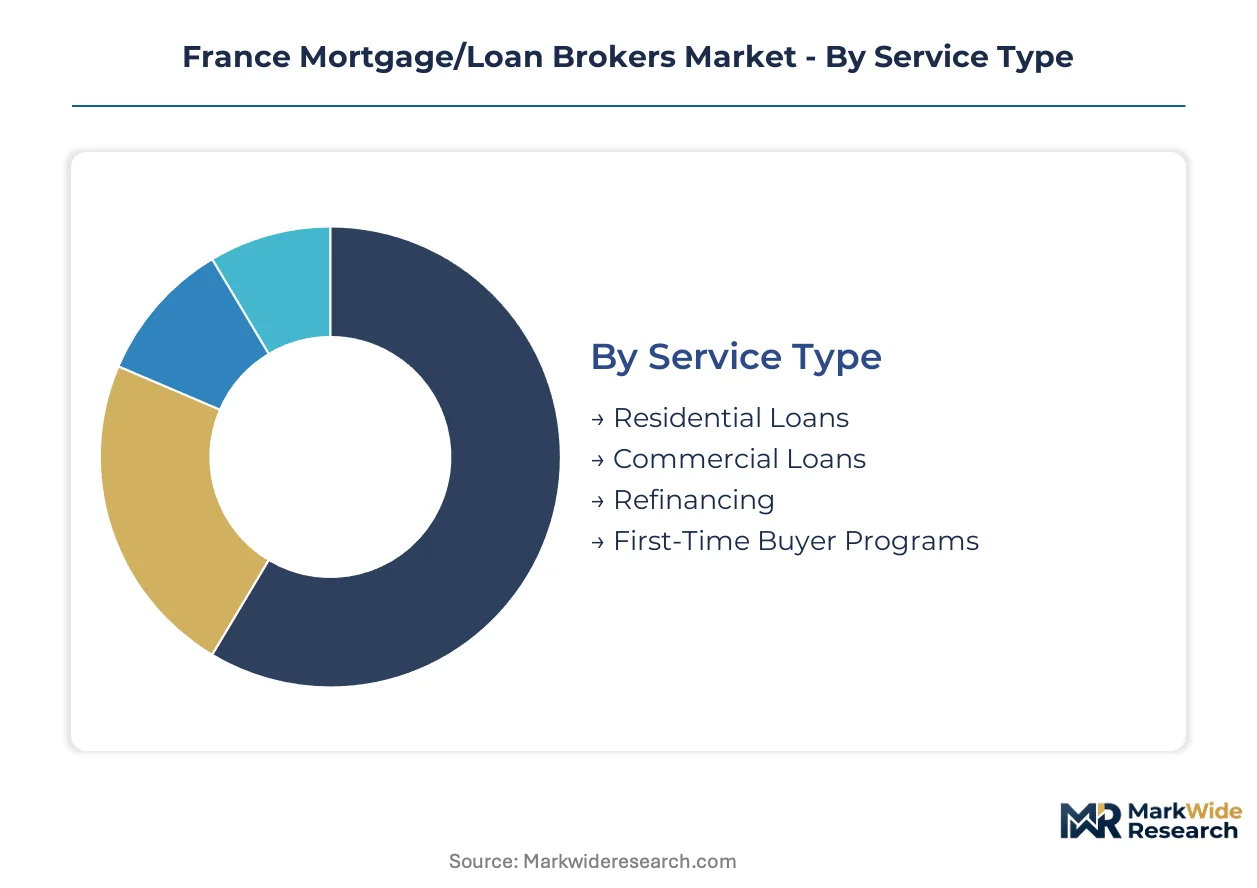
Segmentation in the France mortgage broker market reveals divergent capital requirements and operational architectures across service lines. Broker platforms must align infrastructure investments with the specific documentation intensity and regulatory scrutiny attached to each segment category.
Service Type:
Capital intensity peaks with refinancing operations due to rate-monitoring technology investments, while first-time buyer programs demand heavier compliance staffing.
- Residential Loans:Fixed-rate and variable-rate mortgage products for primary residences dominate broker transaction volumes. Île-de-France households generate the heaviest inquiry flows, with ACPR disclosure mandates extending documentation timelines.
- Commercial Loans:Income-producing property financing requires specialized underwriting expertise and higher professional liability coverage. Lyon and Marseille commercial corridors sustain concentrated demand from small-scale real estate investors.
- Refinancing:Rate-comparison services trigger ECB policy sensitivity.
- First-Time Buyer Programs:Government-subsidized schemes for young professionals in Paris metropolitan zones.
Most installed capacity flows through Residential Loans. Expansion is steepest in Refinancing.
Client Type:
Real estate investors command premium advisory fees, while individual borrowers drive platform scale economics through volume aggregation.
- Individual Borrowers:First-time buyers and homeowners seeking primary residence financing constitute the core demand base. Paris and Lyon metropolitan areas concentrate digital-native millennials demanding automated pre-qualification pathways.
- Real Estate Investors:Portfolio holders and small-scale landlords require complex leverage structuring across multiple properties. Secondary cities including Toulouse and Nice attract investor-focused broker specialization.
- Corporations:Commercial property acquisition and development financing.
- Financial Institutions:Intermediary services for institutional lending arrangements.
Revenue concentration sits with Individual Borrowers. Margin expansion is strongest in Real Estate Investors.
Loan Type:
Fixed-rate products lock brokers into longer servicing relationships, while variable-rate offerings demand active rate-monitoring infrastructure.
- Fixed-Rate Mortgages:Long-term rate stability products preferred by risk-averse French households. Île-de-France borrowers dominate origination volumes, with ECB rate volatility amplifying demand for payment predictability.
- Variable-Rate Mortgages:Rate-indexed products tied to Euribor benchmarks offering lower initial payments. Young professionals in Paris metropolitan zones accept repricing risk for improved short-term affordability.
- Interest-Only Loans:Payment structures deferring principal amortization.
- FHA Loans:Government-backed financing for credit-constrained borrowers.
Transaction volume concentrates in Fixed-Rate Mortgages. Digital adoption is advancing fastest in Variable-Rate Mortgages.
Broker Model:
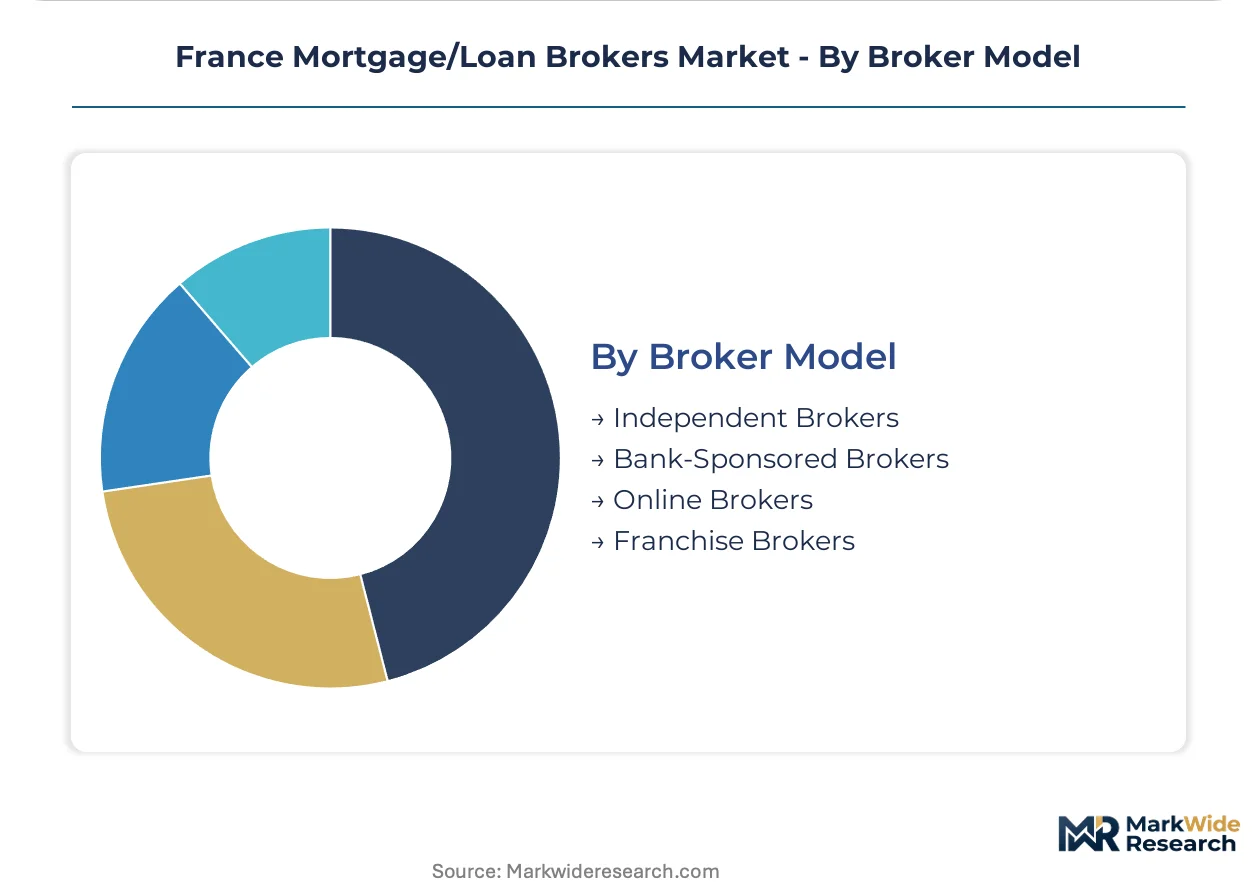
Online platforms achieve lowest marginal cost per application, while franchise networks carry the heaviest fixed-cost burden from physical footprint maintenance.
- Online Brokers:Fully digital intermediation platforms leveraging automated underwriting and open-banking APIs. Pretto and similar operators capture accelerating demand from Paris and Lyon metropolitan borrowers seeking frictionless documentation.
- Independent Brokers:Solo practitioners and small partnerships maintaining direct lender relationships. Secondary cities including Bordeaux and Lille sustain independent operator density through localized advisory relationships.
- Bank-Sponsored Brokers:Captive distribution channels tied to specific lending institutions.
- Franchise Brokers:Networked operations under shared branding and compliance frameworks.
Customer acquisition efficiency favors Online Brokers. Regulatory compliance scale advantages concentrate in Franchise Brokers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's mortgage intermediary sector operates under tighter capital requirements than France, while Spain's broker market remains more fragmented with stronger regional banking ties. Both countries illustrate how national regulatory frameworks shape competitive dynamics differently across European mortgage distribution.
Île-de-France
Paris metropolitan borrowers drive the highest transaction volumes through digital-first platforms seeking automated pre-qualification. The ACPR enforces strict broker licensing and disclosure standards under Loi Lagarde provisions. Young professionals in Paris and inner suburbs concentrate demand for first-time buyer programs with streamlined documentation workflows.
Auvergne-Rhône-Alpes
Lyon anchors the second-largest regional mortgage origination cluster with accelerating adoption of online rate-comparison tools. Local brokers face margin pressure from Paris-based digital platforms expanding into secondary markets. The metropolitan zone attracts investor-focused advisory services for small-scale rental property portfolios.
Provence-Alpes-Côte d'Azur
Nice and Marseille sustain independent broker density through face-to-face advisory relationships with affluent retirees and seasonal property investors. France Connect integration is reducing KYC friction for digital onboarding in coastal markets. Secondary cities in the region lag Paris and Lyon in automated underwriting adoption.
Hauts-de-France
Lille and surrounding industrial zones generate steady refinancing demand tied to ECB rate volatility and household payment optimization. Traditional branch-based brokers maintain stronger market position here than in southern metropolitan areas. The region shows slower penetration of fully digital mortgage platforms compared to Île-de-France.
Nouvelle-Aquitaine
Bordeaux's property market attracts first-time buyers from Paris seeking lower entry prices, sustaining broker inquiry volumes. Local independent operators compete through personalized advisory rather than technology investment. The region exhibits lower concentration of bank-sponsored broker networks than northern France.
France Mortgage/Loan Brokers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the French mortgage intermediary sector. The market structure shows moderate consolidation at the top tier alongside persistent fragmentation among regional independents. Three strategic archetypes dominate: algorithm-driven digital platforms, branch-network incumbents with secondary city density, and independent practitioners leveraging localized relationships. Competitive moves center on API-based distribution partnerships and automation investments that compress origination timelines.
Within the digital-native tier, Pretto exemplifies fully automated pre-qualification workflows, while Meilleurtaux anchors rate-comparison efficiency through proprietary algorithms. Empruntis occupies a position representing branch-network resilience across secondary French cities. These three operators illustrate how technology intensity and physical footprint serve as alternative vectors for customer acquisition in a market where regulatory disclosure requirements constrain pricing differentiation.
| Leading Market Players |
|---|
| Meilleurtaux |
| Empruntis |
| CAFPI |
| Pretto |
| Vousfinancer |
| AB Courtage |
| Immoprêt |
| Monemprunt.com |
| BoursedesCrédits |
| Others |
Pricing and Supply Chain Analysis
ACPR certification costs and professional liability insurance premiums flow through broker fee structures, with digital platforms compressing these overheads into lower per-transaction pricing tiers than branch-network incumbents can match. The spread between online and traditional broker margins reflects this input cost divergence.
Pricing Analysis
Capacity additions in digital underwriting infrastructure are reshaping price floors across the French mortgage intermediation sector. Three-tier pricing structure across premium advisory, standard intermediation, and economy digital-only levels separates white-glove service bundling from automated rate-comparison tools. Price differentiation hinges on documentation intensity and after-sales rate-monitoring inclusion. Cost compression in economy tiers is intensifying because open-banking APIs slash manual verification labor. First-time buyers in Paris metropolitan zones exhibit highest price sensitivity, while affluent real estate investors in Lyon and Marseille accept premium fees for complex leverage structuring.
Supply Chain Analysis
Certified broker workforce availability in Île-de-France and Auvergne-Rhône-Alpes determines service capacity expansion limits. France draws from ACPR-accredited training pipelines in Paris, Lyon, and Toulouse for licensed intermediary talent. Technology vendors supplying automated underwriting engines and open-banking API middleware concentrate in French fintech clusters and broader European financial technology hubs. Single-source vulnerability sits with legacy bank-specific submission portals that fragment workflow automation. Distribution runs through direct digital platforms, independent branch networks, and embedded finance partnerships with property listing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France mortgage broker market compounds steadily as ECB rate volatility perpetuates refinancing cycles and rate-comparison demand. Residential property transaction frequency in metropolitan zones sustains intermediary service utilization regardless of cyclical turns.
For Market Incumbents: Cement market position by acquiring ACPR-licensed broker talent pools in secondary cities where certification bottlenecks constrain competitor expansion. Deepen backward integration into proprietary rate-monitoring technology to defend margin position against pure-play digital platforms. Prioritize France Connect integration completion before regulatory deadlines to lock in onboarding efficiency advantages over smaller digital entrants facing disproportionate compliance costs.
For New Entrants and Emerging Players: PSD2-mandated open banking in France opens a window for API-native platforms to capture first-time buyer segments in Lyon, Marseille, and Toulouse where automated pre-qualification penetration lags Paris. Target green mortgage advisory white space tied to MaPrimeRénov energy renovation incentives, a segment underserved by incumbent generalist brokers. Deploy embedded finance partnerships with notary services and property listing platforms as primary go-to-market channel rather than competing for direct search traffic against established rate-comparison brands.
For Investors and Strategic Acquirers: Consolidation pressure builds where ACPR compliance costs and DORA cybersecurity mandates disproportionately burden sub-scale digital brokers. Frame long-term viability around recurring revenue migration from transaction fees to subscription-based rate-monitoring retainers among affluent Île-de-France borrowers. Target acquisition archetype: regional independent brokers in Hauts-de-France and Nouvelle-Aquitaine with localized lender relationships and untapped digital transformation potential. Monitor ECB policy pivot timing as inflection signal for refinancing volume resurgence.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Pre-Qualification Platform Deployment | Pretto-style frictionless onboarding captures millennial borrowers in Paris and Lyon metropolitan zones. |
| Open Banking API Integration | PSD2-mandated data feeds slash documentation timelines and abandonment rates for loan applicants. |
| Green Mortgage Product Specialization | MaPrimeRénov-tied advisory services open specialized revenue streams in energy renovation financing. |
| Embedded Finance Partnership Expansion | API integrations with SeLoger and notary platforms create distribution beyond traditional search channels. |
| Subscription Advisory Model Migration | Annual retainers for ongoing rate-monitoring displace success-fee dependency among affluent borrowers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mortgage broker principals, ACPR regulatory affairs specialists, bank distribution heads, and fintech platform executives with secondary validation. Bottom-up transaction volume modeling and top-down macroeconomic calibration anchored the analytical framework. Secondary sources included ACPR licensing databases, ECB monetary policy communications, French consumer protection statute filings, and open-banking API provider technical documentation.
Segment-weighting approaches distributed value and volume estimates across service type, client archetype, loan structure, and broker model dimensions throughout the forecast period. CAGRs derived from historical origination trajectory analysis and policy-sensitive scenario modeling. Forecast inputs incorporated ECB rate path assumptions, first-time buyer subsidy program enrollment trends, and digital platform adoption velocity in secondary metropolitan zones.
Revisions become necessary when ECB policy trajectory shifts, ACPR regulatory framework changes, or open-banking technical standard evolutions materialize outside baseline assumptions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
North America Used Car Financing Market