
 UK Car Loan Market | 2026-2036
UK Car Loan Market Size, Share, and Industry Trends Forecast 2026-2036
UK Car Loan Market Insights
UK captive finance arms is broadening their direct-to-consumer digital origination platforms. Black Horse leverages its parent bank's branch network to sustain high street visibility for used vehicle financing. Close Brothers Motor Finance anchors its position in the independent dealer channel through specialized floorplan and retail lending products. Santander Consumer UK competes aggressively on PCP pricing for volume brands distributed through franchised networks.
A car loan is a secured or unsecured credit instrument collateralized by a vehicle, governed by APR disclosure requirements, fixed or variable interest schedules, and term structures typically spanning 12 to 60 months, designed to transfer vehicle ownership or usage rights from lender to borrower. Its primary commercial purpose is to bridge the liquidity gap between consumer savings and automotive acquisition costs while generating interest income for originators. Hire Purchase and PCP structures dominate origination volumes, with PCP commanding disproportionate margin contribution due to residual value management fees and end-of-term renewal conversion economics. Personal Loan segments serve higher-credit borrowers seeking outright ownership, though this channel faces compression from dealer-captive alternatives.
The Financial Conduct Authority enforces Consumer Duty standards mandating clear affordability assessments and fair value demonstrations across all regulated credit agreements. The Prudential Regulation Authority supervises capital adequacy and stress-testing requirements for bank-owned lenders such as Barclays Partner Finance and Nationwide Building Society. Stakeholders must monitor how the FCA's ongoing review of motor finance discretionary commission arrangements reshapes broker-lender economics and consumer pricing transparency.
Market Dynamics
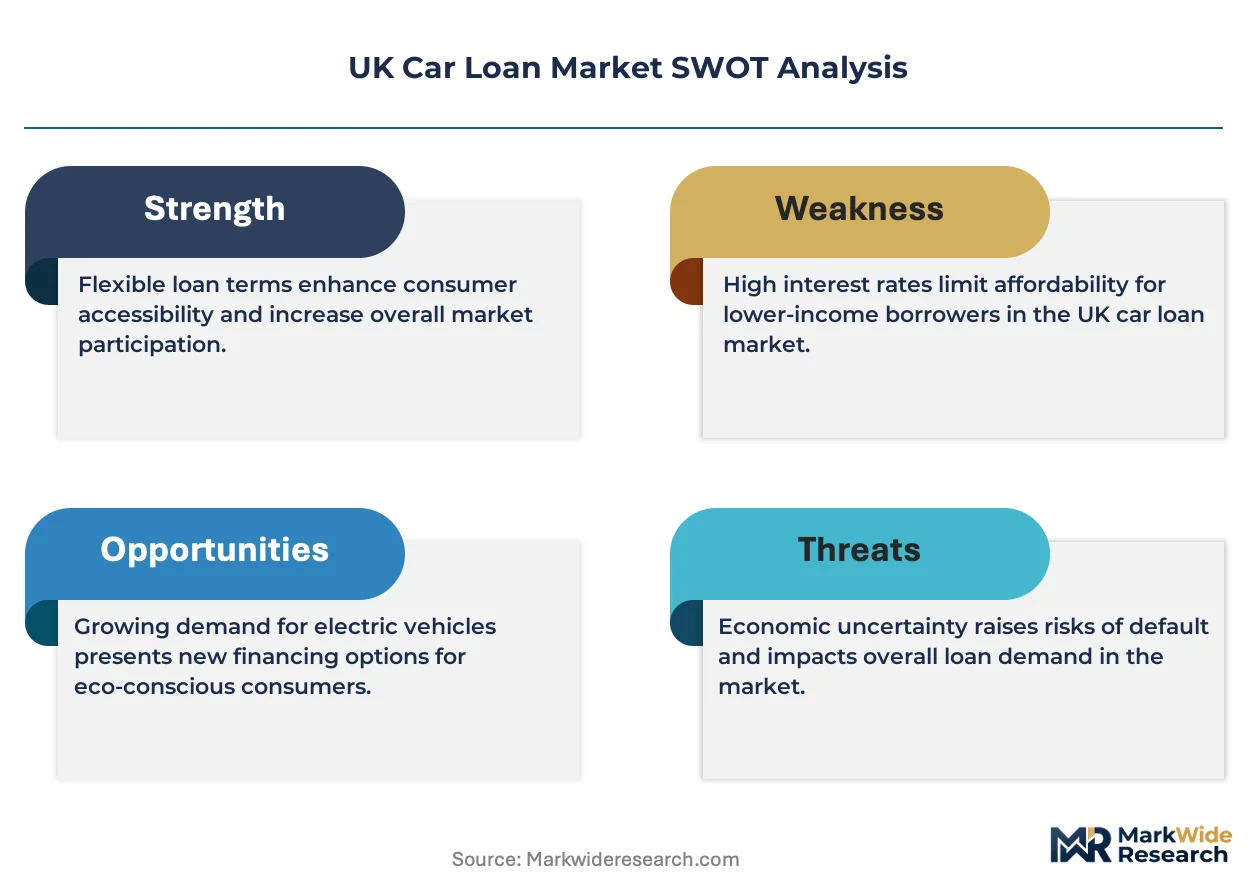
The Financial Conduct Authority's Consumer Duty rules are compressing broker-lender economics while forcing originators to rebuild affordability assessment infrastructure. This regulatory pressure is reshaping how captives and independents structure commission arrangements and price transparency.
Growth Catalysts
- Used car captive finance expansion:Independent dealerships are building in-house lending arms to capture margin from retail origination. This vertical integration reduces dependency on third-party funders.
- FCA Consumer Duty compliance investment:Lenders upgrading systems for fair value demonstration are gaining regulatory goodwill and operational clarity. Early movers secure distribution partnerships locked out from slower competitors.
- Personal Contract Purchase residual value management:Sophisticated RV forecasting tools are enabling competitive monthly pricing. Captive finance arms monetize end-of-term renewal economics through guaranteed future value structures.
Market Restraints
- Interest rate volatility transmission:Bank of England base rate movements compress net interest margins faster than lenders can reprice back-books. Fixed-rate PCP products expose originators to funding cost mismatches.
- Dealer network concentration in England's metropolitan counties:Origination volumes cluster in Greater London, Greater Manchester, and West Midlands. Geographic dependency creates systemic exposure to regional economic shocks.
- Discretionary commission arrangement scrutiny:The FCA's ongoing review threatens broker remuneration models. Lenders face retroactive remediation costs and forward pricing uncertainty.
Strategic Opportunities
- Digital direct-to-consumer origination platforms:Captive finance arms can bypass dealer networks entirely. Santander Consumer UK and Black Horse are building proprietary acquisition channels.
- EV-specific financing products:Battery electric vehicle residual value uncertainty creates demand for manufacturer-backed guarantees. Lenders can structure battery health certification into PCP terms.
- Scotland and Wales dealer network penetration:Used car finance penetration lags England's metropolitan corridors. Specialized floorplan and retail products tailored to independent dealer economics can capture underserved volume.
Industry Challenges
- Affordability assessment automation:Open banking integration and real-time income verification require substantial IT capex. Legacy core banking systems constrain deployment velocity.
- Residual value forecasting model recalibration:Post-pandemic used vehicle price volatility invalidated historical depreciation curves. Lenders must rebuild RV databases with compressed historical windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Car Loan Market |
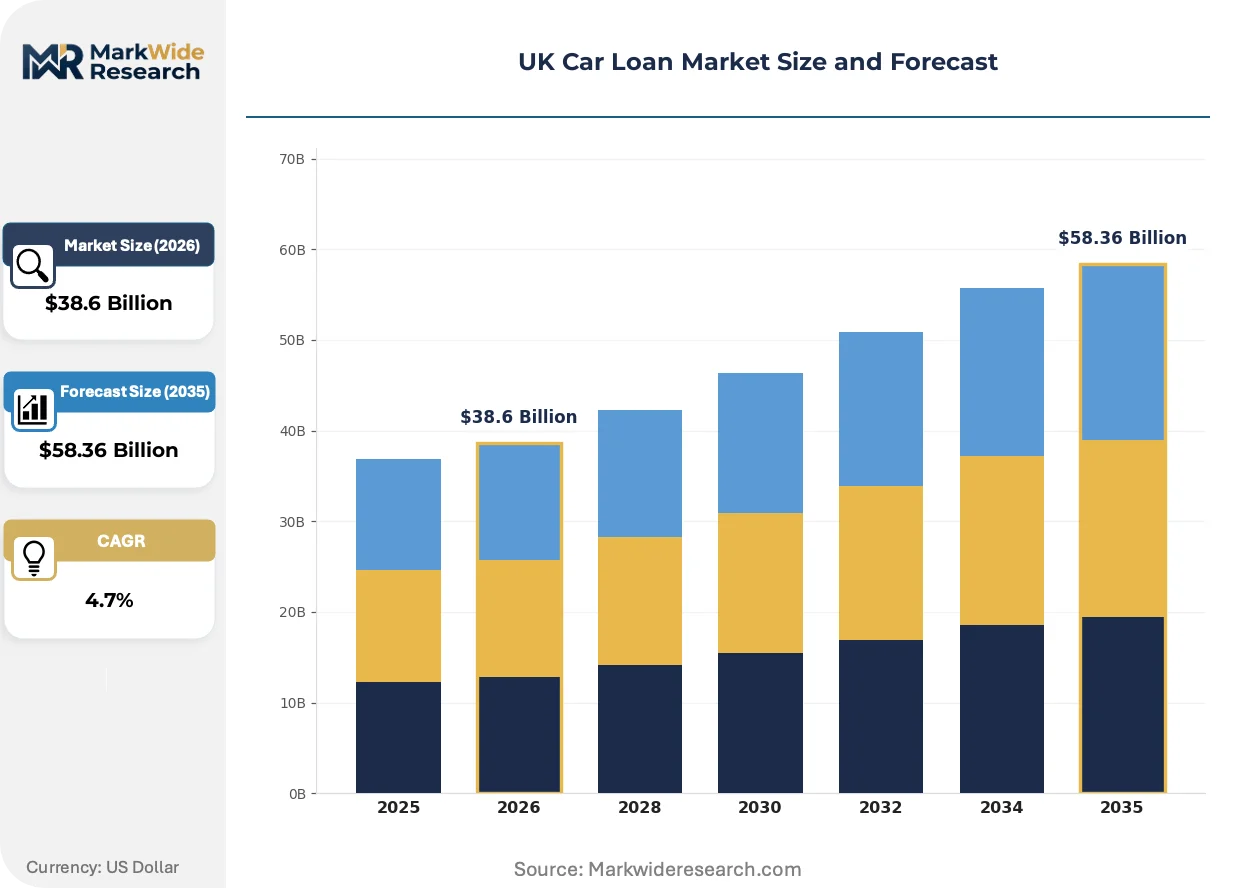
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Personal Loan, Business Loan, Hire Purchase, PCP Customer Demographic: First-Time Buyers, Existing Owners, Business Fleet, Student Buyers Credit Score Range: Excellent, Good, Fair, Poor Loan Duration: Short-Term, Medium-Term, Long-Term, Flexible |
| Companies Covered | Black Horse, Close Brothers Motor Finance, Santander Consumer UK, MotoNovo Finance, Northridge Car Finance, Barclays Partner Finance, Nationwide Building Society, Blue Motor Finance, Moneybarn, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Car Loan Market Trends and Innovations
Digital origination infrastructure is unifying previously fragmented credit decision workflows. Lenders are converging on API-first platforms that embed affordability checks into dealer point-of-sale systems.
Embedded finance orchestration layers are unifying credit bureau pulls, open banking verification, and automated underwriting into single-call workflows. Tier-2 and tier-3 independent dealers are adopting these platforms fastest. The technology is compressing time-to-yes from hours to minutes, shifting competitive advantage from rate to speed.
The FCA's Consumer Duty rules are mandating explicit fair value demonstrations across all regulated credit agreements. Lenders must document how product pricing aligns with customer outcomes. PCP products with complex residual value structures face the steepest compliance redesign requirements.
Buyer concentration is shifting toward prime-rated borrowers seeking outright ownership alternatives. Personal loan channels are losing share to dealer-captive PCP products with lower monthly payments. This preference rotation is most visible in England's home counties where household leverage sensitivity runs highest.
UK Car Loan Market Segmentation
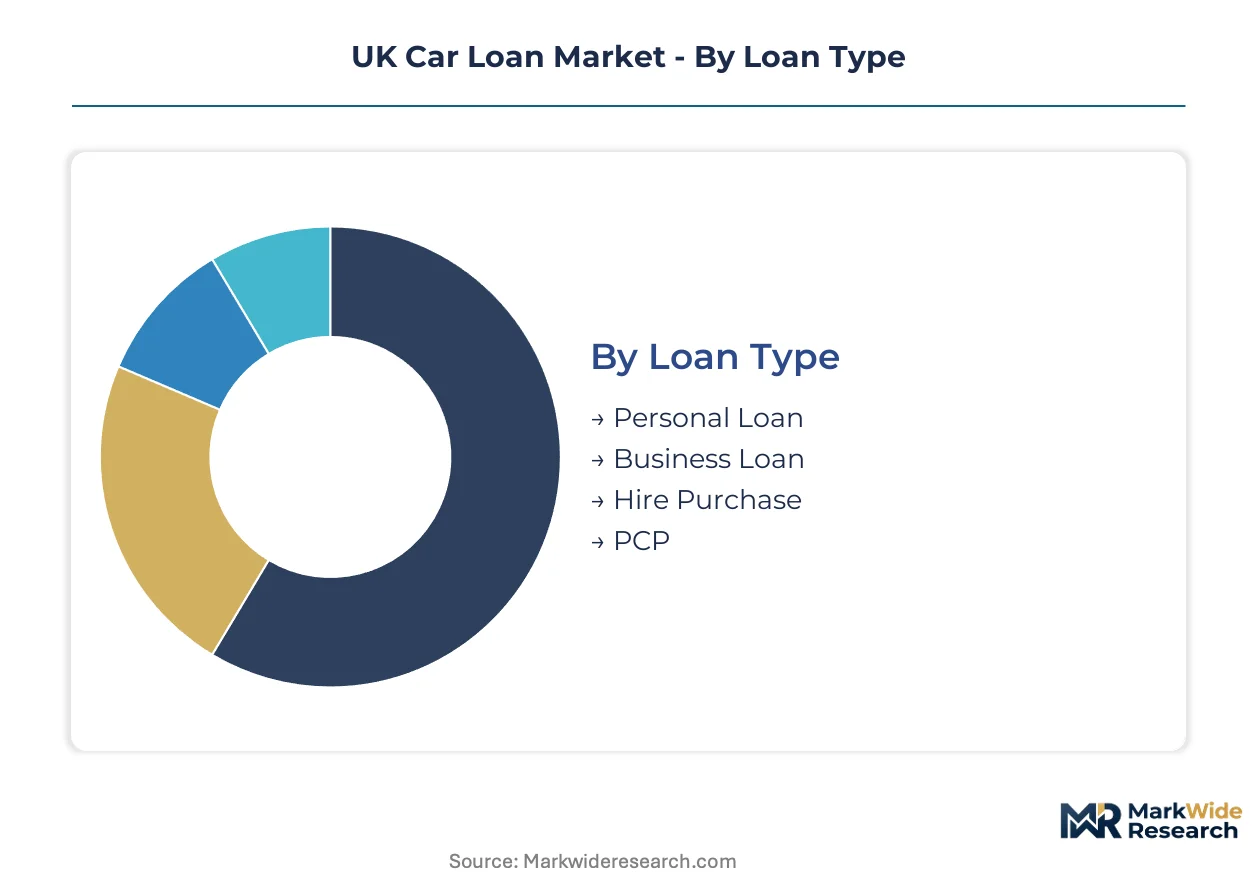
Segmentation in the UK car loan market determines lender pricing power, distribution channel selection, and regulatory compliance intensity. Each dimension creates distinct risk-return profiles that shape capital allocation across originators.
Loan Type:
Capital intensity varies sharply across structures, with residual value exposure requiring the most sophisticated balance sheet management.
- Personal Loan:Unsecured credit instruments with fixed APR schedules and no vehicle collateral requirement. Demand concentrates among prime-rated borrowers in England's home counties who seek outright ownership and avoid dealer-captive dependency.
- PCP:Secured agreements featuring guaranteed future value structures and balloon payment mechanics. Metropolitan dealerships in Greater London and Greater Manchester push PCP volumes hardest, driven by monthly payment affordability and captive finance margin capture.
- Hire Purchase:Traditional ownership-transfer structure with fixed monthly payments and no residual value risk to borrower. Independent dealers favor HP for subprime penetration.
- Business Loan:Fleet-focused origination with VAT recovery mechanics and accelerated depreciation benefits. SME lessors in West Midlands generate concentrated demand.
PCP absorbs the bulk of installed capacity; Personal Loan is expanding most quickly among credit unions and challenger banks.
Customer Demographic:
Margin profiles diverge by acquisition cost and default probability, with repeat customers offering the lowest cost-to-serve.
- Existing Owners:Proven payment history and trade-in equity reduce underwriting friction. Refinancing activity clusters in England's metropolitan corridors where vehicle turnover rates run highest.
- Business Fleet:Multi-vehicle agreements with centralized credit decisions and bulk pricing negotiations. Fleet managers in Greater Manchester prioritize total cost of ownership metrics over headline rates.
- First-Time Buyers:Thin-file applicants requiring enhanced affordability verification under FCA Consumer Duty rules. Digital brokers capture this segment through open banking integration.
- Student Buyers:Guarantor-backed structures with parental income support. University towns in Scotland and Wales show rising penetration.
Existing Owners dominate current origination volumes; Business Fleet is climbing the fastest as SMEs rebuild vehicle pools.
Credit Score Range:
Regulatory scrutiny intensifies at the subprime boundary, where fair value demonstration becomes most contested.
- Excellent:Prime-tier borrowers qualifying for sub-5% APR and minimal dealer markup. Competition from direct-to-consumer platforms is fiercest here.
- Good:Near-prime segment with rate dispersion driven by lender funding cost differences. Building societies target this tier aggressively.
- Fair:Mid-tier applicants facing affordability assessment automation requirements. Open banking verification reduces friction.
- Poor:Deep subprime with specialized non-bank originators and higher regulatory remediation exposure. FCA discretionary commission review threatens broker economics.
Good and Excellent tiers command the majority of balance sheet allocation; Fair is gaining share fastest as lenders deploy alternative data models.
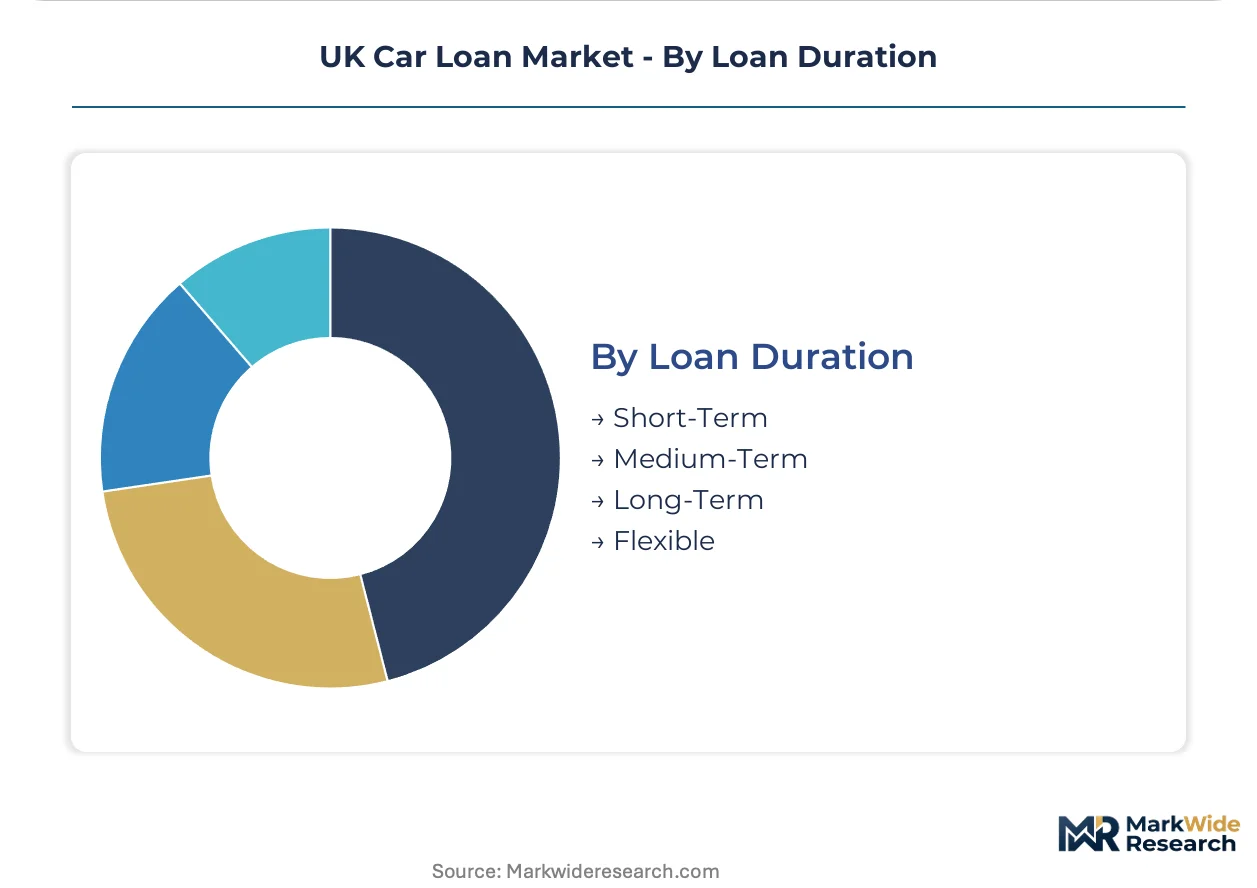
Loan Duration:
Funding cost mismatch risk escalates with term length, pressuring fixed-rate product design.
- Medium-Term:36-48 month structures aligning PCP balloon payments with typical ownership cycles. Captive finance arms optimize here.
- Long-Term:49-60 month agreements stretching affordability for higher-priced vehicles. Used car independents in Greater London push extended terms.
- Short-Term:12-24 month agreements for near-cash buyers seeking minimal interest exposure. Personal loan channels dominate.
- Flexible:Revolving structures with payment holidays and early settlement options. Challenger banks differentiate through these features.
Medium-Term structures anchor current origination; Flexible duration is expanding most quickly among digitally native lenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan financial centers across England generate the bulk of UK car loan origination, with branch networks and dealer partnerships clustering around established banking infrastructure.
Greater London
Prime-rated borrowers in London's home counties drive PCP penetration through franchised dealer networks. The Financial Conduct Authority's Consumer Duty rules enforce strict affordability assessments across City-based lender headquarters. Canary Wharf and the Square Mile host captive finance decision centers for major banking groups.
West Midlands
SME fleet operators in Birmingham and Coventry generate concentrated demand for business loan structures with VAT recovery mechanics. The Bank of England's base rate transmission affects regional net interest margins for local building society branches. Solihull's automotive manufacturing heritage sustains specialist floorplan lending relationships.
Greater Manchester
Independent used car dealerships across Lancashire and Cheshire expand captive finance arms to capture retail origination margin. The FCA's discretionary commission arrangement review pressures broker remuneration models in the North West. Trafford Park's logistics corridor anchors dealer network distribution infrastructure.
Scotland
Used car finance penetration lags England's metropolitan corridors, creating whitespace for specialized floorplan products. The Prudential Regulation Authority supervises capital adequacy for Edinburgh-based banking operations. Glasgow's independent dealer channel shows rising guarantor-backed structures for first-time buyers.
Wales
University towns in South Wales demonstrate climbing student buyer penetration with parental income support mechanisms. Welsh building societies face IT capex constraints for open banking integration required by Consumer Duty standards. Cardiff's emerging dealer networks attract challenger bank digital origination platforms.
UK Car Loan Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer digital channels and EV-specific product innovation. The UK car loan market structures around bank-owned captives, independent non-bank specialists, and building society lenders. Three archetypes dominate: high street branch network deployers, dealer channel-anchored independents, and digitally native challengers. Competitive moves concentrate on proprietary origination platform builds and residual value forecasting capability acquisitions.
Among bank-owned captive finance arms, Black Horse and Santander Consumer UK exemplify the branch network deployment archetype, leveraging parent banking infrastructure for high street visibility. Close Brothers Motor Finance occupies a position within the independent specialist tier, anchoring dealer channel relationships through floorplan and retail product specialization. These three represent distinct competitive positioning strategies across the origination value chain.
| Leading Market Players |
|---|
| Black Horse |
| Close Brothers Motor Finance |
| Santander Consumer UK |
| MotoNovo Finance |
| Northridge Car Finance |
| Barclays Partner Finance |
| Nationwide Building Society |
| Blue Motor Finance |
| Moneybarn |
| Others |
Pricing and Supply Chain Analysis
Funding cost volatility propagates through UK car loan pricing tiers from base rate transmission through dealer markups to consumer APR schedules. The Bank of England's monetary policy stance feeds directly into captive finance arms' cost of funds, compressing net interest margins before repricing adjustments reach retail products.
Pricing Analysis
Warranty and service bundling separates captive finance pricing from independent lender offerings. Three-tier pricing structure across premium, standard, and economy levels reflects residual value guarantee comprehensiveness and dealer markup discretion. Price differentiation hinges on FCA Consumer Duty compliance investment levels and geographic delivery cost variations within England's metropolitan corridors. Pricing pressure stems from broker commission transparency mandates, with subprime channels experiencing the steepest margin compression. First-time buyers in Scotland and Wales exhibit highest price sensitivity; prime-rated borrowers in Greater London show lowest elasticity due to monthly payment fixation.
Supply Chain Analysis
End-of-term vehicle returns and refurbishment flows anchor residual value realization for PCP products. The UK car loan supply chain draws from Germany, Japan, and South Korea for vehicle sourcing, with domestic independent dealers providing used inventory concentration. Raw material dependencies include automotive semiconductor content, battery cell supply for EV financing products, and steel pricing for residual value forecasting. Single-source vulnerability concentrates in captive finance IT infrastructure for digital origination platforms. Distribution runs through franchised dealer networks in Greater London and Greater Manchester, supplemented by independent dealer channels across West Midlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK car loan market functions as a vertical-integration race where upstream control over digital origination platforms and downstream capture of dealer network relationships determine margin sustainability.
For Market Incumbents: Deploy proprietary affordability assessment automation to defend against challenger bank encroachment. Black Horse and Santander Consumer UK must accelerate open banking integration capex before FCA Consumer Duty remediation deadlines lock out slower competitors. Consolidate floorplan lending relationships with independent dealers in Scotland and Wales to preempt regional expansion by digitally native entrants. The discretionary commission arrangement review threatens broker-dependent origination channels. For New Entrants and Emerging Players: The FCA's Consumer Duty rules in the United Kingdom open a window for compliance-first digital platforms to capture first-time buyer segments abandoned by legacy affordability assessment bottlenecks. Target guarantor-backed structures in university towns across South Wales and Scottish central belt cities where parental income support mechanisms reduce credit risk. Penetrate underserved EV financing whitespace through battery health certification product differentiation. For Investors and Strategic Acquirers: The Prudential Regulation Authority's capital adequacy stress-test outcomes for building society lenders is the leading indicator that sector consolidation will accelerate among IT-constrained regional players. Long-term viability favors acquirers of residual value forecasting capability and digital origination platform assets over pure balance sheet scale. Target acquisition archetype: mid-tier independent non-bank specialists with established dealer channel relationships and upgradeable core banking infrastructure. Monitor FCA motor finance discretionary commission arrangement review final determinations for forced seller dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Direct-to-Consumer Platform Launch | Santander Consumer UK and Black Horse bypass dealer markups to capture prime borrower relationships directly. |
| EV-Specific Financing Product Development | Battery health certification integration addresses residual value uncertainty for electric vehicle PCP structures. |
| Open Banking Affordability Integration | Real-time income verification satisfies FCA Consumer Duty requirements while compressing time-to-yes metrics. |
| Scotland and Wales Dealer Network Expansion | Specialized floorplan products capture whitespace in used car finance penetration lagging England's corridors. |
| Residual Value Forecasting Capability Acquisition | Post-pandemic depreciation curve invalidation demands rebuilt databases with compressed historical windows. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with captive finance executives, independent dealer principals, FCA policy specialists, and building society lending officers combined with Financial Conduct Authority Consumer Duty consultation documents, Prudential Regulation Authority capital adequacy disclosures, and Society of Motor Manufacturers and Traders registration statistics. Bottom-up origination volume triangulation against top-down credit stock estimates validated market sizing.
Granularity-level modeling deployed loan type, customer demographic, credit score range, and loan duration dimensions at the UK regional cluster level. CAGRs derived from trend extrapolation of origination volumes adjusted for macroeconomic scenario weighting across the projection horizon. Industry-specific forecast inputs incorporated Bank of England base rate path assumptions and used vehicle price depreciation curve recalibration parameters.
The model assumes a particular technology adoption path for digital origination platform deployment; alternative pathways for open banking integration velocity would alter the competitive concentration outlook. Forecasts reflect assumptions regarding FCA regulatory enforcement intensity and residual value forecasting model accuracy. Practitioners should monitor Bank of England monetary policy trajectory and discretionary commission arrangement review final determinations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
UK Mortgage / Loan Broker Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Factoring Market
Loans and Leasing
Europe Used Car Financing Market