
 Digital Lending Software Market | 2026-2036
Digital Lending Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Lending Software Market Insights
Buyer concentration among mid-tier credit unions and non-banking financial companies is restructuring procurement patterns across the digital lending stack. Fiserv leverages its core banking integration depth to anchor enterprise relationships with top-tier consumer finance companies. Nucleus Software specializes in loan origination workflows for emerging-market banks, while Temenos competes through its cloud-native platform architecture designed for rapid regulatory adaptation.
Digital lending software encompasses cloud-deployed, API-first platforms that automate credit decisioning, loan servicing, and compliance reporting through machine-driven risk scoring algorithms and real-time data orchestration. These systems process structured and alternative credit data to execute lending decisions within sub-minute timeframes, replacing manual underwriting pipelines in retail and commercial banking operations. Cloud-based deployment leads solution uptake due to elastic infrastructure economics, while loan origination modules capture the dominant share of vendor revenue as institutions prioritize front-end automation over back-office retrofitting. Embedded finance integrations within auto financing and small business financing use cases are expanding fastest, driven by point-of-sale lending partnerships between fintech startups and non-financial platforms.
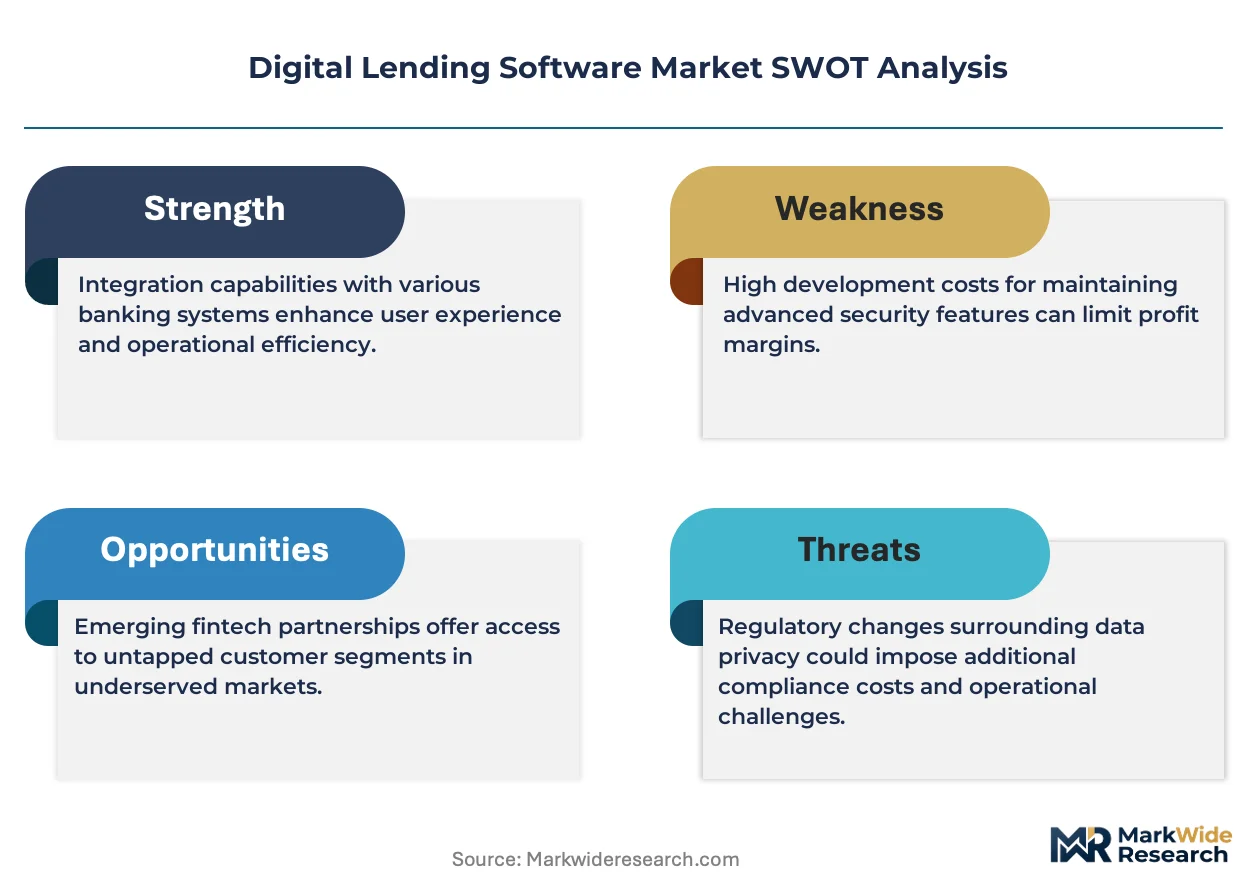
The Reserve Bank of India mandates multi-factor authentication and granular data localization for digital lending applications through its regulatory framework for NBFCs and fintech partnerships. The EU AI Act imposes risk-tiered algorithmic transparency requirements on automated credit scoring systems, compelling vendors to build explainability layers into their decision engines. Stakeholders must monitor how divergent data governance standards across jurisdictions reshape platform architecture roadmaps and determine which vendor ecosystems can sustain cross-border compliance without fragmenting their codebases.
Market Dynamics
Cloud-native architecture is compressing deployment timelines from 18-month waterfall implementations to 6-week agile sprints, forcing incumbent vendors to restructure engineering teams and subscription pricing models around consumption-based billing rather than perpetual licenses.
Growth Catalysts
- Open Banking Mandates:The EU's PSD2 framework compels incumbent banks to expose customer data APIs, creating standardized entry points for automated underwriting engines and credit scoring algorithms.
- Alternative Data Proliferation:Utility payment histories, gig-economy earnings streams, and behavioral biometrics now feed machine learning models that expand addressable borrower pools beyond traditional credit bureau coverage.
- Embedded Finance Partnerships:Auto dealerships and e-commerce marketplaces in Brazil, Indonesia, and Nigeria are white-labeling lending infrastructure to offer point-of-sale credit without building proprietary technology stacks.
Market Restraints
- Data Localization Requirements:India's RBI mandates granular data residency for digital lending applications, forcing vendors to maintain separate cloud instances and compliance audits for each jurisdiction.
- Algorithmic Explainability Costs:The EU AI Act's risk-tiered transparency requirements impose engineering overhead that disproportionately burdens mid-tier software vendors with limited R&D budgets.
- Core Banking Integration Complexity:Legacy mainframe systems at established financial institutions resist API connectivity, extending implementation timelines and inflating professional services costs.
Strategic Opportunities
- Agricultural Lending Digitization:Satellite imagery and weather data integration enables automated crop yield forecasting for smallholder farmers across sub-Saharan Africa and Southeast Asia.
- Regulatory Sandbox Participation:Brazil's central bank and the Monetary Authority of Singapore offer controlled environments for testing novel credit models with relaxed capital requirements during pilot phases.
- Voice and Conversational Interfaces:Natural language processing converges with biometric authentication to enable fully automated loan applications through messaging platforms and smart speakers.
Industry Challenges
- Model Risk Management Talent Scarcity:Financial institutions struggle to hire quantitative analysts capable of validating machine learning credit models against regulatory fairness standards.
- Multi-Jurisdiction Compliance Fragmentation:Divergent data governance frameworks across operating markets force vendors to maintain parallel codebases, increasing maintenance overhead and release cycle complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Lending Software Market |
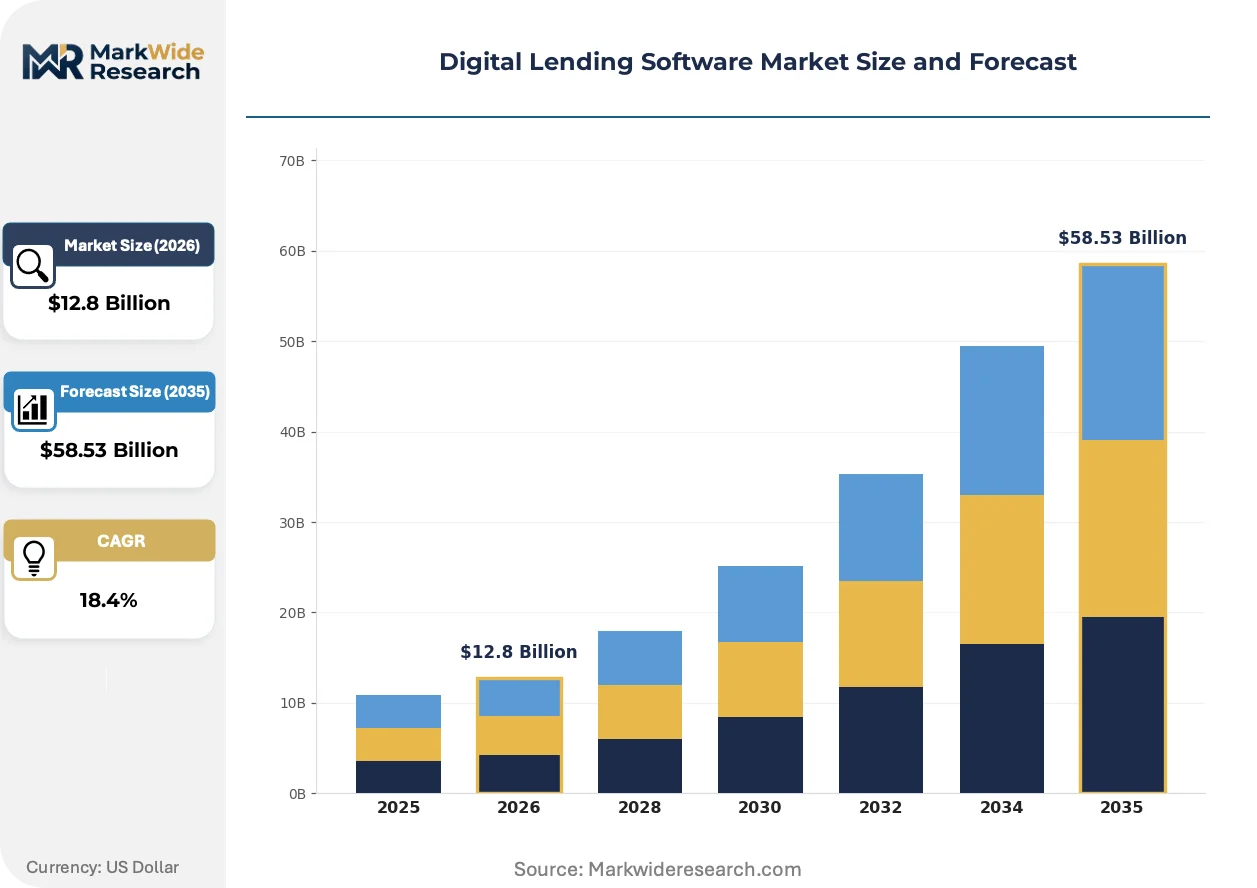
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $58.53 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Software-as-a-Service, Embedded Solution Offering: Loan Origination, Credit Scoring, Risk Management, Customer Onboarding, Fraud Detection, Collections Management Use Case: Personal Loans, Small Business Financing, Mortgage Processing, Auto Financing, Education Lending, Peer-to-Peer Lending End User: Consumer Finance Companies, Credit Unions, Microfinance Institutions, Fintech Startups, Non-Banking Financial Companies, Student Loan Servicers |
| Companies Covered | Fiserv, FIS, Newgen Software, Nucleus Software, Temenos, Finastra, Pegasystems, Sigma Infosolutions, Intellect Design Arena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Lending Software Market Trends and Innovations
Distributed ledger infrastructure and real-time payment rails are collapsing settlement delays that historically justified batch-processed credit decisions, enabling instantaneous fund disbursement and continuous risk monitoring.
Blockchain-based identity verification is decentralizing customer onboarding workflows by enabling self-sovereign credential portability across lending platforms. Community banks and credit unions in pilot programs are adopting decentralized identifiers to reduce Know-Your-Customer duplication costs. This architecture is decentralizing data control away from centralized credit bureaus toward borrower-owned credential vaults, compressing verification timelines from days to minutes.
The EU AI Act imposes mandatory algorithmic impact assessments for automated credit scoring systems classified as high-risk. Vendors must now embed explainability layers and bias detection modules directly into decision engines before deployment. European consumer finance subsidiaries are responding by restructuring procurement criteria to prioritize vendors with pre-certified compliance documentation.
Buyers are consolidating vendor relationships around integrated platform suites rather than best-of-breed point solutions. Mid-tier credit unions now demand unified loan origination, servicing, and analytics modules from single providers to reduce integration friction. This pattern is most visible in the United States, where core banking modernization cycles coincide with lending stack replacement decisions.
Digital Lending Software Market Segmentation
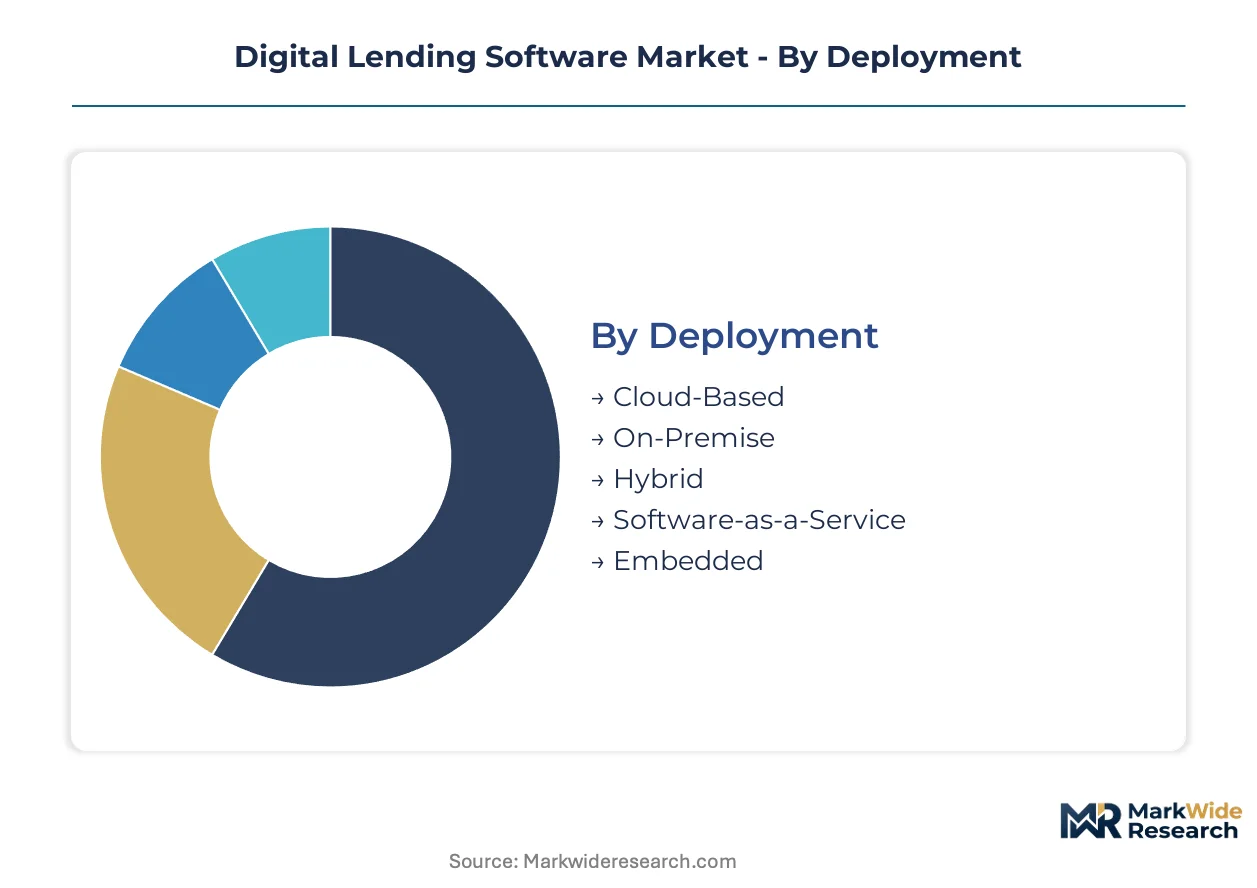
Deployment architecture and solution modularity determine how vendors structure pricing, implementation timelines, and compliance architectures across lending institutions. Each segmentation dimension reveals distinct capital requirements, buyer concentration patterns, and technology maturity gaps that reshape competitive positioning.
Deployment:
Cloud-native deployment models demand the heaviest upfront infrastructure investment in elastic compute provisioning and multi-tenant security architectures.
- Cloud-Based:Elastic infrastructure enables sub-minute credit decisioning through distributed processing nodes. Demand concentrates among mid-tier credit unions in the United States and community banks in Brazil seeking to bypass legacy mainframe constraints. RBI data localization mandates in India force vendors to maintain jurisdiction-specific instances, inflating operational overhead.
- Software-as-a-Service:Subscription economics shift capital expenditure to operating expenditure, lowering barriers for microfinance institutions and fintech startups. European adoption accelerates under EU AI Act compliance requirements that favor centralized platform updates over on-premise patch management.
- On-Premise:Retained by established banks with sunk investments in core banking infrastructure and stringent internal security protocols.
- Hybrid:Blends sensitive data residency with cloud scalability for institutions navigating transitional compliance environments.
- Embedded:White-labeled lending modules integrate directly into auto dealership and e-commerce checkout flows, minimizing buyer technology investment.
Most installed capacity flows through Cloud-Based deployment. Expansion is steepest in Embedded configurations as point-of-sale partnerships proliferate.
Solution Offering:
Front-end automation modules command premium pricing relative to back-office retrofitting, concentrating vendor R&D investment toward origination and scoring engines.
- Loan Origination:API-first platforms orchestrate application intake, document verification, and approval workflows through machine-driven pipelines. Credit unions in the United States prioritize this module during core banking modernization cycles. EU AI Act explainability requirements compel vendors to embed bias detection layers directly into decision engines.
- Credit Scoring:Alternative data integration—utility payments, gig-economy earnings, behavioral biometrics—expands addressable borrower pools beyond traditional bureau coverage. Nigerian fintech startups and Indonesian digital banks adopt these models to serve underbanked populations.
- Risk Management:Real-time portfolio monitoring and stress testing tools for institutional lenders managing concentrated exposure.
- Customer Onboarding:Biometric verification and digital identity workflows compress Know-Your-Customer timelines from days to minutes.
- Fraud Detection:Pattern recognition algorithms flag synthetic identities and application manipulation across high-volume channels.
- Collections Management:Automated outreach and payment restructuring tools for delinquency recovery operations.
Loan Origination captures the dominant revenue share. Credit Scoring is gaining share fastest as alternative data proliferation reshapes underwriting economics.
Use Case:
Asset-backed lending segments require heavier collateral valuation infrastructure than unsecured personal credit, altering platform configuration costs.
- Auto Financing:Point-of-sale integration with dealership management systems enables instant approval at vehicle purchase. Embedded finance partnerships between fintech platforms and Brazilian auto retailers drive volume concentration.
- Small Business Financing:Cash flow analytics and tax data integration automate underwriting for merchants lacking traditional credit histories. Demand clusters among NBFCs in India and digital lenders in Indonesia.
- Personal Loans:Unsecured consumer credit with streamlined application flows and rapid disbursement.
- Mortgage Processing:Complex collateral valuation and regulatory documentation requirements extend implementation timelines.
- Education Lending:Enrollment verification and future income modeling for student debt origination.
- Peer-to-Peer Lending:Marketplace infrastructure connecting retail investors with individual borrowers.
Auto Financing leads current deployment volume. Small Business Financing shows the steepest adoption curve as merchant lending platforms scale.
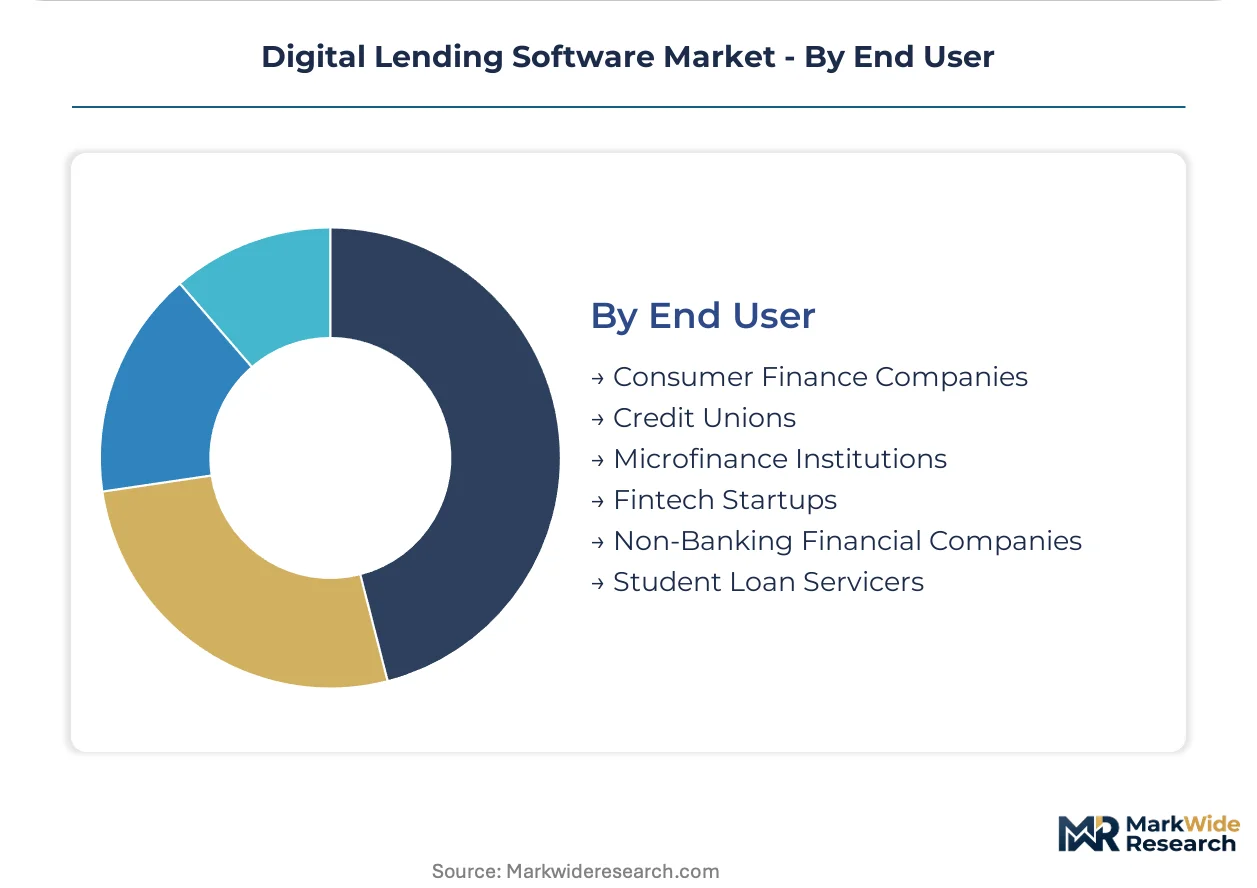
End User:
Regulated deposit-taking institutions face steeper compliance burdens than non-bank lenders, segmenting procurement priorities and vendor selection criteria.
- Credit Unions:Community-focused institutions prioritize unified platform suites combining origination, servicing, and analytics to reduce integration friction. United States procurement cycles align with core banking replacement decisions.
- Fintech Startups:Greenfield operators adopt cloud-native stacks without legacy migration costs, enabling rapid market entry in Nigeria and Indonesia. These buyers favor consumption-based pricing over perpetual licenses.
- Consumer Finance Companies:Specialized lenders focusing on installment credit and point-of-sale financing.
- Microfinance Institutions:Small-balance agricultural and rural lending requiring mobile-first collection tools.
- Non-Banking Financial Companies:Indian NBFCs navigate RBI multi-factor authentication and data localization mandates for fintech partnerships.
- Student Loan Servicers:Federal and private education debt administrators with specialized compliance reporting requirements.
Credit Unions represent the largest installed base. Fintech Startups are expanding most quickly as regulatory sandboxes lower capital barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil leapfrogs legacy infrastructure faster than Germany modernizes established systems, creating divergent deployment patterns across emerging and mature markets. India's regulatory mandates force vendor localization while the United States drives consolidation through core banking replacement cycles. These dynamics reshape where cloud-native architectures gain traction versus where hybrid models prevail.
United States
Mid-tier credit unions drive procurement volume as core banking modernization cycles align with lending stack replacements. The CFPB supervises fair lending algorithms, compelling vendors to embed bias detection into decision engines. Chicago and Dallas host concentrated fintech-development clusters where embedded finance partnerships with auto dealerships proliferate.
Brazil
Point-of-sale lending partnerships between fintech platforms and auto retailers accelerate faster than traditional bank digitization. The Banco Central do Brasil operates regulatory sandboxes that lower capital barriers for novel credit model testing. São Paulo anchors the densest vendor implementation activity as cloud-native deployments bypass legacy mainframe constraints.
India
NBFCs and fintech partnerships expand addressable borrower pools through alternative data integration. The RBI mandates multi-factor authentication and granular data localization, forcing vendors to maintain jurisdiction-specific cloud instances. Mumbai and Bangalore concentrate software development talent for loan origination workflow customization.
Germany
Established banks retrofit automated underwriting onto core banking infrastructure rather than greenfield replacement. The EU AI Act imposes risk-tiered algorithmic transparency requirements that elevate engineering overhead for all vendors. Frankfurt's financial services cluster demands pre-certified compliance documentation in procurement criteria.
Indonesia
Digital banks and fintech startups adopt consumption-based pricing models without legacy migration burdens. The Otoritas Jasa Keuangan supervises peer-to-peer lending platforms through evolving fintech regulations. Jakarta hosts the primary vendor implementation hub for merchant lending platforms serving underbanked small businesses.
Digital Lending Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architecture and solution modularity. The vendor base stratifies into three tiers: core-anchored platform suites, cloud-native specialists, and embedded finance enablers. Dominant competitive moves include strategic partnerships with auto dealership networks and consumption-based pricing restructuring away from perpetual licenses.
Within the core-anchored tier, Fiserv and FIS represent diversified financial technology conglomerates whose integration depth anchors enterprise relationships. Temenos exemplifies the cloud-native architecture specialist competing through rapid regulatory adaptation capabilities. Nucleus Software occupies a focused position serving emerging-market loan origination workflows. These three entities illustrate how vendor selection criteria diverge between institutions prioritizing unified platform breadth versus those demanding modular specialization.
| Leading Market Players |
|---|
| Fiserv |
| FIS |
| Newgen Software |
| Nucleus Software |
| Temenos |
| Finastra |
| Pegasystems |
| Sigma Infosolutions |
| Intellect Design Arena |
| Others |
Pricing and Supply Chain Analysis
Mid-tier credit union procurement consolidation in the United States is compressing vendor margins and forcing platform providers to restructure engineering teams around consumption-based billing rather than perpetual license models. This demand-side pressure cascades through supply chains as vendors prioritize cloud-native talent acquisition in Bangalore and São Paulo over legacy mainframe specialists in Frankfurt and Chicago.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for cloud-native deployment modules as engineering labor pools expand. SaaS-tiered subscription models dominate, with price differentiation resting on EU AI Act compliance certification and core banking integration depth. Cost compression in mid-tier credit union segments is intensifying because buyers demand unified platform suites over best-of-breed point solutions. Fintech startups exhibit highest price sensitivity due to capital constraints, while established consumer finance companies accept premium tiers for pre-certified regulatory documentation.
Supply Chain Analysis
Machine learning engineering talent shortages in Mumbai, Bangalore, and São Paulo are constraining platform development velocity for automated underwriting engines. Supply chains draw from specialized cloud infrastructure providers, alternative data aggregators, and biometric authentication vendors. Single-source vulnerability concentrates in satellite imagery providers for agricultural lending modules. Distribution runs through direct enterprise sales teams for credit unions and channel partnerships with core banking vendors for community banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities separate vendors with India-based development centers benefiting from RBI data localization mandates against competitors bearing EU AI Act compliance overhead in Germany. This cost and regulatory differential favors cloud-native architectures built for rapid jurisdiction-specific adaptation.
For Market Incumbents: To counter embedded finance partnerships between fintech startups and Brazilian auto retailers, Fiserv and Temenos must accelerate API-first platform consolidation and deepen vertical integration into alternative data aggregation through strategic acquisitions in Southeast Asia. For New Entrants and Emerging Players: Agricultural cooperatives in sub-Saharan Africa represent an underserved buyer archetype with minimal incumbent penetration. These institutions require mobile-first collection tools and satellite-based crop yield forecasting. A direct-to-cooperative sales model bypassing traditional banking channels offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native specialists possessing pre-certified EU AI Act compliance documentation and established India cloud instances. Long-term viability over a decade hinges on regulatory adaptation speed rather than core banking integration depth. The inflection signal to monitor is central bank sandbox participation rates in Brazil and Singapore as leading indicators of novel credit model validation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Participation | Brazil's Banco Central and Singapore's MAS enable novel credit model testing with relaxed capital requirements during pilot phases. |
| Alternative Data Partnership | Utility payment aggregators and gig-economy platforms expand addressable borrower pools beyond traditional bureau coverage in Indonesia and Nigeria. |
| Cloud Instance Localization | RBI-mandated data residency forces vendors to maintain jurisdiction-specific infrastructure, elevating operational overhead for India-focused providers. |
| Embedded Finance Integration | White-labeled lending modules integrate into Brazilian auto dealership management systems and Indonesian e-commerce checkout flows. |
| Explainability Layer Certification | EU AI Act compliance documentation becomes a procurement gate for European consumer finance subsidiaries restructuring vendor selection criteria. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Primary interviews engaged chief technology officers at credit unions, digital lending platform engineers, regulatory affairs specialists at NBFCs, and procurement officers at consumer finance companies. Secondary sources included RBI circulars on fintech partnerships, EU AI Act implementation guidance, SEC filings from diversified financial technology conglomerates, and central bank sandbox participation records. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume estimates.
Rate-of-change decomposition separates deployment model shifts, regulatory compliance burden evolution, and alternative data integration velocity across the analysis window. Segmentation dimensions modeled include deployment architecture, solution modularity, use case specialization, and end-user regulatory classification. CAGRs derive from elasticity-adjusted adoption curves and jurisdiction-specific compliance timeline assumptions. Forecast inputs incorporate open banking mandate implementation schedules and core banking replacement cycle phasing in the United States.
Underlying measurement precision varies by segment; cloud-based deployment and loan origination modules carry tighter precision than emerging embedded finance configurations. Forecasts reflect assumptions about regulatory sandbox expansion continuity and alternative data provider consolidation trajectories. Material deviation in EU AI Act enforcement intensity or RBI data localization granularity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Refinancing Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
United States Digital Lending Market