
 China Home Loan Market | 2026-2036
China Home Loan Market Size, Share, and Industry Trends Forecast 2026-2036
China Home Loan Market Insights
Pricing for first-time buyers is decoupling from investor-grade products as the People's Bank of China imposes differentiated down-payment ratios and interest rate floors. Industrial and Commercial Bank of China leverages its branch density across county-level markets to dominate originations outside tier-one cities. China Construction Bank anchors its portfolio through dedicated housing finance subsidiaries that underwrite mortgages tied to new development projects. Agricultural Bank of China navigates rural land reform pilot zones by extending mortgage products to collective land leaseholders.
A home loan constitutes a secured credit instrument collateralized by residential real estate, typically structured with loan-to-value ratios capped by prudential regulation and serviced through amortized principal-and-interest schedules over ten to thirty years. Fixed-rate products now lead origination volumes among first-time buyers seeking payment certainty, while adjustable-rate instruments attract investors exploiting the loan prime rate's downward trajectory. Hybrid structures that combine initial fixed periods with floating-rate resets are capturing margin pools from borrowers anticipating early refinancing.
The People's Bank of China calibrates the loan prime rate to steer credit toward owner-occupied housing, while the China Banking and Insurance Regulatory Commission enforces concentration limits and stress-testing protocols for mortgage portfolios. The National Development and Reform Commission coordinates urbanization targets that determine land supply and construction quotas, directly shaping addressable demand for housing finance. Stakeholders must monitor how local government special bond issuance for affordable housing interacts with central bank liquidity operations to determine origination capacity and pricing trajectories.
Market Dynamics
The People's Bank of China's recalibration of the loan prime rate mechanism is compressing investor-grade origination margins while redirecting credit flows toward owner-occupied housing, fundamentally restructuring how lenders price risk across buyer segments.
Growth Catalysts
- Loan Prime Rate Adjustment:The central bank's downward rate trajectory reduces monthly payment burdens for first-time buyers, expanding the addressable borrower pool in tier-two cities where urbanization policies concentrate rural migration flows.
- Yangtze River Delta Urbanization:Metropolitan cluster development absorbs population inflows from interior provinces, generating sustained demand for residential collateral that underwrites mortgage expansion.
- Fixed-Rate Product Innovation:Amortization structures offering payment certainty attract risk-averse households previously excluded from adjustable-rate markets, broadening origination channels beyond investor-dominated segments.
Market Restraints
- Land Supply Constraints:National Development and Reform Commission construction quotas limit addressable housing stock in tier-one cities, compressing origination volume growth regardless of credit availability.
- Concentration Limits:China Banking and Insurance Regulatory Commission stress-testing protocols cap mortgage portfolio exposure at systemically important banks, constraining balance sheet capacity for aggressive expansion.
- Collective Land Title Complexity:Rural land reform pilot zones generate legal ambiguity around collateral enforceability for collective leaseholders, elevating recovery risk in county-level markets.
Strategic Opportunities
- County-Level Branch Density:Agricultural Bank of China's existing rural infrastructure positions lenders to capture mortgage demand from collective land reform beneficiaries as title clarity improves.
- Hybrid Rate Structures:Products combining initial fixed periods with floating resets attract borrowers anticipating early refinancing, capturing margin pools from payment-certainty seekers.
- Pearl River Delta Migration:Guangdong province urbanization targets sustain housing demand from manufacturing workforce relocation, creating origination volume in manufacturing corridor cities.
Industry Challenges
- Legacy System Integration:Industrial and Commercial Bank of China's core banking infrastructure requires substantial reconfiguration to process differentiated down-payment ratios across buyer segments without manual underwriting bottlenecks.
- Credit Assessment Talent Scarcity:Rural branch networks lack sufficient underwriters trained in collective land collateral valuation, delaying product rollout in reform pilot zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Home Loan Market |
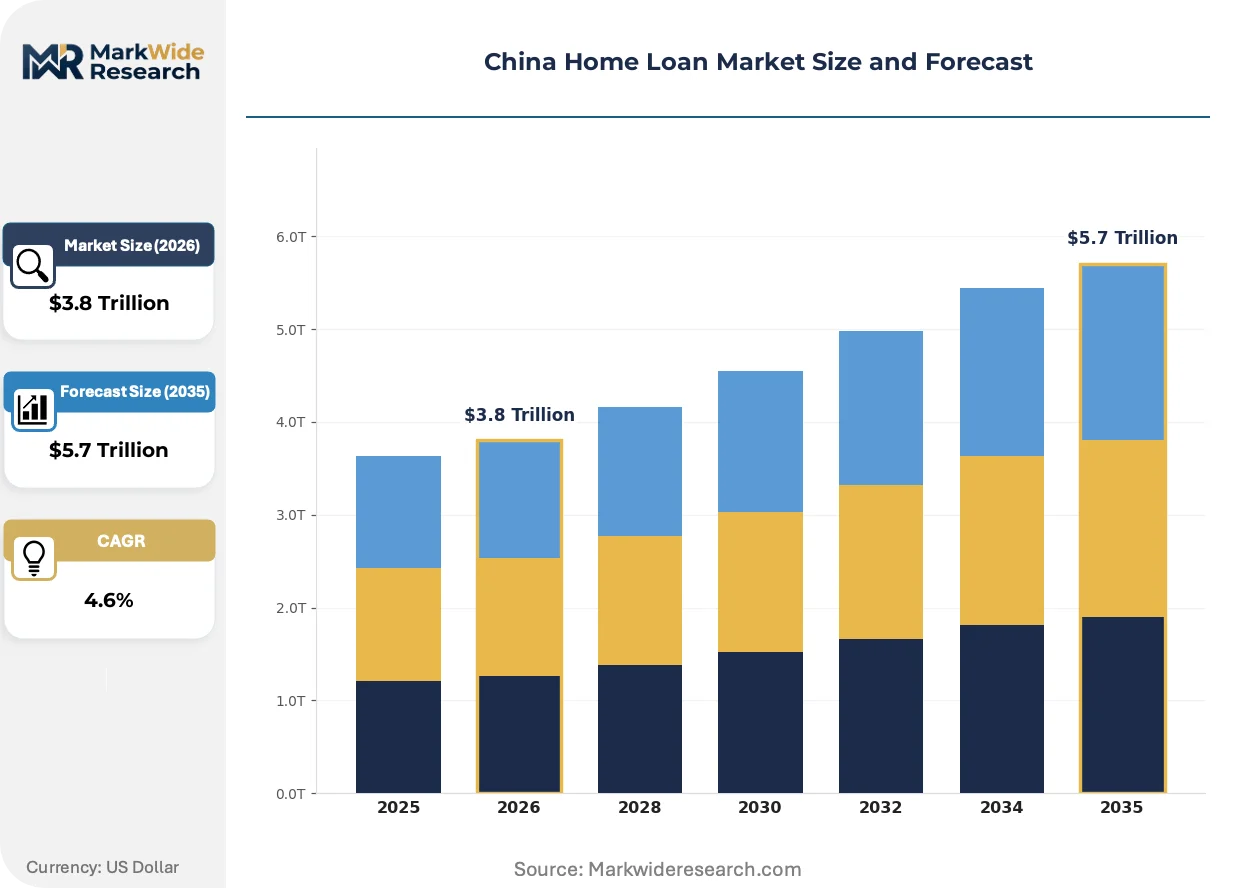
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $5.7 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Fixed Rate, Adjustable Rate, Interest Only, Hybrid Borrower Profile: First-Time Buyers, Repeat Buyers, Investors, Refinancers Property Type: Residential, Commercial, Vacation, Multi-Family Loan Term: Short-Term, Mid-Term, Long-Term, 30-Year |
| Companies Covered | Industrial and Commercial Bank of China, Bank of China, China Construction Bank, Agricultural Bank of China, Postal Savings Bank of China, China Merchants Bank, Shanghai Pudong Development Bank, China CITIC Bank, Hua Xia Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Home Loan Market Trends and Innovations
Digitization of mortgage origination workflows is compressing approval timelines while regulatory differentiation between owner-occupied and investor products is fragmenting pricing architectures across lender portfolios.
Blockchain-enabled property title verification is absorbing documentary due diligence costs previously borne by manual registry searches. First-time buyers in tier-two cities adopt this infrastructure fastest as municipal governments digitize land records. The technology is absorbing title insurance premiums and accelerating collateral verification timelines that previously delayed drawdown schedules.
The People's Bank of China's differentiated interest rate floors create regulatory segmentation between owner-occupied and investor-grade products. Lenders must maintain parallel pricing architectures with distinct risk-weighting calculations for each buyer category. First-time buyers in Yangtze River Delta metropolitan clusters benefit most from this bifurcation as rate floors compress their relative borrowing costs against investor competition.
Direct-to-consumer digital origination platforms disintermediate traditional branch-based application processes. Younger first-time buyers in tier-two cities prefer mobile-first submission workflows that bypass physical documentation requirements. This channel rotation concentrates in Pearl River Delta manufacturing cities where workforce demographics skew younger and smartphone penetration exceeds national averages.
China Home Loan Market Segmentation
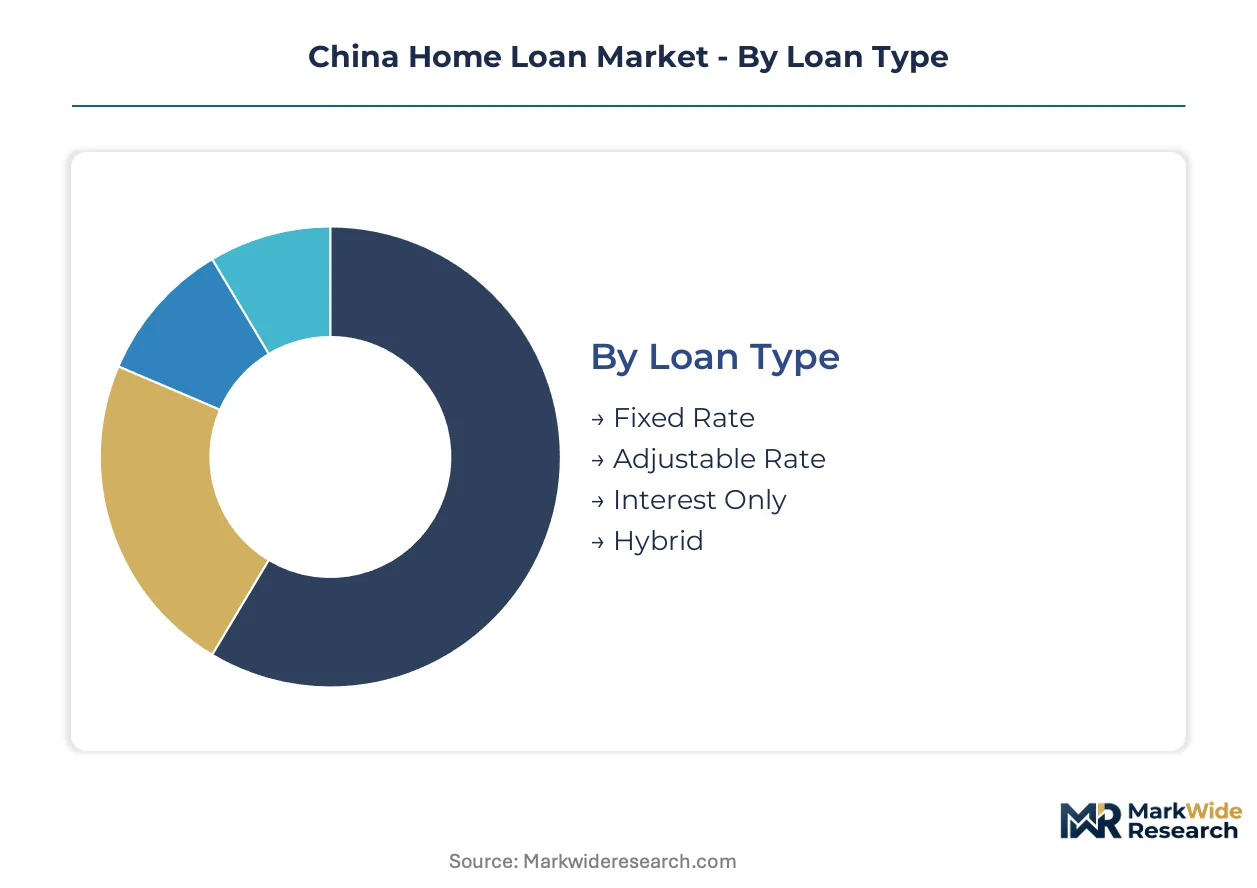
Segmentation in China's home loan market reveals how regulatory differentiation and borrower risk profiles reshape origination strategies. Lenders must align product architectures with the People's Bank of China's bifurcated rate mechanisms while capturing distinct demand pools across property collateral types.
Loan Type:
Fixed-rate products command premium pricing power while adjustable-rate instruments dominate origination volumes in tier-two cities where rate-sensitive first-time buyers cluster.
- Fixed Rate:Amortization schedules lock borrowing costs across the full loan tenor, eliminating exposure to People's Bank of China policy rate volatility. Yangtze River Delta metropolitan clusters absorb the highest concentration of fixed-rate originations as households prioritize payment certainty over rate arbitrage opportunities.
- Adjustable Rate:Interest obligations reset periodically against the loan prime rate benchmark, transferring policy rate risk to borrowers while offering lower initial coupons. Pearl River Delta manufacturing corridor cities generate outsized demand from younger buyers exploiting the central bank's downward rate trajectory to minimize early-year payments.
- Interest Only:Structures defer principal amortization for initial periods, preserving cash flow for investors deploying capital across multiple properties.
- Hybrid:Products combine fixed-rate introductory periods with subsequent floating-rate resets, capturing margin pools from borrowers anticipating early refinancing or income growth.
Today's leader: Fixed Rate. Tomorrow's challenger: Hybrid.
Borrower Profile:
First-time buyers anchor origination volumes outside tier-one cities while regulatory rate floors compress investor-grade margins.
- First-Time Buyers:Households purchasing primary residences qualify for preferential down-payment ratios and interest rate floors under differentiated prudential rules. County-level markets in tier-two cities absorb the fastest expansion of first-time buyer originations as urbanization policies channel rural migration toward affordable housing clusters.
- Repeat Buyers:Existing homeowners trading up property collateral face elevated down-payment requirements and reduced rate concessions. Transaction volumes concentrate in Pearl River Delta upgrade corridors where manufacturing workforce savings accumulate toward secondary residence purchases.
- Investors:Non-owner-occupied purchasers encounter stricter loan-to-value caps and higher interest rate floors designed to suppress speculative demand.
- Refinancers:Existing borrowers restructuring obligations to capture rate declines or extract equity face documentation requirements that digitized origination platforms are compressing.
First-time buyers hold volume dominance. Refinancers are gaining share fastest as rate differentials widen.
Property Type:
Residential collateral underwrites the overwhelming majority of portfolio exposure while commercial property financing faces concentration limit constraints.
- Residential:Single-family and condominium units collateralize owner-occupied mortgages that qualify for regulatory preferencing. New development projects in Yangtze River Delta urbanization zones generate pipeline demand for residential-backed construction-to-permanent products.
- Commercial:Office and retail properties collateralize investor-grade exposures subject to higher risk-weighting and stress-testing protocols. Origination volumes face China Banking and Insurance Regulatory Commission portfolio caps that constrain balance sheet allocation.
- Vacation:Seasonal-use properties in coastal or mountain resort clusters attract niche demand from high-net-worth households seeking portfolio diversification.
- Multi-Family:Rental housing developments qualify for affordable housing financing incentives where local government special bond issuance supplements private credit.
Residential maintains origination leadership. Multi-Family presents the steepest expansion trajectory as rental housing policy support intensifies.
Loan Term:
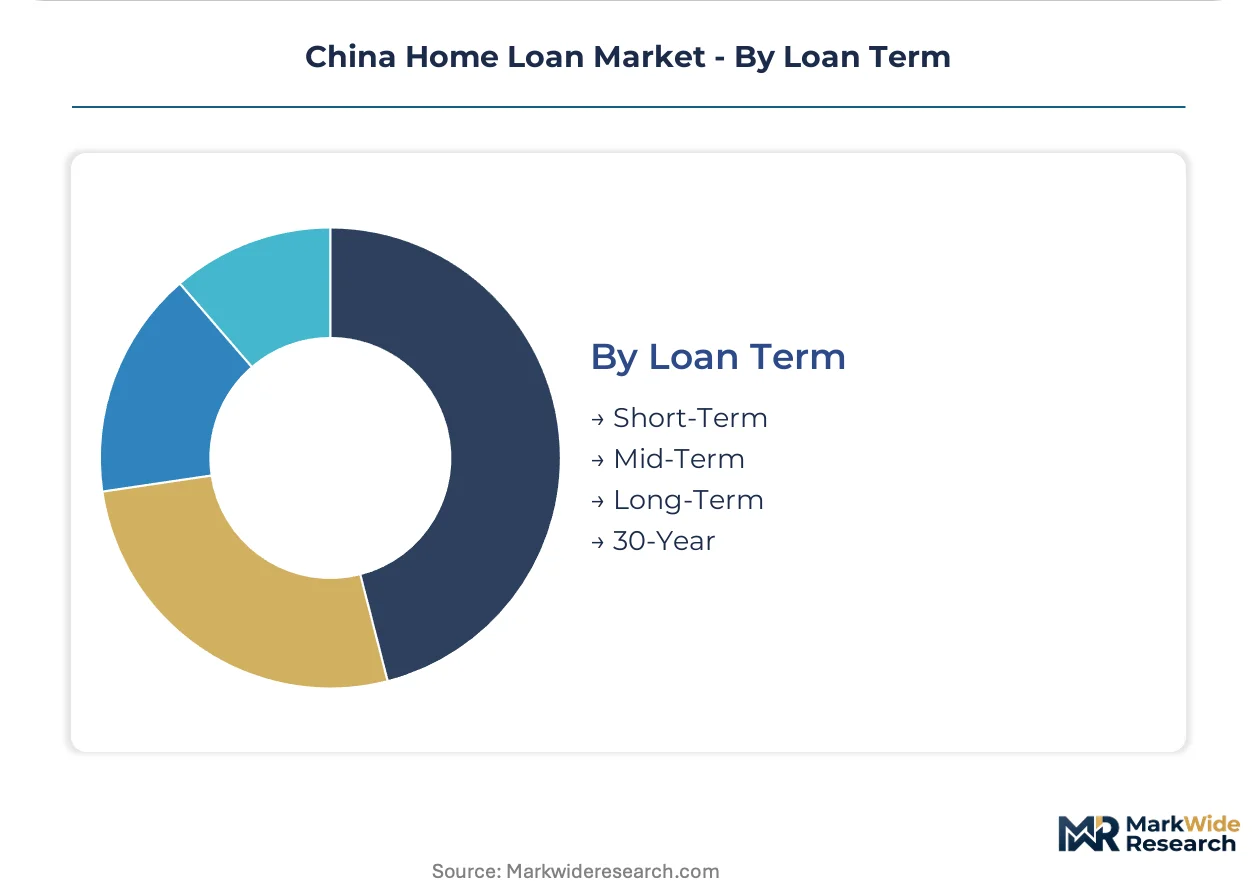
Long-tenor products dominate monthly affordability calculations while short-term structures serve bridge financing and investor liquidity management.
- Short-Term:Tenors under five years collateralize bridge loans and construction-phase financing where borrowers anticipate rapid refinancing or asset sale. Developers in Pearl River Delta new construction corridors utilize short-term facilities to manage pre-sale receivables timing.
- Mid-Term:Five-to-fifteen year amortization structures balance monthly payment burdens against total interest cost accumulation. Tier-two city first-time buyers in intermediate income brackets gravitate toward mid-term products as affordability constraints limit appetite for maximum tenor extension.
- Long-Term:Extended amortization beyond fifteen years minimizes monthly obligations while maximizing interest cost over the loan lifecycle. Yangtze River Delta metropolitan households with stable manufacturing or services sector employment favor long-term structures to preserve discretionary income.
- 30-Year:Maximum tenor products represent the outer bound of prudential regulation, available primarily to owner-occupied borrowers with strongest credit profiles and youngest demographic profiles.
Long-Term structures anchor current origination. Mid-Term products are climbing the fastest as rate uncertainty prompts tenor conservatism.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mortgage underwriters concentrate talent pools in Yangtze River Delta and Pearl River Delta metropolitan clusters where urbanization policies channel rural workforce migration toward residential collateral demand.
Yangtze River Delta
Shanghai anchors origination volume as manufacturing workforce migration from Anhui and Jiangsu sustains first-time buyer demand. The People's Bank of China's loan prime rate adjustments compress borrowing costs for owner-occupied purchasers in this corridor. Suzhou and Hangzhou municipal governments digitize land registries, accelerating collateral verification timelines for mortgage approvals.
Pearl River Delta
Shenzhen and Guangzhou absorb manufacturing relocation from interior provinces, generating housing finance demand from younger workforce cohorts. Guangdong province urbanization targets determine construction quotas that shape addressable mortgage collateral stock. Dongguan and Foshan manufacturing corridor cities exhibit fastest adoption of direct-to-consumer digital origination platforms among first-time buyers.
Beijing-Tianjin-Hebei
Tier-one city concentration limits constrain origination growth despite credit availability, as National Development and Reform Commission quotas cap residential construction permits. The China Banking and Insurance Regulatory Commission enforces stricter stress-testing protocols for mortgage portfolios in this political center. Tianjin's port economy sustains repeat buyer demand from logistics sector households trading up property collateral.
Sichuan-Chongqing
Western urbanization policies channel interior migration toward Chengdu and Chongqing, expanding first-time buyer pools in tier-two city categories. Agricultural Bank of China leverages existing rural branch infrastructure to underwrite mortgages for collective land reform beneficiaries in surrounding county-level markets. Local government special bond issuance for affordable housing supplements private credit capacity in this corridor.
Shandong Peninsula
Qingdao and Jinan manufacturing bases generate stable employment profiles that qualify households for long-tenor mortgage structures. Industrial and Commercial Bank of China deploys county-level branch density to capture origination volume outside provincial capitals. Shandong's rural land reform pilot zones create legal ambiguity around collateral enforceability, elevating recovery risk in peripheral markets.
China Home Loan Market Competitive Landscape
Capital-heavy state-owned commercial banks compete with asset-light joint-stock institutions for origination volume, creating a tiered structure where deposit base scale determines pricing power. The market consolidates around four systemic banks with branch networks exceeding ten thousand outlets, while mid-tier players differentiate through digital channels and regional specialization. Strategic archetypes separate into state-owned deposit giants, joint-stock digital innovators, and policy-oriented rural specialists. Competitive moves concentrate on county-level branch expansion and hybrid-rate product development to capture early refinancing demand.
Among state-owned commercial banks, Industrial and Commercial Bank of China, China Construction Bank, and Agricultural Bank of China occupy positions as archetypal scale-driven originators. Industrial and Commercial Bank of China exemplifies the deposit-base dominance model through county-level branch density. China Construction Bank represents construction-to-permanent product specialization via dedicated housing finance subsidiaries. Agricultural Bank of China anchors the rural inclusion archetype, navigating collective land reform zones where title clarity remains evolving.
| Leading Market Players |
|---|
| Industrial and Commercial Bank of China |
| Bank of China |
| China Construction Bank |
| Agricultural Bank of China |
| Postal Savings Bank of China |
| China Merchants Bank |
| Shanghai Pudong Development Bank |
| China CITIC Bank |
| Hua Xia Bank |
| Others |
Pricing and Supply Chain Analysis
Blockchain-enabled title verification is compressing documentary due diligence costs while concentrating origination infrastructure among lenders with capital to deploy distributed-ledger systems across county-level markets. This technology shift simultaneously reduces per-loan processing expenses and raises barriers for smaller institutions lacking scale to absorb platform investment, reshaping competitive economics across the People's Bank of China's differentiated rate environment.
Pricing Analysis
Bundled origination services combining appraisal, title verification, and insurance placement command premium spreads over unbundled transactional offerings. Three-tier pricing structure across premium, standard, and economy levels separates state-owned banks with full-service branch networks from digital-only joint-stock competitors and rural cooperative lenders. Price differentiation rests on after-sales servicing depth and geographic coverage density. Pricing pressure stems from direct-to-consumer digital platforms disintermediating traditional branch-based fee structures. First-time buyers in tier-two cities exhibit highest price sensitivity, while high-net-worth refinancers prioritize speed over rate minimization.
Supply Chain Analysis
Domestic-content mandates in financial technology procurement reshape sourcing toward indigenous core banking system vendors and local cloud infrastructure providers. Origination capacity concentrates in China, with secondary dependencies on Hong Kong SAR for cross-border capital markets access and Singapore for regional risk-management software development. Raw material inputs include property valuation data services, credit bureau scoring algorithms, and municipal land registry digitization platforms. Supply chain risk centers on single-source vulnerability in blockchain title verification protocols where municipal government partnerships create exclusive provider relationships. Distribution runs through state-owned bank branch networks exceeding ten thousand outlets, supplemented by mobile-first direct channels in manufacturing corridor cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
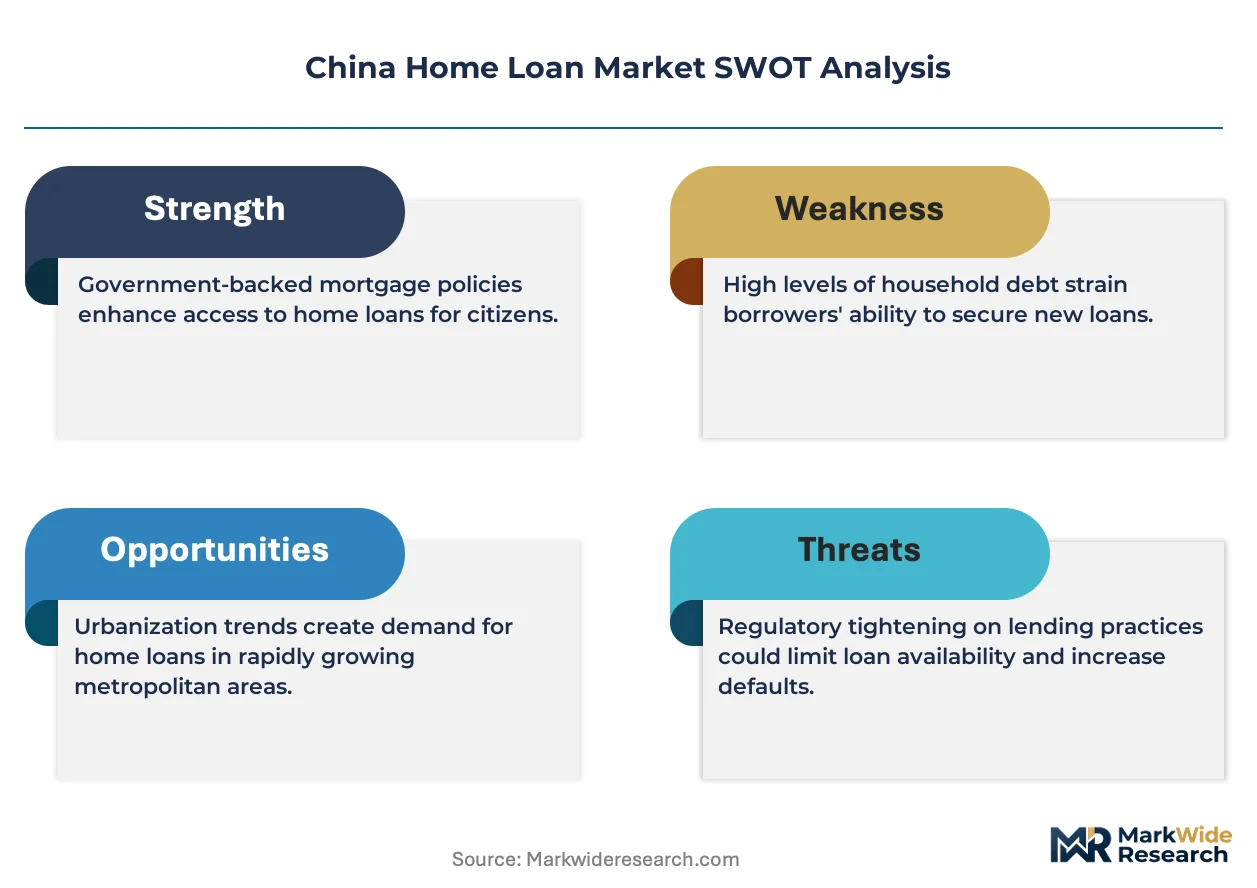
This market functions as a regulatory compounder where the People's Bank of China's loan prime rate mechanism recalibration generates sustained origination volume shifts toward owner-occupied segments. The central bank's differentiated down-payment ratio rules create structural demand pools that amplify lender positioning advantages.
For Market Incumbents: Deploy hybrid-rate product innovation as the primary lever to capture early refinancing demand from first-time buyers anticipating income growth. Agricultural Bank of China should extend county-level branch digitization to defend against joint-stock digital entrants targeting collective land reform zones. Industrial and Commercial Bank of China must reconfigure legacy core systems to process differentiated risk-weighting calculations without underwriting bottlenecks that delay drawdown schedules.
For New Entrants and Emerging Players: Direct-to-consumer mobile origination platforms offer the fastest route to penetrate tier-two city first-time buyer segments where smartphone penetration exceeds national averages. White-space targets include Pearl River Delta manufacturing corridor cities with younger workforce demographics and Sichuan-Chongqing affordable housing clusters supported by local government special bond issuance. A partnership-based go-to-market angle with municipal land registry digitization projects accelerates collateral verification capabilities without proprietary infrastructure investment.
For Investors and Strategic Acquirers: Roll-up economics work for county-level rural cooperative lenders because Agricultural Bank of China's branch density creates acquisition currency and collective land title clarity improvements unlock trapped collateral value. Long-term viability hinges on central bank policy continuity across a five-to-ten year regulatory cycle. Target acquisition archetypes include digital origination platform specialists with municipal government partnerships. The signal to watch is local government special bond issuance velocity for affordable housing as an inflection indicator for addressable demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Rate Product Launch | Captures margin pools from first-time buyers anticipating early refinancing in Yangtze River Delta clusters. |
| County-Level Branch Digitization | Compresses approval timelines for Agricultural Bank of China in collective land reform pilot zones. |
| Municipal Registry Partnership | Accelerates blockchain-enabled collateral verification for China Construction Bank construction-to-permanent products. |
| Direct-to-Consumer Platform Expansion | Disintermediates branch-based origination in Pearl River Delta manufacturing corridor cities. |
| Housing Finance Subsidiary Integration | Consolidates construction-phase and permanent financing for Industrial and Commercial Bank of China developer relationships. |
Research Methodology
Coverage spans Yangtze River Delta, Pearl River Delta, Beijing-Tianjin-Hebei, Sichuan-Chongqing, and Shandong Peninsula, with primary inputs from each metropolitan cluster. The approach combines primary interviews with mortgage underwriting executives, branch operations managers, regulatory affairs specialists at the China Banking and Insurance Regulatory Commission, and digital channel product heads with secondary validation. Secondary sources include People's Bank of China loan prime rate announcements, National Development and Reform Commission urbanization policy documents, municipal land registry digitization disclosures, and China Banking and Insurance Regulatory Commission stress-testing protocols. Bottom-up origination volume triangulation against top-down credit stock aggregates ensures consistency across estimation layers.
Rate-of-change decomposition separates volume growth into urbanization-driven addressable demand expansion, regulatory policy shift effects, and pricing elasticity responses across borrower segments. The analytical framework models loan type, borrower profile, property collateral category, and geographic metropolitan cluster as core segmentation dimensions throughout the forecast period. CAGRs derive from fitted trend extrapolation adjusted for policy inflection scenarios. Industry-specific forecast inputs include rural migration flow projections from National Development and Reform Commission targets and loan prime rate trajectory assumptions calibrated against central bank communication patterns.
The model assumes a particular technology adoption path for blockchain-enabled title verification; alternative pathways for distributed-ledger municipal registry integration would alter the outlook for origination timeline compression and cost structure evolution. Forecasts reflect assumptions regarding regulatory differentiation continuity between owner-occupied and investor-grade products, with revision risk from potential central bank rate floor adjustments or concentration limit recalibrations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Factoring Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
Global Healthcare Equipment Leasing Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
UK Home Equity Lending Market