
 Polycoated Cup Stock Market | 2026-2036
Polycoated Cup Stock Market Size, Share, and Industry Trends Forecast 2026-2036
Polycoated Cup Stock Market Analytics
The EU Single-Use Plastics Directive is realigning procurement priorities across European food service chains, compelling converters to source certified fiber-based alternatives. Mondi Group leverages its integrated pulp-to-paperboard operations to secure supply continuity for major quick-service accounts. International Paper Company anchors North American capacity through mill-level investments in barrier-coated grades. Huhtamäki Oyj differentiates via specialized forming expertise that reduces material weight without compromising liquid resistance.
Polycoated cup stock denotes paperboard substrate laminated with polyethylene or bio-based barrier layers, typically ranging from 200 to 350 gsm basis weight, engineered to prevent liquid permeation in disposable beverage containers. The material serves commercial food service operators requiring cost-effective, heat-tolerant packaging for both hot and cold drinks. Single wall and double wall product types dominate current volume, though insulated variants command premium positioning in specialty coffee channels. Biodegradable material grades represent the fastest-expanding segment as converters respond to compostability certifications demanded by institutional buyers.
The U.S. Food and Drug Administration regulates direct food contact substances through 21 CFR compliance, while the EU REACH framework governs chemical migration limits for coating chemistries. China's SAMR enforces GB standards for food packaging materials that restrict certain polyethylene formulations, shaping export-oriented production decisions. Stakeholders must monitor evolving extended producer responsibility schemes and coating chemistry restrictions that will determine which barrier technologies retain market access across jurisdictions.
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand for conventional plastic cups while redirecting converter capex toward fiber-based barrier technologies. This regulatory compression is reshaping raw material procurement, coating chemistry R&D priorities, and mill-level capacity allocation across three continents.
Growth Catalysts
- Extended Producer Responsibility schemes:France's AGEC law and Germany's VerpackG impose fee structures that favor recyclable fiber substrates over multilayer plastics. Quick-service operators in Paris and Berlin are accelerating specification changes to avoid compliance penalties.
- Compostability certification demand:Institutional buyers including university food service and corporate campus operators now require BPI or OK Compost INDUSTRIAL certification. This specification pull is expanding addressable volume for bio-based barrier grades.
- China:SAMR enforcement of GB standards restricting certain polyethylene formulations is forcing export-oriented converters to qualify alternative barrier chemistries. Domestic food service chains in Shanghai and Beijing are adopting these specifications for local supply security.
Market Restraints
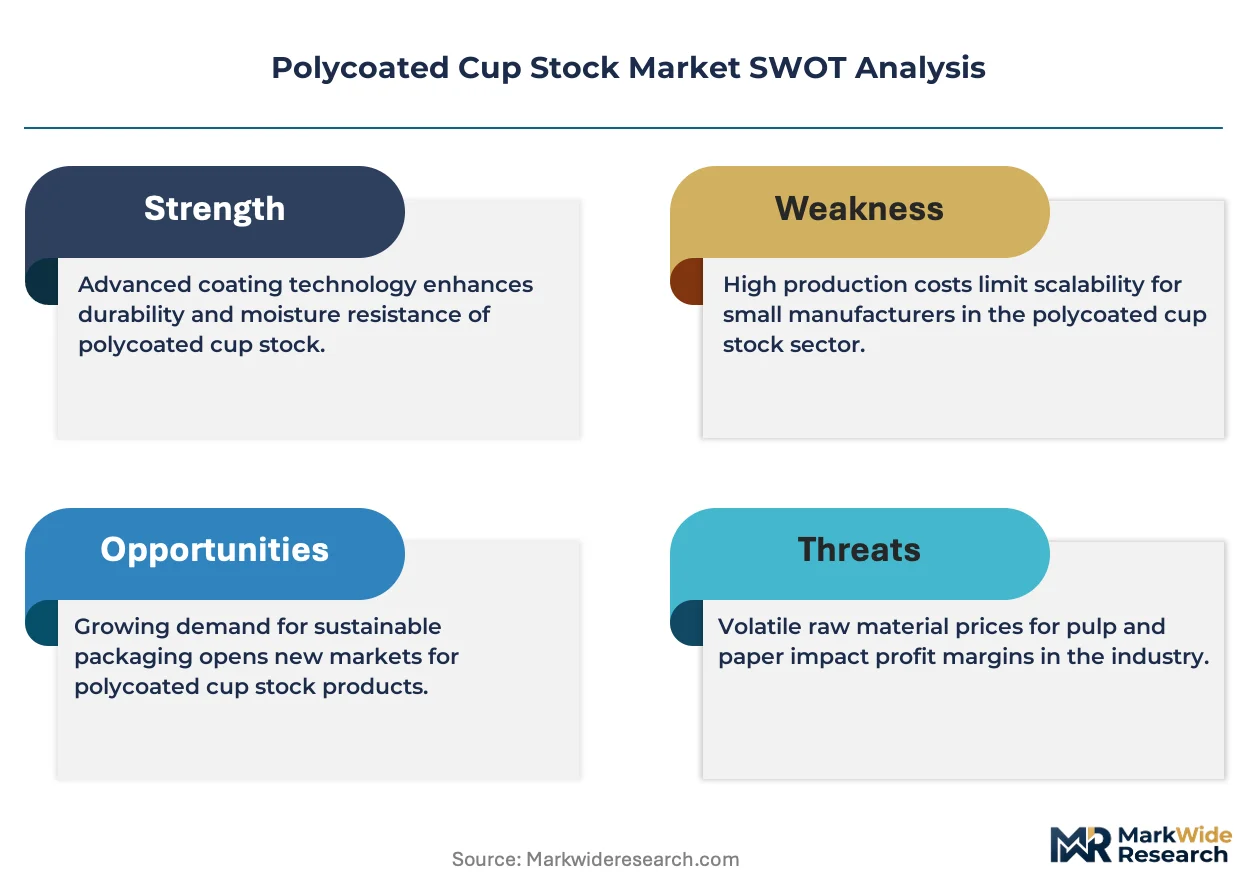
- Pulp cost volatility:Northern bleached softwood kraft pulp prices swing with energy and freight inputs, compressing converter margins on fixed-price annual contracts with quick-service accounts.
- Barrier coating supply concentration:Specialized aqueous and extrusion coating capacity clusters in the US Midwest and Germany's Rhineland, creating geographic vulnerability to weather-related outages or energy price spikes.
- Performance ceiling for bio-based barriers:Current polylactic acid and aqueous barrier formulations exhibit inferior hot-fill tolerance above 85°C, limiting deployment in specialty tea and soup applications where polypropylene-lined cups retain specification lock-in.
Strategic Opportunities
- India:FSSAI implementation of stricter food contact material standards is creating first-mover advantage for converters with pre-qualified barrier technologies. Quick-service penetration in Mumbai and Bangalore remains underdeveloped relative to per-capita income trajectories.
- Reusable cup deposit systems:Copenhagen and Amsterdam municipal mandates for dine-in deposit schemes are stimulating demand for durable polycoated stock with enhanced abrasion resistance for 50+ wash cycles.
- Digital printing convergence:Inline inkjet decoration at cup-forming lines eliminates pre-printed roll stock inventory. This technology pairing enables short-run customization for regional beverage promotions without minimum order quantity constraints.
Industry Challenges
- Migration testing timeline compression:EU REACH and FDA 21 CFR compliance for novel barrier chemistries requires 6-18 month migration studies, delaying commercialization of promising bio-based formulations.
- Extrusion coating technician shortage:Specialized expertise in multilayer coextrusion die configuration and melt index control is aging out of the workforce faster than vocational programs replenish supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycoated Cup Stock Market |
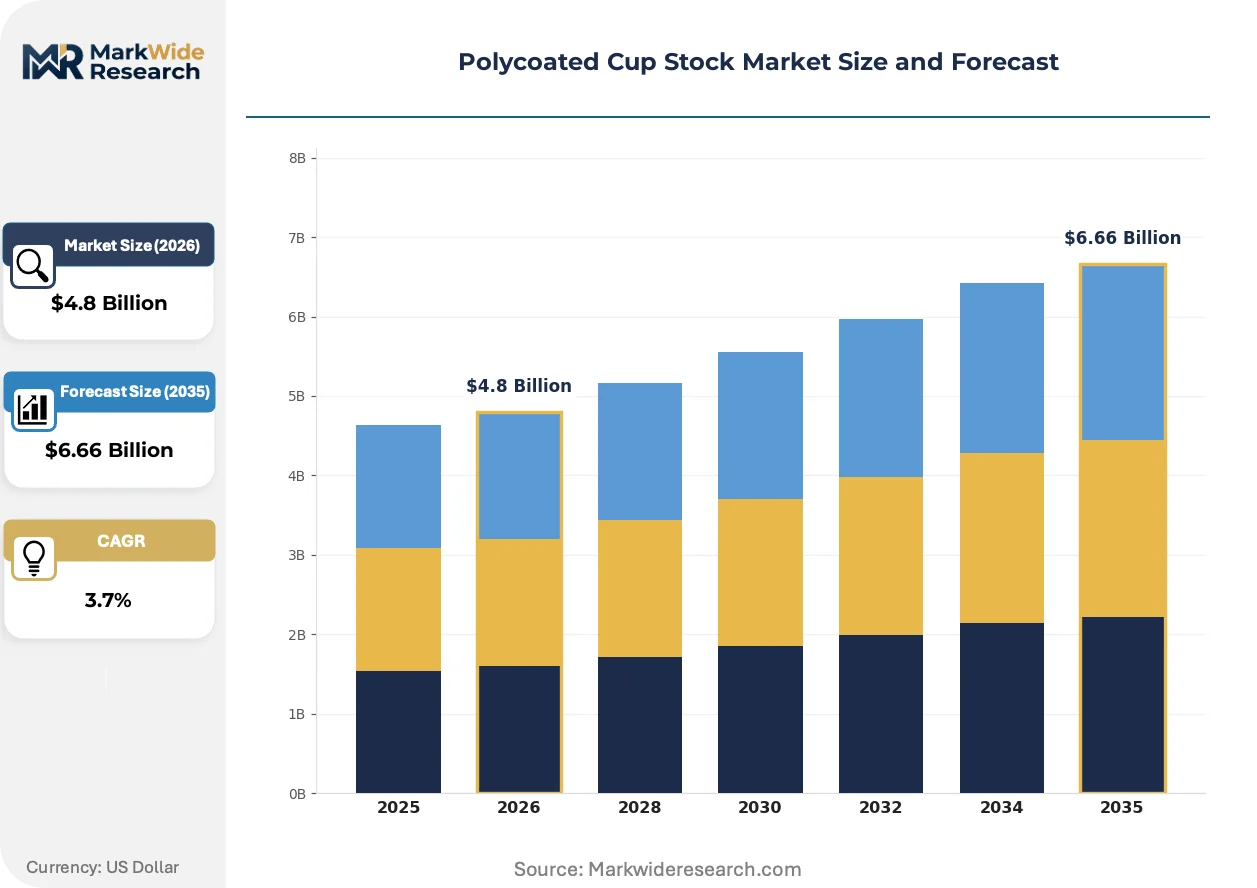
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Insulated, Rippled Material Type: Paperboard, Plastic, Biodegradable, Wax-Coated End User: Food Service, Retail, Industrial, Catering Size: Small, Medium, Large, Extra Large |
| Companies Covered | Mondi Group, International Paper Company, Huhtamäki Oyj, Pactiv Evergreen Inc., Dart Container Corporation, Graphic Packaging International, WestRock Company, Georgia-Pacific LLC, Stora Enso Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycoated Cup Stock Market Evolving Landscape
Barrier chemistry innovation is racing ahead of certification infrastructure, creating temporary mismatches between laboratory-validated formulations and commercially approved products. Three developmental tracks are absorbing the bulk of converter R&D investment.
Water-based barrier coatings are absorbing market share in cold beverage applications where polyethylene extrusion was previously standard. Starbucks and Costa Coffee specifications in the United Kingdom now permit aqueous barriers for iced drinks under 12 ounces. This substitution is compressing demand for conventional extrusion coating lines while expanding aqueous coating capacity at mills in Finland and the Netherlands.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of oil and grease resistant barriers by December 2025. The European Chemicals Agency designation of PFAS as substances of very high concern is accelerating converter qualification of silicone-based and clay-modified alternatives. Hot beverage chains in Germany and Austria are conducting field trials with modified specifications to maintain supply continuity.
Direct-to-store distribution models are displacing traditional distributor intermediaries for large quick-service accounts. McDonald's and Chipotle procurement teams in the United States now negotiate mill-direct contracts with volume commitments spanning 3-5 years. This channel compression is visible in Texas and California where distributor inventory buffers have thinned, exposing operators to lead time volatility during mill maintenance shutdowns.
Polycoated Cup Stock Market Segmentation
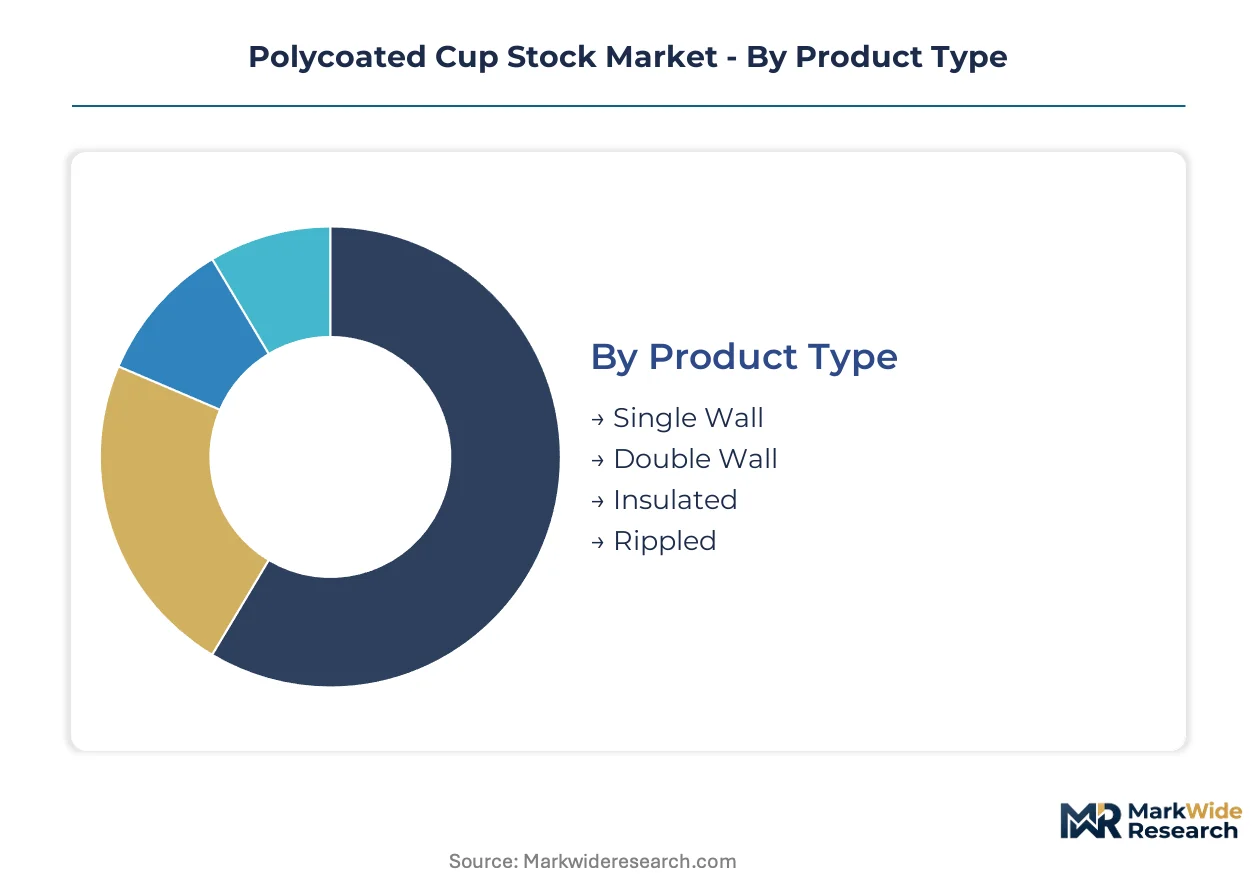
Polycoated cup stock procurement decisions hinge on thermal performance requirements, disposal infrastructure, and beverage temperature profiles. Converters align mill capacity with specific segment specifications to capture premium positioning in quick-service supply chains.
Product Type:
Quick-service operators cycle through cup formats as beverage menus expand and sustainability mandates tighten, driving specification upgrades across thermal performance tiers.
- Single Wall:Lightweight paperboard construction with single polyethylene barrier layer, typically 200-250 gsm. Demand clusters in cold beverage applications at United States quick-service chains where cost-per-unit drives procurement. California and Texas distribution centers stock this grade for high-volume iced coffee programs.
- Double Wall:Dual-layer construction with air-gap insulation eliminating need for separate sleeves. European coffee chains in Germany and France specify this format for hot beverages to meet EU Single-Use Plastics Directive compliance while maintaining hand-comfort standards.
- Insulated:Foam-integrated or advanced barrier configurations for extended heat retention.
- Rippled:Textured outer surface providing grip and marginal insulation without sleeve requirement.
Volume placements concentrate in Single Wall; the faster expansion belongs to Double Wall.
Material Type:
Raw material selection now tracks disposal pathway availability and regulatory pressure on coating chemistries rather than unit cost alone.
- Paperboard:Bleached kraft or SBS substrate forming structural base of conventional polycoated stock. German quick-service operators specify FSC-certified grades to satisfy VerpackG extended producer responsibility requirements, with mills in Finland and Sweden capturing this certified demand.
- Biodegradable:PLA or aqueous barrier alternatives qualifying for industrial composting streams. United Kingdom university food service and corporate campus operators mandate BPI certification, pulling supply from Dutch and Belgian converters with validated composting pathways.
- Plastic:Polypropylene or PET-lined formats retaining specification in high-temperature soup and tea applications.
- Wax-Coated:Paraffin or vegetable-based barriers for limited cold beverage niches.
Paperboard commands the installed base; Biodegradable climbs the fastest as certification infrastructure matures.
End User:
Customer procurement sophistication varies dramatically across institutional, commercial, and retail channels, dictating specification complexity and contract structure.
- Food Service:Quick-service restaurants, coffee chains, and institutional cafeterias with direct mill relationships. McDonald's and Chipotle procurement teams in the United States negotiate 3-5 year volume commitments, compressing distributor margins and demanding lot-level traceability.
- Retail:Supermarket and convenience store private-label programs with seasonal promotional requirements.
- Industrial:Food processing and beverage manufacturing captive packaging operations.
- Catering:Event and hospitality services with sporadic large-batch purchasing patterns.
Contract value pools deepest in Food Service; Catering exhibits the most volatile demand cadence.
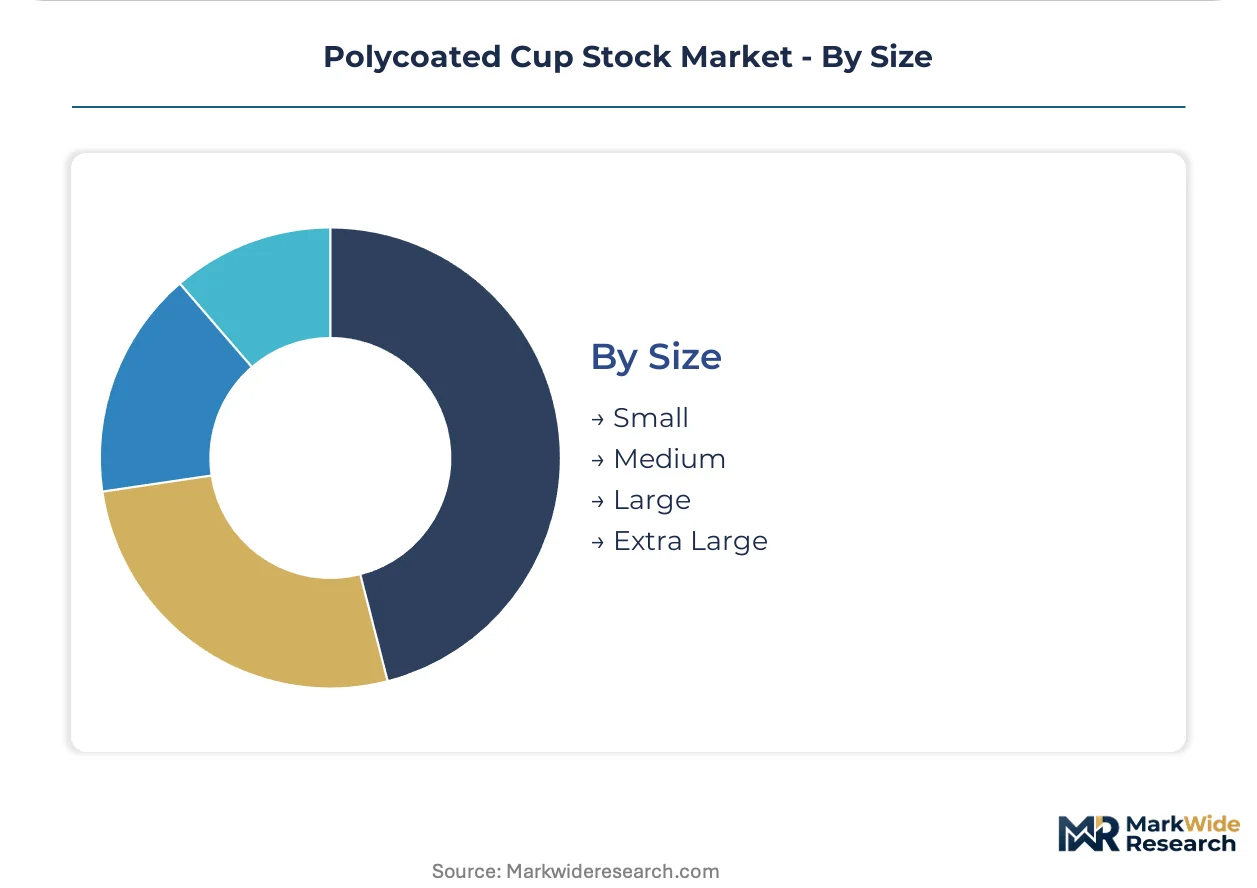
Size:
Portion standardization across beverage categories creates predictable volume ladders, though specialty formats are gaining traction in premium positioning strategies.
- Small:8-10 ounce formats for espresso-based drinks and children's portions.
- Medium:12-16 ounce specification dominating United States quick-service iced beverage programs.
- Large:20-24 ounce capacity for fountain soda and specialty coffee applications.
- Extra Large:30+ ounce formats for cinema, stadium, and convenience store fountain programs.
Medium size anchors procurement volumes; Large formats expand most quickly as specialty coffee chains upsize standard offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American polycoated cup stock procurement through its concentration of quick-service restaurant headquarters and distribution infrastructure.
United States
Texas and California distribution centers stock single-wall grades for high-volume iced coffee programs. FDA 21 CFR compliance governs direct food contact specifications. McDonald's and Chipotle procurement teams negotiate mill-direct contracts spanning 3-5 years, compressing distributor margins across the Midwest and Southeast.
Germany
Berlin and Paris quick-service operators accelerate specification changes to avoid VerpackG compliance penalties. The EU Single-Use Plastics Directive redirects converter capex toward fiber-based barrier technologies. Rhineland coating capacity clusters create geographic vulnerability to energy price spikes.
China
Shanghai and Beijing domestic food service chains adopt GB-standard specifications for local supply security. SAMR enforcement restricts certain polyethylene formulations, forcing export-oriented converters to qualify alternative barrier chemistries. Yangtze River Delta mills absorb R&D investment for aqueous coating scale-up.
India
Mumbai and Bangalore quick-service penetration remains underdeveloped relative to per-capita income trajectories. FSSAI implementation of stricter food contact material standards creates first-mover advantage for converters with pre-qualified barrier technologies. Western Maharashtra industrial corridors attract pilot coating line investments.
United Kingdom
London university food service and corporate campus operators mandate BPI certification for industrial composting streams. Costa Coffee specifications now permit aqueous barriers for iced drinks under 12 ounces. Dutch and Belgian converters capture certified demand through validated composting pathways.
Polycoated Cup Stock Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology sophistication and certification depth. The vendor base stratifies into integrated pulp-to-paperboard operators, specialized forming equipment owners, and regional converters with distributor relationships. Three archetypes dominate: integrated fiber giants with captive coating capacity, mid-scale specialists with compostability certifications, and contract converters serving private-label retail programs. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators secure volume commitments from quick-service accounts.
Among integrated fiber giants, Mondi Group, International Paper Company, and Huhtamäki Oyj occupy positions spanning the premium-to-mid margin spectrum. Mondi exemplifies the integrated pulp-to-paperboard archetype through its supply continuity focus for major quick-service accounts. International Paper anchors North American capacity positioning through mill-level infrastructure. Huhtamäki represents specialized forming expertise that reduces material weight without compromising liquid resistance. These three entities sit within the tier that captures the deepest contract value pools from food service procurement teams.
| Leading Market Players |
|---|
| Mondi Group |
| International Paper Company |
| Huhtamäki Oyj |
| Pactiv Evergreen Inc. |
| Dart Container Corporation |
| Graphic Packaging International |
| WestRock Company |
| Georgia-Pacific LLC |
| Stora Enso Oyj |
| Others |
Value Network & Pricing Analysis
Quick-service restaurant procurement teams with mill-direct contract structures anchor pricing power in the polycoated cup stock market. Their volume commitments spanning three-to-five years compress spot-market volatility while favoring suppliers with certified barrier technologies and lot-level traceability systems.
Pricing Analysis
Outcome-based pricing tied to liquid resistance performance and compostability certification anchors contract structures. Three-tier pricing stratifies across premium bio-based barrier grades, standard polyethylene-laminated stock, and economy single-wall formats for cold beverages. Pricing pressure intensifies as pulp cost volatility transmits through fixed-price annual contracts, squeezing converter margins. Food service chains with direct mill relationships exhibit lowest price sensitivity; private-label retail programs show highest elasticity to per-unit fluctuations.
Supply Chain Analysis
Certification infrastructure for BPI and OK Compost INDUSTRIAL qualifications gates mill access to premium contract tiers. Geographic supply concentrates in the United States, Germany, and Finland where integrated pulp-to-paperboard operations cluster. Raw material dependencies center on northern bleached softwood kraft pulp, specialized aqueous barrier chemistries, and extrusion-grade polyethylene resins. Single-source vulnerability runs through Rhineland and US Midwest coating capacity exposed to energy price spikes. Distribution feeds from mill-direct contracts for large quick-service accounts and distributor intermediaries for smaller retail programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polycoated cup stock market functions as a cost-of-compliance arena where EU REACH restrictions on per- and polyfluoroalkyl substances erect steep qualification barriers that favor incumbents with validated migration study portfolios.
For Market Incumbents: Deploy certification depth as a competitive moat by accelerating BPI and OK Compost INDUSTRIAL validation for bio-based barrier formulations before December deadlines. Channel control through mill-direct relationships with McDonald's and Chipotle procurement teams locks out regional converters lacking lot-level traceability infrastructure. Capacity addition in Finland and the Netherlands captures aqueous coating demand as Starbucks and Costa Coffee specifications shift. For New Entrants and Emerging Players: E-commerce-enabled specialty coating services offer a low-capital entry path serving university food service and corporate campus operators with sub-container-load minimums. White-space concentrates in India where FSSAI implementation lags qualified supplier penetration, and in reusable cup deposit systems for Copenhagen and Amsterdam municipal mandates. A forming-equipment-leasing model paired with barrier chemistry tolling sidesteps mill-level capital intensity. For Investors and Strategic Acquirers: The window for entry favors mid-scale specialists with compostability certifications and established quick-service relationships over commodity-grade producers facing margin compression. Long-term viability hinges on coating chemistry R&D pipelines and geographic diversification beyond single-region pulp dependencies. Watch for SAMR enforcement actions on polyethylene formulations as a signal for accelerated bio-based barrier adoption in export-oriented production.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Chemistry R&D Partnership | Joint development of PLA and aqueous formulations with hot-fill tolerance above 85°C unlocks specialty tea and soup specifications. |
| Compostability Certification Fast-Track | Pre-qualified BPI and OK Compost INDUSTRIAL status captures university food service and corporate campus procurement mandates. |
| Mill-Direct Contract Negotiation | Three-to-five year volume commitments with McDonald's and Chipotle procurement teams displace distributor intermediaries. |
| Coating Capacity Geographic Diversification | Yangtze River Delta and Western Maharashtra investments reduce Rhineland and US Midwest concentration risk. |
| Digital Printing Inline Integration | Inkjet decoration at cup-forming lines enables short-run regional beverage promotions without pre-printed roll stock inventory. |
Research Methodology
Trade association filings, customs export records, and regulatory submission databases formed the secondary backbone for supply-side calibration. Primary interviews with coating line operators, quick-service procurement directors, and mill technical sales managers validated barrier chemistry adoption timelines. Conversations with university food service contractors and corporate campus facility managers tested compostability certification demand intensity. Bottom-up volume modeling triangulated against top-down pulp consumption analysis.
Historical trendline analysis of polycoated cup stock shipments anchored the projection framework across the analysis window. Segmentation dimensions included product type, material grade, end-use channel, and geographic regulatory cluster. CAGRs derived from regression-adjusted growth rates incorporating pulp price elasticity and coating technology substitution curves. Forecast inputs integrated EU Single-Use Plastics Directive compliance deadlines and SAMR enforcement trajectories for polyethylene formulation restrictions.
The model holds under stable regulatory enforcement timelines; deviation in REACH restriction implementation dates or FSSAI standard acceleration would shift bio-based barrier adoption curves. Forecasts reflect assumptions on certification infrastructure maturation and quick-service specification change velocity. A model refresh is warranted upon material change in extended producer responsibility fee structures or coating chemistry migration study timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Strip Pack Laminates Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Desiccant Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
PET Strap Market