
 Next Generation Processors Market | 2026-2036
Next Generation Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Processors Market Foresight
The EU AI Act is realigning the cost-of-entry calculus for processor vendors serving European data centers and automotive clients. Intel Corporation leverages its foundry investments to sustain manufacturing scale across multiple nodes. Nvidia Corporation dominates AI accelerator architecture through proprietary interconnect and software ecosystems. Qualcomm Incorporated anchors mobile and automotive edge processor design with integrated modem-AI platforms.
Next generation processors integrate advanced semiconductor architectures fabricated at nanometer-scale nodes to execute complex computational workloads with optimized power efficiency. These devices employ multi-core configurations, 3D chip stacking, and specialized AI acceleration engines to deliver throughput measured in teraflops while managing thermal design power constraints. Server processors command the largest revenue pool as hyperscalers refresh infrastructure for generative AI training and inference. AI accelerators represent the fastest-expanding technology segment, outpacing conventional CPU growth as cloud providers deploy custom tensor processing units. Embedded processors serving automotive and IoT end users are maturing into high-margin categories as functional safety certification becomes a prerequisite for market access.
FDA guidelines on software as a medical device and EPA energy efficiency standards for data center equipment are reshaping validation requirements for processors deployed in healthcare and cloud environments. The EU AI Act, alongside REACH substance restrictions on semiconductor materials, is forcing redesign cycles that favor vendors with established European compliance operations. Stakeholders must monitor how export control frameworks evolve for advanced node manufacturing equipment, as these restrictions will determine which geographies can participate in next-generation fabrication.
Market Dynamics
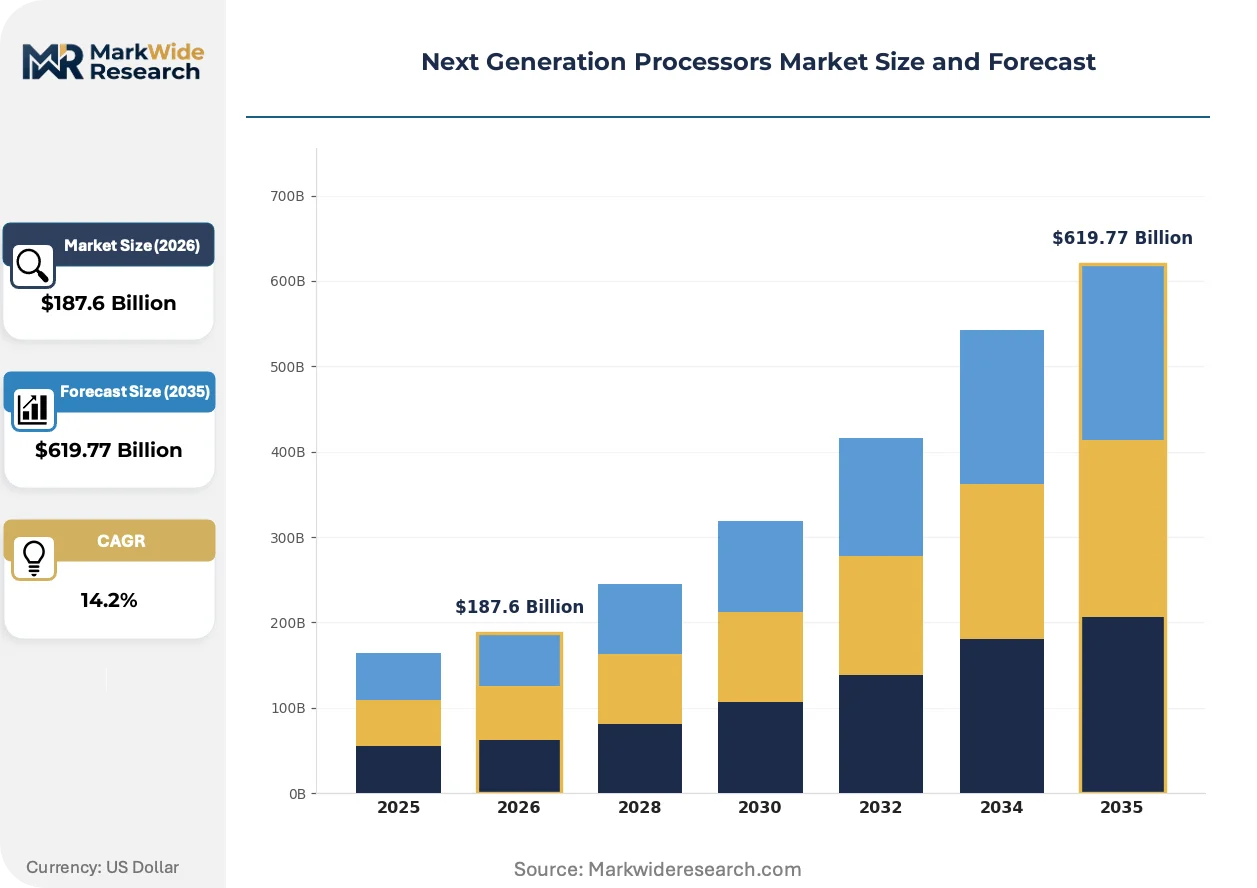
Hyperscaler procurement of custom AI accelerators is compressing design cycles and forcing foundry capacity allocation toward advanced nodes, while the EU AI Act imposes compliance burdens that favor vendors with established European certification operations.
Growth Catalysts
- EU AI Act compliance mandates:The regulation's risk-classification framework for high-risk automated systems is creating dedicated procurement channels for certified processors in European data centers and automotive supply chains.
- Chiplets and 3D stacking:Advanced packaging technologies are enabling performance gains without sole reliance on monolithic die shrinks, expanding design flexibility for AI training workloads.
- United States hyperscaler capex:Cloud providers are expanding custom silicon programs that bypass merchant processor roadmaps, directly funding foundry capacity at Taiwan Semiconductor Manufacturing Company and Samsung Foundry.
Market Restraints
- Extreme ultraviolet lithography equipment concentration:Dutch and Japanese export controls on ASML and Nikon/Screen Holdings systems are constraining which geographies can fabricate at 3nm and below.
- Advanced substrate scarcity:Ajinomoto Build-up Film and other high-density organic substrate suppliers are capacity-constrained, creating bottlenecks for chiplet-based designs regardless of node availability.
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for automotive processors extends development cycles by 18-24 months, freezing out fabless entrants without established safety cultures.
Strategic Opportunities
- India semiconductor ecosystem:The country's PLI scheme for electronics manufacturing is attracting assembly and test operations, creating a lower-cost node for processors serving price-sensitive IoT and industrial segments.
- Edge AI inference at automotive tier-1s:On-vehicle neural processing for autonomous driving and cabin monitoring is opening processor sockets outside traditional central compute architectures.
- EPA ENERGY STAR for data center servers:The efficiency benchmarking program is tilting procurement specifications toward processors with dynamic voltage-frequency scaling and specialized low-power inference modes.
Industry Challenges
- Physical design engineering scarcity:Expertise in 3nm and below custom layout, electromigration analysis, and thermal-aware floorplanning is concentrated at a handful of design services firms and captive teams.
- Co-packaged optics integration:Merging silicon photonics with processor dies requires new assembly flows, test protocols, and supply chain coordination that strain existing outsourced semiconductor assembly and test networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Processors Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Processors, Mobile Processors, Server Processors, Embedded Processors Technology: AI Accelerators, Quantum Computing, Multi-Core, 3D Chip Technology End User: Gaming, Data Centers, Automotive, IoT Devices Application: Cloud Computing, Machine Learning, Real-Time Processing, High-Performance Computing |
| Companies Covered | Intel Corporation, Advanced Micro Devices, Inc, Nvidia Corporation, Qualcomm Incorporated, IBM Corporation, Fujitsu Ltd, Apple Inc., AMD, Cerebras Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Processors Market Shifts & Advancements
Processor architecture is fragmenting into workload-specialized designs that trade general-purpose flexibility for tensor operation efficiency, while regulatory pressure on energy consumption and algorithmic transparency is embedding compliance into hardware roadmaps.
Chiplet-based disaggregation is rewriting how performance scaling economics work for server processors. AMD and Intel have deployed multi-die configurations that mix process nodes within a single package, and hyperscalers are now specifying custom chiplets for their internal workloads. This modularity is compressing time-to-market for specialized accelerators while decoupling memory and logic scaling roadmaps.
The EU AI Act's conformity assessment requirements for high-risk systems are forcing processor vendors to embed audit logging, deterministic execution modes, and fault containment into silicon. European data center operators are now demanding documentation trails that trace training data provenance through hardware execution paths. Vendors with existing automotive functional safety cultures are repurposing those quality systems to capture this compliance premium.
Hyperscalers are unbundling traditional server processor procurement into disaggregated component sourcing—purchasing chiplets, memory stacks, and interconnect silicon separately for in-house integration. This bypass of merchant socket definitions is most visible in United States cloud campuses, where custom accelerators now outnumber general-purpose CPUs in new training cluster deployments. The shift is compressing incumbent vendor design-in cycles and favoring foundry-direct relationships.
Next Generation Processors Market Segmentation
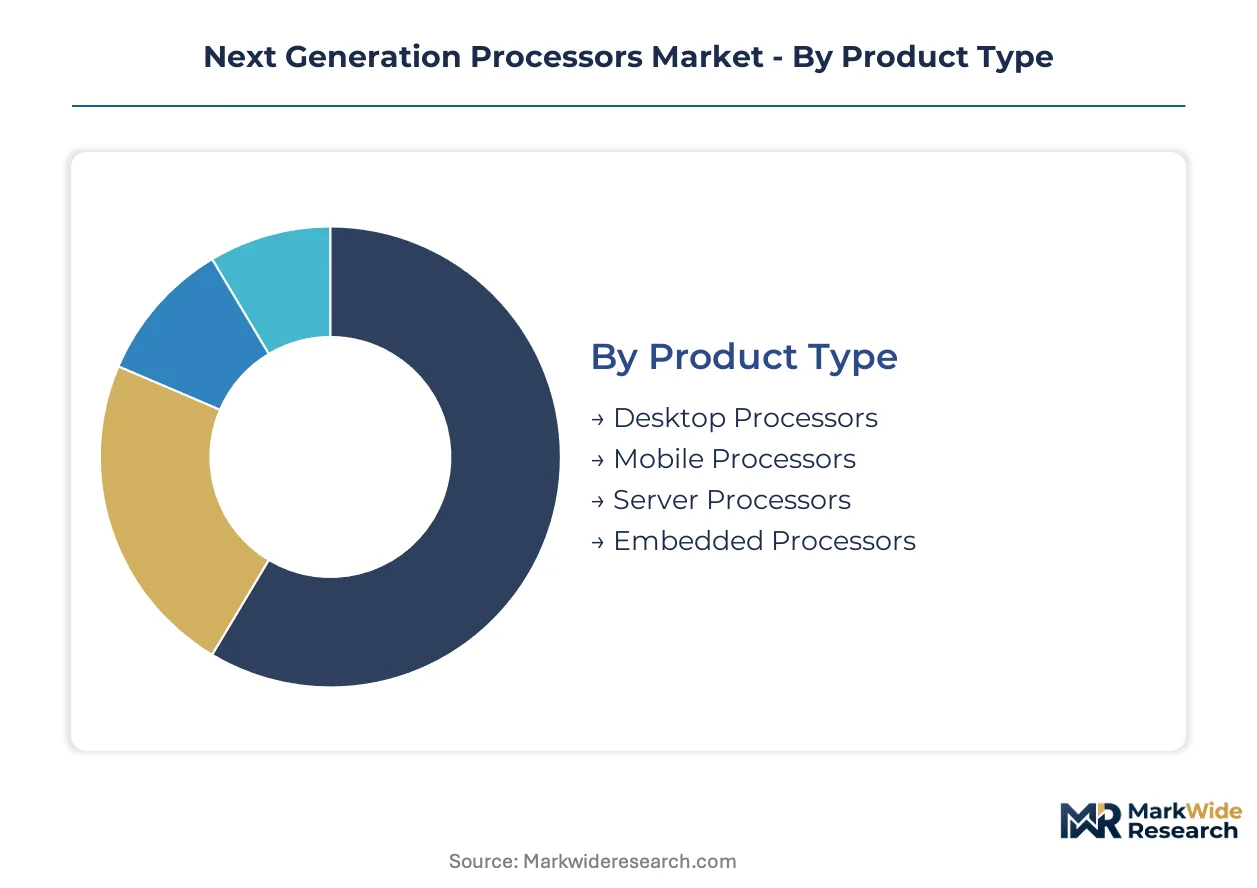
Processor segmentation reveals how architectural specialization fragments procurement patterns across computing environments. Each dimension—product form, underlying technology, end-use sector, and workload type—carries distinct margin structures and compliance burdens that reshape vendor positioning.
Product Type:
Integration depth varies sharply: server and embedded processors ship as socketed components or soldered subsystems, while mobile and desktop units reach end-users as standalone retail products.
- Server Processors:Multi-socket configurations with high core counts and extensive cache hierarchies dominate hyperscaler infrastructure refresh cycles. United States cloud campuses concentrate procurement of custom variants that bypass merchant roadmaps, with thermal design power envelopes now exceeding 350W per socket.
- Embedded Processors:Heterogeneous SoCs with integrated neural engines and functional safety islands serve automotive domain controllers and industrial edge nodes. ISO 26262 ASIL-D qualification timelines extend development cycles, freezing out fabless entrants without established safety cultures.
- Desktop Processors:Unlocked multiplier variants target enthusiast overclocking segments with discrete GPU pairings.
- Mobile Processors:Tightly integrated modem-AI platforms power smartphone flagships with aggressive thermal constraints.
Server processors lead volumes today; embedded variants are gaining share fastest.
Technology:
Cost tier stratification separates premium tensor-optimized silicon from commodity multi-core dies, with quantum approaches occupying speculative R&D budgets.
- AI Accelerators:Proprietary interconnect fabrics and sparse matrix execution units optimize training throughput for generative workloads. Hyperscaler capex on custom tensor processing units now outpaces general-purpose CPU procurement in new cluster deployments.
- 3D Chip Technology:Hybrid bonding and through-silicon vias enable memory-logic stacking that decouples scaling roadmaps. Ajinomoto Build-up Film scarcity constrains substrate supply regardless of node availability.
- Multi-Core:Homogeneous core arrays with shared L3 caches serve legacy enterprise workloads.
- Quantum Computing:Cryogenic control electronics and superconducting qubit interfaces remain laboratory-bound.
Multi-core architectures lead volumes today; AI accelerators are climbing the fastest.
End User:
Application maturity determines whether processors ship as validated subsystems or merchant components, with automotive and data center demands imposing the strictest qualification regimes.
- Data Centers:Rack-scale deployments of disaggregated chiplets, memory stacks, and interconnect silicon bypass traditional server vendor definitions. EPA ENERGY STAR benchmarking tilts procurement toward dynamic voltage-frequency scaling capabilities.
- Automotive:Zonal architectures with centralized neural processing units demand deterministic execution modes and fault containment under EU AI Act conformity assessments.
- Gaming:Discrete GPU pairing and high-refresh display output drive core frequency optimization.
- IoT Devices:Ultra-low-power sleep states and intermittent wake architectures serve battery-constrained sensors.
Data center deployments lead volumes today; automotive sockets are expanding most quickly.
Application:
Workload characteristics dictate whether processors emphasize throughput, latency, or energy efficiency, with cloud and machine learning demands reshaping foundry capacity allocation.
- Cloud Computing:Virtualization extensions and encrypted memory domains serve multi-tenant infrastructure at Taiwan Semiconductor Manufacturing Company and Samsung Foundry advanced nodes. United States hyperscalers now specify custom chiplets for internal workload optimization.
- Machine Learning:Mixed-precision matrix multiply engines with specialized data movement reduce training time for large language models. EU AI Act audit logging requirements embed provenance tracing into silicon execution paths.
- Real-Time Processing:Deterministic interrupt latency and cache partitioning serve industrial control loops.
- High-Performance Computing:Vector extensions and high-bandwidth memory integration target simulation workloads.
Cloud computing leads volumes today; machine learning deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized physical design engineers cluster around Taiwan Semiconductor Manufacturing Company's advanced node fabs and Samsung Foundry's Pyeongtaek complex, concentrating expertise for 3nm and below tape-outs. This talent concentration shapes where processor vendors establish development centers and foundry partnerships.
United States
Hyperscaler capex on custom AI accelerators drives procurement of disaggregated chiplets and memory stacks at cloud campuses in Oregon, Arizona, and Texas. EPA ENERGY STAR benchmarking for data center servers tilts specifications toward dynamic voltage-frequency scaling capabilities. The Pacific Northwest corridor hosts training clusters where custom silicon outnumbers merchant CPUs in new deployments.
Taiwan
Foundry capacity allocation at Taiwan Semiconductor Manufacturing Company compresses design cycles for AI training accelerators as Apple, Nvidia, and AMD compete for 3nm wafer starts. The island's National Development Council prioritizes semiconductor talent retention through immigration fast-tracks for analog and mixed-signal engineers. Hsinchu Science Park anchors the world's densest concentration of extreme ultraviolet lithography systems and advanced packaging operations.
South Korea
Samsung Foundry's Pyeongtaek complex expands 3nm gate-all-around production for internal Exynos programs and external AI accelerator customers. METI-aligned national semiconductor strategies fund high-bandwidth memory stacking research at Seoul National University and KAIST. The Suwon-Yongin corridor concentrates backend assembly and test capacity for chiplet-based processor modules.
China
Domestic cloud providers accelerate procurement of locally designed AI accelerators as MIIT indigenous computing initiatives redirect infrastructure budgets toward homegrown tensor processing units. SMIC's 7nm-equivalent node serves military and surveillance applications outside Western export controls. The Yangtze River Delta cluster around Shanghai maintains assembly and test operations for legacy node processors serving industrial IoT segments.
Germany
Automotive OEMs in Stuttgart and Munich demand ISO 26262 ASIL-D qualified embedded processors for zonal architectures with centralized neural compute. The EU AI Act's conformity assessment requirements for high-risk automated systems force documentation trails tracing training data provenance through hardware execution paths. Bavaria's semiconductor ecosystem around Ingolstadt and Regensburg specializes in functional safety certification services that extend development cycles by 18-24 months.
Next Generation Processors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where foundry access and software ecosystem lock-in determine positioning. The vendor base stratifies between captive silicon operations at hyperscalers, merchant processor vendors with full-stack portfolios, and fabless AI accelerator startups. Three archetypes dominate: integrated device manufacturers leveraging captive fabrication, fabless designers dependent on foundry partnerships, and cloud providers developing in-house silicon. Competitive moves center on foundry capacity reservation agreements and strategic acquisitions of physical design services firms.
Within the integrated device manufacturer tier, Intel Corporation and IBM Corporation exemplify vertical fabrication strategies spanning multiple process nodes. Among fabless specialists, Nvidia Corporation and Qualcomm Incorporated occupy positions defined by proprietary interconnect fabrics and modem-AI integration respectively. Cerebras Systems represents the wafer-scale acceleration archetype targeting training workloads outside conventional socket definitions.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices, Inc |
| Nvidia Corporation |
| Qualcomm Incorporated |
| IBM Corporation |
| Fujitsu Ltd |
| Apple Inc. |
| AMD |
| Cerebras Systems |
| Others |
Supply & Pricing Matrix
Chiplet-based disaggregation is compressing cost curves for AI accelerators while redistributing pricing power toward foundry-direct hyperscaler relationships and away from traditional merchant CPU vendors. Advanced packaging investments at Taiwan Semiconductor Manufacturing Company and Samsung Foundry now command premium wafer pricing that propagates through substrate-scarce supply chains.
Pricing Analysis
Bundled processor-socket procurement from Intel and AMD faces unbundled component sourcing by United States hyperscalers purchasing chiplets, memory stacks, and interconnect silicon separately. Pricing stratifies across ASIL-D certified automotive processors, enterprise-grade server SKUs with extended validation, and price-optimized IoT variants where Indian assembly operations enable cost competitiveness. Cost compression in general-purpose multi-core segments intensifies as cloud providers bypass merchant roadmaps, while AI accelerator pricing holds firmer due to sparse matrix execution specialization. Data center operators exhibit lowest price sensitivity given workload-optimized performance requirements; industrial IoT buyers face tightest procurement constraints.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing is redirecting assembly and test operations away from legacy China-centric configurations, though extreme ultraviolet lithography equipment concentration in the Netherlands and Japan constrains advanced node fabrication geography. Substrate supply draws from Ajinomoto Build-up Film suppliers in Japan, high-bandwidth memory stack production in South Korea, and silicon wafer refining in the United States. Single-source vulnerability at ASML for EUV systems creates chokepoint exposure regardless of geographic diversification elsewhere. Distribution runs through foundry-direct relationships with hyperscalers, bypassing traditional distributor channels for advanced AI accelerators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Processor procurement is becoming a geographic-arbitrage play between Taiwan's advanced node concentration and India's emerging assembly cost advantages, with EU AI Act compliance costs tilting total-cost-of-ownership calculations toward European-certified vendors.
For Market Incumbents: To counter hyperscaler bypass of merchant socket definitions, Intel and AMD must deepen foundry partnership reservations at Taiwan Semiconductor Manufacturing Company while accelerating in-house advanced packaging capacity. Certification investment in EU AI Act conformity assessment capabilities captures procurement channels at European automotive OEMs and data center operators. Channel control through design-in support for automotive tier-1s extends engagement timelines beyond commodity server refresh cycles.
For New Entrants and Emerging Players: Automotive tier-1 suppliers represent the most penetrable channel for edge AI inference processors outside central compute architectures. Target zonal architecture sockets with deterministic execution modes and fault containment features that incumbent mobile-focused vendors lack. White-space exists in EPA ENERGY STAR compliant low-power inference modes for data center edge deployments where hyperscaler custom silicon does not reach.
For Investors and Strategic Acquirers: Valuations sit cheapest among physical design services firms with 3nm and below tape-out expertise concentrated around Hsinchu and Pyeongtaek. Long-term viability hinges on foundry capacity reservation visibility and automotive functional safety culture transferability. Physical design engineering scarcity at specialized services firms signals inflection when acquisition premiums compress relative to captive team buildout costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Secures wafer starts at Taiwan Semiconductor Manufacturing Company for AI accelerator tape-outs ahead of hyperscaler competition. |
| EU AI Act Certification Investment | Opens procurement channels at Stuttgart and Munich automotive OEMs requiring conformity assessment documentation trails. |
| Physical Design Services Acquisition | Captures scarce 3nm custom layout expertise concentrated at Hsinchu Science Park design services firms. |
| India Assembly Footprint Expansion | Reduces cost position for price-sensitive IoT and industrial segments under PLI scheme incentives. |
| Co-Packaged Optics Integration | Merges silicon photonics with processor dies for training cluster bandwidth scaling at United States cloud campuses. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hyperscaler infrastructure procurement officers, automotive tier-1 supplier engineering directors, foundry account managers at Taiwan Semiconductor Manufacturing Company and Samsung Foundry, and physical design services firm technical leads with secondary validation against SEC hyperscaler capex disclosures, EPA ENERGY STAR server certification databases, EU AI Act implementation guidance documents, and ISO 26262 functional safety audit records. Bottom-up unit economics from chiplet cost modeling and top-down market sizing from foundry wafer allocation data were triangulated for consistency.
Segment-weighting approaches distributed value across server, embedded, desktop, and mobile processor form factors, with technology segmentation separating AI accelerators, 3D chip implementations, multi-core architectures, and quantum computing R&D, and end-use segmentation capturing data center, automotive, gaming, and IoT deployment patterns. CAGRs were derived from foundry capacity expansion announcements, hyperscaler infrastructure refresh cadences, and automotive platform electrification timelines across the projection horizon. Model inputs incorporated EU AI Act compliance cost pass-through assumptions and extreme ultraviolet lithography equipment export control scenario sensitivities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASML equipment export control tightening, Ajinomoto Build-up Film capacity expansion delays, and hyperscaler custom silicon program acceleration or cancellation decisions. Forecasts reflect documented assumptions around foundry yield learning curves and automotive functional safety certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Global Terahertz Technology Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Swarm Intelligence Market