
 Global WI SUN Technology Market | 2026-2036
Global WI SUN Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global WI SUN Technology Market Intelligence
China's significant investment in domestic semiconductor fabrication for IoT devices is rewriting supply chain dynamics for WI SUN components. Texas Instruments leverages its extensive portfolio of microcontrollers and transceivers to serve diverse end markets. Semtech Corporation specializes in long-range, low-power technologies like LoRa, which complements WI SUN in certain applications. NXP Semiconductors competes through its secure connectivity solutions for smart city and industrial automation deployments.
WI SUN technology defines a wireless communication protocol based on the IEEE 802.15.4g standard for low-power, wide-area networks. It operates in sub-GHz frequency bands to ensure robust connectivity over long distances for applications like utility metering. Within product types, gateways and controllers form the backbone of network infrastructure, commanding higher value. The smart home application segment represents the fastest-growing area, driven by consumer demand for automated energy and security systems.
Regulatory frameworks from the FCC in the United States and compliance with CE marking in Europe dictate radio frequency spectrum allocation and device certification. In China, the MIIT governs wireless standards, influencing market access for both domestic and foreign component suppliers. These standards directly impact design and interoperability for device manufacturers. Future success depends on developing solutions that can seamlessly integrate across different regional communication protocols and smart grid architectures.
Market Dynamics
The central dynamic shaping the WI SUN technology market is the tension between regionally fragmented wireless standards and the globalized nature of semiconductor supply chains. Component manufacturers must navigate divergent frequency allocation rules from bodies like the FCC, MIIT, and European regulators while attempting to maintain scale.
Growth Catalysts
- Smart Grid Mandates:Government policies in developed economies promoting energy efficiency and grid modernization are compelling utilities to deploy Advanced Metering Infrastructure (AMI), creating a foundational demand for WI SUN-based communication networks.
- Proliferation of IoT Devices:The expansion of smart home and smart city ecosystems requires low-power, wide-area networking solutions to connect a massive number of sensors and actuators for applications ranging from environmental monitoring to automated lighting.
- Utility Deployment Concentration:Large-scale rollouts of smart meters by utilities across the United States and Japan provide significant, stable volume demand for WI SUN modules and gateways, anchoring the market's core revenue base.
Market Restraints
- Competition from Alternative LPWANs:The availability of competing low-power, wide-area network technologies, including LoRaWAN and NB-IoT, creates market fragmentation and can lead to customer uncertainty, slowing adoption decisions in certain applications.
- Spectrum Allocation Fragmentation:Operating in unlicensed sub-GHz bands requires device manufacturers to engineer products for different regional frequency and power regulations, such as those from the FCC and CE marking directives, increasing design complexity and cost.
- High Initial Infrastructure Cost:The capital expenditure required to install a dense network of gateways and routers for a full-scale utility or smart city deployment can be a significant barrier for municipalities and smaller utility providers.
Strategic Opportunities
- Expansion into Smart Agriculture:Applying WI SUN for long-range sensor networks to monitor soil conditions, control irrigation, and track assets in rural and agricultural settings represents a significant, underpenetrated vertical market.
- Convergence with Edge Computing:Integrating processing capabilities directly into WI SUN gateways and nodes enables localized data analytics for industrial predictive maintenance and real-time grid fault detection, creating higher-value service opportunities.
- Smart City Initiatives in Southeast Asia:Emerging smart city projects in countries like Vietnam and Indonesia present new geographic markets for WI SUN deployments, particularly for public lighting, traffic management, and waste management systems.
Industry Challenges
- Legacy System Integration:A primary operational hurdle for utilities is the complex and costly process of integrating new WI SUN-based AMI networks with their existing operational technology (OT) and customer information system (CIS) software.
- Standardization and Interoperability:Ensuring seamless interoperability and backward compatibility between devices from different vendors built on evolving versions of the IEEE 802.15.4g standard remains a persistent challenge for the ecosystem.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global WI SUN Technology Market |
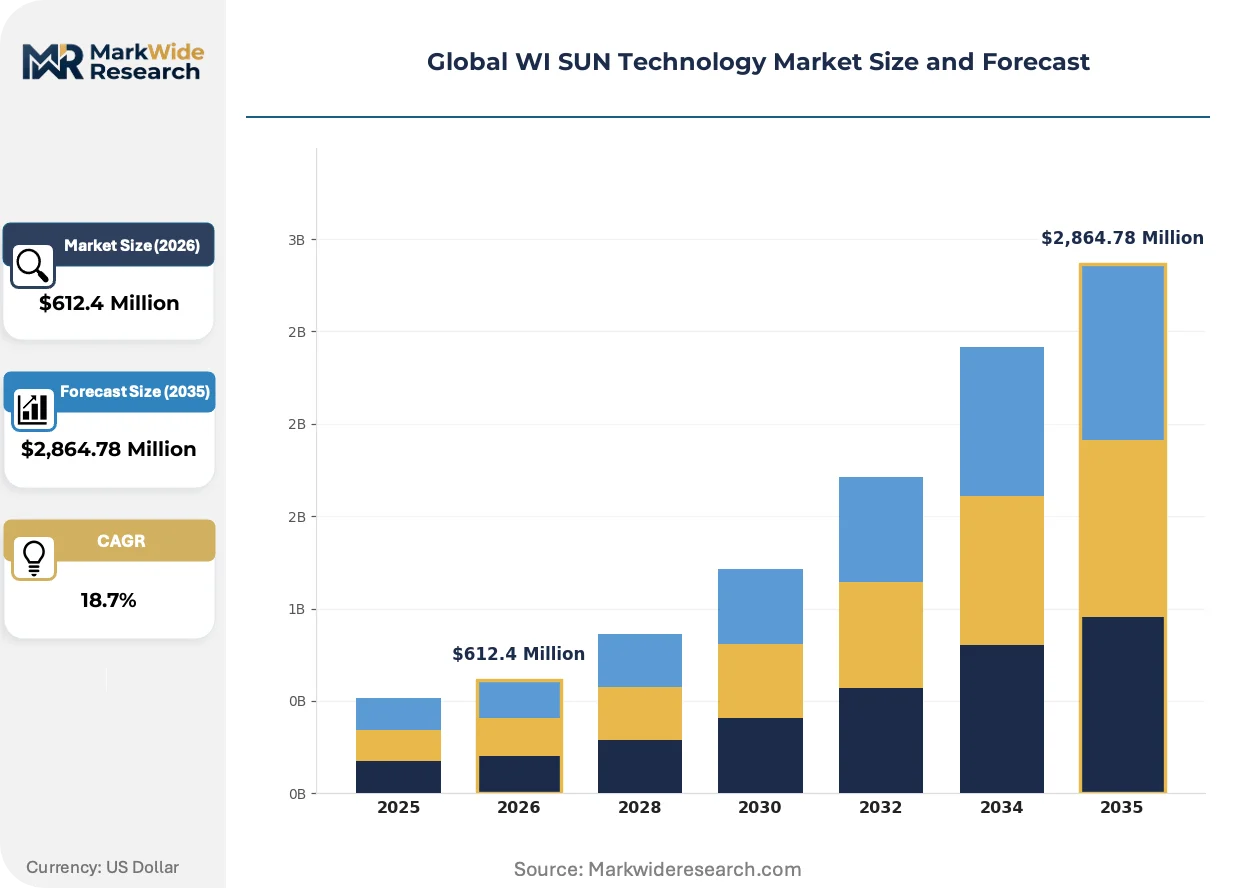
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor, Transmitter, Gateway, Controller Technology: RFID, Zigbee, LoRa, Bluetooth Application: Agriculture, Smart Home, Environmental Monitoring, Asset Tracking End User: Farmers, Manufacturers, Retailers, Logistics Providers |
| Companies Covered | Semtech Corporation, NXP Semiconductors, Texas Instruments, Microchip Technology, Analog Devices, Renesas Electronics Corporation, Cisco Systems, Itron, Landis+Gyr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global WI SUN Technology Market Strategic Shifts & Innovations
A clear shift from single-purpose network deployments toward multi-functional, hybrid communication architectures defines the market's evolution. This transition prioritizes flexibility and future-proofing investments in smart infrastructure, moving beyond basic metering to support a wider array of IoT services.
Multi-protocol chipsets that integrate WI SUN with other wireless standards like Bluetooth Low Energy (BLE) are becoming a product focus. Smart city and industrial IoT device manufacturers are adopting these advanced System-on-Chips to build more versatile endpoints. This development is hybridizing network architectures, allowing a single device to use WI SUN for long-range data backhaul while using BLE for local device commissioning.
Europe's regulatory drive for grid modernization, guided by policies within the EU Green Deal, is creating powerful tailwinds. These frameworks compel utilities to invest in digital technologies for enhanced energy monitoring and management to meet stringent efficiency targets. The smart metering segment is most directly affected, with European utilities accelerating deployment schedules for compliant AMI systems.
A notable behavioral shift sees enterprise and municipal customers procuring complete, integrated solutions instead of discrete hardware components. This trend disrupts traditional distribution channels that focus on selling modules, favoring system integrators who can deliver and manage end-to-end network services. The pattern is most visible in North American smart city projects for intelligent traffic and lighting systems.
Global WI SUN Technology Market Segmentation
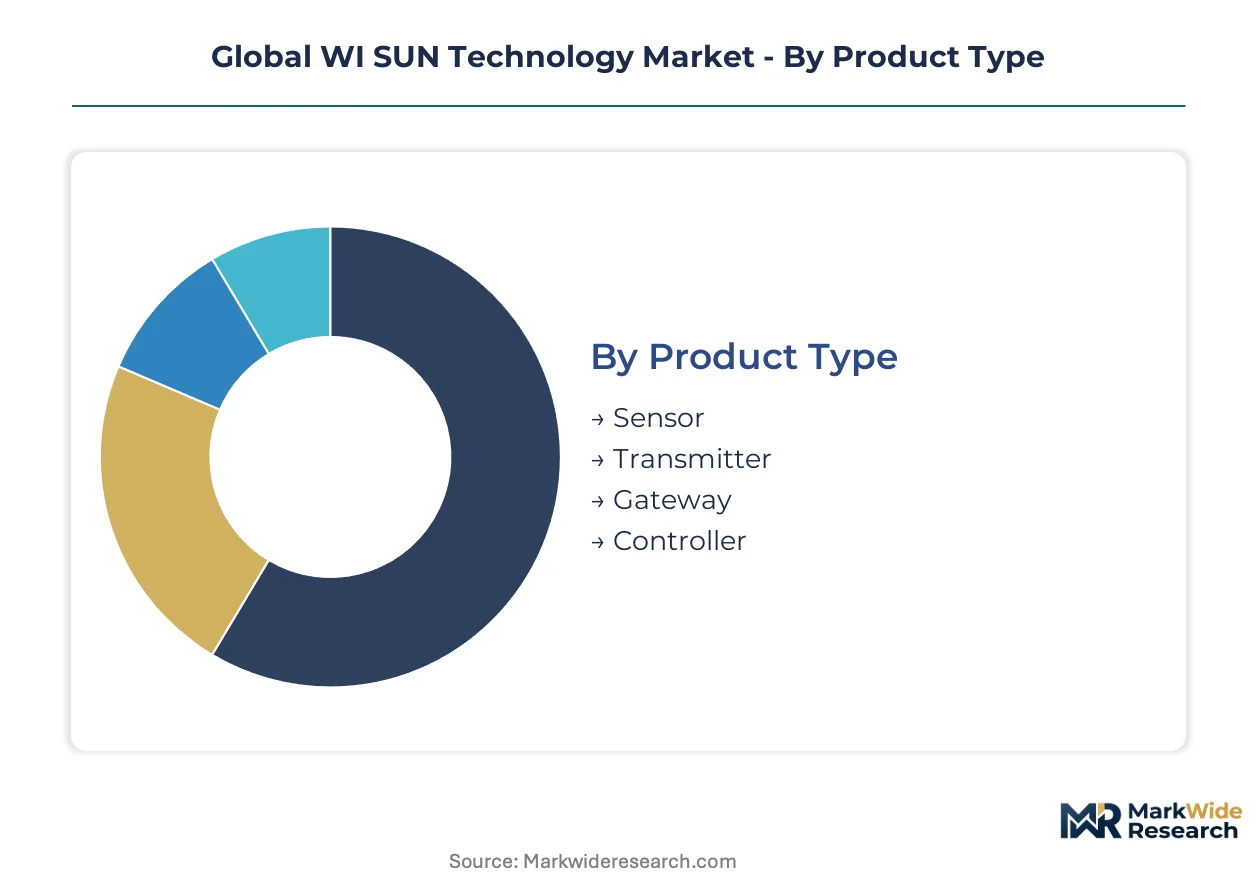
Understanding the Global WI SUN Technology Market through segmentation provides clarity on where value creation and demand aggregation occur. This detailed breakdown helps pinpoint specific product types, underlying technologies, application areas, and end-user groups that drive market expansion. Analyzing these segments reveals distinct growth patterns and competitive landscapes across the WI SUN ecosystem.
Product Type:
The after-sales service intensity for WI SUN products varies significantly, with complex infrastructure components demanding more specialized support than simpler endpoints.
- Gateway:These devices serve as the central communication hub, aggregating data from numerous WI SUN nodes and forwarding it to a central network or cloud platform. Demand concentrates within large-scale utility metering deployments in the United States, driven by the need for robust data backhaul.
- Controller:Controllers manage network operations, device configuration, and data routing within the WI SUN mesh network, ensuring reliable and secure data flow. Smart city initiatives in Europe require advanced controllers for intelligent lighting and traffic management systems, enhancing operational efficiency.
- Sensor:Sensors collect various environmental or operational data points, such as temperature, humidity, or energy consumption, and transmit them via the WI SUN network.
- Transmitter:Transmitters are responsible for sending data from devices to gateways, often integrated into smart meters or other IoT endpoints.
Gateway holds the largest share; momentum sits with Controller.
Technology:
Supply concentration for WI SUN-compatible technologies is diverse, reflecting varied development pathways and intellectual property landscapes.
- LoRa:This long-range, low-power wireless technology is optimized for wide-area IoT applications, offering deep penetration and extensive coverage, often complementing WI SUN in hybrid deployments. Demand is strong in smart agriculture for remote sensor monitoring across vast fields.
- Zigbee:A low-power, short-range wireless standard primarily used for mesh networks in home automation and industrial control applications, often integrated into multi-protocol chipsets alongside WI SUN. Smart home applications in Japan utilize Zigbee for local device control and automation.
- RFID:Radio-frequency identification technology uses electromagnetic fields to automatically identify and track tags attached to objects.
- Bluetooth:This short-range wireless technology connects devices over short distances, increasingly integrated into multi-protocol chipsets for local device commissioning and diagnostics.
LoRa leads in growth; Zigbee maintains a stable base.
Application:
The suitability of WI SUN technology varies significantly across different application domains, impacting deployment scale and operational requirements.
- Smart Home:This segment involves integrating WI SUN into devices for automated energy management, security systems, and connected appliances, driven by consumer convenience and efficiency demands. Consumer demand for automated energy and security systems drives this segment's rapid expansion.
- Environmental Monitoring:WI SUN networks connect sensors for tracking air quality, water levels, and soil conditions, providing crucial data for environmental protection and resource management. Smart city projects in Southeast Asia deploy environmental monitoring solutions for urban air quality tracking.
- Agriculture:WI SUN enables long-range sensor networks for precision farming, monitoring soil moisture, crop health, and livestock, optimizing resource use and yield.
- Asset Tracking:This application uses WI SUN for tracking the location and status of valuable assets across industrial sites or logistics networks.
Smart Home exhibits the steepest expansion trajectory; Environmental Monitoring maintains consistent adoption.
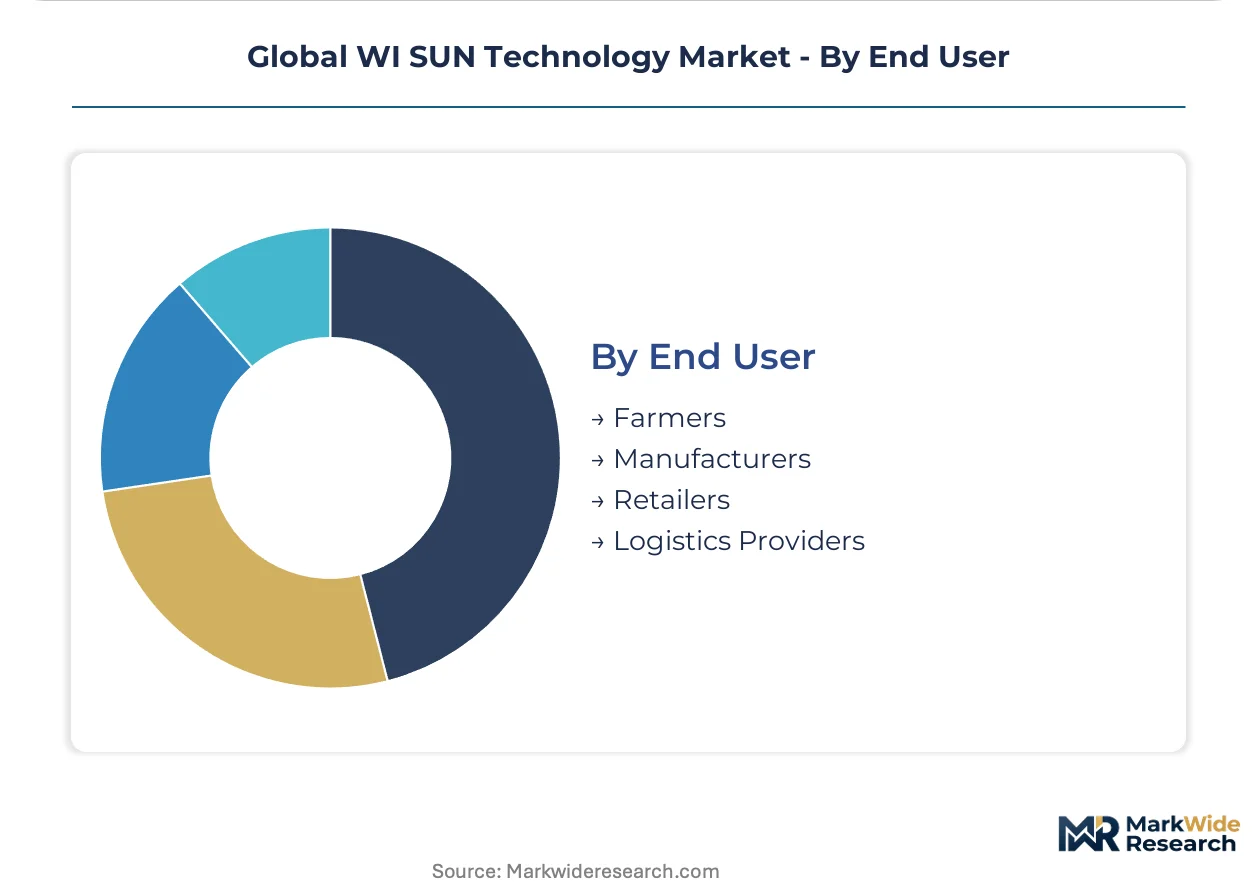
End User:
The customer types for WI SUN technology exhibit distinct procurement patterns and solution requirements, influencing vendor engagement strategies.
- Manufacturers:Industrial manufacturers deploy WI SUN for factory automation, predictive maintenance, and supply chain visibility, integrating it into their operational technology infrastructure. Automotive manufacturers in Germany utilize WI SUN for asset tracking within large production facilities.
- Logistics Providers:These companies leverage WI SUN for real-time tracking of goods, fleet management, and warehouse optimization, enhancing operational efficiency and reducing loss. Major logistics firms in the United States adopt WI SUN for container tracking across vast distribution centers.
- Farmers:Agricultural enterprises use WI SUN for smart farming applications, including irrigation control and remote monitoring of field conditions.
- Retailers:Retail businesses apply WI SUN for inventory management, smart shelving, and customer analytics within large store environments.
Manufacturers are gaining share fastest; Logistics Providers maintain a significant user base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The proliferation of smart grid infrastructure underwrites the geographic distribution of WI SUN technology adoption. Utilities and municipalities across developed and emerging economies are modernizing their energy and urban management systems. This global trend drives demand for robust, low-power wireless communication protocols.
United States
Massive Advanced Metering Infrastructure deployments by major utilities across the United States create foundational demand for WI SUN networks. The FCC allocates sub-GHz frequency bands, influencing device design and ensuring reliable long-range communication. Cities like San Diego and Austin are implementing smart street lighting and traffic management systems, integrating WI SUN for operational efficiency.
Japan
Japan's aggressive push for smart grid integration and energy management systems drives significant WI SUN adoption, particularly in utility metering. The Ministry of Economy, Trade and Industry (METI) promotes advanced energy infrastructure, fostering technology deployment. Tokyo and Osaka are at the forefront of smart city initiatives, utilizing WI SUN for environmental monitoring and public safety applications.
Germany
Germany's commitment to the EU Green Deal mandates extensive grid modernization and energy efficiency targets, accelerating WI SUN integration. Compliance with CE marking directives ensures device interoperability and regulatory adherence across the European Union. Smart metering rollouts in regions like Bavaria and North Rhine-Westphalia exemplify WI SUN's role in digitalizing energy distribution.
China
China's substantial investments in IoT devices and smart city initiatives generate considerable demand for WI SUN components and solutions. The Ministry of Industry and Information Technology (MIIT) governs wireless standards, impacting market access for local and international suppliers. Major urban centers such as Shenzhen and Shanghai are deploying WI SUN for intelligent transportation and environmental sensing.
Vietnam
Emerging smart city projects in Vietnam present new growth avenues for WI SUN deployments, especially for public lighting and waste management systems. Local government initiatives support infrastructure modernization, creating opportunities for low-power wide-area networking. Cities like Hanoi and Ho Chi Minh City are piloting smart urban solutions that leverage WI SUN for enhanced municipal services.
Global WI SUN Technology Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the WI SUN technology market. The competitive structure is tiered, reflecting varied capabilities from silicon design to full-stack solution delivery. Strategic archetypes include dedicated semiconductor manufacturers, network infrastructure providers, and specialized system integrators. Companies frequently engage in strategic partnerships to expand their ecosystem reach and pursue targeted mergers and acquisitions for portfolio diversification.
Within the component specialist archetype, Texas Instruments leverages its extensive portfolio of microcontrollers and transceivers to serve diverse end markets. NXP Semiconductors occupies a position through its secure connectivity solutions for smart city and industrial automation deployments. Semtech Corporation exemplifies a focus on long-range, low-power technologies like LoRa, which complements WI SUN in certain applications.
| Leading Market Players |
|---|
| Semtech Corporation |
| NXP Semiconductors |
| Texas Instruments |
| Microchip Technology |
| Analog Devices |
| Renesas Electronics Corporation |
| Cisco Systems |
| Itron |
| Landis+Gyr |
| Others |
Cost & Logistics Intelligence
Regulatory fragmentation across global markets influences both pricing tier spreads and the distributed supply chain for WI SUN components. This divergence in standards necessitates localized product variations, impacting manufacturing scale and cost efficiencies.
Pricing Analysis
Volume-based discount structures characterize pricing for WI SUN components and integrated solutions. Per-unit transactional models prevail for smaller orders, while large utility deployments secure contract-based long-term agreements. Price differentiation stems from performance specifications, including range and power consumption, and compliance with regional regulatory standards such as FCC or CE marking. Pricing pressure stems from intense competition with alternative LPWAN technologies like LoRaWAN, pushing component costs down. Smart home device manufacturers exhibit high price sensitivity, whereas large utility providers prioritize reliability and long-term operational costs over initial unit price.
Supply Chain Analysis
Single-source vulnerability for specialized chipsets dominates the WI SUN supply chain, creating potential chokepoints. Component manufacturing concentrates in China and Taiwan, while design houses often reside in the United States. Key component dependencies include sub-GHz transceivers and microcontrollers. Geopolitical tensions impacting semiconductor trade represent a significant structural risk. Distribution runs through direct channels to large system integrators, with regional distributors supporting smaller device manufacturers and specialized solution providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The WI SUN market is undergoing a platform-economics inflection, driven by the shift towards multi-functional, hybrid communication architectures. This transition emphasizes seamless interoperability between WI SUN and other wireless standards like Bluetooth Low Energy within smart city ecosystems.
For Market Incumbents: Entrench market leadership by investing in multi-protocol chipset development, integrating WI SUN with complementary technologies like BLE. This mitigates the threat from alternative LPWANs by offering versatile solutions for diverse applications. Consolidate channel partnerships with major utility providers and smart city integrators to secure long-term volume contracts. Focus R&D on enhancing security features and edge computing capabilities within gateways to maintain a competitive advantage. For New Entrants and Emerging Players: Establish a beachhead in underpenetrated vertical markets such as smart agriculture or environmental monitoring in emerging economies. Target Southeast Asia, where smart city initiatives are nascent and demand for low-cost, long-range sensing is high. Develop niche application-specific WI SUN modules with integrated analytics capabilities. A go-to-market angle focusing on complete, outcome-based solutions for specific municipal challenges can bypass established hardware distribution channels. For Investors and Strategic Acquirers: The EU Green Deal mandates reshape the acquisition landscape, favoring companies with proven smart grid integration expertise. Long-term viability extends over the next decade for firms offering integrated WI SUN solutions that facilitate energy efficiency and grid modernization. Target archetype: vertically integrated system integrators specializing in utility AMI deployments or smart city infrastructure. The signal to watch is the acceleration of large-scale smart meter rollouts in Europe and North America.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-protocol Chipset Development | Enables versatile devices, reducing complexity for smart city and industrial IoT manufacturers. |
| Edge Computing Integration | Facilitates real-time data processing for predictive maintenance and grid fault detection in industrial settings. |
| Strategic Partnerships with Utilities | Secures foundational demand from large-scale Advanced Metering Infrastructure deployments in the United States. |
| Geographic Expansion into Southeast Asia | Captures new growth opportunities in emerging smart city projects for public lighting and waste management. |
| Cybersecurity Enhancements | Builds trust and ensures data integrity for critical infrastructure applications like smart grid management. |
Research Approach
The analysis maps WI SUN product types, application segments, and end-user groups, each validated through extensive interviews with industry experts. Primary research involved discussions with semiconductor manufacturers, utility planning officers, smart city project managers, and system integrators. Secondary validation drew from IEEE standards documentation, FCC and MIIT regulatory filings, and smart grid deployment reports. This approach ensured robust bottom-up and top-down data triangulation.
Forecast assumptions held constant geopolitical stability and existing regulatory frameworks, while varying technology adoption rates and infrastructure investment levels across the analysis window. Segmentation dimensions modeled included product type, underlying technology, application area, and end-user vertical. Compound Annual Growth Rates were derived from historical data trends and projected future demand. Key forecast inputs included smart meter deployment schedules and smart city project pipelines.
Sensitivities concentrate around shifts in global semiconductor supply chains or changes in regional regulatory mandates. Forecasts reflect assumptions documented at the time of publication, acknowledging potential impacts from unforeseen economic downturns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Global Ultrafast Lasers Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market