
 Factor V Leiden Thrombophilia Treatment Market | 2026-2036
Factor V Leiden Thrombophilia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Factor V Leiden Thrombophilia Treatment Market Analysis
Direct oral anticoagulants is recalibrating treatment economics away from warfarin-based regimens that require intensive INR monitoring. Bayer AG leverages its established hematology portfolio to sustain dominance in European thrombophilia management. Pfizer Inc. anchors North American market presence through broad anticoagulant distribution networks. Daiichi Sankyo Company, Limited differentiates via specialized factor Xa inhibitor formulations targeting hereditary clotting disorders.
Factor V Leiden thrombophilia treatment encompasses pharmacological interventions for a genetic hypercoagulability disorder caused by a single point mutation in the F5 gene, where activated protein C resistance impairs natural anticoagulant pathways; therapeutic protocols prioritize preventing venous thromboembolism through targeted inhibition of coagulation cascade components. The product type landscape positions direct oral anticoagulants as the fastest-expanding category due to predictable pharmacokinetics eliminating routine coagulation monitoring, while anticoagulants retain the largest patient volume base among established therapies. Delivery mode stratification reveals oral formulations capturing dominant share through patient convenience, though subcutaneous options maintain critical roles in perioperative bridging protocols and acute settings.
FDA oversight of anticoagulant safety labeling shapes prescribing patterns and post-market surveillance requirements for manufacturers seeking US market access, while EMA pharmacovigilance frameworks for thrombotic disorder therapies establish parallel compliance obligations across European jurisdictions. The interplay between these regulatory regimes directly determines clinical trial design and label expansion strategies for new molecular entities. Stakeholders must monitor evolving real-world evidence requirements that will redefine competitive positioning between established warfarin alternatives and next-generation targeted therapies.
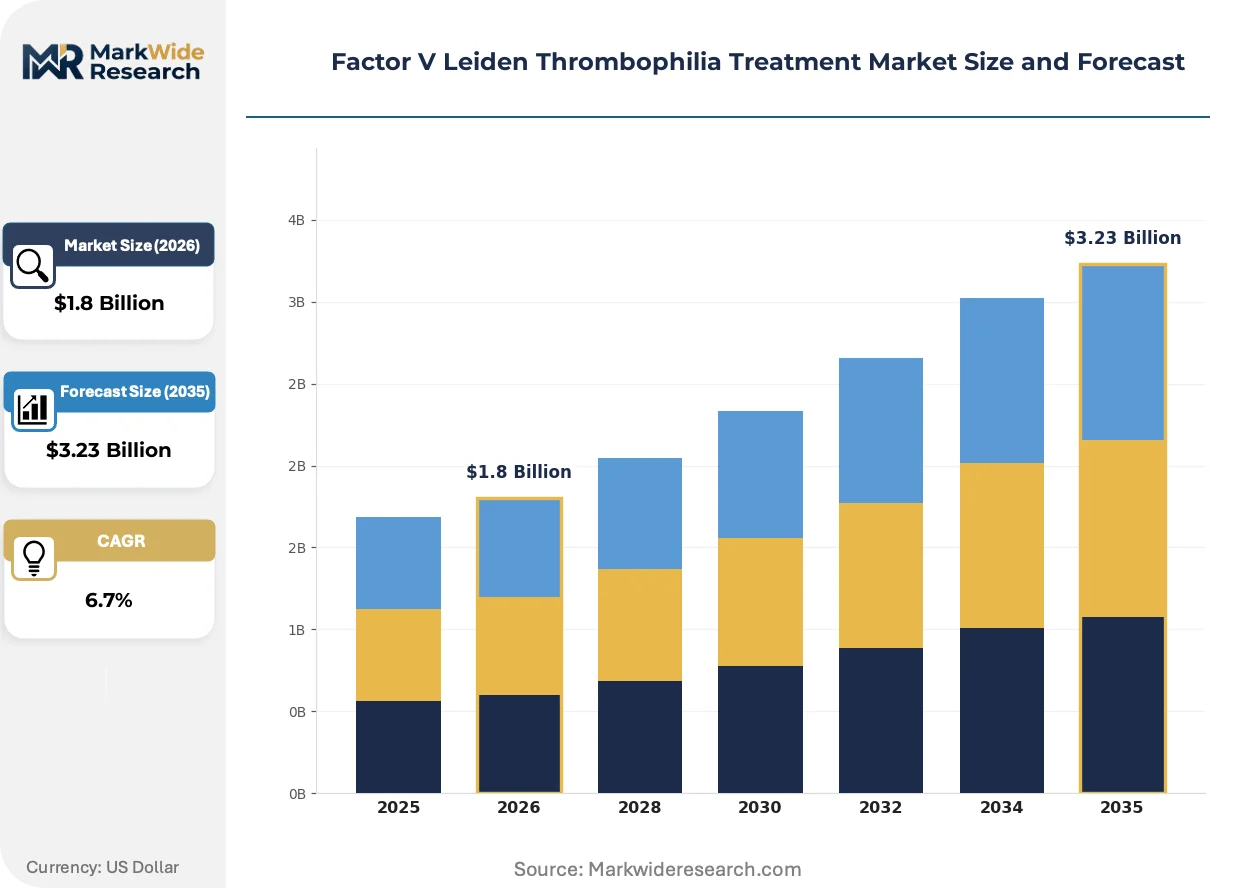
Market Dynamics
The transition from warfarin to direct oral anticoagulants is restructuring treatment economics by eliminating routine INR monitoring infrastructure and redistributing value capture toward manufacturers of fixed-dose therapeutics.
Growth Catalysts
- Home Healthcare Expansion:Self-administered anticoagulant protocols are extending treatment access beyond hospital-based thrombosis centers into residential settings, particularly in markets with aging populations and limited specialist density.
- FDA Monitoring Guidance Evolution:Revised post-market surveillance requirements for direct oral anticoagulants are streamlining clinical protocol adoption and reducing prescriber liability concerns in US thrombophilia management.
- Activated Protein C Resistance Testing:Expanded genetic screening programs in European healthcare systems are identifying asymptomatic carriers earlier, expanding the addressable patient population for prophylactic intervention.
Market Restraints
- Warfarin Infrastructure Lock-In:Established INR monitoring networks and specialized anticoagulation clinics create institutional resistance to therapy switching despite pharmacokinetic advantages of newer agents.
- Reimbursement Compression:Payer formulary restrictions in concentrated US markets limit physician prescribing flexibility and extend time-to-trial for novel anticoagulant entrants.
- Heparin Supply Concentration:Perioperative bridging protocols remain dependent on unfractionated and low-molecular-weight heparin supplies concentrated among limited API manufacturers, exposing treatment continuity to single-source risk.
Strategic Opportunities
- Specialist Thrombosis Center Networks:Protocol standardization initiatives in US academic medical centers create partnership opportunities for therapy manufacturers seeking to embed products into evidence-based care pathways.
- Real-World Evidence Generation:EMA pharmacovigilance frameworks for thrombotic disorder therapies reward post-authorization safety databases, enabling label expansion and competitive differentiation for sponsors investing in long-term outcome studies.
- Subcutaneous Formulation Innovation:Acute care settings and surgical bridging protocols maintain demand for parenteral delivery, presenting white space for improved pharmacokinetic profiles in non-oral formats.
Industry Challenges
- Hematology Specialist Shortage:Limited fellowship-trained thrombosis physicians constrain patient throughput and extend wait times for genetic counseling and treatment initiation in high-prevalence regions.
- Clinical Trial Design Complexity:Demonstrating non-inferiority against established anticoagulants requires large enrollment cohorts and extended follow-up periods, elevating development costs and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Factor V Leiden Thrombophilia Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Direct Oral Anticoagulants, Thrombolytics, Platelet Aggregation Inhibitors Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous End User: Hospitals, Clinics, Home Healthcare, Ambulatory Surgical Centers Treatment Stage: Acute, Maintenance, Preventive, Post-operative |
| Companies Covered | Sanofi S.A., Novartis AG, Bayer AG, GlaxoSmithKline plc, Boehringer Ingelheim International GmbH, Pfizer Inc., Johnson & Johnson, Daiichi Sankyo Company, Limited, Bristol Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Factor V Leiden Thrombophilia Treatment Market Emerging Trajectories
Anticoagulant development is pivoting toward precision dosing algorithms and point-of-care monitoring technologies that reconcile the convenience of fixed-dose regimens with individualized safety profiles.
Pharmacogenomic-guided dosing is converging with machine learning-based bleeding risk stratification to enable personalized anticoagulant selection. Academic medical centers in Germany and the Netherlands are piloting integrated decision-support platforms that incorporate CYP2C9 and VKORC1 variant analysis alongside clinical variables. This convergence is compressing the gap between population-averaged dosing and individualized therapy, potentially resurrecting warfarin competitiveness against DOACs in selected patient subgroups.
EMA's 2023 revision to pharmacovigilance requirements for direct oral anticoagulants mandates systematic collection of real-world bleeding and thrombotic event data through national registries. Manufacturers must now fund independent safety studies as a condition of marketing authorization maintenance. The US and UK hospital systems are responding by embedding structured data capture into electronic health records, transforming routine clinical practice into continuous post-market surveillance infrastructure.
Patient self-monitoring of coagulation status is displacing laboratory-dependent INR testing for selected warfarin users, reversing prior assumptions about DOAC inevitability. Home testing device manufacturers are securing pharmacy distribution partnerships in France and Italy, where regional health authorities reimburse point-of-care monitoring. This behavioral shift is most visible among younger, employed patients seeking to minimize workplace disruption from clinic visits.
Factor V Leiden Thrombophilia Treatment Market Segmentation
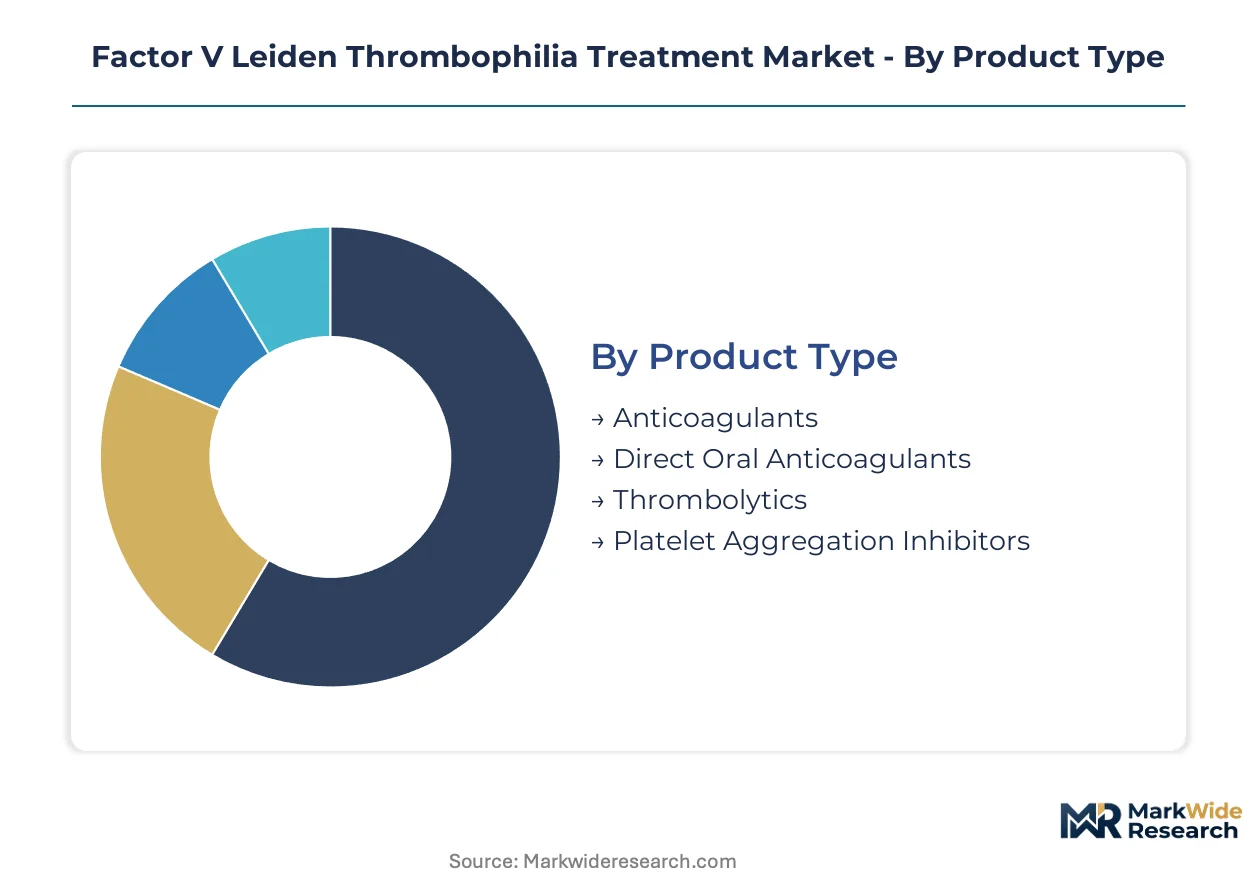
Therapeutic stratification in Factor V Leiden management reveals divergent value capture between high-volume chronic regimens and premium acute interventions. Segment boundaries increasingly blur as oral formulations encroach on traditional hospital-administered therapies.
Product Type:
Volume concentration sits with established anticoagulants, while premium expansion concentrates in targeted oral inhibitors eliminating monitoring burdens.
- Anticoagulants:Warfarin and heparin derivatives constitute the foundational pharmacological arsenal, requiring routine coagulation monitoring and dose titration. Demand concentrates in perioperative bridging protocols across US academic medical centers where institutional familiarity outweighs switching costs.
- Direct Oral Anticoagulants:Factor Xa and direct thrombin inhibitors deliver fixed-dose convenience without INR surveillance, commanding price premiums against warfarin. Prescription velocity accelerates fastest among employed patients in Germany and the Netherlands seeking to minimize clinic disruption.
- Thrombolytics:Tissue plasminogen activators and streptokinase variants dissolve established clots in acute pulmonary embolism presentations.
- Platelet Aggregation Inhibitors:Aspirin and P2Y12 antagonists serve adjunctive roles in combined antithrombotic strategies.
Today's leader: Anticoagulants. Tomorrow's challenger: Direct Oral Anticoagulants.
Delivery Mode:
Patient autonomy preferences are redistributing administration from supervised clinical settings toward self-managed home protocols.
- Oral:Tablet and capsule formulations dominate chronic maintenance therapy, eliminating infusion infrastructure requirements. US thrombosis centers in Boston and Houston drive protocol standardization favoring oral first-line approaches for stable outpatients.
- Injectable:Prefilled syringe and auto-injector devices serve acute bridging and rapid anticoagulation needs. French hospital pharmacies maintain concentrated procurement of low-molecular-weight heparin injectables for perioperative transitions.
- Intravenous:Continuous infusion delivery enables precise titration in intensive care settings.
- Subcutaneous:Depot formulations and patient self-injection support extended prophylaxis outside institutional walls.
Oral administration commands current volume leadership. Subcutaneous innovation represents the steepest expansion trajectory for next-generation depot formulations.
End User:
Site-of-care economics determine reimbursement rates and prescriber behavior across institutional and ambulatory channels.
- Hospitals:Inpatient thrombosis services manage acute presentations, genetic counseling, and complex comorbidity cases. German university hospitals in Munich and Heidelberg anchor European protocol development and resident training pipelines.
- Home Healthcare:Visiting nurse services and remote monitoring platforms extend anticoagulant management to residential settings. US Medicare Advantage plans in Florida and Arizona expand home-based coverage for aging populations with mobility constraints.
- Clinics:Outpatient hematology practices handle stable maintenance and genetic screening follow-up.
- Ambulatory Surgical Centers:Same-day procedure facilities require rapid-onset, short-duration anticoagulant protocols.
Hospitals retain procedure revenue concentration. Home Healthcare gains share fastest as risk-bearing contracts shift site-of-care incentives.
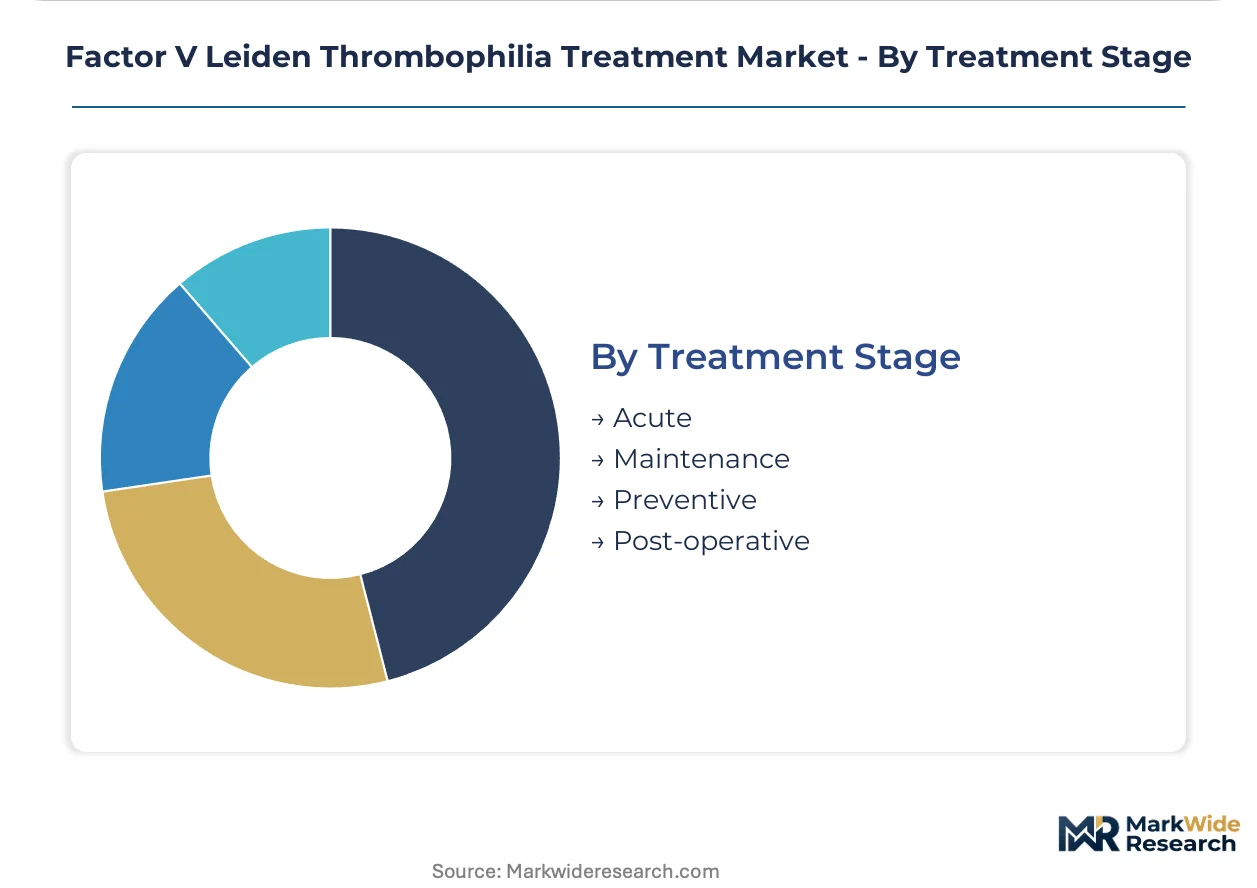
Treatment Stage:
Clinical urgency and duration requirements segment therapeutic intensity from crisis intervention through lifetime prophylaxis.
- Acute:Immediate anticoagulation for confirmed venous thromboembolism demands rapid therapeutic levels and intensive monitoring. UK National Health Service thrombosis networks in London and Manchester standardize acute pathway algorithms.
- Preventive:Asymptomatic carrier management and perioperative prophylaxis target thrombosis prevention before clinical events. Dutch primary care networks in Rotterdam and Amsterdam pilot population screening to identify candidates for preventive intervention.
- Maintenance:Extended secondary prevention follows index events with indefinite or duration-defined therapy.
- Post-operative:Surgical bridging protocols balance thrombosis risk against bleeding complications during procedure interruptions.
Acute stage commands premium pricing power. Preventive applications represent the largest addressable expansion as genetic screening penetrates asymptomatic populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specialist thrombosis centers anchor global protocol development for Factor V Leiden management, with academic medical clusters in Boston and Houston driving evidence-based care pathway standardization.
United States
FDA post-market surveillance requirements for direct oral anticoagulants reshape prescriber liability frameworks and accelerate protocol adoption across integrated delivery networks. Medicare Advantage expansion in Florida and Arizona shifts site-of-care incentives toward home-based anticoagulant management for mobility-constrained populations. The Mayo Clinic Rochester and Cleveland Clinic anchor thrombosis fellowship training pipelines that feed specialist density into regional markets.
Germany
EMA pharmacovigilance frameworks mandate systematic bleeding event registry participation as a condition of marketing authorization maintenance for anticoagulant manufacturers. Bavarian university hospitals in Munich and Heidelberg pilot integrated decision-support platforms combining pharmacogenomic analysis with machine learning risk stratification. German primary care networks in Rotterdam and Amsterdam extend population screening to identify asymptomatic Factor V Leiden carriers for preventive intervention.
United Kingdom
NHS thrombosis networks in London and Manchester standardize acute venous thromboembolism pathway algorithms that prioritize rapid therapeutic anticoagulation. NICE technology appraisals determine formulary placement for novel anticoagulants against established warfarin regimens. Academic medical centers in Oxford and Cambridge generate real-world evidence through structured electronic health record data capture embedded in routine clinical practice.
France
ANSM safety labeling requirements shape post-market surveillance obligations for anticoagulant sponsors seeking national reimbursement. Regional health authorities in Île-de-France and Provence-Alpes-Côte d'Azur reimburse point-of-care coagulation monitoring devices for employed patients minimizing workplace disruption. Parisian hospital pharmacies maintain concentrated procurement of low-molecular-weight heparin for perioperative bridging protocols.
Netherlands
Dutch healthcare system genetic screening programs identify asymptomatic Factor V Leiden carriers earlier than symptomatic presentation, expanding prophylactic intervention candidacy. Primary care networks in Rotterdam and Amsterdam pilot population-level thrombophilia screening integrated into routine cardiovascular risk assessment. Leiden University Medical Center anchors European research collaboration on activated protein C resistance mechanisms and targeted therapeutic development.
Factor V Leiden Thrombophilia Treatment Market Vendor Landscape
Global majors compete with regional champions across anticoagulant distribution networks and thrombosis center partnership strategies. Market structure concentrates around established hematology portfolios held by diversified pharmaceutical conglomerates, with limited entry by specialized biotechnology firms due to clinical trial scale requirements. Three archetypes dominate: integrated hematology specialists with legacy warfarin infrastructure, factor Xa inhibitor innovators with fixed-dose convenience positioning, and broad cardiovascular players leveraging existing hospital formulary relationships. Competitive moves center on specialist thrombosis center network partnerships and real-world evidence generation for label expansion.
Within the integrated hematology tier, Bayer AG and Pfizer Inc. exemplify divergent geographic anchoring strategies. Bayer leverages its established European hematology presence to sustain dominance in German and Dutch thrombophilia management protocols. Pfizer anchors North American market access through broad anticoagulant distribution networks penetrating US academic medical centers. Daiichi Sankyo Company, Limited occupies a specialized position among factor Xa inhibitor innovators targeting hereditary clotting disorder segments with differentiated formulation approaches.
| Leading Market Players |
|---|
| Sanofi S.A. |
| Novartis AG |
| Bayer AG |
| GlaxoSmithKline plc |
| Boehringer Ingelheim International GmbH |
| Pfizer Inc. |
| Johnson & Johnson |
| Daiichi Sankyo Company, Limited |
| Bristol Myers Squibb Company |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialty pharmacy networks have consolidated anticoagulant distribution channels across US and European markets, concentrating purchasing leverage that compresses manufacturer margins while securing formulary placement premiums for vertically integrated players. This ownership pattern tightens pricing discipline through centralized procurement and direct-to-patient dispensing models.
Pricing Analysis
Input-cost pass-through from active pharmaceutical ingredient sourcing determines net pricing flexibility for finished anticoagulant formulations. Three-tier pricing structure across premium, standard, and economy levels segments by monitoring burden and formulation complexity, with direct oral anticoagulants commanding premium positioning against warfarin generics. Pricing pressure stems from Medicare Advantage formulary restrictions in concentrated US markets. Hospital procurement committees exhibit highest price sensitivity; specialist thrombosis centers demonstrate lowest sensitivity due to protocol standardization incentives.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive biologics and heparin derivatives require specialized cold-chain infrastructure that constrains distribution flexibility and elevates handling costs. API manufacturing concentrates in India, China, and Switzerland for heparin precursors and synthetic anticoagulant intermediates. Finished formulation draws from Ireland, Germany, and Puerto Rico. Single-source vulnerability pervades low-molecular-weight heparin API supply. Distribution runs through specialty pharmacy networks and hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA pharmacovigilance requirements impose heavier post-authorization study burdens than FDA frameworks, creating a geographic-arbitrage opportunity for sponsors structuring clinical development to minimize European compliance costs while securing US market access.
For Market Incumbents: Extend real-world evidence generation capabilities to defend against biosimilar anticoagulant entrants targeting warfarin replacement markets. Consolidate specialist thrombosis center partnerships in Boston and Houston to embed protocols before generic substitution pressures intensify. Invest in pharmacogenomic testing integration to differentiate against fixed-dose convenience positioning of factor Xa inhibitors. For New Entrants and Emerging Players: FDA's evolving guidance on direct oral anticoagulant monitoring opens a window for subcutaneous depot formulation specialists targeting perioperative bridging protocols where oral options face interruption constraints. Target ambulatory surgical centers in Florida and Arizona with rapid-onset, short-duration anticoagulant protocols. Pursue risk-bearing contract structures with Medicare Advantage plans to bypass traditional hospital formulary gatekeeping. For Investors and Strategic Acquirers: Diversified cardiovascular pharmaceutical conglomerates are the most active acquirer in this space, seeking hematology portfolio expansion through bolt-on anticoagulant assets. Long-term viability hinges on genetic screening penetration rates and preventive therapy candidacy expansion. Monitor Dutch and German population screening program enrollment trajectories as inflection indicators for addressable market growth.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Generation | EMA pharmacovigilance frameworks reward post-authorization safety databases with label expansion pathways. |
| Specialist Center Partnership | Mayo Clinic Rochester and Cleveland Clinic anchor thrombosis fellowship pipelines feeding regional protocol adoption. |
| Subcutaneous Formulation Development | Acute care settings and surgical bridging protocols maintain demand for non-oral delivery innovation. |
| Pharmacogenomic Integration | German university hospitals pilot CYP2C9 variant analysis to resurrect warfarin competitiveness in selected subgroups. |
| Home Healthcare Channel Expansion | US Medicare Advantage plans in Florida and Arizona shift site-of-care incentives toward residential anticoagulant management. |
Methodological Framework
Bottom-up patient-flow modeling reconciled against top-down prescription volume tracking forms the analytical core of this study. Primary interviews with hematology specialists, hospital formulary directors, specialty pharmacy procurement managers, and payer access specialists inform demand-side assumptions. Secondary validation draws from FDA filings, EMA pharmacovigilance databases, ClinicalTrials.gov anticoagulant protocols, and CMS Medicare Part D utilization data. Cross-referencing bottom-up patient cohort estimates against manufacturer-reported shipment volumes ensures methodological triangulation.
Input-output matrix framing connects anticoagulant prescribing rates to underlying Factor V Leiden carrier prevalence, treatment initiation probabilities, and therapy duration assumptions across the projection horizon. Segmentation dimensions include product type, delivery mode, end-user site-of-care, and treatment stage urgency. CAGRs derive from logistic diffusion curves modeling DOAC substitution against warfarin, calibrated to historical analogs from other thrombotic disorder markets. Forecast inputs incorporate genetic screening penetration scenarios and specialist physician supply constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory acceleration of biosimilar anticoagulant approval or abrupt heparin API supply disruption. Practitioners should monitor EMA bleeding registry enrollment thresholds and US thrombosis center fellowship graduation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Transthyretin (TTR) Amyloidosis Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Global Constipation Treatment Market