
 China Feed Amino Acids Market | 2026-2036
China Feed Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
China Feed Amino Acids Market Analysis
Pharmaceutical-grade lysine specifications is collapsing the gap between industrial and food-grade amino acid production lines. Adisseo leverages its integrated methionine platform to sustain cost leadership across coastal manufacturing zones. Wudi Deda Agriculture Co. Limited anchors regional supply chains through backward integration into corn fermentation. Evonik Industries AG differentiates via specialty hydroxy-analogue formulations that command premium positioning in aquaculture channels.
Feed amino acids are nitrogen-containing organic compounds produced through fermentation or chemical synthesis, typically specified at minimum 98.5% purity for lysine hydrochloride and 99% for DL-methionine, functioning as essential protein building blocks that livestock cannot synthesize endogenously. Lysine dominates volume flows across the product landscape due to its deficiency in cereal-based diets, while methionine captures concentrated margin pools in poultry applications where sulfur amino acid requirements peak. Aquaculture represents the fastest-growing application vector as shrimp and marine fish diets intensify amino acid fortification beyond traditional livestock norms.
China's Ministry of Agriculture and Rural Affairs sets mandatory feed additive catalogues that restrict unapproved amino acid variants from commercial circulation, while GB standards enforce contaminant limits on heavy metals and microbial loads. The National Medical Products Administration coordinates with feed safety frameworks where amino acid production overlaps pharmaceutical intermediates. Stakeholders must monitor how China's dual carbon goals reshape energy pricing for fermentation-based production and whether provincial environmental inspections force capacity relocations from the Yangtze Delta to northern industrial corridors.
Market Dynamics
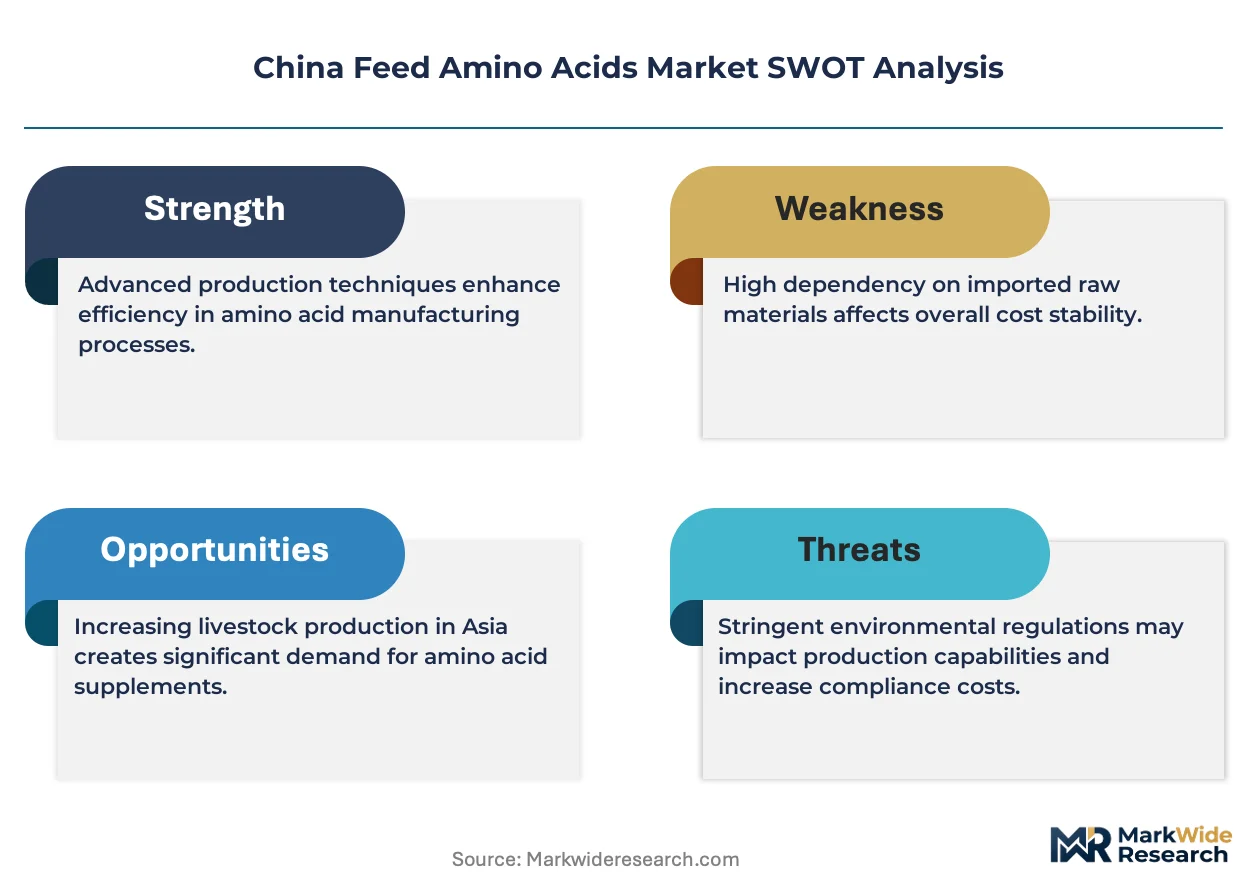
China's feed amino acids sector operates under tightening GB standards for contaminant limits while fermentation capacity concentrates in Shandong Province's corn-soy processing clusters, creating a dual pressure of regulatory compliance and geographic supply concentration.
Growth Catalysts
- Dual carbon energy transition:Provincial renewable energy mandates in Shandong and Hebei are lowering electricity costs for fermentation plants, improving cost structures for lysine and methionine output.
- Aquaculture diet intensification:Shrimp and marine fish farming in Guangdong and Fujian provinces is accelerating amino acid fortification beyond traditional livestock feed specifications.
- MIIT industrial upgrading policies:China's Ministry of Industry and Information Technology feed additive modernization incentives are accelerating pharmaceutical-grade production line conversions.
Market Restraints
- Corn price volatility:Input cost swings for fermentation feedstock strain margin stability across Shandong-based lysine manufacturers dependent on domestic grain procurement.
- MEE environmental inspections:Ministry of Ecology and Environment enforcement actions in the Yangtze Delta are forcing unplanned capacity idling and relocation capital requirements.
- Synthetic amino acid substitution:Chemical synthesis routes for DL-methionine from petroleum derivatives compete with fermentation-based production on cost in certain specifications.
Strategic Opportunities
- Northwest corridor expansion:Xinjiang and Inner Mongolia offer untapped fermentation capacity zones with lower environmental compliance density and proximity to corn belts.
- Hydroxy-analogue aquaculture penetration:Specialty methionine formulations for shrimp and marine fish diets command premium positioning in coastal farming zones.
- SAMR feed additive catalog expansion:China's State Administration for Market Regulation approval of novel amino acid variants creates first-mover positioning for compliant producers.
Industry Challenges
- GB standards compliance timeline:Heavy metal and microbial load certification requirements demand 12-18 month validation cycles that delay new product commercialization.
- Fermentation process engineering talent:Specialized bioprocess optimization expertise for large-scale amino acid production remains concentrated among a limited pool of technical specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Feed Amino Acids Market |
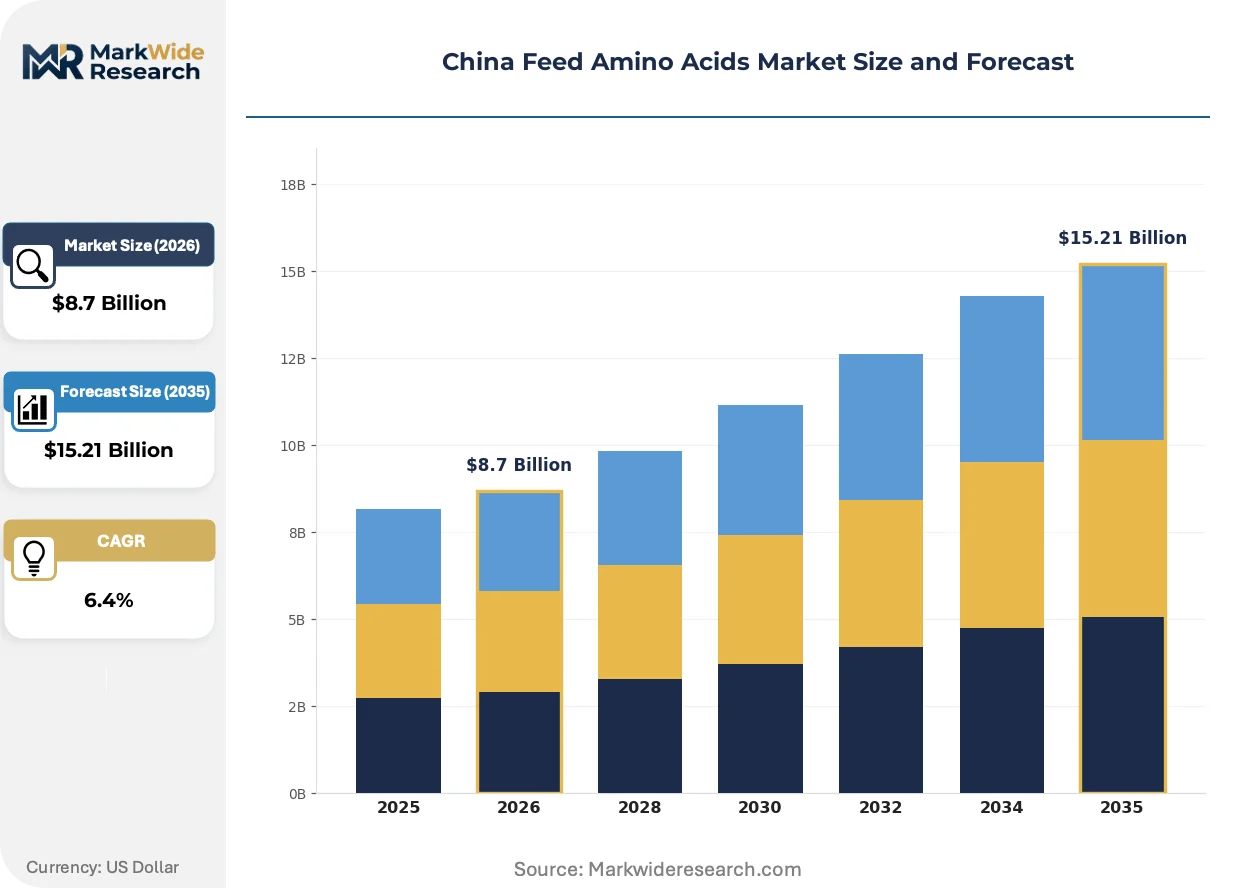
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lysine, Methionine, Threonine, Tryptophan Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granules, Pellets Distributor Type: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | IFF (Danisco Animal Nutrition), Ajinomoto Co., Inc., Adisseo, Impextraco NV, Kemin Industries, Alltech, Inc., SHV (Nutreco NV), Wudi Deda Agriculture Co. Limited, Evonik Industries AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Feed Amino Acids Market Emerging Trajectories
Fermentation technology advances and regulatory purity mandates are compressing the gap between industrial-grade and pharmaceutical-grade amino acid specifications, reshaping production line economics and competitive positioning across China's coastal manufacturing zones.
Continuous fermentation systems with real-time metabolite monitoring is supplanting traditional batch processing in Shandong's largest lysine facilities. Swine feed compounders in Henan Province are demanding higher assay consistency, driving adoption of automated bioreactor controls. This shift is compressing unit production costs while raising capital barriers for smaller batch operators.
GB 7300 feed additive standards revisions are mandating stricter heavy metal and microbial contamination thresholds for all commercial amino acid circulation. The National Medical Products Administration coordination with agricultural safety frameworks is forcing dual-use facilities to segregate pharmaceutical intermediate and feed-grade production lines. Lysine hydrochloride manufacturers in coastal zones face the steepest compliance retrofit requirements.
Direct procurement contracts between amino acid producers and integrated livestock operations in Sichuan and Hunan provinces are displacing traditional distributor-mediated transactions. Large swine enterprises are consolidating supplier relationships to secure volume commitments and assay consistency guarantees. This channel consolidation is most visible in the Yangtze River basin where vertical livestock integration has advanced furthest.
China Feed Amino Acids Market Segmentation
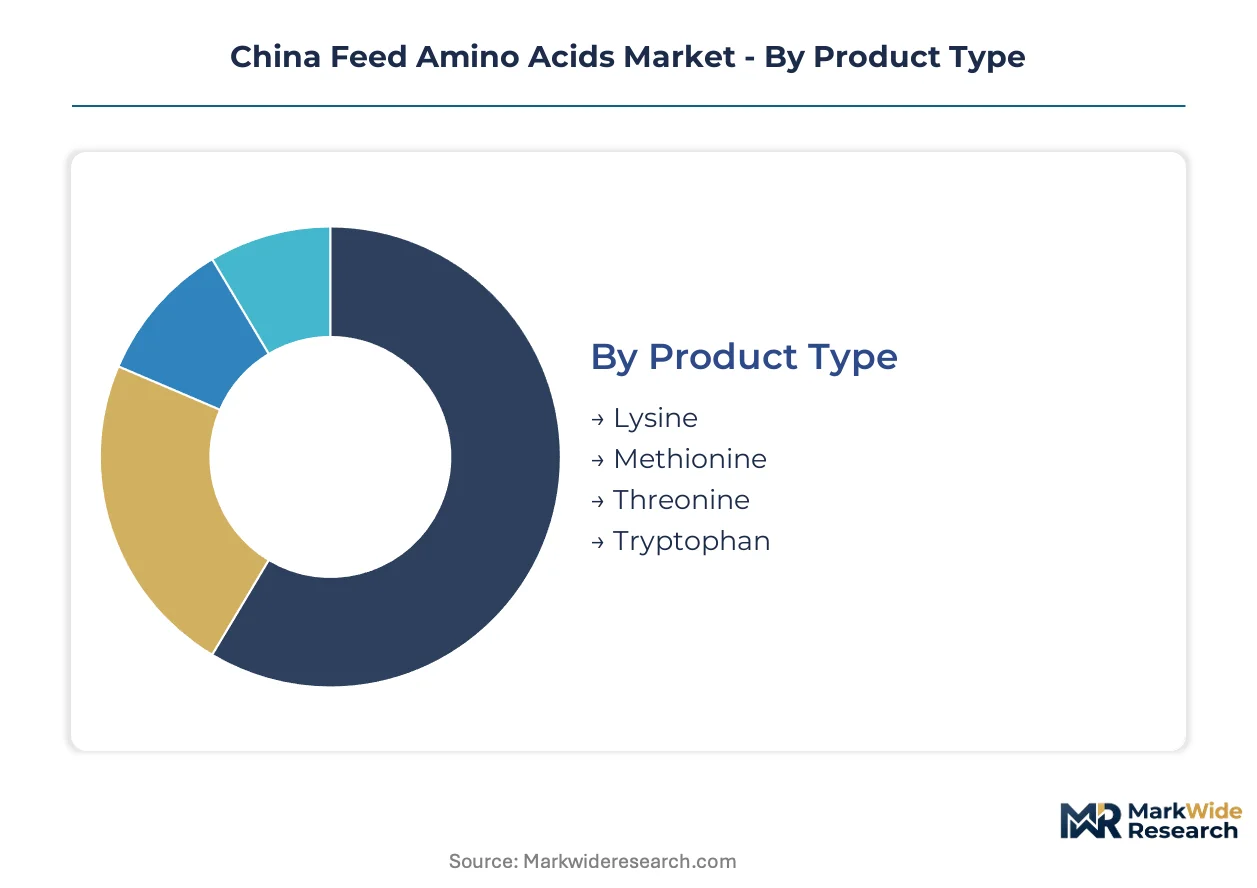
Segmentation in China's feed amino acids market reveals how regulatory frameworks, application-specific purity mandates, and supply chain configurations create distinct commercial zones. Each dimension carries unique cost structures and compliance burdens that reshape procurement patterns across Shandong's manufacturing clusters and downstream feed compounders.
Product Type:
GB standards enforce divergent contaminant thresholds across amino acid variants, with lysine hydrochloride and DL-methionine facing the strictest heavy metal and microbial load certification requirements under feed additive catalogues.
- Lysine:Lysine hydrochloride specifications mandate minimum 98.5% purity with tight limits on arsenic and lead residues. Demand concentrates in Henan Province's swine operations where feed conversion efficiency drives volume procurement from Shandong fermentation facilities.
- Methionine:DL-methionine requires 99% purity with sulfur amino acid functionality critical for poultry feather development and egg production. Coastal Guangdong poultry integrators source methionine through direct contracts prioritizing assay consistency over spot market flexibility.
- Threonine:This essential amino acid fortifies swine and poultry diets where cereal-based feed formulations create deficiency gaps. Threonine procurement flows through wholesale distributors serving mid-sized feed mills in Sichuan's livestock corridors.
- Tryptophan:The lowest-volume product type serves specialized aquaculture and high-performance swine breeder formulations. Tryptophan commands premium positioning in shrimp feed applications across Fujian's marine farming zones.
Established volume favors lysine; emerging adoption favors methionine specialty formulations.
Application:
End-use specifications diverge sharply across livestock categories, with aquaculture diets demanding amino acid fortification levels that exceed traditional poultry and swine norms by substantial margins.
- Poultry:Broiler and layer operations in Shandong and Hebei provinces drive methionine consumption for optimal feed conversion ratios. GB 7300 standards for poultry feed additives mandate stricter documentation of amino acid sourcing than ruminant applications.
- Swine:Finishing hog operations in Henan and Hunan provinces represent the dominant lysine demand vector. Large integrated producers are consolidating supplier relationships to secure volume commitments and bypass traditional distributor markups.
- Ruminants:Dairy and beef cattle applications utilize amino acid supplementation at lower inclusion rates than monogastric species. Ruminant feed compounders in Inner Mongolia source protected methionine formulations for bypass protein optimization.
- Aquaculture:Shrimp and marine fish farming in Guangdong and Fujian provinces is climbing the fastest as diet intensification accelerates beyond traditional livestock feed specifications. Aquaculture channels command premium positioning for hydroxy-analogue methionine variants.
Poultry and swine anchor current procurement volumes; aquaculture applications are gaining share fastest.
Form:
Physical form selection hinges on feed mill processing infrastructure, with powder and liquid variants dominating large-scale compounder operations while granules and pellets serve specialized blending requirements.
- Powder:Standard lysine and methionine powder formulations serve high-volume feed mills with automated mixing systems. Powder dominates procurement flows to Shandong's integrated poultry and swine operations.
- Liquid:Liquid methionine hydroxy-analogue formulations reduce dust exposure and improve handling efficiency in coastal aquaculture feed plants. Liquid adoption is expanding most quickly in Guangdong's shrimp feed manufacturing clusters.
- Granules:Granular lysine offers improved flow characteristics for smaller feed mills with limited pneumatic conveying infrastructure. Granule procurement concentrates in Sichuan and Hunan provincial feed cooperatives.
- Pellets:Pelletized amino acid premixes serve ruminant operations requiring precise inclusion in total mixed rations. Pellet demand remains concentrated among Inner Mongolia dairy feed suppliers.
Powder and liquid forms dominate commercial flows; granules and pellets serve niche infrastructure requirements.
Distributor Type:
Channel structure is reshaping as large livestock integrators bypass traditional wholesale networks in favor of direct manufacturer relationships that secure volume commitments and quality guarantees.
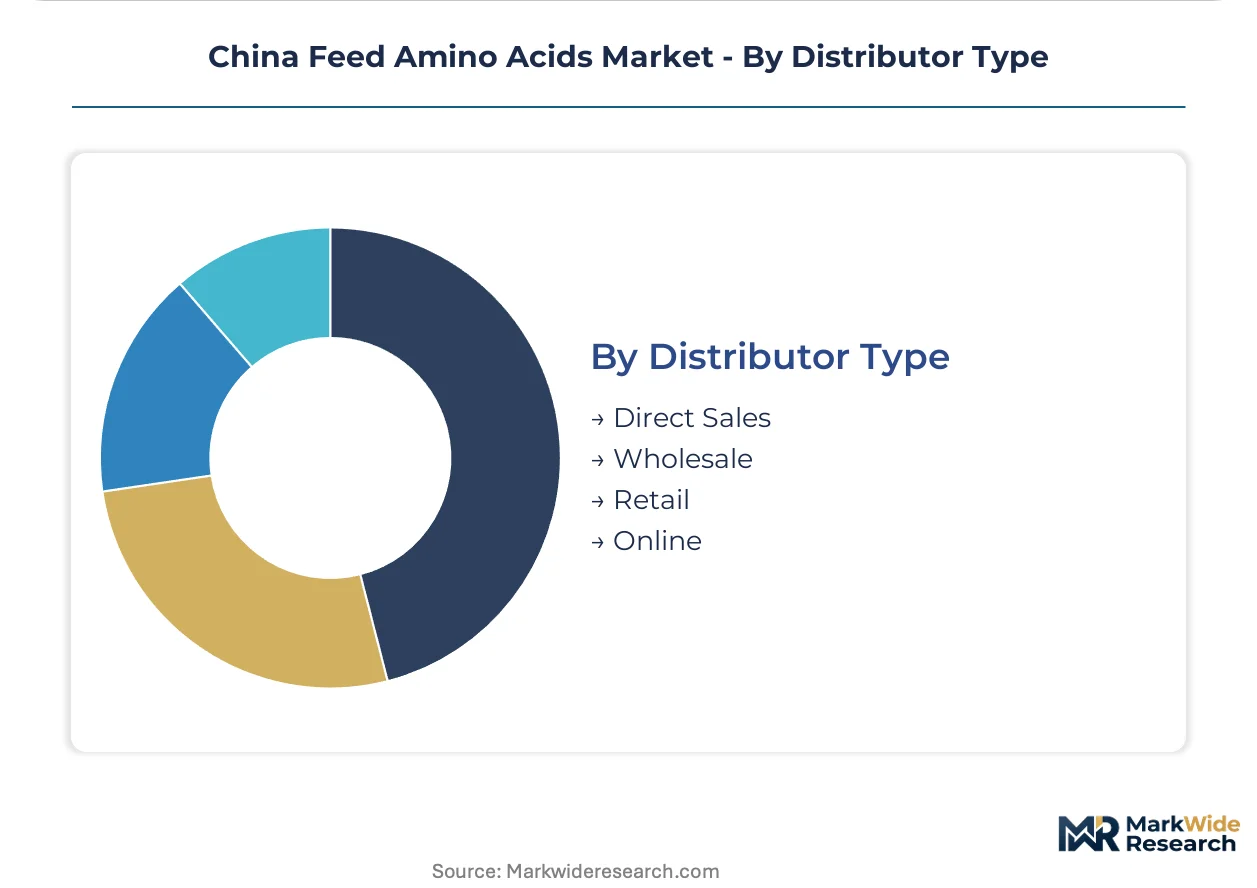
- Direct Sales:Direct procurement contracts between amino acid producers and integrated livestock operations are displacing traditional distributor-mediated transactions. Direct channels dominate in the Yangtze River basin where vertical livestock integration has advanced furthest.
- Wholesale:Wholesale distributors retain relevance for mid-sized feed mills lacking procurement scale for manufacturer-direct relationships. Wholesale networks serve Sichuan and Hunan provincial feed cooperatives.
- Retail:Retail channels supply smallholder livestock operations through agricultural supply cooperatives. Retail procurement concentrates in western provinces with fragmented farm structures.
- Online:Digital procurement platforms are emerging for standardized amino acid specifications in spot market transactions. Online channels currently capture minimal volume but are expanding among smaller aquaculture feed producers in coastal zones.
Direct sales and wholesale anchor current distribution; online channels represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's feed amino acids sector balances domestic production concentration against import dependency for specialty formulations. Export flows from Shandong Province supply Southeast Asian aquaculture operations while coastal provinces absorb hydroxy-analogue methionine imports.
Shandong Province
Corn-soy processing clusters in Weifang and Qingdao generate lysine hydrochloride for Henan swine operations. GB 7300 standards enforcement by provincial agriculture bureaus tightens heavy metal certification timelines. Fermentation capacity expansion concentrates in Binzhou's industrial corridor where electricity tariffs favor continuous processing systems.
Guangdong Province
Shrimp farming intensification across Zhanjiang and Shantou drives methionine hydroxy-analogue procurement beyond traditional poultry specifications. SAMR's feed additive catalog implementation requires import documentation for European specialty formulations. Aquaculture feed manufacturers in Foshan consolidate supplier relationships to secure assay consistency for marine fish diets.
Jiangsu Province
Yangtze Delta poultry integrators in Nantong and Xuzhou source DL-methionine through direct procurement contracts displacing wholesale channels. MEE environmental inspections force fermentation capacity idling and capital relocation to northern corridors. Nantong's port infrastructure facilitates bulk amino acid imports for coastal compounders.
Sichuan Province
Swine finishing operations in Chengdu and Deyang anchor lysine demand from Shandong fermentation facilities via rail freight corridors. Provincial agricultural modernization subsidies accelerate automated feed mill infrastructure adoption. Deyang's livestock integration clusters bypass traditional distributors for manufacturer-direct amino acid procurement.
Xinjiang Uyghur Autonomous Region
Corn belt proximity and lower environmental compliance density attract greenfield fermentation investment for lysine production. Dual carbon renewable energy mandates reduce electricity costs for bioreactor operations compared to eastern coastal zones. Urumqi's logistics hub position enables overland export routing to Central Asian livestock markets.
China Feed Amino Acids Market Vendor Landscape
Listed leaders compete with private specialists across fermentation scale and specialty formulation capabilities. The vendor base organizes around three tiers: integrated chemical conglomerates with methionine platforms, regional corn-fermentation specialists with backward integration into grain procurement, and European-Japanese precision nutrition players with hydroxy-analogue patent positions. Consolidation pressure intensifies as GB standards compliance costs favor capital-heavy operators with multi-product fermentation trains. Capacity expansion and pharmaceutical-grade production line conversion represent the dominant competitive vectors.
Among foreign-incumbent precision nutrition specialists, Adisseo and Evonik Industries AG occupy positions defined by methionine platform breadth and hydroxy-analogue formulation expertise respectively. Wudi Deda Agriculture Co. Limited exemplifies the regional Chinese archetype combining corn-fermentation scale with provincial supply chain anchoring. These three represent distinct strategic postures: multinational technology licensing against domestic raw-material integration against European specialty chemistry.
| Leading Market Players |
|---|
| IFF (Danisco Animal Nutrition) |
| Ajinomoto Co., Inc. |
| Adisseo |
| Impextraco NV |
| Kemin Industries |
| Alltech, Inc. |
| SHV (Nutreco NV) |
| Wudi Deda Agriculture Co. Limited |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Continuous fermentation scale economies in Shandong's lysine facilities compress unit costs while simultaneously concentrating pricing power among operators with multi-product bioreactor trains. This dual dynamic of cost reduction and supply consolidation establishes price floors that smaller batch processors cannot match, reshaping procurement negotiations across downstream feed compounders.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for lysine and methionine volumes, with three-tier pricing structure across pharmaceutical-grade, feed-grade, and industrial-grade certification levels. Price differentiation stems from GB 7300 compliance certification costs and volume scale commitments, with pharmaceutical-grade lysine commanding substantial premiums over feed-grade specifications. Cost compression in standard-grade lysine is intensifying because corn price volatility strains margin stability for Shandong-based fermentation operators. Mid-sized feed mills in Sichuan and Hunan provinces exhibit highest price sensitivity, while integrated swine enterprises in Henan prioritize assay consistency over spot market flexibility.
Supply Chain Analysis
MEE environmental inspection enforcement in the Yangtze Delta underwrites supply chain vulnerability as unplanned capacity idling forces reliance on Shandong and Hebei fermentation clusters. Geographic supply concentration centers on China for lysine hydrochloride, Germany and Belgium for specialty methionine hydroxy-analogues, and Malaysia for tryptophan fermentation capacity. Raw material dependencies rest on domestic corn procurement for fermentation feedstock, petroleum derivatives for synthetic DL-methionine routes, and sulfur compounds for methionine synthesis. Single-source vulnerability concentrates in Shandong's corn-soy processing corridors where environmental compliance density threatens operational continuity. Distribution runs through direct procurement contracts displacing wholesale channels for large integrated livestock operations, while wholesale networks retain relevance for mid-sized provincial feed cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's feed amino acids sector is approaching a cyclical recovery as aquaculture diet intensification in Guangdong and Fujian provinces rebuilds volume demand after environmental compliance disruptions. Corn price stabilization and renewable energy cost reductions in northern fermentation corridors reinforce this demand-side momentum.
For Market Incumbents: Compound backward integration into corn fermentation to secure feedstock cost control against domestic grain price volatility. Expand pharmaceutical-grade production line conversions to capture premium positioning as GB standards compress industrial and food-grade specifications. Prioritize capacity relocation from Yangtze Delta zones to Xinjiang and Inner Mongolia corridors where MEE inspection density remains lower and renewable electricity tariffs favor continuous processing economics.
For New Entrants and Emerging Players: Aquaculture specialty formulation services represent an under-served layer where European precision nutrition players currently dominate hydroxy-analogue methionine supply. Target Guangdong shrimp feed manufacturers with liquid methionine handling efficiency and assay consistency guarantees that displace incumbent powder formulations. Pursue SAMR feed additive catalog pre-approval positioning for novel amino acid variants to secure first-mover commercialization rights.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional Chinese fermentation specialists with captive corn supply and provincial supply chain anchoring over multinational technology licensors facing margin compression. Long-term viability across the projection horizon rests on environmental compliance adaptability and pharmaceutical-grade certification capabilities. Acquisition target archetype: Shandong-based operators with multi-product fermentation trains and established direct procurement relationships with integrated livestock enterprises. Monitor MEE enforcement intensity in eastern coastal zones as the critical inflection signal for capacity relocation timing and valuation adjustments.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Production Line Conversion | GB 7300 standards revisions compress industrial-pharmaceutical grade gaps, rewarding early compliance investment with premium positioning. |
| Northwest Corridor Capacity Expansion | Xinjiang and Inner Mongolia fermentation greenfields exploit lower MEE compliance density and corn belt proximity. |
| Backward Integration into Corn Fermentation | Wudi Deda Agriculture Co. Limited exemplifies how captive grain supply stabilizes margin structures against procurement volatility. |
| Hydroxy-Analogue Aquaculture Formulation Development | Evonik Industries AG demonstrates premium capture in Guangdong shrimp farming zones through specialty methionine chemistry. |
| Direct Procurement Contract Consolidation | Yangtze River basin livestock integrators bypass wholesale markups, reshaping channel economics for volume operators. |
Methodological Framework
Desk research of MIIT industrial policy filings, SAMR feed additive catalogues, and MEE environmental enforcement records preceded structured interviews with fermentation plant managers, feed mill procurement directors, and aquaculture nutrition specialists. Primary fieldwork encompassed technical discussions with Shandong-based lysine manufacturers, Guangdong shrimp feed compounders, and provincial agriculture bureau regulators. Secondary validation drew from GB standards documentation, customs trade data for amino acid imports, and SEC filings of listed chemical conglomerates with methionine platforms. Bottom-up volume modeling triangulated against top-down sector sizing from agricultural modernization subsidy disbursements.
Variance decomposition across product type, application, and regional production hub dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated lysine hydrochloride purity tiers, methionine formulation variants, aquaculture versus livestock end-use specifications, and distributor channel structures. CAGRs were derived from trend extrapolation of fermentation capacity utilization rates, corn-soy processing cluster expansion plans, and aquaculture diet intensification trajectories. Industry-specific forecast inputs included dual carbon renewable energy mandate implementation timelines and SAMR novel amino acid variant approval pipelines.
Forecasts assume regulatory continuity in GB standards enforcement and MIIT industrial upgrading policies; material policy shifts would require re-modeling of compliance cost structures and capacity relocation economics. Specific risk factors encompass MEE inspection intensity variations, corn price volatility from import policy adjustments, and synthetic amino acid substitution rates from petroleum derivative pricing. Practitioners should keep alternative scenarios live as dual carbon energy transition implementation and aquaculture disease outbreak patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Europe Feed Enzymes Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Plant Growth Regulators Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
Agricultural Miticides Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Strobilurin Fungicide Market