
 North America Agricultural Chemical Packaging Market | 2026-2036
North America Agricultural Chemical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Chemical Packaging Market Analytics
Asset-light leasing models for intermediate bulk containers are rewriting competitive entry barriers across the North American farm supply chain. Mauser Packaging Solutions leverages its reconditioning network to sustain circular packaging economics at scale. Greif Inc. anchors its position through steel drum manufacturing dominance in the US agricultural heartland. ProAmpac LLC differentiates via multi-layer film technology for crop protection sachets and water-soluble pouches.
Agricultural chemical packaging encompasses engineered containment systems designed to store, transport, and dispense pesticides, fertilizers, herbicides, and adjuvants while preventing contamination, spillage, and degradation through barrier properties typically measured in oxygen transmission rates below 0.5 cc per square meter per day. These systems employ high-density polyethylene, fluorinated polymers, or epoxy-lined steel to resist corrosive chemistries and UV exposure during seasonal field application cycles. Plastic bottles and jerrycans lead volume in the crop protection segment due to their compatibility with closed-transfer systems and EPA-compliant child-resistant closures. Bulk containers represent the fastest-expanding size category as Midwest grain operations consolidate input purchases and adopt just-in-time delivery contracts with cooperatives.
The EPA regulates agricultural chemical packaging through 40 CFR Part 165 container and containment standards, while OSHA mandates hazard communication labeling under the Hazard Communication Standard. Canada's PMRA enforces equivalent packaging integrity requirements through the Pest Control Products Act, creating a dual-compliance burden for cross-border suppliers. State-level regulations in California and New York impose additional residue-testing protocols that elevate material specification thresholds beyond federal minimums. Stakeholders must monitor evolving extended producer responsibility frameworks in both countries that will increasingly assign end-of-life collection costs to original packaging manufacturers rather than downstream agricultural retailers.
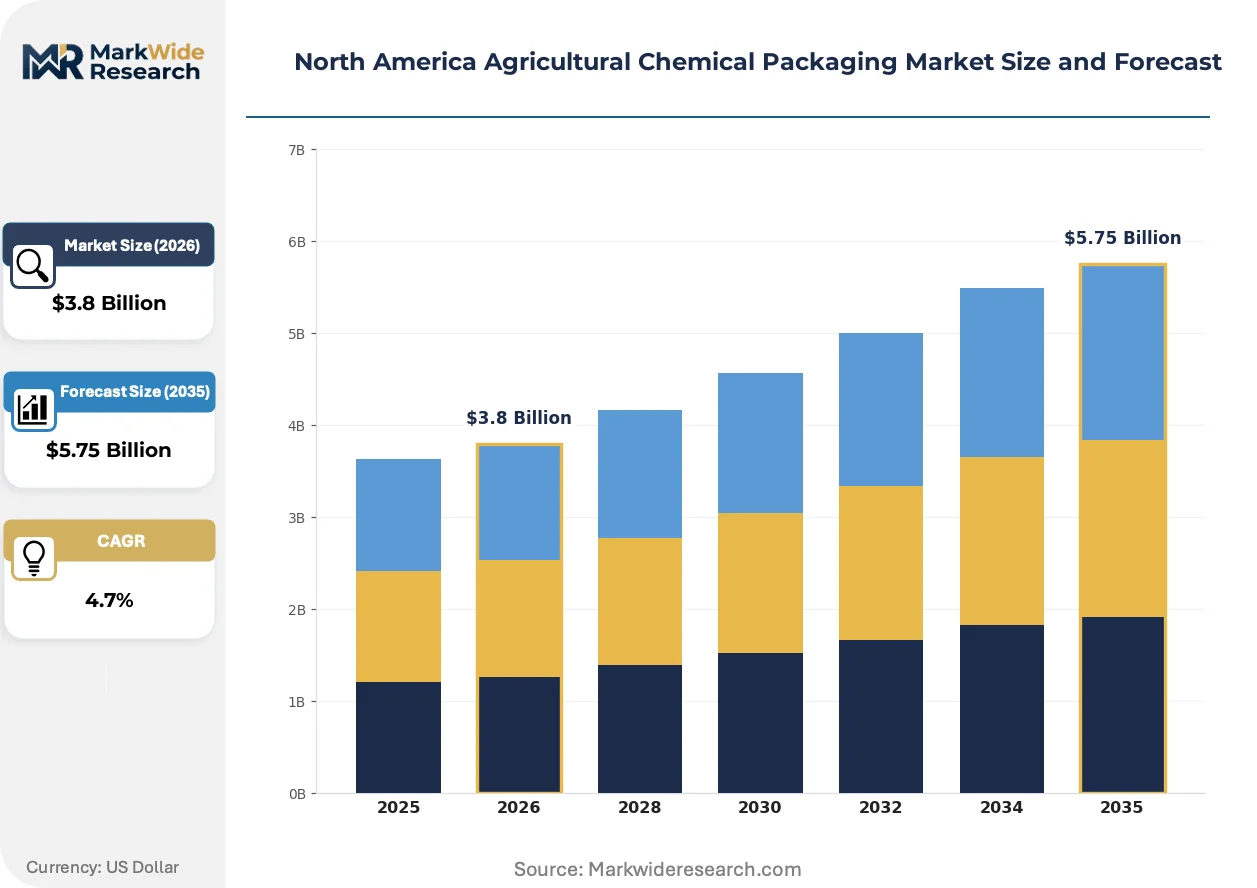
Market Dynamics
Asset-light leasing models for intermediate bulk containers are compressing capital requirements across the North American farm supply chain, allowing cooperatives to scale storage capacity without balance-sheet expansion. This structural shift toward circular packaging economics is redistributing margin capture from manufacturers to logistics orchestrators.
Growth Catalysts
- 40 CFR Part 165 containment standards:EPA-mandated closed-transfer systems for refillable containers are accelerating replacement cycles in the US Corn Belt, where anhydrous ammonia distributors face residue-handling compliance deadlines.
- Precision-dosed sachets:Specialty crop producers in California's Central Valley are adopting water-soluble pouches for vineyard fungicides, reducing field-mixing labor and drift exposure.
- Midwest grain operation consolidation:Just-in-time delivery contracts with agricultural cooperatives are concentrating demand for bulk intermediate bulk containers across Iowa and Illinois.
Market Restraints
- Fluorinated polymer cost volatility:Barrier-layer raw materials for multi-layer crop protection films face supply concentration from limited North American resin producers.
- California residue-testing protocols:State-level requirements under the Department of Pesticide Regulation exceed federal EPA minimums, elevating material specification costs for cross-border suppliers.
- Steel drum substitution pressure:Epoxy-lined steel containers for corrosive herbicides face displacement from high-density polyethylene alternatives with improved UV resistance.
Strategic Opportunities
- Florida specialty crop expansion:Citrus and strawberry producers in the Lake Wales Ridge region represent underpenetrated demand for precision-dosed packaging formats with Spanish-language labeling compliance.
- Extended producer responsibility frameworks:Emerging state-level mandates in New York and California will assign end-of-life collection costs to original manufacturers, creating first-mover advantage for reconditioning network operators.
- RFID-enabled container tracking:Convergence of polymer engineering and IoT sensor integration enables real-time inventory management for cooperative bulk chemical pooling systems.
Industry Challenges
- Child-resistant closure certification timelines:EPA-compliant CR packaging testing protocols create 12-18 month product development cycles that compress competitive response windows.
- Legacy drum reconditioning integration:Steel drum refurbishment operations require capital-intensive wash-and-recoat facilities that conflict with asset-light leasing model economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Chemical Packaging Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Bottles, Drums, Containers Material: Plastic, Metal, Glass, Paperboard End Use Industry: Crop Protection, Fertilizers, Biopesticides, Soil Amendments Size: Small, Medium, Large, Bulk |
| Companies Covered | LC Packaging International BV, Mauser Packaging Solutions, Greif Inc., Silgan Holdings, Amcor PLC, Mondi Group, ProAmpac LLC, United Caps, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Chemical Packaging Market Evolving Landscape
Water-soluble film technology is actively displacing conventional rigid packaging across North American specialty agriculture, with material science advances enabling cold-water dissolution at lower cost points. This shift is compressing the traditional three-layer supply chain between chemical formulators and field applicators.
Multi-layer coextruded films with oxygen transmission rates below 0.5 cc per square meter per day are rendering obsolete single-barrier polyethylene containers for moisture-sensitive pesticide formulations. Specialty crop producers in Florida and California are adopting these formats for pre-dosed adjuvant sachets. The technology is compressing field-mixing labor costs while elevating barrier property specifications across supplier qualification processes.
EPA container and containment standards under 40 CFR Part 165 are tightening residue-handling requirements for refillable intermediate bulk container systems. Agricultural retailers in the US Midwest face capital allocation decisions between reconditioning infrastructure and disposable packaging conversion. The regulation is accelerating cooperative investment in closed-transfer system compatibility testing for legacy drum fleets.
Cooperative procurement consolidation is compressing supplier negotiation cycles across the Corn Belt, with Iowa and Illinois grain operations pooling chemical purchases through shared-service entities. Traditional distributor markups face pressure from direct manufacturer contracts with large-scale farm enterprises. This concentration is most visible in anhydrous ammonia and liquid fertilizer segments where volume thresholds determine logistics pricing tiers.
North America Agricultural Chemical Packaging Market Segmentation
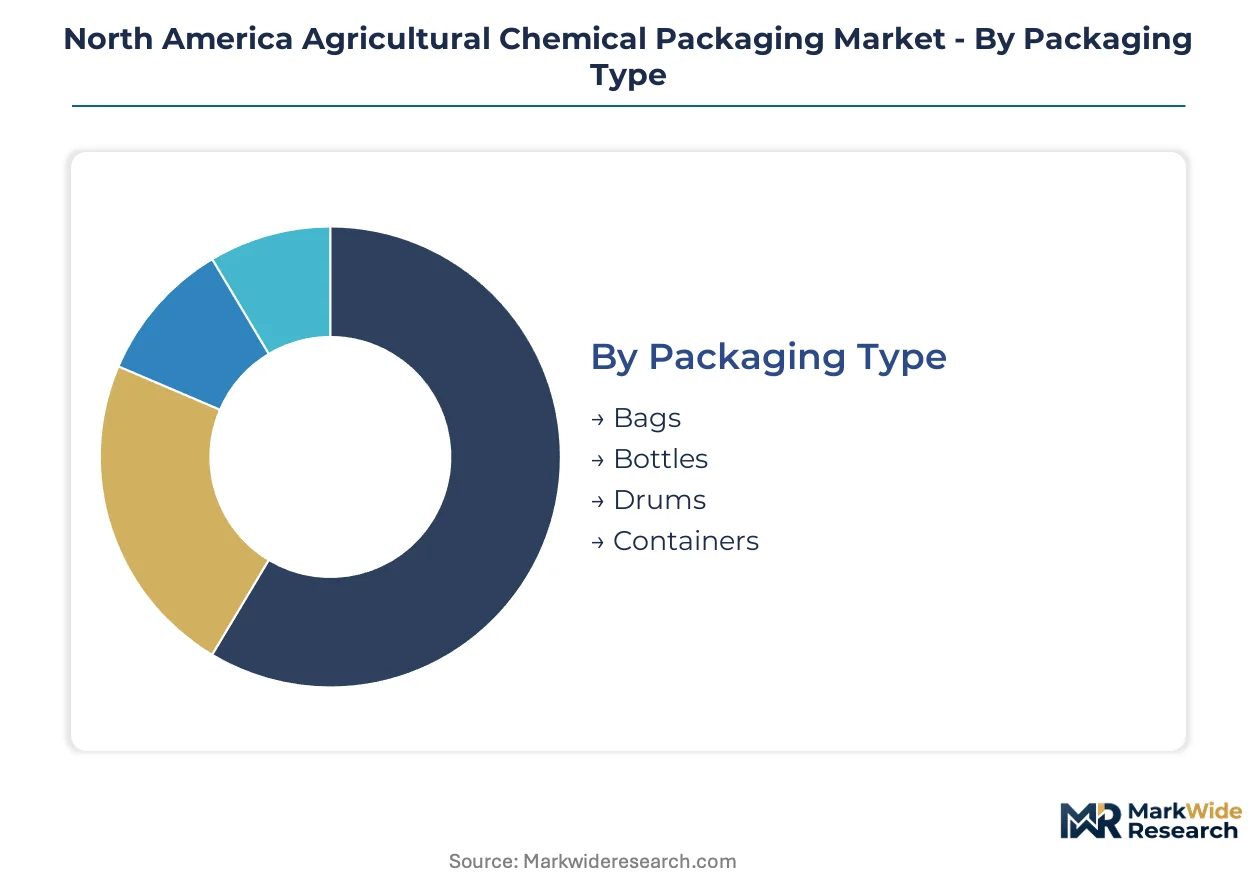
Agricultural chemical packaging segmentation reflects the tension between EPA-mandated containment standards and farm-level operational economics. Each dimension carries distinct after-sales service intensity, from drum reconditioning networks to water-soluble film technical support.
Packaging Type:
Service intensity varies sharply across formats, with refillable systems demanding ongoing technical compliance support versus single-use disposables.
- Bottles:High-density polyethylene construction with child-resistant closures dominates crop protection retail distribution. Demand concentrates in California specialty crop regions where precision-dosed formats reduce field-mixing labor.
- Drums:Epoxy-lined steel and fluorinated polymer variants handle corrosive herbicide formulations. Iowa and Illinois cooperatives drive replacement cycles through EPA 40 CFR Part 165 closed-transfer compliance deadlines.
- Containers:Intermediate bulk systems enable just-in-time delivery contracts across the Corn Belt. Asset-light leasing models redistribute margin capture toward logistics orchestrators.
- Bags:Multi-layer film construction with sub-0.5 cc oxygen transmission rates protects moisture-sensitive pesticides. Florida citrus operations adopt pre-dosed adjuvant sachets for drift reduction.
Bottles hold the largest share; momentum sits with containers.
Material:
Cost tier differentiation separates premium barrier specifications from commodity-grade alternatives, with fluorinated polymers commanding technical service premiums.
- Plastic:High-density polyethylene and fluorinated polymers resist UV degradation and corrosive chemistries. Midwest grain operations favor HDPE alternatives displacing legacy steel for anhydrous ammonia handling.
- Metal:Epoxy-lined steel drums maintain dominance in high-volume liquid fertilizer logistics. Reconditioning network density determines competitive positioning across the agricultural heartland.
- Paperboard:Limited penetration in primary chemical containment; finds application in secondary bundling and retail display configurations for consumer-facing crop protection products.
- Glass:Restricted to laboratory reference standards and specialty adjuvant sampling; negligible volume in field-scale agricultural deployment due to breakage risk and weight penalties.
Plastic dominates volume; metal retains margin concentration in bulk logistics.
End Use Industry:
Application-driven specifications range from single-season biodegradability for biopesticides to multi-year barrier integrity for synthetic chemistries.
- Crop Protection:Herbicide, fungicide, and insecticide packaging demands sub-0.5 cc oxygen transmission rates through multi-layer coextruded films. California Central Valley vineyard operators drive water-soluble pouch adoption for fungicide delivery.
- Fertilizers:Anhydrous ammonia and liquid formulations require corrosion-resistant bulk containment. Iowa and Illinois cooperative consolidation concentrates demand for intermediate bulk container pooling systems.
- Soil Amendments:pH modifiers and micronutrient blends utilize standard HDPE bottles and drums with reduced barrier specifications compared to synthetic pesticides.
- Biopesticides:Living organism formulations demand breathable yet contamination-resistant packaging with shorter shelf-life requirements driving higher turnover velocity.
Crop protection commands premium pricing; biopesticides are climbing the fastest.
Size:
Volume scale determines logistics economics, with bulk formats enabling cooperative procurement consolidation and small formats serving precision agriculture workflows.
- Bulk:Intermediate bulk containers and tote systems support just-in-time delivery contracts. EPA 40 CFR Part 165 residue-handling standards accelerate cooperative investment in closed-transfer infrastructure.
- Large:55-gallon drum equivalents serve commercial-scale farm operations with annual volume thresholds qualifying for direct manufacturer pricing.
- Medium:5-30 gallon containers bridge retail distribution and commercial application, common in specialty crop regions with moderate acreage scales.
- Small:Precision-dosed sachets and water-soluble pouches reduce field-mixing labor. Florida strawberry and citrus producers adopt these formats for Spanish-language labeling compliance.
Bulk formats anchor revenue; small formats gain share fastest in specialty crop regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the US Midwest Corn Belt, where cooperative procurement consolidation extracts volume discounts unavailable to fragmented specialty crop operators in California and Florida. This asymmetry reshapes manufacturer go-to-market economics across North America.
United States
Iowa and Illinois grain operations drive intermediate bulk container demand through just-in-time delivery contracts with agricultural cooperatives. EPA 40 CFR Part 165 closed-transfer compliance deadlines accelerate replacement cycles for legacy drum fleets. California's Central Valley vineyard operators adopt water-soluble pouches for fungicide delivery, reducing field-mixing labor costs.
Canada
Prairie province grain handlers favor bulk containment systems for anhydrous ammonia storage across Saskatchewan and Manitoba. PMRA enforces packaging integrity requirements through the Pest Control Products Act, creating dual-compliance burdens for cross-border suppliers. Ontario's corn-soybean belt concentrates demand for high-density polyethylene alternatives to steel drums.
Mexico
Sinaloa and Sonora vegetable exporters drive precision-dosed sachet adoption for compliance with US residue tolerance standards. Mexico's national agricultural regulator mandates child-resistant closure specifications for crop protection products entering domestic distribution. Bajío region strawberry producers adopt Spanish-language labeled water-soluble pouches for drift reduction.
North America Agricultural Chemical Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and conversion technologies. The vendor base clusters around three functional layers: circular logistics orchestrators, barrier film engineers, and rigid container fabricators. Consolidation pressure concentrates in the Midwest, where cooperative procurement scale favors suppliers with reconditioning network density. Dominant competitive moves include asset-light leasing model expansion and multi-layer coextrusion capacity additions.
Among circular logistics specialists, Mauser Packaging Solutions and Greif Inc. occupy positions defined by reconditioning infrastructure scale and steel drum manufacturing presence respectively. ProAmpac LLC exemplifies the barrier film engineering tier through its multi-layer technology positioning for crop protection sachets. These three anchors illustrate how competitive advantage separates logistics network operators from materials science specialists across the North American farm supply chain.
| Leading Market Players |
|---|
| LC Packaging International BV |
| Mauser Packaging Solutions |
| Greif Inc. |
| Silgan Holdings |
| Amcor PLC |
| Mondi Group |
| ProAmpac LLC |
| United Caps |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
Union Pacific rail corridors from the Gulf Coast petrochemical complex to Iowa distribution hubs dictate landed cost structures for fluorinated polymer resins, concentrating pricing power among resin producers while forcing Midwest cooperatives into volume-commitment contracts that separate large-scale buyers from fragmented specialty crop operators.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification premiums for EPA 40 CFR Part 165 closed-transfer compliance, while economy tiers serve basic HDPE bottle demand. Pricing pressure stems from fluorinated polymer cost volatility as limited North American resin producers constrain supply. Small-scale California vineyard operators exhibit highest price sensitivity due to fragmented procurement, whereas Iowa cooperative consortiums leverage volume scale for direct manufacturer contracts.
Supply Chain Analysis
Export controls on fluoropolymer production technology limit resin manufacturing expansion outside established facilities, concentrating supply in the US Gulf Coast, Germany, and Japan. Agricultural chemical packaging draws from high-density polyethylene feedstocks, epoxy coating compounds, and multi-layer film substrates. Single-source vulnerability pervades fluorinated polymer supply given patent-protected barrier-layer formulations. Distribution runs through agricultural cooperative networks in the Corn Belt and specialty crop distributor channels in California and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of closed-transfer system engineering talent constrains rapid compliance adaptation, rewarding first-movers who capture certified technical capabilities before EPA enforcement deadlines tighten.
For Market Incumbents: Harden reconditioning network density across the agricultural heartland to defend against asset-light leasing model disruption. Expand backward integration into fluorinated polymer compounding to secure barrier-layer supply against resin concentration risk. Prioritize certification investment for 40 CFR Part 165 closed-transfer compatibility testing to compress competitor response windows. For New Entrants and Emerging Players: Florida's Lake Wales Ridge citrus and strawberry regions offer underpenetrated demand for Spanish-language precision-dosed packaging with minimal incumbent reconditioning infrastructure. Target biopesticide breathable packaging segments where shorter shelf-life requirements favor agile manufacturing over scale economies. Pursue direct contracts with Sinaloa vegetable exporters seeking US residue compliance through precision-dosed formats. For Investors and Strategic Acquirers: Regional reconditioning network operators with EPA-certified wash-and-recoat facilities represent prime acquisition targets as extended producer responsibility mandates shift end-of-life costs to manufacturers. Long-term viability hinges on circular logistics orchestration capabilities rather than commodity container fabrication. Monitor California Department of Pesticide Regulation residue-testing protocol expansions as signal for material specification cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Reconditioning Network Expansion | Captures margin redistribution toward circular logistics orchestrators serving Iowa and Illinois cooperatives. |
| Multi-Layer Coextrusion Capacity Addition | Enables sub-0.5 cc oxygen transmission rate specifications for California vineyard fungicide pouches. |
| Closed-Transfer System Certification | Accelerates EPA 40 CFR Part 165 compliance for legacy drum fleets across Midwest grain operations. |
| RFID-Enabled Container Tracking Integration | Supports real-time inventory management for cooperative bulk chemical pooling systems. |
| Spanish-Language Labeling Compliance Investment | Unlocks Florida specialty crop and Mexico Bajío region strawberry producer demand. |
Research Methodology
Cross-validation between primary interviews with agricultural cooperative procurement managers, EPA compliance officers, and multi-layer film technical directors anchors the qualitative findings against secondary sources including EPA 40 CFR regulatory filings, USDA agricultural chemical use surveys, and customs trade data for fluorinated polymer imports. Bottom-up triangulation across packaging format demand curves and top-down reconciliation with regional farm input expenditure patterns validates volume estimates.
Calibration against historical replacement cycles for steel drum fleets and water-soluble film adoption curves in California specialty crops shapes the analytical framework across the projection horizon. Segmentation dimensions span packaging type, material barrier specification, end-use chemistry sensitivity, and size category. CAGRs derive from weighted average growth across cooperative procurement consolidation trends and precision agriculture packaging conversion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light logistics orchestrators would shift outcomes beyond modeled parameters. Material shifts in EPA residue-handling enforcement intensity or fluorinated polymer supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
North America Feed Enzymes Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Europe Feed Antibiotics Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Poultry Premix Market
Agricultural Chemicals
North America Feed Phytogenics Market