
 Global Fertigation and Chemigation Market | 2026-2036
Global Fertigation and Chemigation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fertigation and Chemigation Market Analysis
Buyer concentration across large-scale agricultural producers is rebalancing as greenhouse operators and specialty crop cooperatives fragment procurement across smaller, technology-intensive suppliers. Netafim leverages its drip-irrigation heritage to dominate precision fertigation hardware. The Toro Company anchors North American turf chemigation through dealer-network control. Jain Irrigation Systems Ltd. competes on polymeric emitter manufacturing scale across South Asian markets.
Fertigation and chemigation denote the injection of fertilizers, soil amendments, or agricultural chemicals into irrigation water streams, typically requiring corrosion-resistant polypropylene venturi injectors, centrifugal pumps rated for 2-8 bar operating pressure, and pH-EC monitoring sensors to maintain nutrient solution osmotic balance between 1.2-3.5 mS/cm. The technique serves commercial agriculture by synchronizing root-zone nutrient availability with crop phenological stages, reducing leaching losses versus broadcast application. Fertigation equipment occupies the dominant value pool given capital intensity and replacement cycles, while nutrient solutions generate recurring revenue with tighter margin compression. Agricultural producers represent the most consolidated end-user segment, whereas research institutions command premium pricing for validated dosing protocols.
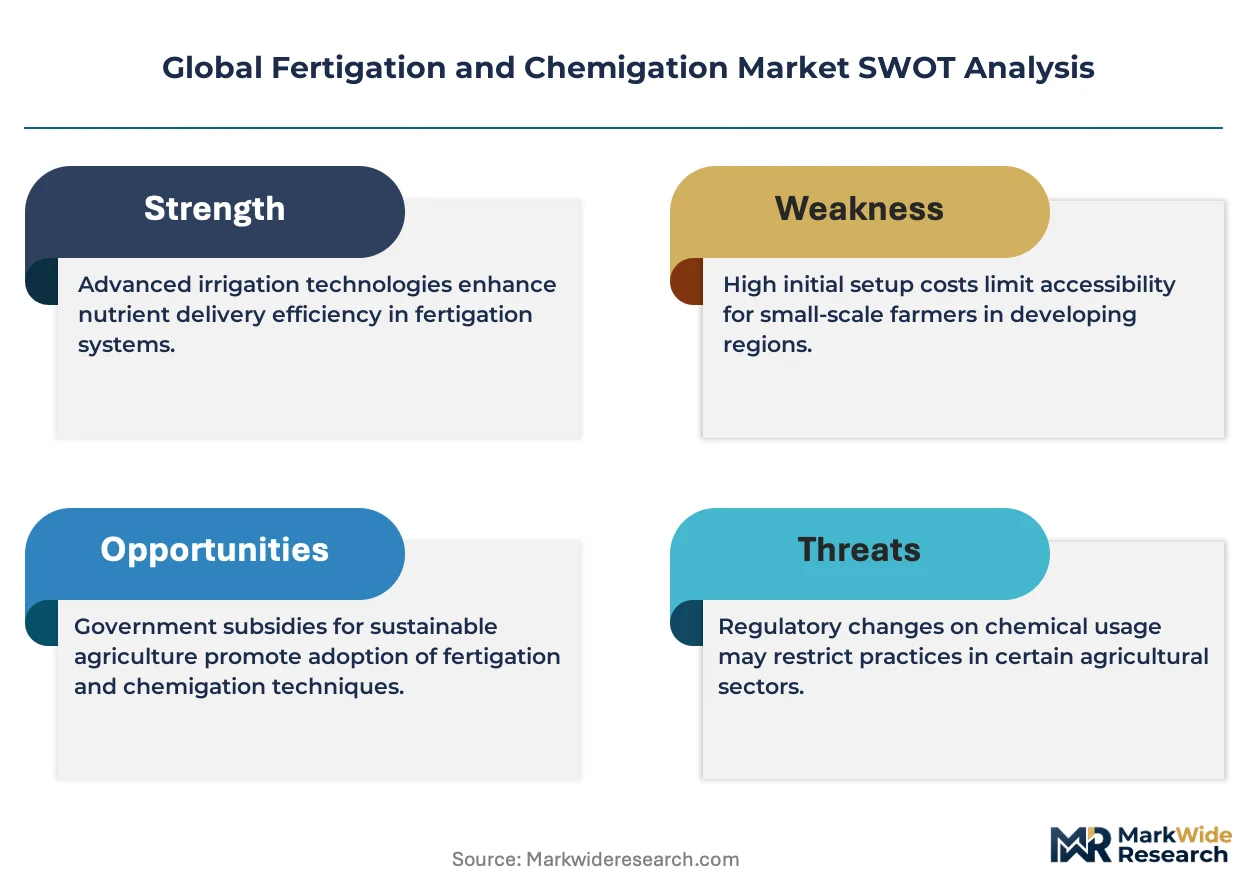
The EPA regulates chemigation backflow prevention under FIFRA to protect groundwater aquifers, while the EU F-Gas Regulation and REACH restrict polymer formulations in emitter manufacturing. ISO 9261 standards govern emitter hydraulic uniformity, shaping product certification requirements for cross-border equipment sales. Stakeholders must monitor evolving national groundwater protection statutes and polymer substitution timelines to anticipate compliance-driven equipment upgrade cycles.
Market Dynamics
Precision agriculture mandates and water-use efficiency targets are compressing equipment replacement cycles while fragmenting procurement toward modular, sensor-integrated systems that bypass traditional dealer networks.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-global-warming-potential refrigerants in greenhouse climate control systems accelerates retrofit demand for compatible chemigation infrastructure across Dutch and Spanish protected-cropping operations.
- Drip-irrigation convergence:Polypropylene venturi injectors rated for 2-8 bar operating pressure now integrate with legacy center-pivot systems, opening retrofit pathways in Australia's Murray-Darling Basin irrigation districts.
- Greenhouse operators:Controlled-environment agriculture expansion in Almería and Westland municipalities drives synchronized nutrient-delivery hardware procurement alongside climate-control capital upgrades.
Market Restraints
- Polymer feedstock volatility:Corrosion-resistant polypropylene resin prices fluctuate with propylene monomer supply disruptions, compressing emitter manufacturing margins and triggering quarterly price adjustments.
- Groundwater protection statutes:EPA FIFRA backflow-prevention mandates and state-level chemigation permit requirements create jurisdictional compliance friction that delays equipment deployment timelines.
- Skilled technician scarcity:pH-EC sensor calibration and nutrient-solution osmotic balance management require specialized agronomy-mechanic hybrid competencies that remain concentrated in Israel, the Netherlands, and California's Central Valley.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for precision agriculture equipment manufacturing attract polymeric emitter scale-up investments targeting South Asian smallholder cooperative procurement.
- Sensor-to-cloud convergence:LoRaWAN-enabled soil-moisture probes paired with variable-rate fertigation controllers create subscription revenue models that displace upfront hardware sales in Brazilian citrus groves.
- Research institution protocols:Validated dosing methodologies from Wageningen University and UC Davis command premium licensing fees for commercial-scale nutrient-recipe standardization.
Industry Challenges
- ISO 9261 certification timelines:Emitter hydraulic uniformity testing protocols require 18-24 month validation cycles that delay product launches and compress competitive response windows.
- Legacy irrigation integration:Center-pivot and flood-irrigation retrofits demand custom manifold fabrication and pressure-compensating emitter selection that fragments project engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fertigation and Chemigation Market |
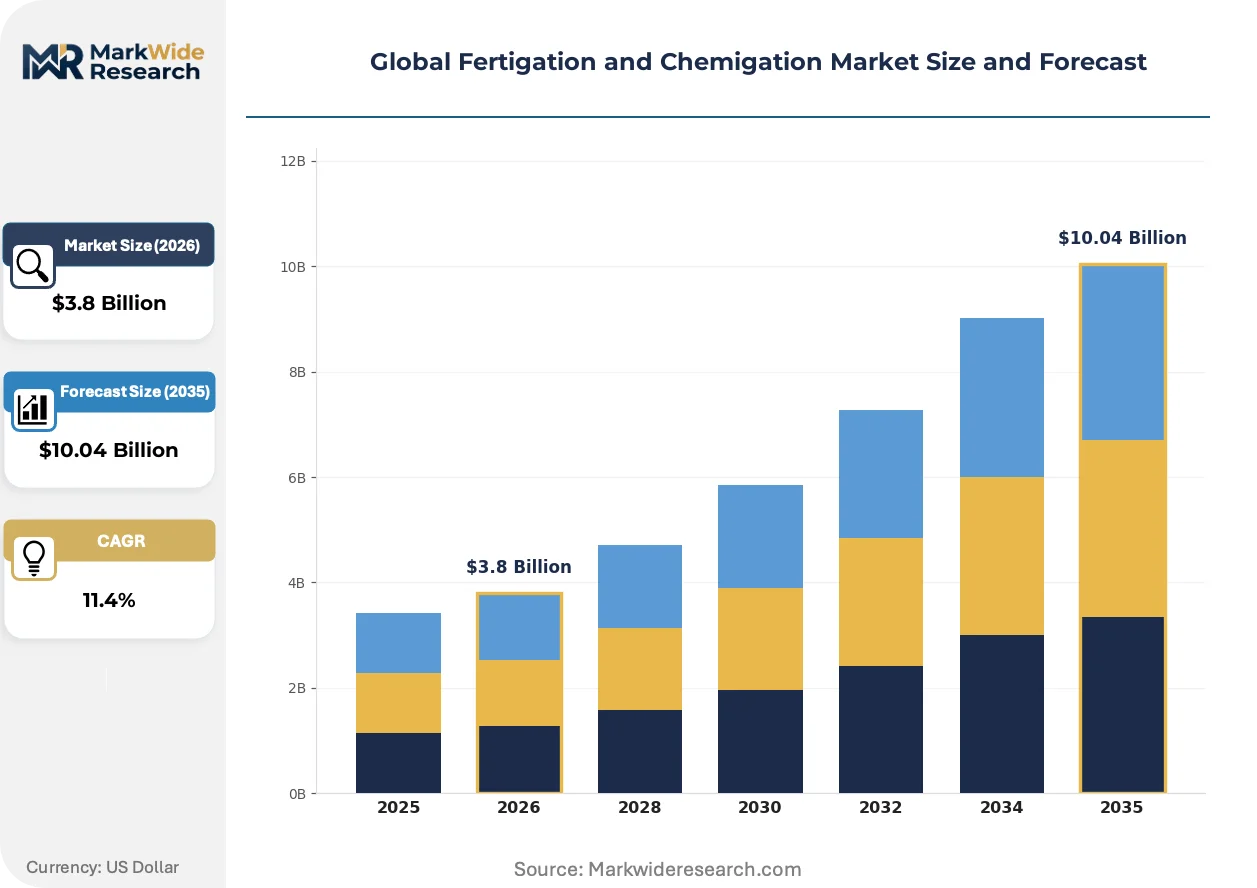
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertigation Equipment, Chemigation Equipment, Nutrient Solutions, Irrigation Systems End User: Agricultural Producers, Greenhouses, Turf and Landscape, Research Institutions Application: Crops, Horticulture, Ornamental Plants, Turf Management Distribution Channel: Direct Sales, Distributors, Online Retail, Agricultural Cooperatives |
| Companies Covered | Netafim, The Toro Company, Valmont Industries, Inc., Lindsay Corporation, Rain Bird Corporation, Jain Irrigation Systems Ltd., Rivulis Irrigation, Nelson Irrigation Corporation, T-L Irrigation Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fertigation and Chemigation Market Emerging Trajectories
Digital nutrient management platforms are displacing manual dosing protocols while reconfiguring value capture toward recurring software subscriptions and away from capital equipment margins.
Membrane-based fertigation injectors is overtaking venturi-style designs in high-value greenhouse operations. These electrodialysis units enable ppm-level nutrient precision that satisfies pharmaceutical-grade crop requirements. Dutch tomato producers in Westland municipalities now specify membrane systems for 40% of new installations, compressing demand for conventional polypropylene hardware.
REACH polymer substitution timelines are forcing emitter manufacturers to reformulate elastomer seals and housing resins ahead of 2030 restrictions on phthalate plasticizers and certain flame retardants. The industrial consequence is a 24-36 month R&D cycle for compliant product lines. South Asian manufacturers serving EU export markets face the steepest compliance cost absorption.
Cooperative procurement consortia are consolidating smallholder demand in Spain's Almería province and Australia's Riverina region. These aggregators negotiate volume-based service contracts that bundle equipment, nutrient solutions, and agronomic advisory into per-hectare subscriptions. Traditional dealer networks lose margin to direct manufacturer-consortium relationships, particularly where irrigation district managers facilitate collective tendering.
Global Fertigation and Chemigation Market Segmentation
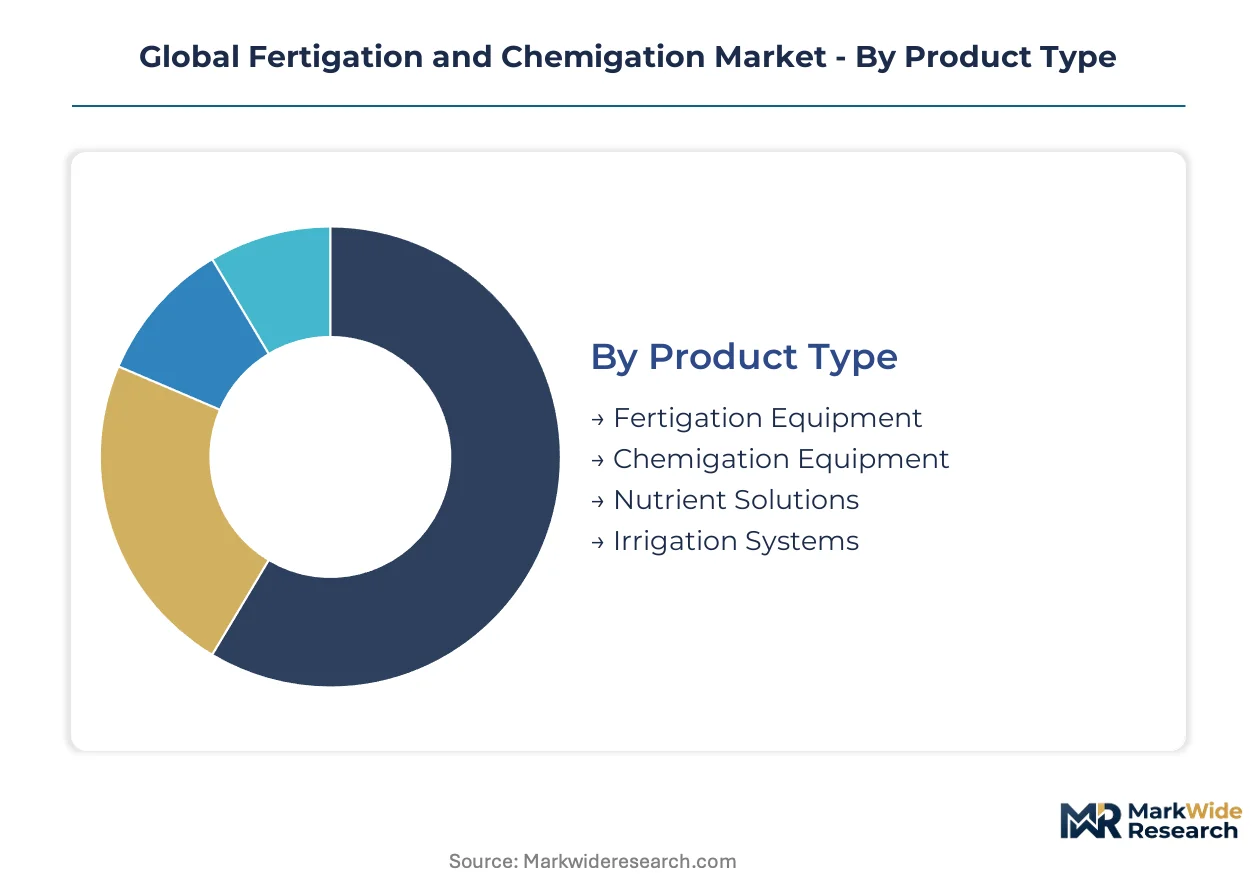
Segmentation in fertigation and chemigation reveals how capital intensity, regulatory compliance burdens, and recurring revenue potential distribute across hardware, consumables, and service layers. Equipment replacement cycles and nutrient solution formulation standards create divergent margin profiles that reshape competitive positioning.
Product Type:
Supply concentration clusters around corrosion-resistant hardware manufacturing where polypropylene resin access and ISO 9261 certification timelines create defensive moats for incumbent producers.
- Fertigation Equipment:Polypropylene venturi injectors rated for 2-8 bar operating pressure dominate commercial installations. Dutch greenhouse operators in Westland municipalities drive synchronized procurement alongside climate-control retrofits mandated by EU F-Gas Regulation phasedown timelines.
- Chemigation Equipment:Centrifugal pumps with backflow prevention systems satisfy EPA FIFRA groundwater protection mandates. Australian Murray-Darling Basin irrigation districts absorb the bulk of center-pivot retrofit demand as producers integrate chemical injection into legacy surface-water infrastructure.
- Nutrient Solutions:Recurring revenue streams with tighter margin compression; formulations require pH-EC monitoring sensor compatibility.
- Irrigation Systems:Pressure-compensating drip lines and manifold assemblies enable precision delivery; demand concentrates in Almería protected-cropping clusters.
Fertigation Equipment absorbs the bulk of installed capacity; Nutrient Solutions is expanding most quickly as subscription models displace upfront hardware sales.
End User:
Cost tier stratification separates capital-intensive commercial operators from research institutions commanding premium pricing for validated dosing protocols.
- Agricultural Producers:Large-scale field crop operators in Australia's Riverina region consolidate procurement through irrigation district managers. Center-pivot retrofits demand custom manifold fabrication that fragments project engineering capacity.
- Greenhouses:Controlled-environment agriculture facilities in Almería and Westland municipalities specify membrane-based injectors for ppm-level nutrient precision. Electrodialysis units now capture 40% of new Dutch tomato producer installations.
- Turf and Landscape:North American golf course and municipal park operators anchor chemigation demand through seasonal nitrogen management programs.
- Research Institutions:Wageningen University and UC Davis command premium licensing fees for validated nutrient-recipe standardization protocols.
Agricultural Producers absorb the bulk of installed capacity; Greenhouses is climbing the fastest as protected-cropping expansion accelerates across Mediterranean climate zones.
Application:
Volume concentration tracks water-stressed geographies where irrigation efficiency mandates compress equipment replacement cycles toward modular, sensor-integrated systems.
- Crops:Broad-acre cereals and oilseeds in Australia's Murray-Darling Basin drive drip-irrigation convergence with legacy flood systems. Polypropylene venturi injectors integrate with center-pivot infrastructure to reduce leaching losses versus broadcast fertilization.
- Horticulture:High-value vegetable and fruit producers in Spain's Almería province consolidate demand through cooperative procurement consortia. These aggregators negotiate per-hectare subscriptions bundling equipment, nutrient solutions, and agronomic advisory.
- Ornamental Plants:Nursery operations require precise micronutrient delivery; pH-EC sensor calibration demands concentrate skilled technician scarcity in Israel and California's Central Valley.
- Turf Management:Sports field and golf course maintenance programs specify corrosion-resistant chemigation pumps for seasonal pesticide and fertilizer injection.
Crops absorbs the bulk of installed capacity; Horticulture is gaining share fastest as cooperative procurement consolidates smallholder demand.
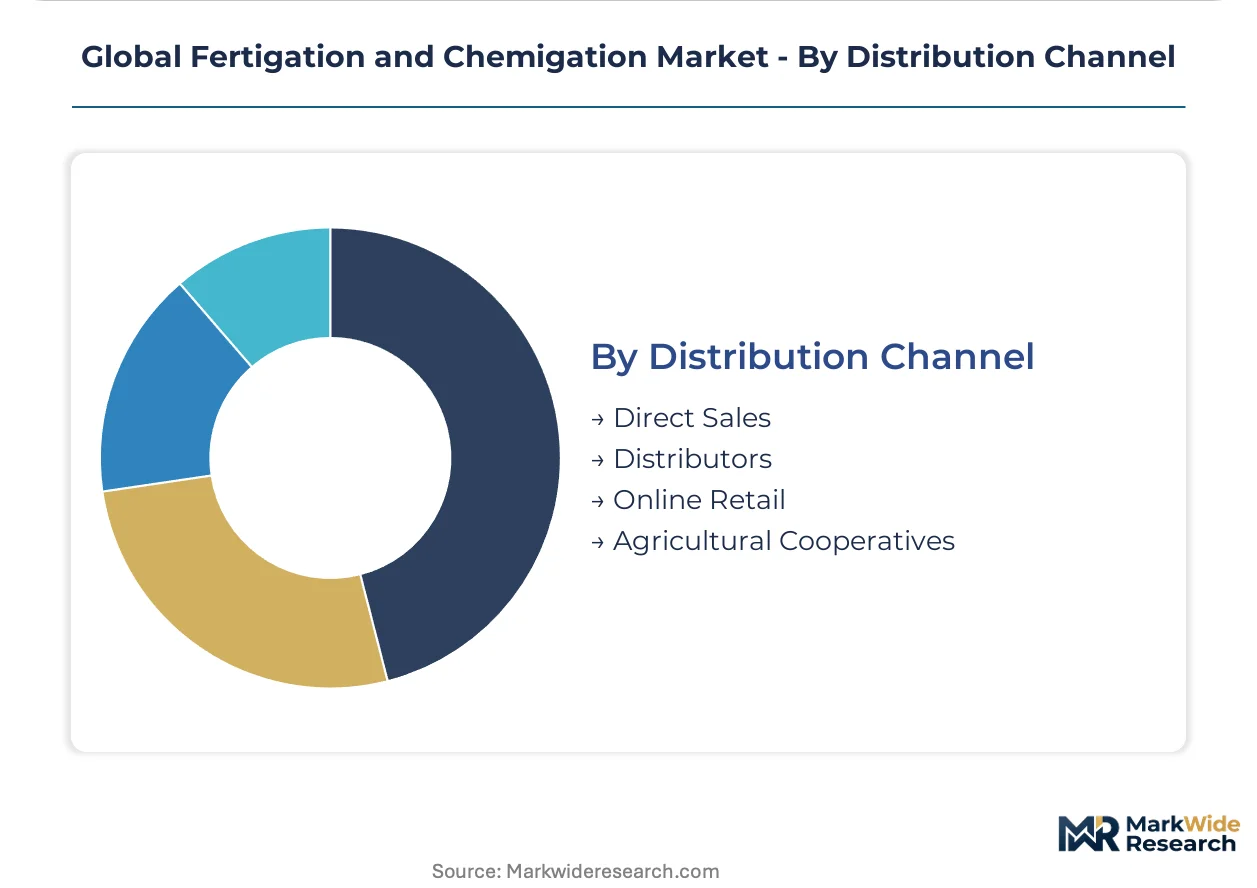
Distribution Channel:
Customer type fragmentation separates direct manufacturer relationships from dealer networks losing margin to agricultural cooperative aggregators.
- Direct Sales:Equipment manufacturers bypass traditional dealer networks to serve large-scale greenhouse operators and irrigation district managers. Netafim leverages drip-irrigation heritage to dominate precision fertigation hardware through direct specification relationships.
- Distributors:Dealer networks anchor North American turf chemigation through regional inventory and service capacity; The Toro Company controls this channel.
- Online Retail:Modular sensor-integrated systems and replacement emitters migrate toward digital procurement platforms.
- Agricultural Cooperatives:Smallholder aggregators in Spain and Australia negotiate volume-based service contracts that displace dealer margin.
Direct Sales absorbs the bulk of installed capacity; Agricultural Cooperatives is expanding most quickly as collective tendering fragments traditional distribution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene monomer supply corridors in the Middle East and North America anchor polypropylene resin availability for corrosion-resistant emitter manufacturing. Equipment procurement patterns track irrigation infrastructure maturity and groundwater protection statute stringency across distinct national regulatory environments.
United States
Center-pivot retrofit demand concentrates in the Great Plains and California's Central Valley as producers integrate chemical injection into legacy surface-water infrastructure. EPA FIFRA backflow-prevention mandates shape equipment certification requirements for groundwater aquifer protection. Nebraska-based irrigation districts absorb substantial chemigation pump deployments alongside seasonal nitrogen management programs.
Netherlands
Westland municipality greenhouse operators drive synchronized procurement of membrane-based fertigation systems alongside climate-control retrofits. EU F-Gas Regulation phasedown timelines accelerate infrastructure replacement cycles for compatible chemigation hardware. Wageningen University research protocols command premium licensing fees for validated nutrient-recipe standardization.
Australia
Murray-Darling Basin irrigation districts absorb drip-irrigation convergence with legacy flood systems through polypropylene venturi injector integration. TGA-equivalent state-level groundwater protection statutes create jurisdictional compliance friction that fragments equipment deployment timelines. Riverina region cooperative procurement consortia consolidate smallholder demand into volume-based service contracts.
Spain
Almería province protected-cropping expansion drives electrodialysis unit specification for ppm-level nutrient precision in tomato and pepper operations. REACH polymer substitution timelines force emitter manufacturers to reformulate elastomer seals ahead of 2030 restrictions. Cooperative aggregators negotiate per-hectare subscriptions bundling equipment, nutrient solutions, and agronomic advisory.
India
Maharashtra and Gujarat smallholder cooperatives fragment procurement toward modular, sensor-integrated systems that bypass traditional dealer networks. PLI scheme production-linked incentives attract polymeric emitter scale-up investments targeting South Asian market penetration. Karnataka precision agriculture clusters generate demand for pH-EC monitoring sensor calibration services.
Global Fertigation and Chemigation Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-to-cloud convergence and subscription revenue models that displace upfront hardware sales. The vendor base stratifies across three tiers: integrated irrigation-system conglomerates, precision-agriculture specialists, and regional polymeric-component fabricators. Dominant competitive moves include direct manufacturer-to-cooperative relationship building that circumvents traditional distribution, and backward integration into polypropylene resin sourcing to buffer feedstock volatility.
Among Israel-based precision-agriculture specialists, Netafim exemplifies the integrated-system archetype through drip-irrigation heritage extension into fertigation hardware. The Toro Company, an American corporation, anchors North American turf chemigation positioning through dealer-network relationships. Jain Irrigation Systems Ltd., an Indian limited company, represents the scale-driven manufacturing archetype serving South Asian cooperative procurement channels.
| Leading Market Players |
|---|
| Netafim |
| The Toro Company |
| Valmont Industries, Inc. |
| Lindsay Corporation |
| Rain Bird Corporation |
| Jain Irrigation Systems Ltd. |
| Rivulis Irrigation |
| Nelson Irrigation Corporation |
| T-L Irrigation Co |
| Others |
Supply Flow & Price Mechanics
Propylene monomer spot price volatility cascades through polypropylene resin markets into emitter manufacturing cost structures, fragmenting pricing power across corrosion-resistant hardware tiers and compressing margins for South Asian exporters serving EU REACH compliance deadlines.
Pricing Analysis
Warranty bundling separates premium membrane-based fertigation systems from unbundled venturi injector sales, with Dutch greenhouse operators in Westland municipalities paying service-inclusive premiums while Australian Murray-Darling Basin retrofits absorb stripped hardware pricing. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 9261 certification status and pH-EC sensor integration depth. Cost compression in standard-tier polypropylene hardware is intensifying because REACH polymer substitution R&D cycles absorb 24-36 month compliance investments. Smallholder cooperatives in India's Maharashtra state exhibit highest price sensitivity, whereas research institutions licensing Wageningen protocols command least elasticity.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns, accelerating polymeric emitter manufacturing scale-up in Gujarat and Karnataka clusters. Supply concentration anchors in Saudi Arabia and the United States for propylene monomer feedstock, with downstream fabrication clustering in Israel, the Netherlands, and India. Raw material dependencies center on corrosion-resistant polypropylene resin, elastomer seal compounds, and electrodialysis membrane substrates. Single-source vulnerability runs through Middle Eastern propylene corridors exposed to regional logistics chokepoints. Distribution runs through direct manufacturer relationships with irrigation district managers and cooperative procurement consortia, bypassing traditional dealer networks in Almería and Riverina regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polypropylene resin sourcing and captive nutrient solution formulation capacity represents the dominant vertical-integration race, with incumbents securing feedstock buffers and subscription revenue streams against polymer price volatility.
For Market Incumbents: Acquire polypropylene resin compounding assets to buffer propylene monomer volatility and anchor margin control. Secure ISO 9261 certification pipelines for 18-24 month validation timelines that delay competitive response windows. Defend against membrane-based injector substitution by integrating electrodialysis R&D partnerships with Wageningen University protocol licensing. For New Entrants and Emerging Players: Enter via sensor-to-cloud convergence platforms that displace upfront hardware sales with per-hectare subscription models in Brazilian citrus and Australian Riverina cooperative clusters. Target India's PLI scheme beneficiary status for manufacturing scale-up serving Maharashtra smallholder procurement. White-space penetration concentrates on pH-EC sensor calibration service networks where skilled technician scarcity in California's Central Valley creates capacity gaps. For Investors and Strategic Acquirers: The window for entry favors precision-agriculture specialists with membrane technology IP and direct cooperative channel relationships over legacy drip-irrigation hardware portfolios. Long-term viability hinges on nutrient-recipe standardization licensing moats and recurring software revenue attachment rates. Monitor EU F-Gas Regulation phasedown acceleration as inflection indicator for synchronized climate-control and fertigation retrofit demand in Dutch and Spanish protected-cropping municipalities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply buffers margin compression from propylene monomer volatility in Middle Eastern corridors. |
| Membrane Technology R&D Partnership | Electrodialysis unit development satisfies Dutch tomato producer demand for ppm-level nutrient precision in Westland. |
| Cooperative Procurement Channel Capture | Direct manufacturer relationships with Almería and Riverina aggregators displace traditional dealer network economics. |
| Sensor-to-Cloud Platform Launch | LoRaWAN-enabled subscription models displace upfront hardware sales in Brazilian citrus grove precision agriculture. |
| REACH Compliance Certification Investment | Elastomer seal reformulation ahead of 2030 phthalate restrictions secures EU export market access for South Asian manufacturers. |
Methodological Framework
Document review covered customs trade data for polypropylene resin flows, EPA FIFRA enforcement records, EU ECHA REACH substitution timelines, and ISO 9261 certification registries, complemented by interviews with irrigation district managers in Australia's Murray-Darling Basin, greenhouse operations directors in Almería and Westland municipalities, polymeric emitter manufacturing plant engineers in Gujarat, and precision agriculture R&D leads at Wageningen University and UC Davis. Secondary validation drew from agricultural equipment customs classifications, SEC 10-K filings of listed irrigation equipment manufacturers, and irrigation district capital expenditure disclosures. Bottom-up equipment shipment tallies and top-down nutrient solution consumption estimates were triangulated against regional agricultural water use statistics.
Installed base projections and revenue forecasts across the analysis window reflect segmentation by product type, end-user concentration, application water-stress intensity, and distribution channel control. The modeling framework incorporated drip-irrigation convergence retrofit rates, EU F-Gas Regulation phasedown compliance timelines, and PLI scheme incentive absorption curves as industry-specific demand drivers. CAGRs were derived from equipment replacement cycle compression patterns and subscription revenue migration trajectories in cooperative procurement clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene monomer supply disruption scenarios, REACH polymer substitution acceleration, and groundwater protection statute tightening in EPA and TGA-equivalent jurisdictions. Forecasts reflect documented assumptions on irrigation infrastructure maturity curves and skilled technician training pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Europe Feed Antibiotics Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
China Feed Enzymes Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
Plant Activator Market