
 China Feed Enzymes Market | 2026-2036
China Feed Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
China Feed Enzymes Market Analysis
Buyer concentration among large-scale poultry integrators is rebalancing procurement leverage across the China feed enzymes supply base. Novonesis A/S leverages its fermentation technology leadership to sustain premium positioning in phytase supply. DSM Nutritional Products AG anchors its presence through integrated premix-to-enzyme bundling with provincial feed compounders. Angel Yeast competes on cost-engineered cellulase variants tailored to corn-wheat blended rations prevalent in North China.
Feed enzymes are protein-based biocatalysts, typically produced via submerged fermentation of fungal or bacterial strains, that hydrolyze anti-nutritional factors in cereal-based diets to release digestible phosphorus, amino acids, and energy. Their primary commercial purpose is to reduce feed formulation costs while maintaining animal performance under nutrient-reduced diet regimes. Phytase dominates value capture due to mandatory phosphorus reduction protocols, while protease registers the fastest structural expansion as low-protein diet formulations gain technical validation across broiler operations. Liquid form factors command margin premiums in automated dosing systems at megafarm feed mills, whereas powder formulations occupy cost-sensitive distributor channels serving mid-tier swine producers.
China's Ministry of Agriculture and Rural Affairs enforces feed additive registration under the Feed and Feed Additive Regulations, compelling foreign suppliers to complete domestic efficacy trials before market entry. The National Health Commission and SAMR jointly monitor enzyme production facility compliance with food-grade hygiene standards that cascade into feed-grade manufacturing audits. GB standards for enzyme activity assays create technical barriers for uncertified imports. Stakeholders must monitor provincial environmental bureau enforcement of livestock wastewater phosphorus limits, as these local rules directly tighten or relax the economic case for phytase inclusion rates.
Market Dynamics
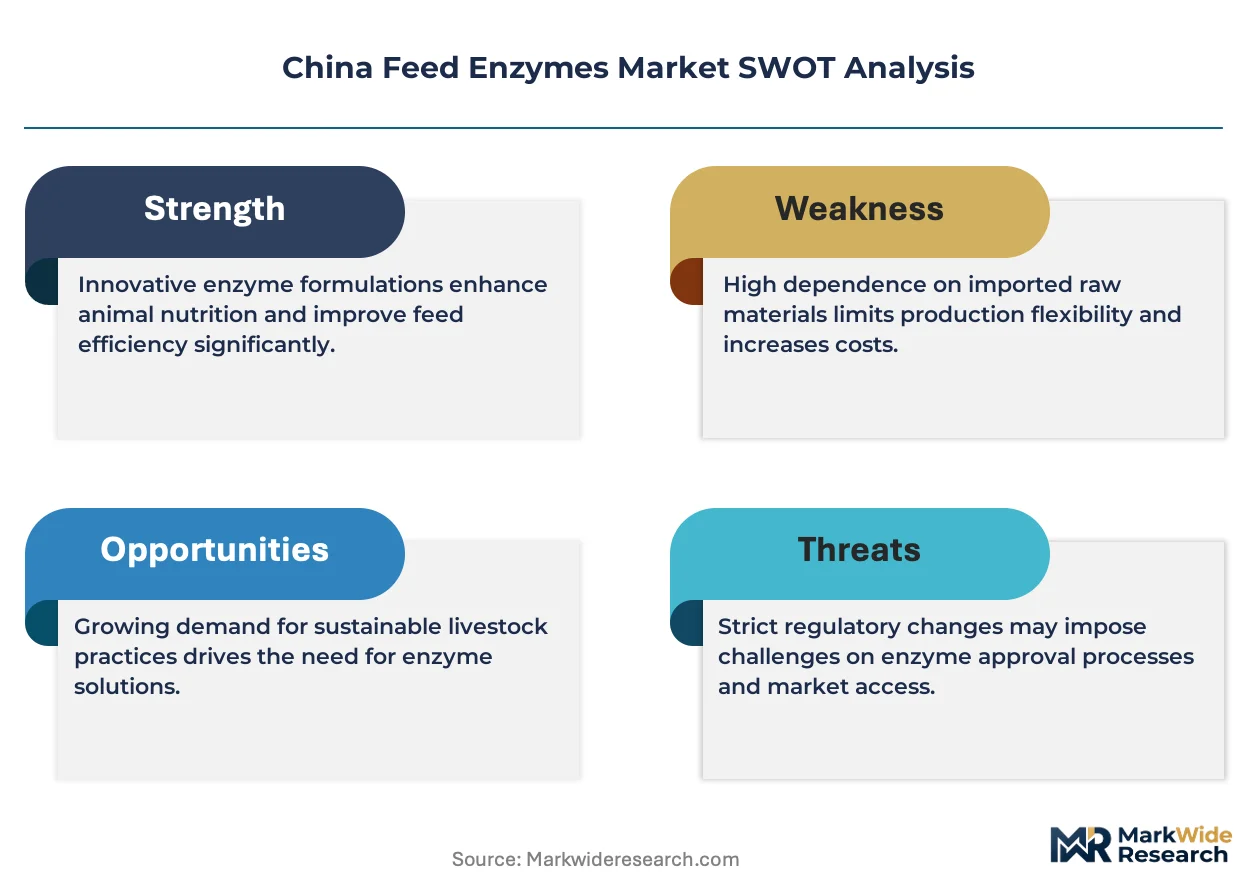
China's Ministry of Agriculture and Rural Affairs is tightening feed additive registration protocols, forcing foreign suppliers into lengthy domestic efficacy trials while provincial environmental bureaus enforce livestock wastewater phosphorus limits that directly determine phytase inclusion economics.
Growth Catalysts
- Phytase mandate cascade:Shandong Province environmental bureaus enforce wastewater phosphorus discharge limits that compel concentrated animal feeding operations to elevate enzyme dosing rates.
- Low-protein diet validation:Broiler integrators accelerate protease adoption as amino acid matrix formulations demonstrate feed conversion ratio improvements in commercial scale trials.
- Fermentation capacity expansion:Domestic submerged fermentation infrastructure clusters near feed milling hubs in North China, compressing enzyme delivery lead times.
Market Restraints
- GB standards compliance cost:Foreign suppliers face technical barriers from mandatory enzyme activity assay certifications under national standards that require dedicated analytical laboratories.
- Corn-wheat price volatility:Feed compounders experience margin compression from cereal input fluctuations that destabilize enzyme ROI calculations in blended rations.
- Single-province supply concentration:Shandong Province hosts disproportionate fermentation capacity, creating geographic vulnerability to regional logistics disruptions.
Strategic Opportunities
- Henan Province penetration:Underdeveloped swine enzyme adoption in Central China feed mills offers whitespace for cellulase variants optimized to local corn-soy formulations.
- Liquid dosing automation:Megafarm feed mills upgrade to automated enzyme injection systems that command premium form factor pricing and lock in supplier relationships.
- SAMR food-grade hygiene bridge:Dual-use fermentation facilities certified under National Health Commission standards can pivot capacity toward feed-grade production with reduced compliance overhead.
Industry Challenges
- Fermentation strain IP fragmentation:Licensing complexity around proprietary bacterial and fungal host organisms creates supplier negotiation friction and royalty stacking.
- Feed mill legacy system integration:Mid-tier swine producers operate powder-handling equipment incompatible with liquid enzyme dosing infrastructure, forcing costly retrofit decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Feed Enzymes Market |
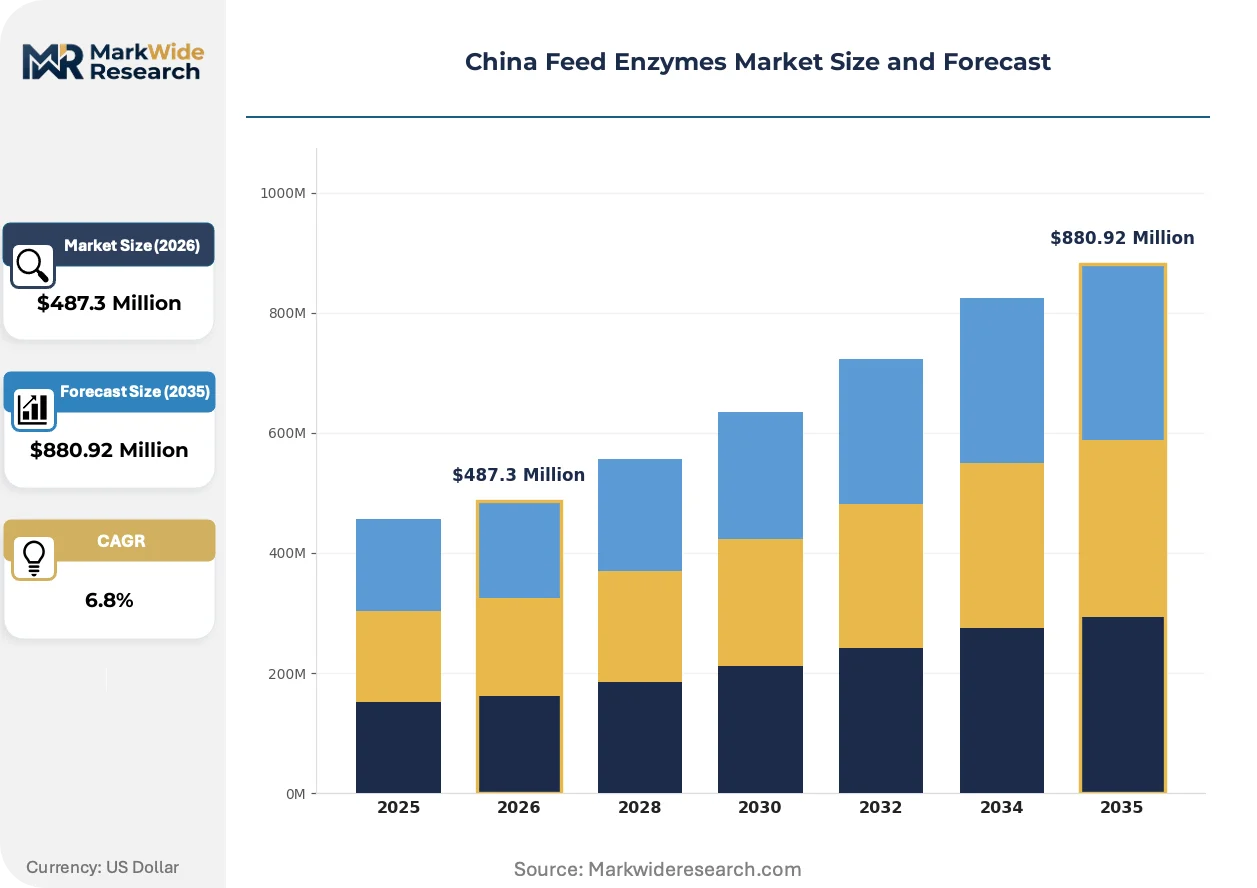
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Phytase, Amylase, Protease, Cellulase Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Microencapsulated Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | IFF (Danisco Animal Nutrition), Novonesis A/S, Adisseo, Kemin Industries, Angel Yeast, DSM Nutritional Products AG, Kerry Group PLC, BASF SE, Elanco Animal Health Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Feed Enzymes Market Emerging Trajectories
Enzyme formulation science is pivoting toward precision-delivery systems that match biocatalyst activity profiles to specific anti-nutritional factor loads in regional cereal blends, compressing the gap between laboratory efficacy and commercial performance.
Multi-enzyme complexes is converging with site-specific protease variants that target residual protein matrices in heat-processed soybean meal. Large-scale poultry integrators in Shandong Province deploy these formulations at commercial scale within eighteen months of technical validation. This convergence is compressing the traditional single-enzyme procurement model into bundled biocatalyst service contracts.
GB standards for enzyme activity assays are tightening assay precision requirements under Ministry of Agriculture and Rural Affairs enforcement protocols. Foreign suppliers must establish domestic analytical laboratories or partner with certified third-party testing facilities to maintain registration validity. Phytase suppliers with existing GB certification infrastructure capture accelerated registration timelines for portfolio extensions.
Buyer concentration among megafarm integrators is consolidating procurement decision authority into technical teams that specify enzyme activity units per ton rather than branded product volumes. Provincial feed compounders in North China respond by unbundling technical service from product supply, shifting margin capture toward formulation consulting. This pattern concentrates most visibly in Shandong Province where integrated poultry operations own captive feed milling capacity.
China Feed Enzymes Market Segmentation
Feed enzyme procurement in China diverges sharply across customer scale and automation maturity. Large integrators specify activity units per ton while mid-tier compounders prioritize cost-per-dose simplicity, fragmenting supplier engagement models.
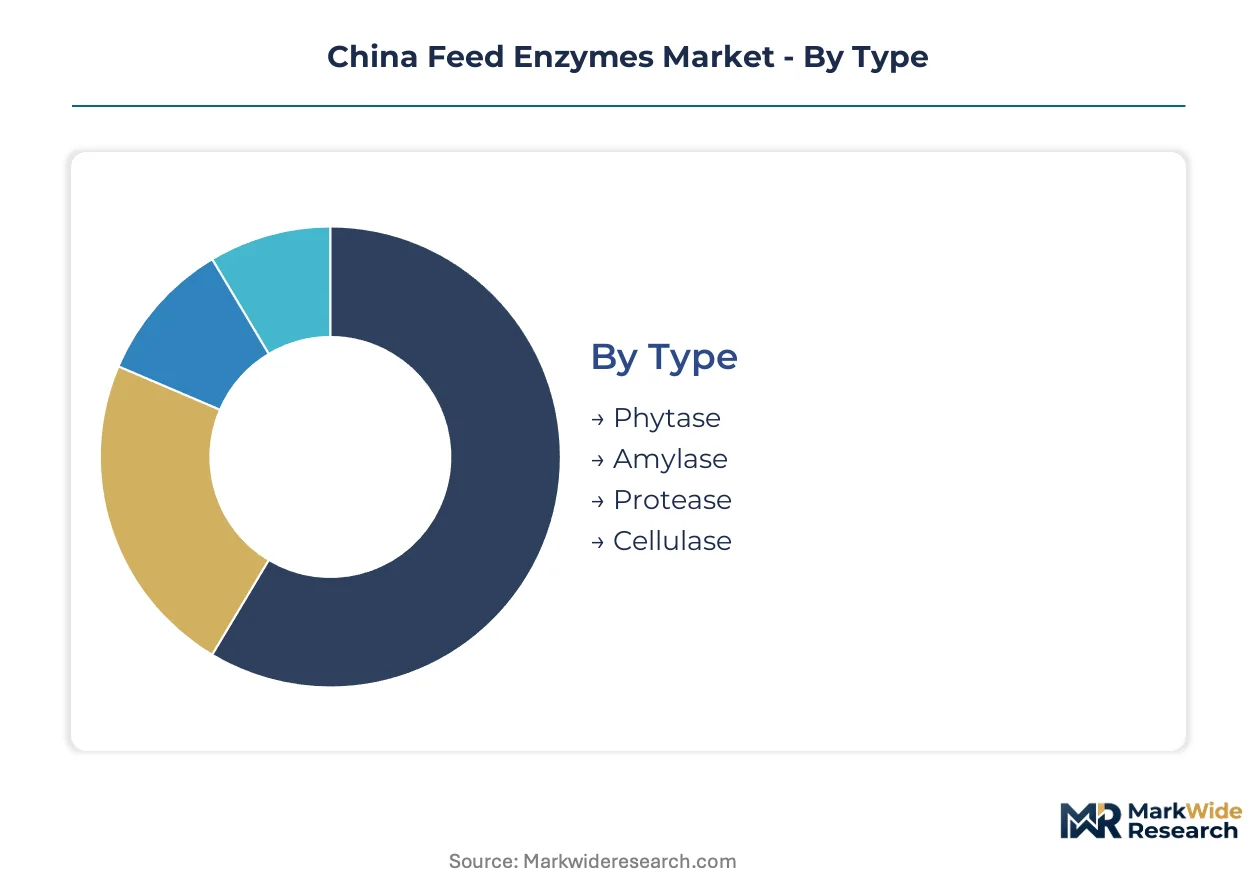
Type:
Buyers differentiate by phosphorus reduction mandates versus amino acid optimization priorities.
- Phytase:This phosphorus-releasing biocatalyst dominates value capture due to mandatory discharge limits enforced by Shandong Province environmental bureaus. Concentrated animal feeding operations in North China elevate inclusion rates to comply with wastewater phosphorus caps.
- Protease:Amino acid-targeting variants are expanding most quickly as broiler integrators validate low-protein diet formulations. Technical teams at megafarm operations specify protease activity matrices to maintain feed conversion ratios under reduced crude protein regimes.
- Amylase:Starch-hydrolyzing enzymes support energy release in corn-wheat blended rations prevalent across North China feed mills.
- Cellulase:Fiber-degrading formulations from Angel Yeast target cost-engineered applications in corn-soy diets for Central China swine producers.
Volume sits with phytase; growth tilts toward protease.
Application:
Species-specific digestive physiology dictates enzyme specification complexity and dosing precision requirements.
- Poultry:Broiler integrators deploy multi-enzyme complexes at commercial scale within compressed validation timelines. Shandong Province operations lead adoption of site-specific protease variants targeting residual protein in heat-processed soybean meal.
- Swine:Sow and grower operations in Henan Province represent whitespace opportunity for cellulase variants optimized to local corn-soy formulations.
- Ruminants:Fiber-digesting enzyme applications concentrate in dairy regions where forage quality variability demands adaptive biocatalyst dosing.
- Aquaculture:Species-specific protease requirements for carp and shrimp feed create formulation complexity that limits supplier penetration.
Procurement scale concentrates in poultry; technical validation investment favors swine.
Form:
Automation infrastructure maturity separates megafarm integrators from distributor-dependent mid-tier producers.
- Liquid:Automated dosing systems at megafarm feed mills command margin premiums through precise injection capabilities. DSM Nutritional Products AG anchors relationships via integrated premix-to-enzyme bundling with liquid-compatible infrastructure.
- Powder:Cost-sensitive channels serving mid-tier swine producers rely on legacy handling equipment incompatible with liquid systems. Novonesis A/S sustains powder presence through fermentation technology cost advantages.
- Granular:Flow-enhanced formulations reduce dust exposure in manual handling environments common at smaller compounders.
- Microencapsulated:Heat-stable variants protect activity through pelleting temperatures required by high-volume feed mills.
Margin capture clusters in liquid; volume retention depends on powder.
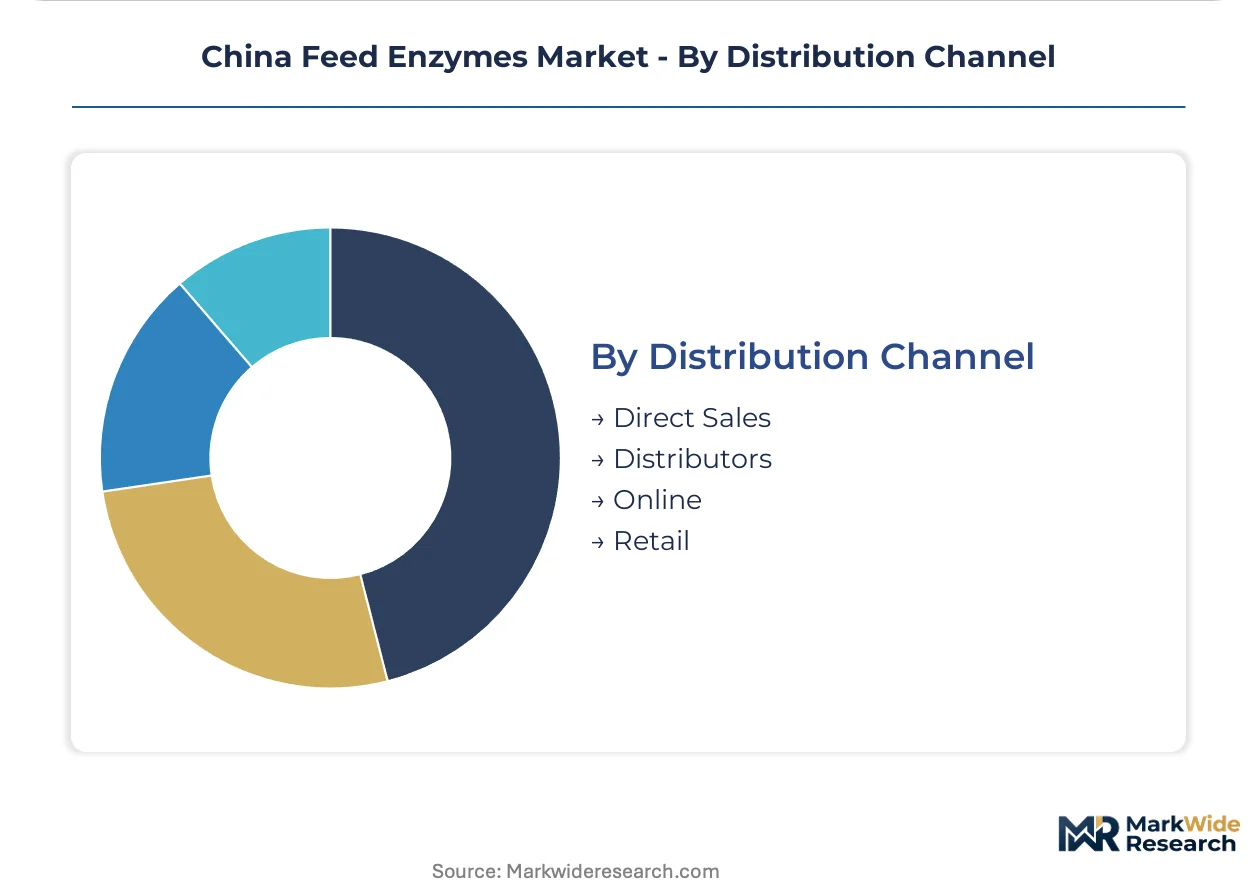
Distribution Channel:
Technical service requirements and order scale determine channel selection across buyer tiers.
- Direct Sales:Large-scale poultry integrators consolidate procurement authority into technical teams that specify activity units directly with fermentation specialists. Novonesis A/S and DSM Nutritional Products AG maintain dedicated account structures for these relationships.
- Distributors:Provincial feed compounders in North China access enzyme supply through regional distributors that bundle technical consulting with product delivery.
- Online:Emerging procurement channels serve smaller livestock operations with standardized product specifications and reduced service overhead.
- Retail:Limited penetration concentrates in veterinary supply points serving backyard producer segments.
Relationship value concentrates in direct sales; geographic coverage expands through distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration among large-scale poultry integrators is rebalancing procurement leverage across provincial supply bases. Provincial environmental bureaus enforce wastewater phosphorus limits that directly determine phytase inclusion economics in concentrated animal feeding operations.
Shandong Province
Concentrated animal feeding operations cluster near feed milling infrastructure in Shandong, driving elevated enzyme dosing rates. The Ministry of Agriculture and Rural Affairs enforces feed additive registration protocols that compel domestic efficacy trials. Qingdao and Yantai host fermentation capacity expansions that compress delivery lead times to poultry integrators.
Henan Province
Underdeveloped swine enzyme adoption in Central China feed mills creates whitespace for cellulase variants optimized to local corn-soy formulations. SAMR monitors production facility compliance with food-grade hygiene standards that cascade into feed-grade manufacturing audits. Zhengzhou-based compounders represent the primary demand concentration for cost-engineered enzyme applications.
Jiangsu Province
Yangtze River Delta feed mills deploy automated liquid dosing systems that command premium form factor pricing. GB standards for enzyme activity assays create technical barriers for uncertified imports entering through Shanghai port infrastructure. Nanjing and Suzhou concentrate technical procurement teams that specify activity units per ton rather than branded product volumes.
Guangdong Province
Pearl River Delta aquaculture operations generate species-specific protease requirements for carp and shrimp feed that limit supplier penetration. Provincial environmental bureaus enforce livestock wastewater phosphorus limits that tighten the economic case for phytase inclusion. Guangzhou serves as the distribution hub for enzyme supply reaching Southeast Asian export markets.
Sichuan-Chongqing Region
Ruminant enzyme applications concentrate in dairy regions where forage quality variability demands adaptive biocatalyst dosing. The National Health Commission jointly monitors enzyme production facility compliance with hygiene standards. Chengdu anchors technical service capabilities for cellulase formulations targeting regional fiber-degradation requirements.
China Feed Enzymes Market Vendor Landscape
Danish and Dutch producers anchor the premium tier; Chinese domestic specialists hold cost-engineered positions. The vendor base separates into fermentation technology leaders, integrated nutrition bundlers, and regional cost optimizers. Three strategic archetypes dominate: multinational biocatalyst innovators, premix-to-enzyme integrators, and domestic fermentation scale players. Competitive moves concentrate on GB standards compliance infrastructure and liquid dosing automation partnerships.
Among fermentation technology leaders, Novonesis A/S and DSM Nutritional Products AG occupy positions that exemplify premium-tier supply relationships. Angel Yeast represents the domestic specialist archetype, sitting within cost-engineered product positioning. These three companies anchor the competitive structure that other participants must navigate through registration compliance, technical service capabilities, or geographic proximity advantages.
| Leading Market Players |
|---|
| IFF (Danisco Animal Nutrition) |
| Novonesis A/S |
| Adisseo |
| Kemin Industries |
| Angel Yeast |
| DSM Nutritional Products AG |
| Kerry Group PLC |
| BASF SE |
| Elanco Animal Health Inc. |
| Others |
Supply Flow & Price Mechanics
Premium-mid-economy pricing differentiation across phytase, protease, and cellulase variants manifests in divergent supply chain configurations, where GB-certified fermentation capacity commands logistics priority from Shandong Province integrators while uncertified imports face extended analytical laboratory qualification timelines at provincial feed mills.
Pricing Analysis
Volume concentrates in powder phytase formulations serving cost-sensitive mid-tier swine compounders, while margin capture clusters in liquid multi-enzyme complexes bundled with automated dosing infrastructure at megafarm poultry operations. Price differentiation rests on GB standards compliance certification and fermentation technology tier, with foreign suppliers absorbing analytical laboratory overhead to maintain registration validity. Cost compression in standard-grade cellulase is intensifying as Angel Yeast expands submerged fermentation scale, eroding legacy supplier positioning. Mid-tier swine producers exhibit highest price sensitivity due to legacy powder-handling equipment retrofit costs, whereas Shandong poultry integrators prioritize activity unit precision over per-dose expenditure.
Supply Chain Analysis
Dual-sourcing requirements from large-scale poultry integrators mandate multi-supplier qualification across domestic fermentation specialists and multinational biocatalyst innovators, fragmenting procurement authority between technical specification teams and provincial compounder networks. Geographic supply concentration centers on China, with Denmark and the Netherlands anchoring premium-tier import flows. Raw material dependencies include fungal and bacterial host strains, specialized fermentation media, and activity assay reagents. Single-province vulnerability persists as Shandong hosts disproportionate fermentation capacity, exposing buyers to regional logistics disruption. Distribution runs through direct sales channels for megafarm integrators and provincial distributor networks for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's feed enzymes sector is consolidating around GB standards compliance infrastructure, with Ministry of Agriculture and Rural Affairs registration protocols forcing weaker players into exit or acquisition trajectories.
For Market Incumbents: Hedge against fermentation strain IP fragmentation by securing proprietary bacterial host organism licenses or exclusive royalty arrangements with domestic research institutes. Expand analytical laboratory capacity in Shandong Province to capture accelerated registration timelines for protease portfolio extensions, defending against DSM Nutritional Products AG's integrated premix-to-enzyme bundling.
For New Entrants and Emerging Players: Direct-to-feed-mill digital procurement platforms offer whitespace penetration into Henan Province swine operations, where cellulase adoption remains underdeveloped relative to Shandong poultry density. Target Zhengzhou-based compounders with cost-engineered corn-soy optimized variants, leveraging online channels to bypass established distributor relationships that lock in incumbent supply.
For Investors and Strategic Acquirers: Re-rating potential sits with dual-use fermentation facilities certified under National Health Commission food-grade hygiene standards given SAMR regulatory bridge opportunities into feed-grade production. Monitor provincial environmental bureau enforcement of livestock wastewater phosphorus limits as the inflection indicator for phytase inclusion rate acceleration across North China concentrated animal feeding operations.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Standards Analytical Laboratory Investment | Domestic certification infrastructure compresses registration timelines for foreign suppliers under Ministry of Agriculture and Rural Affairs protocols. |
| Liquid Dosing Automation Partnership | Megafarm feed mill upgrades lock in supplier relationships through integrated premix-to-enzyme bundling with DSM Nutritional Products AG. |
| Henan Province Distribution Expansion | Central China swine whitespace offers cellulase volume growth outside Shandong poultry concentration. |
| Fermentation Strain IP Licensing | Proprietary bacterial host organism access reduces royalty stacking friction in multi-enzyme complex formulations. |
| Dual-Use Facility Hygiene Certification | National Health Commission food-grade standards enable pivot capacity toward feed-grade production with reduced SAMR compliance overhead. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across fermentation technology directors, provincial feed compounder procurement leads, Ministry of Agriculture and Rural Affairs registration specialists, and poultry integrator technical teams. Bottom-up enzyme activity unit demand modeling converged with top-down feed milling capacity analysis across Shandong, Henan, Jiangsu, Guangdong, and Sichuan-Chongqing regions.
Granularity-level modeling operated at province-formulation-automation tier intersections, with phytase, protease, amylase, and cellulase variants tracked separately across liquid, powder, granular, and microencapsulated form factors. CAGRs were derived from activity unit volume trajectories and value-per-activity-unit pricing trends across the analysis window. Forecast inputs incorporated Shandong Province environmental bureau phosphorus limit enforcement intensity and low-protein diet formulation adoption curves among broiler integrators.
The model holds under sustained GB standards enforcement and stable cereal input price regimes; deviation in corn-wheat price volatility or Ministry of Agriculture and Rural Affairs registration protocol acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Field Marking Paint Market
Agricultural Chemicals
United States Feed Enzymes Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
Europe Feed Enzymes Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
Amino Acid for Agriculture Market