
 China Castor Oil Market | 2026-2036
China Castor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
China Castor Oil Market Intelligence
Biocatalytic refining is reshaping castor oil processing economics in China, enabling lower-temperature epoxidation and reduced solvent waste. Jayant Agro-Organics Limited leverages its Gujarat-based crushing infrastructure to sustain raw material flows into Chinese derivative markets. Arkema anchors high-performance polyamide 11 production using sebacic acid derived from castor oil feedstock. Adani Wilmar Limited competes through integrated agri-commodity sourcing that extends cost advantages across the oleochemical value chain.
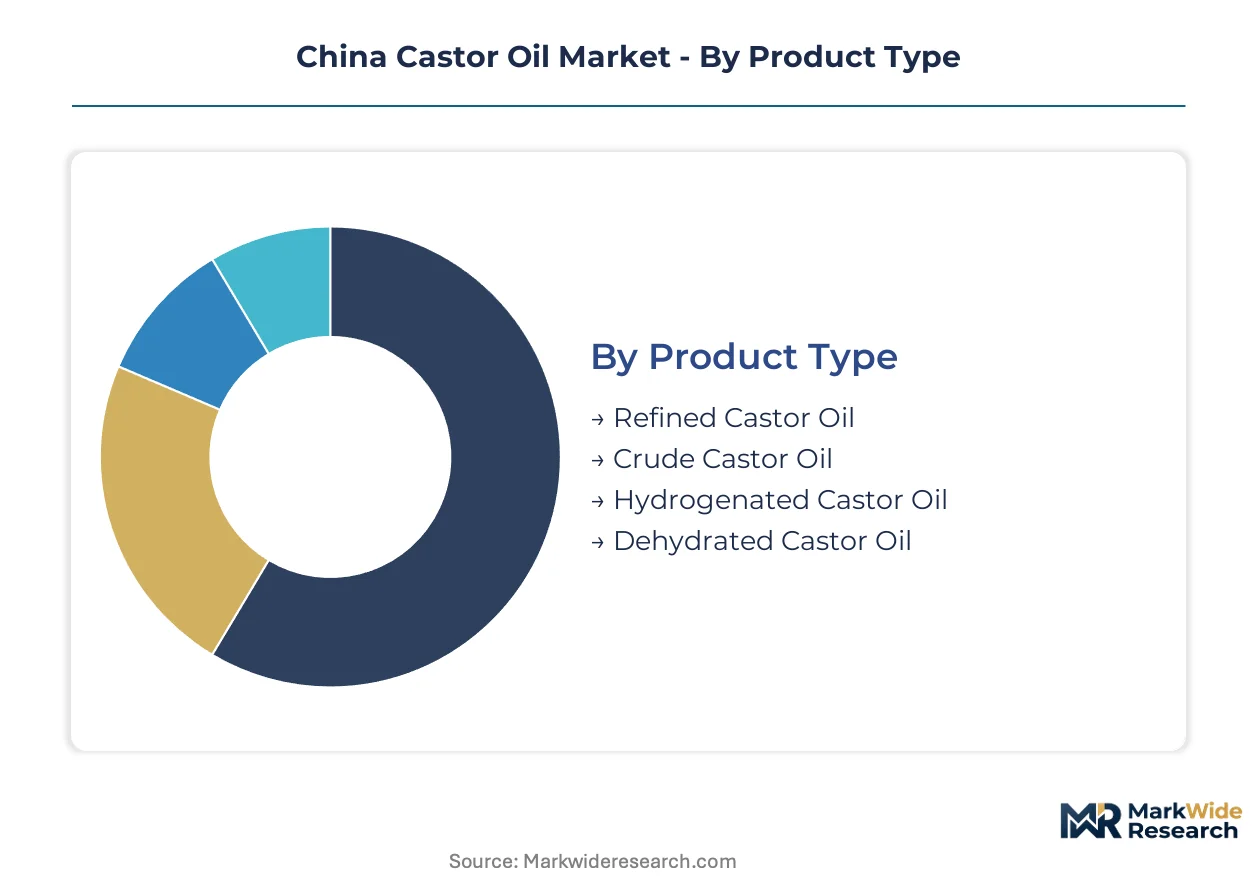
Castor oil is a triglyceride composed of approximately 90% ricinoleic acid, extracted from Ricinus communis seeds through mechanical pressing or solvent extraction followed by degumming and bleaching. Its hydroxyl functionality and high viscosity index suit lubricant formulations, cosmetic emollients, and polyurethane intermediates. Refined castor oil dominates value capture in personal care applications, where NMPA cosmetic ingredient filings require pharmaceutical-grade purity. Hydrogenated castor oil occupies the fastest-expanding segment as automotive sealant manufacturers adopt bio-based plasticizers to meet MIIT new energy vehicle material guidelines. Crude castor oil remains concentrated in chemical industry procurement channels, where wholesale distributors in Zhejiang province control bulk arbitrage.
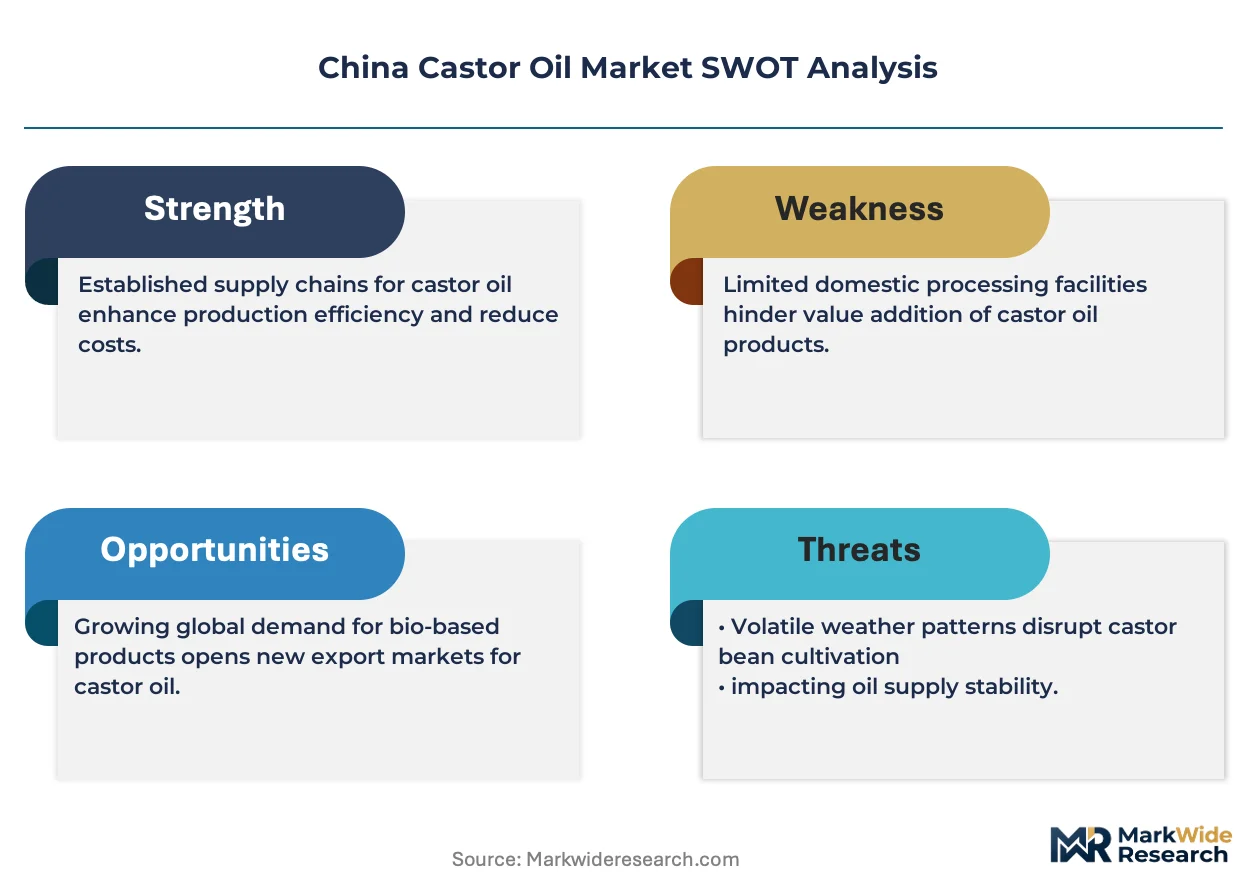
MIIT's dual carbon goals are forcing oleochemical processors to document Scope 1 and 2 emissions, while SAMR enforces GB/T standards on castor oil acid value and moisture content that determine market access. The country's national pharmaceutical regulator evaluates ricinoleic acid derivatives for excipient status, creating compliance tiers that separate export-oriented refiners from domestic commodity suppliers. Stakeholders must monitor how Shandong and Jiangsu provincial environmental bureaus implement MEE wastewater discharge limits on castor meal processing residues, as these rules will determine which integrated crushers can maintain operating permits without capital-intensive effluent retrofit.
Market Dynamics
MIIT's dual carbon goals are forcing oleochemical processors to document Scope 1 and 2 emissions, while SAMR enforces GB/T standards on castor oil acid value and moisture content that determine market access.
Growth Catalysts
- NMPA cosmetic ingredient filings:Pharmaceutical-grade purity requirements for personal care applications are elevating product specifications and expanding addressable market for refined grades.
- Biocatalytic refining:Lower-temperature epoxidation processes are reducing solvent waste and improving processing economics across Jiangsu and Zhejiang chemical clusters.
- New energy vehicle material guidelines:MIIT mandates for bio-based plasticizers in automotive sealants are accelerating hydrogenated castor oil adoption.
Market Restraints
- Raw material import dependency:Crushing infrastructure concentration in Gujarat creates supply vulnerability for Chinese derivative manufacturers.
- Sebacic acid production bottlenecks:Limited domestic capacity for this polyamide 11 intermediate constrains downstream high-performance polymer expansion.
- Castor meal processing residues:MEE wastewater discharge limits in Shandong and Jiangsu provinces threaten operating permits for integrated crushers.
Strategic Opportunities
- Domestic natural ingredient portfolios:Personal care brands expanding formulations create demand pull for pharmaceutical-grade refined castor oil.
- Automotive sealant plasticizer substitution:Bio-based alternatives to petroleum-derived plasticizers open volume opportunities in EV supply chains.
- Polyurethane intermediate diversification:Ricinoleic acid derivatives for coating and adhesive applications represent underdeveloped downstream chemistry.
Industry Challenges
- Scope 1 and 2 emissions documentation:MIIT carbon accounting requirements demand new measurement infrastructure and reporting capabilities.
- GB/T certification timelines:SAMR acid value and moisture content testing creates compliance delays for market entry.
- Excipient status evaluation complexity:National pharmaceutical regulator ricinoleic acid derivative assessments separate export-oriented refiners from domestic commodity suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Castor Oil Market |
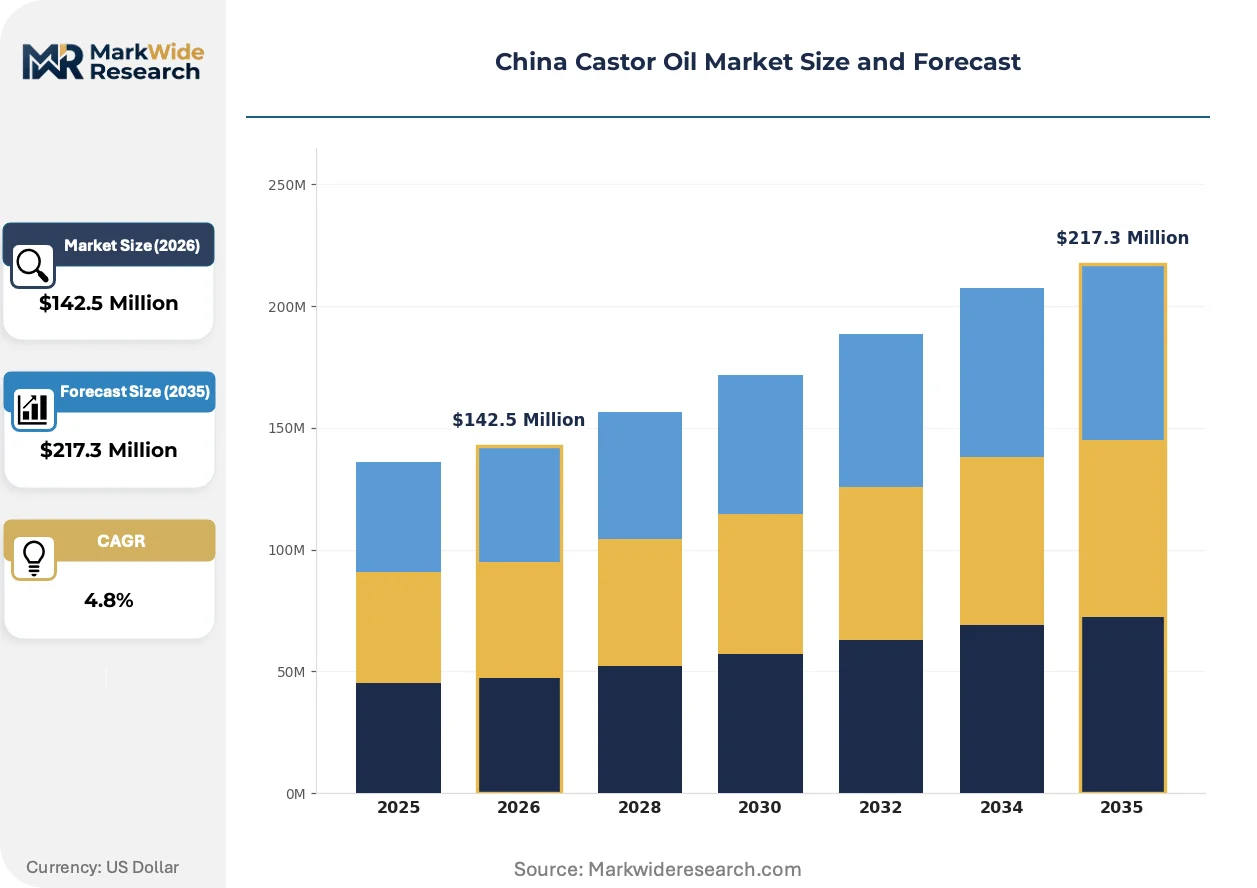
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Castor Oil, Crude Castor Oil, Hydrogenated Castor Oil, Dehydrated Castor Oil Application: Cosmetics, Pharmaceuticals, Lubricants, Biofuels Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Direct Sales End User: Personal Care, Automotive, Chemical Industry, Agriculture |
| Companies Covered | ITOH Oil Chemicals Co Ltd, N.K. Proteins Limited, Adani Wilmar Limited, Thai Castor Oil Industries Co Ltd, Taj Agro Products, Jayant Agro-Organics Limited, Ambuja Solvex Pvt Ltd, Arkema, RPK Agrotech Exports Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Castor Oil Market Strategic Shifts & Innovations
Biocatalytic processes and regulatory carbon accounting are restructuring how castor oil moves from crushing through derivative production, with technology and compliance now determining competitive position.
Enzymatic epoxidation systems are hybridizing traditional solvent-based refining by enabling ambient-temperature processing with 40-60% energy reduction. Chemical processors in Zhejiang province are retrofitting batch reactors with immobilized lipase configurations. This hybridizing approach is compressing capital requirements for mid-scale refiners while meeting MEE effluent standards.
MIIT's dual carbon implementation rules now require documented Scope 1 and 2 emissions across all oleochemical processing above 10,000 tons annual throughput. SAMR has synchronized GB/T castor oil quality standards with carbon intensity disclosures. Hydrogenated castor oil producers serving automotive sealant manufacturers face the steepest compliance curves.
Brand procurement teams are consolidating supplier bases around certified pharmaceutical-grade refiners capable of NMPA cosmetic ingredient filing support. Wholesale distributors in Zhejiang province still control crude oil arbitrage but are losing share to direct mill relationships. This concentration is most visible in personal care supply chains where domestic brands now require batch-level purity documentation.
China Castor Oil Market Segmentation
Segmentation in China's castor oil market reveals how regulatory pressure and end-use specifications fragment supply chains. Product grades, application requirements, and channel economics create distinct competitive arenas with diverging margin profiles.
Product Type:
After-sales technical support intensity varies dramatically across product grades, with pharmaceutical and automotive applications demanding batch-level traceability and regulatory filing assistance that commodity grades do not require.
- Refined Castor Oil:Pharmaceutical-grade purity specifications dominate this segment, with hydroxyl functionality and low acid value meeting NMPA cosmetic ingredient filing requirements. Demand concentrates in Jiangsu and Zhejiang personal care manufacturing clusters, where domestic brands now require documentation support previously expected only from export-oriented suppliers. Refined castor oil holds the largest share; momentum sits with hydrogenated grades.
- Hydrogenated Castor Oil:Solid wax-like consistency at room temperature suits automotive sealant formulations seeking bio-based plasticizer alternatives under MIIT new energy vehicle material guidelines. Zhejiang chemical processors are retrofitting hydrogenation capacity to capture this specification tier. The segment is gaining share fastest as EV supply chains displace petroleum-derived additives.
- Crude Castor Oil:Concentrated in bulk chemical industry procurement channels where wholesale distributors in Zhejiang province control arbitrage flows to derivative manufacturers.
- Dehydrated Castor Oil:Drying oil properties serve coating and adhesive applications with constrained domestic capacity expansion due to sebacic acid production bottlenecks.
Product tiering reflects diverging compliance burdens, with refined and hydrogenated grades capturing value through certification infrastructure that commodity processors cannot replicate.
Application:
Application-driven cost structures separate high-specification formulations from bulk chemical consumption, with regulatory filing requirements creating effective price floors in cosmetic and pharmaceutical uses.
- Cosmetics:Emollient and moisturizing properties drive formulation integration, with GB standards for cosmetic raw materials and NMPA purity requirements elevating supplier qualification thresholds. Jiangsu province personal care manufacturing anchors demand as domestic brands expand natural ingredient portfolios. Cosmetics holds the largest share; steepest expansion trajectory belongs to lubricants.
- Lubricants:High viscosity index and thermal stability suit industrial and automotive formulations, with ricinoleic acid derivatives displacing petroleum-based alternatives in temperature-sensitive applications.
- Pharmaceuticals:Excipient status evaluation by national pharmaceutical regulators creates compliance tiers separating export-oriented refiners from domestic commodity suppliers.
- Biofuels:Castor oil's non-edible status and high cetane number position it as a biodiesel feedstock, though domestic crushing infrastructure constraints limit scale.
Application segmentation concentrates margin capture in regulated end-uses where certification timelines and purity documentation create defendable supplier positions.
Distribution Channel:
Channel economics reflect buyer scale and specification complexity, with direct relationships displacing intermediaries where batch documentation and technical support requirements intensify.
- Wholesale Distributors:Zhejiang province trading houses control crude castor oil arbitrage and bulk chemical industry flows, though losing share to direct mill relationships in personal care supply chains.
- Direct Sales:Pharmaceutical-grade refiners serving NMPA filing requirements consolidate brand procurement relationships through batch-level purity documentation and regulatory support capabilities.
- Online Retail:Small-volume personal care ingredient sourcing for independent formulators and regional cosmetics manufacturers.
- Supermarkets:Limited castor oil presence in consumer-packaged formats, primarily as carrier oil or traditional medicine applications.
Channel structure is concentrating around direct technical relationships in regulated applications while wholesale distributors retain commodity bulk flows.
End User:
End-user maturity and supply concentration determine pricing power allocation, with automotive and personal care sectors consolidating supplier bases around certified processors.
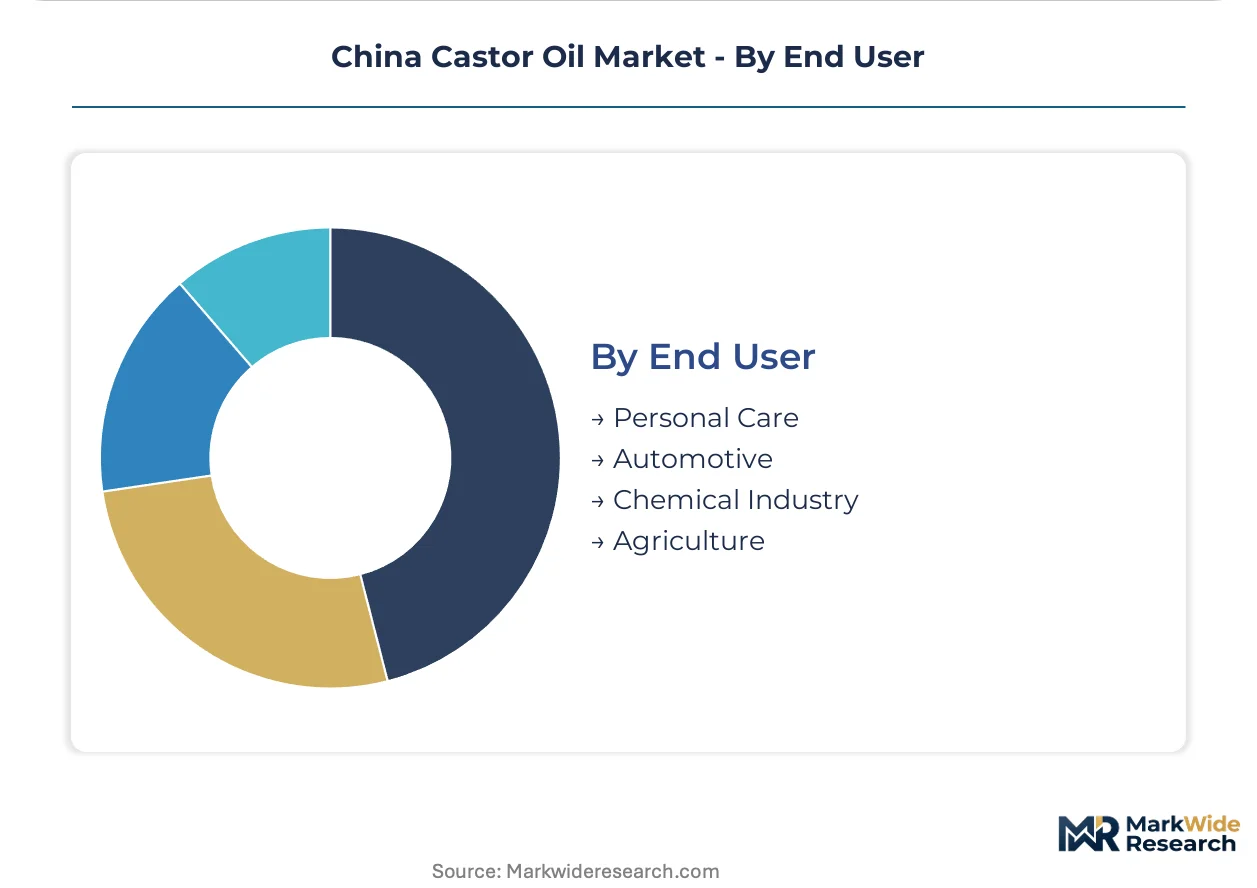
- Personal Care:Domestic brand expansion into natural ingredient portfolios drives pharmaceutical-grade refined castor oil demand, with NMPA filing support now a standard procurement requirement.
- Automotive:MIIT bio-based plasticizer mandates for new energy vehicle sealants accelerate hydrogenated castor oil qualification programs among tier suppliers.
- Chemical Industry:Derivative manufacturers in Jiangsu and Zhejiang provinces anchor downstream polyurethane intermediate and sebacic acid production.
- Agriculture:Castor meal processing for organic fertilizer applications faces MEE wastewater discharge limits in Shandong and Jiangsu provinces.
End-user segmentation concentrates value capture in regulated manufacturing sectors with documentation requirements that commodity processors cannot satisfy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat-based crushing infrastructure sustains raw material flows into Chinese derivative markets, with Jayant Agro-Organics Limited anchoring supply corridors that feed Jiangsu and Zhejiang chemical clusters.
Jiangsu Province
Personal care manufacturing clusters anchor refined castor oil demand as domestic brands expand natural ingredient portfolios. SAMR enforces GB/T standards on acid value and moisture content that determine market access for cosmetic raw material suppliers. Nantong and Taizhou chemical parks host polyurethane intermediate processors sourcing pharmaceutical-grade feedstock.
Zhejiang Province
Wholesale distributors control crude castor oil arbitrage flows to derivative manufacturers while losing share to direct mill relationships in regulated applications. MEE wastewater discharge limits force retrofit decisions among integrated crushers operating near Hangzhou Bay. Wenzhou and Ningbo processors are retrofitting hydrogenation capacity to capture automotive sealant specifications.
Shandong Province
Castor meal processing for organic fertilizer applications faces intensifying environmental scrutiny from provincial environmental bureaus implementing MEE effluent standards. Qingdao and Yantai oleochemical processors document Scope 1 and 2 emissions under MIIT dual carbon implementation rules. Limited domestic sebacic acid capacity constrains downstream polyamide 11 expansion.
Guangdong Province
Pearl River Delta cosmetic formulators source refined grades requiring NMPA cosmetic ingredient filing support previously expected only from export-oriented suppliers. Shenzhen and Guangzhou personal care brands consolidate supplier bases around certified pharmaceutical-grade refiners. Batch-level purity documentation now functions as standard procurement requirement.
Sichuan-Chongqing Region
Western China chemical processing capacity expands as coastal environmental compliance costs rise. Chongqing polyurethane intermediate producers arbitrage freight differentials against Yangtze River Delta supply sources. Chengdu-based distributors serve inland personal care manufacturers with lower-specification grades.
China Castor Oil Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Wholesale distributors in Zhejiang province retain crude oil arbitrage dominance while direct mill relationships displace intermediaries in personal care supply chains. Three archetypes occupy distinct positions: integrated agri-commodity traders with upstream crushing control, pharmaceutical-grade refiners with certification infrastructure, and regional distributors with logistics arbitrage capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure NMPA filing capabilities and automotive sealant qualifications.
Among India-based agri-commodity suppliers, Jayant Agro-Organics Limited exemplifies upstream-integrated positioning through Gujarat crushing infrastructure, while N.K. Proteins Limited occupies a comparable archetype. Adani Wilmar Limited represents diversified agri-trading scale. Arkema anchors the specialty chemical tier as a France-based materials science company. ITOH Oil Chemicals Co Ltd and Thai Castor Oil Industries Co Ltd exemplify Asia-Pacific regional refiners with derivative chemistry focus.
| Leading Market Players |
|---|
| ITOH Oil Chemicals Co Ltd |
| N.K. Proteins Limited |
| Adani Wilmar Limited |
| Thai Castor Oil Industries Co Ltd |
| Taj Agro Products |
| Jayant Agro-Organics Limited |
| Ambuja Solvex Pvt Ltd |
| Arkema |
| RPK Agrotech Exports Pvt Ltd |
| Others |
Cost & Logistics Intelligence
Undercapacity in domestic sebacic acid production is driving Chinese derivative manufacturers toward premium-priced import substitution, compressing margins while elevating procurement risk premiums across Jiangsu and Zhejiang chemical clusters. This utilization gap simultaneously incentivizes backward integration into castor crushing and forces acceptance of volatile Gujarat-origin feedstock pricing.
Pricing Analysis
Biocatalytic refining technology-generation pricing gaps separate ambient-temperature enzymatic processors from legacy solvent-based operators, with energy-efficient configurations commanding 15-25% premiums. Three-tier pricing structure across pharmaceutical-grade refined, hydrogenated automotive-specification, and crude commodity grades reflects NMPA certification intensity and carbon disclosure compliance. Cost compression in hydrogenated grades is intensifying because MIIT dual carbon documentation requirements are adding measurement infrastructure overhead. Small-scale personal care formulators exhibit highest price sensitivity, while automotive sealant tier suppliers prioritize specification certainty over unit economics.
Supply Chain Analysis
Tariff exposure between India and China dominates supply chain risk calculus for Chinese derivative manufacturers dependent on Gujarat crushing infrastructure. Raw material sourcing draws from Indian seed production, Thai intermediate refining, and domestic Zhejiang hydrogenation capacity. Castor meal processing residues and ricinoleic acid derivative feedstocks rest on single-source vulnerability given limited alternative crushing geographies. Distribution runs through Zhejiang wholesale distributors for crude arbitrage and direct mill relationships for pharmaceutical-grade certified supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's castor oil market is entering cyclical recovery phase as NMPA cosmetic ingredient filing backlogs clear and automotive sealant qualification programs accelerate under MIIT bio-based plasticizer mandates.
For Market Incumbents: Pre-empt emerging biocatalytic refiners by retrofitting solvent-based capacity with immobilized lipase configurations in Nantong and Taizhou chemical parks. Secure NMPA batch-level documentation capabilities before domestic personal care brands consolidate supplier bases. Defend against hydrogenated grade margin compression by locking long-term offtake agreements with Wenzhou automotive sealant processors. For New Entrants and Emerging Players: Chongqing polyurethane intermediate production represents the most penetrable entry point, arbitraging freight differentials against Yangtze River Delta supply sources while coastal environmental compliance costs rise. Sichuan-Chongqing regional distributors serving inland personal care manufacturers with lower-specification grades offer channel acquisition targets. Go-to-market positioning should emphasize MEE wastewater discharge compliance as a differentiated permit maintenance capability. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrogenated castor oil production as automotive sealant qualification programs demand dedicated reactor configurations and carbon accounting infrastructure. Long-term viability favors pharmaceutical-grade refiners with integrated NMPA filing support and export-oriented purity documentation. Monitor Shandong provincial environmental bureau enforcement actions on castor meal processing residues as an inflection indicator for integrated crusher permit survival rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing | Gujarat seed processing control secures raw material flow stability for Zhejiang derivative manufacturers. |
| Biocatalytic Refining Retrofit | Immobilized lipase configurations in Jiangsu chemical parks reduce MEE effluent compliance costs. |
| NMPA Certification Investment | Pharmaceutical-grade documentation capabilities capture domestic personal care brand procurement consolidation. |
| Automotive Sealant Qualification | MIIT bio-based plasticizer mandates open volume opportunities in EV supply chain tier supplier programs. |
| Long-term Supply Agreement | Direct mill relationships displace Zhejiang wholesale distributors in regulated personal care applications. |
Research Approach
The analysis maps refined castor oil, hydrogenated castor oil, crude castor oil, and dehydrated castor oil segments, each validated through procurement leads at personal care manufacturers, automotive sealant tier suppliers, polyurethane intermediate processors, and wholesale distributors. Primary interviews with plant managers at Jiangsu and Zhejiang chemical parks, regulatory affairs specialists navigating NMPA filing requirements, and MEE compliance officers supplemented customs trade data, SAMR GB/T standard filings, and MIIT dual carbon implementation disclosures. Bottom-up segment sizing triangulated against top-down oleochemical processing capacity estimates.
Assumptions held fixed include NMPA cosmetic ingredient purity thresholds, MIIT bio-based plasticizer mandate scope, and Gujarat crushing infrastructure capacity. Variables modeled across the analysis window encompass biocatalytic refining adoption rates, provincial environmental bureau enforcement intensity, and automotive sealant formulation substitution velocity. CAGRs derived from segment-level volume trajectories weighted by grade-specific price realization. Forecast inputs incorporated sebacic acid production bottleneck persistence and hydrogenated grade carbon disclosure compliance curves.
Practitioners should monitor NMPA filing backlog clearance rates, Shandong castor meal processing permit revocations, and Wenzhou hydrogenation capacity commissioning for early signals of supply-demand rebalancing. Forecasts reflect assumptions regarding regulatory enforcement continuity and feedstock import corridor stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Poultry Feed Premix Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
North America Feed Phytogenics Market