
 Global Feed Mycotoxin Binders and Modifiers Market | 2026-2036
Global Feed Mycotoxin Binders and Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feed Mycotoxin Binders and Modifiers Market Analysis
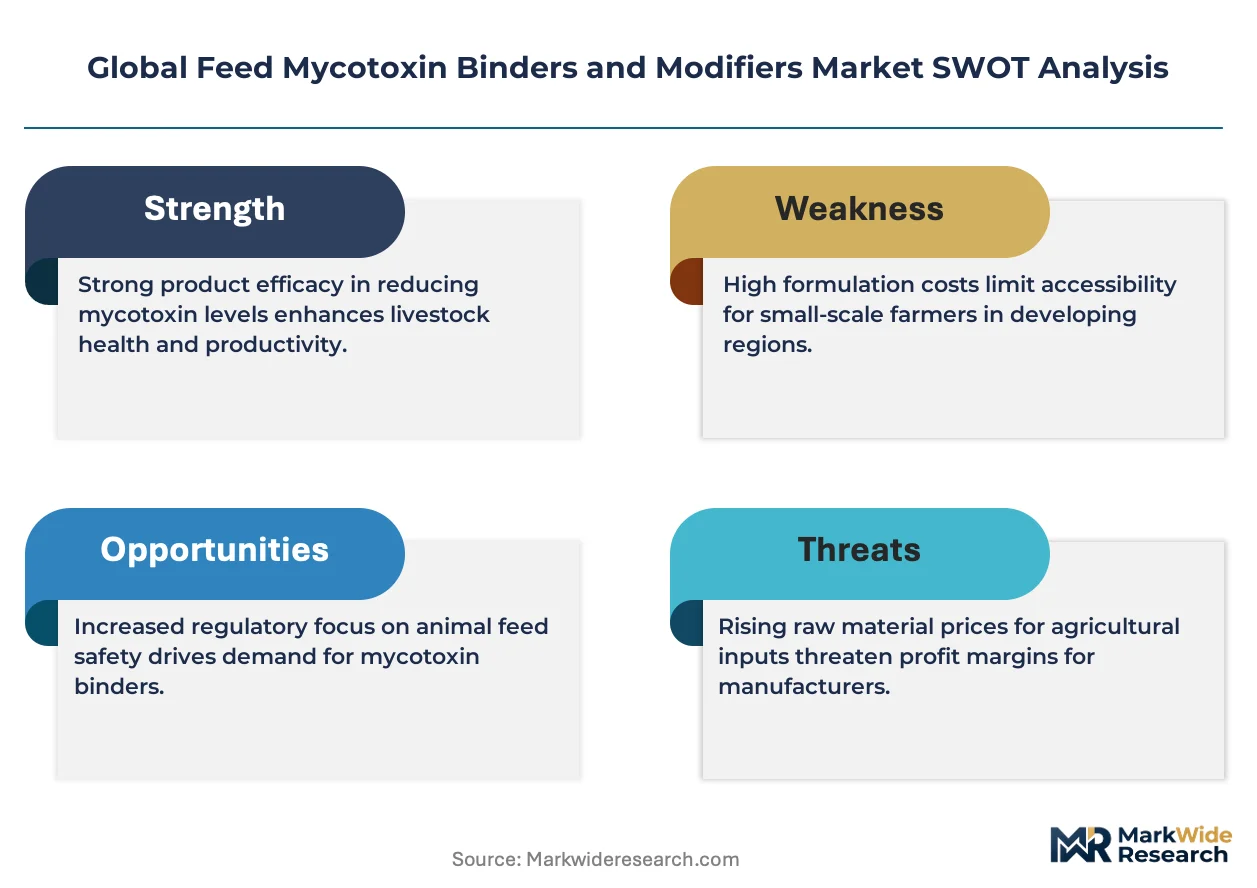
Aftermarket technical service revenue is reconfiguring competitive economics across the feed mycotoxin binder value chain. BASF SE leverages its polymer science heritage to sustain premium positioning in modified clay formulations. Kemin Industries anchors its portfolio through vertically integrated production of yeast cell wall derivatives in Iowa and Belgium. Alltech competes by embedding its mycotoxin management protocols within broader nutritional advisory programs for integrators.
Feed mycotoxin binders and modifiers comprise adsorbent and biotransformation agents engineered to sequester or detoxify aflatoxins, ochratoxins, and fumonisins in animal feed matrices, typically achieving binding capacities of 90% or higher for aflatoxin B1 at inclusion rates between 0.5 and 2.0 kg per metric ton of feed. These inputs serve to protect hepatic and renal function in production animals, reduce carryover into edible tissues, and preserve feed conversion efficiency under mycotoxin challenge conditions. Bentonite dominates volume flows in poultry and ruminant applications due to cost parity and established efficacy against aflatoxins, while activated charcoal commands narrower deployment in pet food and high-value aquaculture settings where broad-spectrum mycotoxin coverage justifies unit cost premiums. The aquaculture application segment is attracting reformulation investment as warm-water species intensification in Vietnam and Indonesia elevates sensitivity to hepatotoxic feed contaminants.
The EU Green Deal and REACH frameworks mandate batch-level mycotoxin monitoring for imported oilseed meals, compelling non-European exporters to certify binder inclusion in compound feeds destined for European livestock operations. FDA guidance on mycotoxin action levels in corn and small grains shapes product registration pathways and label claim substantiation requirements for US market access. Stakeholders must monitor divergence between EU and US maximum permitted levels for emerging mycotoxins such as T-2 toxin and deoxynivalenol, as regulatory asymmetry will dictate regional formulation strategies and inventory allocation across multinational manufacturing networks.
Market Dynamics
Integrated poultry operations across Brazil and Southeast Asia are consolidating procurement authority, forcing binder suppliers to embed technical service teams directly into customer nutrition departments rather than selling through traditional distribution.
Growth Catalysts
- EU Green Deal residue thresholds:The EU Green Deal and F-Gas Regulation now mandate batch-level mycotoxin certification for imported oilseed meals, compelling compound feed exporters to document binder inclusion.
- Aquaculture corridor intensification:Warm-water shrimp and finfish operations in Vietnam and Indonesia face elevated hepatotoxic contamination risks, creating demand for broad-spectrum binder formulations.
- Yeast cell wall biotransformation:Advances in enzymatic detoxification of trichothecenes and fumonisins are expanding modifier efficacy beyond adsorption into metabolic neutralization pathways.
Market Restraints
- Bentonite supply concentration:High-purity smectite clay deposits cluster in Wyoming and the Aegean region, exposing formulators to freight cost volatility and geopolitical transit risks.
- REACH registration burdens:Novel biotransformation enzymes face multi-year ECHA dossier preparation timelines, delaying European market entry for innovative modifier platforms.
- Activated charcoal substitution ceiling:Broad-spectrum mycotoxin coverage in premium aquaculture feeds faces unit economics constraints from coconut shell and peat-derived carbon sources.
Strategic Opportunities
- Underpenetrated Nigerian poultry belt:West Africa's rapidly consolidating broiler integrators lack technical advisory infrastructure, creating openings for binder-plus-protocol bundled offerings.
- Dual carbon alignment in China:Beijing's dual carbon goals incentivize low-carbon bentonite processing and renewable-powered yeast fermentation for modifier production.
- Blockchain-enabled provenance tracking:Integration of distributed ledger verification with mycotoxin batch testing is digitizing supply chain transparency for premium export channels.
Industry Challenges
- Mycotoxin analytical talent scarcity:LC-MS/MS method development and multi-toxin panel interpretation require specialized technicians that outpace veterinary and feed science program output.
- ISO 17025 accreditation timelines:Third-party binder efficacy certification laboratories face 18-24 month expansion cycles, bottlenecking customer qualification for new geographic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feed Mycotoxin Binders and Modifiers Market |
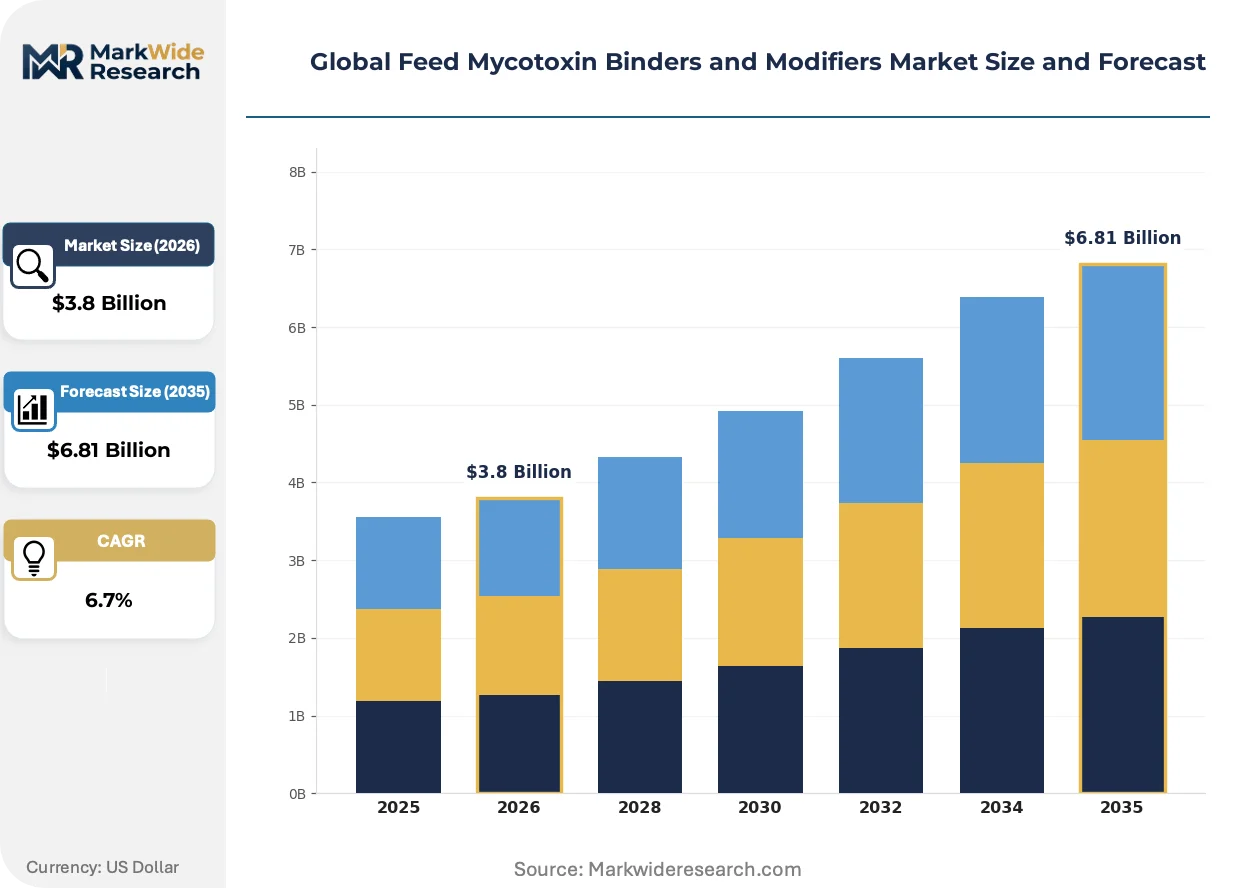
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bentonite, Zeolites, Activated Charcoal, Calcium Silicate Application: Livestock, Poultry, Aquaculture, Pet Food End User: Feed Manufacturers, Farmers, Animal Health Companies, Distributors Distribution Channel: Online Sales, Retail Outlets, Wholesalers, Direct Sales |
| Companies Covered | Kemin Industries, Novus International, Cargill, Perstorp, Archer Daniels Midland Company, BASF SE, Biomin, Impextraco, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feed Mycotoxin Binders and Modifiers Market Emerging Trajectories
Near-infrared spectroscopy and machine learning classification are compressing mycotoxin detection cycles from days to minutes, reshaping how binders are dosed and validated across commercial feed mills.
Enzymatic biotransformation platforms using engineered esterases and epoxidases are digitizing the shift from passive adsorption to active detoxification. Large integrators in Brazil and Thailand are piloting real-time inclusion rate adjustment based on rapid mycotoxin quantification. This compression of the detection-response loop is forcing legacy clay suppliers to co-develop hybrid formulations or cede premium positioning.
REACH and the EU Green Deal are tightening residue thresholds for imported feedstuffs, compelling non-European exporters to certify binder inclusion in compound feeds. FDA guidance on mycotoxin action levels in corn shapes parallel registration pathways for US market access. Divergence between EU and US maximum permitted levels for T-2 toxin and deoxynivalenol is dictating regional formulation strategies across multinational manufacturing networks.
Buyer concentration among integrated poultry and aquaculture operators is consolidating procurement authority into centralized nutrition teams. Traditional distributor relationships are giving way to direct technical partnerships where suppliers embed field scientists into customer operations. Vietnam's shrimp feed sector exhibits this most visibly, with leading integrators requiring binder vendors to co-invest in on-farm mycotoxin monitoring infrastructure.
Global Feed Mycotoxin Binders and Modifiers Market Segmentation
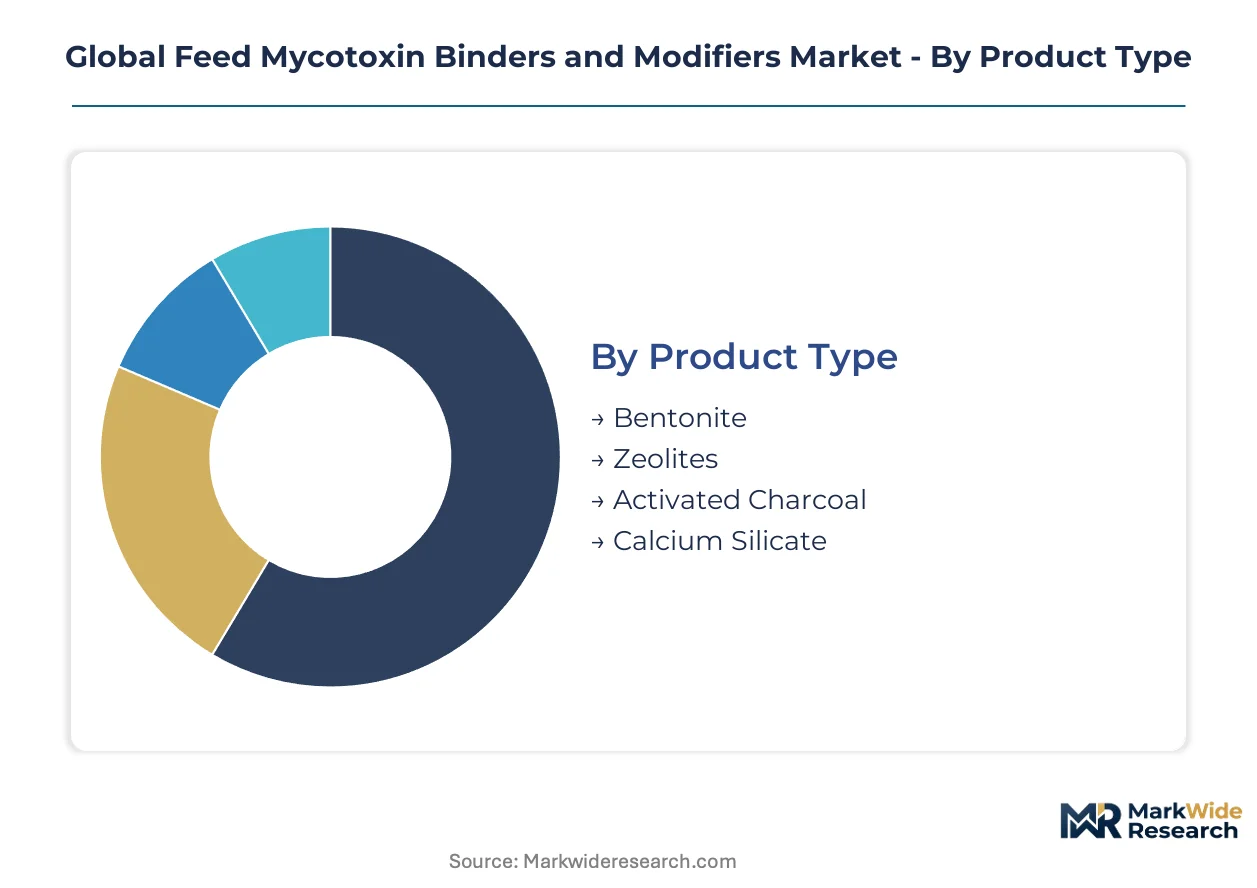
Segmentation in feed mycotoxin binders reveals how formulation chemistry, species sensitivity, and procurement authority reshape commercial access. Suppliers must align product portfolios with the technical requirements of concentrated buyers while navigating divergent regulatory thresholds across export destinations.
Product Type:
Cost tier structures the competitive landscape, separating commodity clay minerals from premium carbon-based solutions.
- Bentonite:Smectite clay minerals achieve 90% aflatoxin B1 binding at 0.5-2.0 kg per metric ton inclusion rates. Wyoming and Aegean deposits supply poultry and ruminant formulators seeking cost parity against hepatotoxic contamination in Brazil's grain belt and Southeast Asian feed mills.
- Zeolites:Crystalline aluminosilicates with defined pore structures target cationic mycotoxin species including ochratoxin A. European compound feed exporters facing EU Green Deal batch certification mandates drive specification intensity for high-purity clinoptilolite grades.
- Activated Charcoal:Coconut shell and peat-derived carbons deliver broad-spectrum coverage across aflatoxins, trichothecenes, and fumonisins for premium aquaculture and pet food matrices where unit economics permit.
- Calcium Silicate:Synthetic hydrated silica compounds provide intermediate adsorption capacity for mid-tier poultry operations balancing efficacy against trichothecenes with formulation cost constraints.
Bentonite commands the established base. The steepest expansion runs through activated charcoal as warm-water aquaculture intensifies.
Application:
Species-specific hepatotoxic sensitivity and production intensity determine binder specification requirements and dosing protocols.
- Livestock:Ruminant operations in the US Corn Belt and EU dairy corridors deploy bentonite-heavy formulations against aflatoxin M1 carryover into milk. FDA action levels for corn and small grains shape label claim substantiation pathways.
- Poultry:Broiler and layer integrators across Brazil, Thailand, and Nigeria represent the volume anchor for modified clay binders. Technical service embedding into centralized nutrition departments is displacing traditional distributor relationships.
- Aquaculture:Shrimp and finfish operations in Vietnam and Indonesia face elevated fumonisin sensitivity as warm-water intensification accelerates. REACH-registered biotransformation modifiers gain traction against adsorption-only formulations.
- Pet Food:Premium dry and wet formulations for companion animals command activated charcoal and yeast cell wall derivatives where broad-spectrum coverage justifies unit cost premiums.
Poultry anchors volume flows. Aquaculture delivers the fastest share gains as hepatotoxic contamination risks intensify in Southeast Asian production corridors.
End User:
Customer type determines whether procurement runs through specification-driven manufacturing partnerships or price-sensitive spot purchasing.
- Feed Manufacturers:Compound feed mills in the EU, Brazil, and China integrate binder inclusion into export certification documentation for Green Deal compliance. Batch-level mycotoxin monitoring mandates elevate supplier technical service requirements.
- Farmers:Independent livestock and poultry operators in underpenetrated West African markets purchase through distributor networks with limited advisory infrastructure, creating bundled protocol opportunities.
- Animal Health Companies:Veterinary pharmaceutical distributors in North America and Europe co-position binders within broader metabolic health portfolios for production animal clients.
- Distributors:Regional feed ingredient traders in Southeast Asia and Latin America face margin compression as integrated operations consolidate procurement authority into direct supplier relationships.
Feed manufacturers concentrate specification authority. Farmers in emerging corridors offer the steepest expansion trajectory for advisory-embedded offerings.
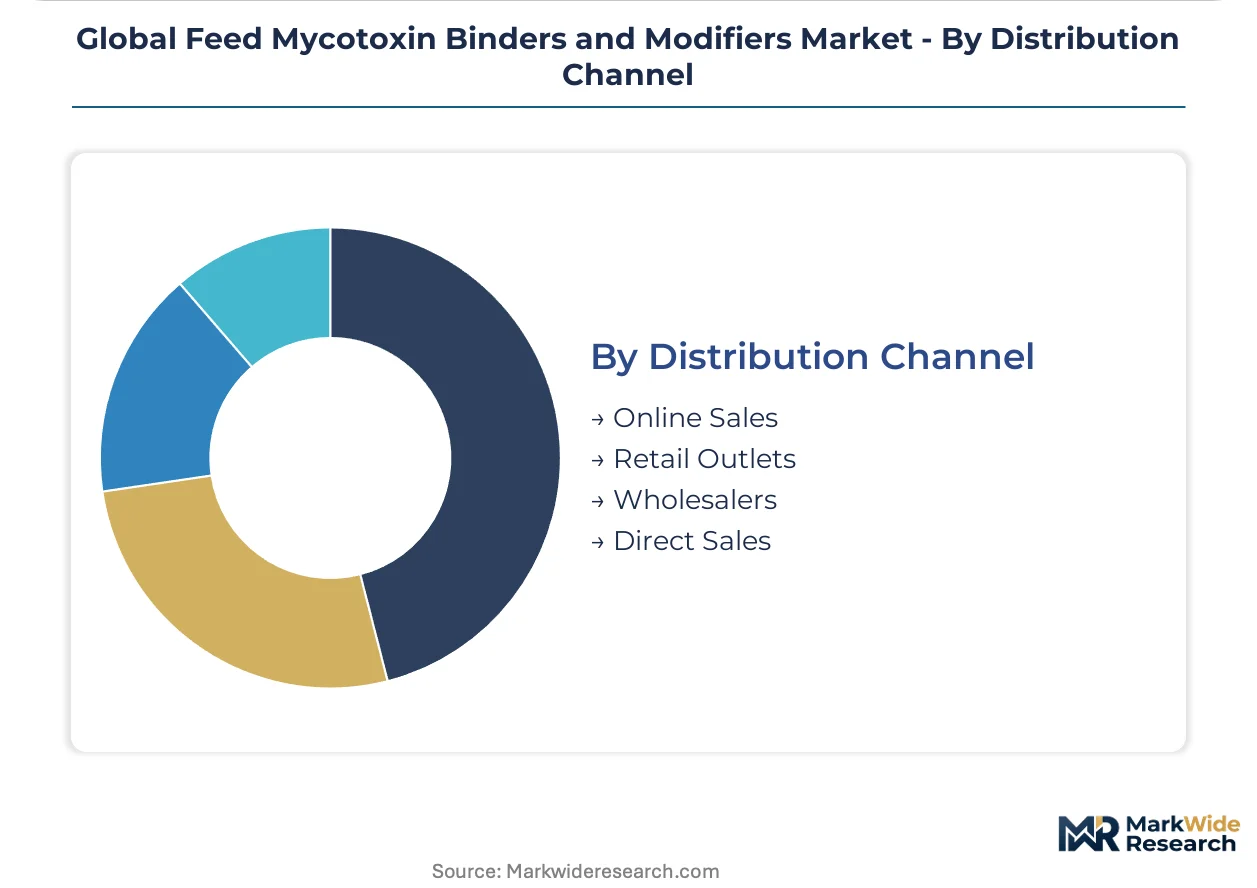
Distribution Channel:
Channel selection reflects buyer concentration and the technical complexity of mycotoxin risk management protocols.
- Direct Sales:Field scientist embedding into customer nutrition departments serves Brazil's integrated poultry giants and Vietnam's shrimp feed leaders requiring real-time inclusion rate adjustment capabilities.
- Wholesalers:Volume aggregation for mid-tier feed mills in India and Mexico maintains relevance where procurement decentralization persists.
- Retail Outlets:Agricultural supply cooperatives in the US Midwest and EU member states serve smaller livestock operations with standardized bentonite formulations.
- Online Sales:Digital procurement platforms capture specialty modifier trials and small-volume aquaculture formulators in Indonesia and the Philippines.
Direct sales commands the established base. Online channels are expanding most quickly as digital procurement penetrates specialty modifier segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and Southeast Asia deploy bentonite-heavy formulations for cost-sensitive poultry operations, while European compound feed exporters absorb premium biotransformation modifiers to satisfy REACH documentation mandates. This consumption-mix differential separates volume-driven markets from specification-intensive corridors.
United States
Corn Belt dairy operations and integrated poultry complexes drive bentonite demand for aflatoxin M1 mitigation in milk. FDA action levels for corn and small grains shape label claim substantiation pathways for modifier registrations. Iowa and Nebraska feed manufacturing clusters concentrate technical service embedding for real-time inclusion rate adjustments.
Brazil
Integrated broiler operations across São Paulo and Paraná consolidate procurement authority into centralized nutrition departments. ANVISA residue monitoring for export-bound poultry elevates documentation requirements for binder efficacy certification. The Mato Grosso grain belt generates hepatotoxic contamination risks that sustain modified clay formulation volumes.
Germany
Compound feed exporters serving EU dairy corridors absorb REACH-registered biotransformation enzymes for trichothecene detoxification. The EU Green Deal batch certification mandates drive specification intensity for high-purity clinoptilolite grades. Lower Saxony and Bavaria host formulation R&D clusters developing hybrid adsorption-biotransformation platforms.
China
Beijing's dual carbon goals incentivize low-carbon bentonite processing and renewable-powered yeast fermentation for modifier production. SAMR feed additive registration timelines shape market entry sequencing for novel enzymatic platforms. Yangtze River Delta feed manufacturing clusters pilot blockchain-enabled mycotoxin provenance tracking for premium export channels.
Vietnam
Warm-water shrimp intensification in the Mekong Delta elevates fumonisin sensitivity and broad-spectrum binder demand. Integrated aquaculture operators require vendor co-investment in on-farm mycotoxin monitoring infrastructure. Ho Chi Minh City corridor feed mills compress detection-response loops through near-infrared spectroscopy integration.
Global Feed Mycotoxin Binders and Modifiers Market Vendor Landscape
Capability concentration sits with biotransformation specialists commanding enzymatic detoxification platforms; scale advantage sits with mineral processors leveraging Wyoming and Aegean bentonite deposits. The market structures around three archetypes: polymer science heritage players sustaining premium modified clay positioning, vertically integrated yeast cell wall producers, and advisory-embedded nutrition protocol bundlers. Dominant competitive moves include direct technical service embedding into customer nutrition departments and hybrid formulation co-development between legacy clay suppliers and enzymatic platform innovators.
Among diversified chemical conglomerates, BASF SE anchors premium positioning through polymer science heritage applied to modified clay formulations. Kemin Industries exemplifies vertical integration control, with captive production of yeast cell wall derivatives across Iowa and Belgium facilities. Alltech occupies the advisory-embedded tier, bundling mycotoxin management protocols within broader nutritional programs for integrated poultry and aquaculture operators.
| Leading Market Players |
|---|
| Kemin Industries |
| Novus International |
| Cargill |
| Perstorp |
| Archer Daniels Midland Company |
| BASF SE |
| Biomin |
| Impextraco |
| Alltech |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Wyoming bentonite processing facilities tightens smectite clay availability for Brazilian poultry formulators, compressing margins for mid-tier suppliers while rewarding premium-positioned modified clay producers with pricing power anchored to polymer science differentiation.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated Brazilian poultry operations and Wyoming-based bentonite suppliers, insulating volume flows from spot volatility. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered biotransformation modifiers from commodity clay minerals and mid-tier calcium silicate formulations. Cost compression in standard-grade bentonite intensifies as freight cost volatility from Aegean deposits erodes landed cost advantages. Independent farmers in Nigeria exhibit the highest price sensitivity, while Vietnamese shrimp integrators absorb premium activated charcoal pricing for broad-spectrum hepatotoxic coverage.
Supply Chain Analysis
Tariff exposure between Turkey and EU member states disrupts clinoptilolite zeolite flows for compound feed exporters facing Green Deal batch certification mandates. High-purity smectite deposits cluster in Wyoming, Aegean Turkey, and China's Inner Mongolia, while coconut shell activated charcoal production concentrates in Indonesia and Sri Lanka. Supply chain vulnerability rests on single-source dependency for engineered esterase biotransformation enzymes produced in Belgian fermentation facilities. Distribution runs through direct technical service embedding for Brazil's integrated poultry giants, with spot purchasing persisting among West African distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized LC-MS/MS analytical talent for multi-toxin panel interpretation outpaces veterinary program output, constraining binder efficacy certification velocity and amplifying returns for laboratories that compress ISO 17025 accreditation timelines.
For Market Incumbents: Entrench market position through captive control over Wyoming smectite deposits and accelerated REACH dossier preparation for novel enzymatic platforms. Biotransformation specialists with esterase engineering capabilities threaten premium modified clay positioning; defend through hybrid formulation co-development with yeast cell wall producers in Iowa and Belgium. For New Entrants and Emerging Players: Pursue advisory-embedded protocol bundling in Nigeria's consolidating broiler belt, where technical infrastructure scarcity creates white-space for binder-plus-monitoring service packages. Blockchain-enabled provenance tracking for premium export channels offers the most penetrable go-to-market angle for digital-native modifiers targeting Yangtze River Delta feed manufacturing clusters. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biotransformation modifier production as multi-year ECHA registration timelines extend cash conversion cycles. Long-term viability favors acquisition targets with existing REACH-registered enzymatic platforms and embedded technical service relationships with Vietnamese aquaculture integrators. The signal to watch is consolidation velocity among Brazil's centralized nutrition departments as procurement authority concentrates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Smectite Deposits | Secures Wyoming clay supply for Brazilian poultry formulators facing ANVISA export documentation requirements. |
| REACH-Registered Enzymatic Platform Development | Accelerates European market entry for trichothecene biotransformation modifiers ahead of ECHA dossier bottlenecks. |
| Technical Service Team Embedding | Displaces traditional distributor relationships in Vietnam's Mekong Delta shrimp feed sector. |
| Blockchain-Enabled Provenance Tracking | Digitizes batch-level mycotoxin certification for EU Green Deal compliance in Chinese export channels. |
| Hybrid Adsorption-Biotransformation Formulation | Combines bentonite cost parity with enzymatic detoxification for warm-water aquaculture intensification corridors. |
Methodological Framework
Desk research of customs/trade data, SEC 10-K filings, and ECHA registration databases preceded structured interviews with feed mill procurement directors, veterinary nutritionists at integrated poultry operations, biotransformation R&D leads, and ISO 17025 laboratory accreditation managers. Primary fieldwork across Iowa, Belgium, and São Paulo feed manufacturing clusters validated secondary estimates of binder inclusion rates and efficacy certification timelines. Bottom-up volume aggregation across species-specific application segments triangulated against top-down value estimates from compound feed production data.
Assumptions held fixed include current EU-US regulatory divergence on T-2 toxin maximum permitted levels and existing Wyoming bentonite processing capacity utilization rates across the projection horizon. The analytical framework modeled product type, application species, end-user procurement authority, and distribution channel technical complexity as segmentation dimensions. CAGRs derived from historical volume trajectories in Brazil's grain belt and Southeast Asian aquaculture corridors incorporated SAMR registration timeline assumptions for novel enzymatic platforms.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese bentonite processors or accelerated FDA guidance shifts on mycotoxin action levels would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Neonicotinoid Insecticides Market