
 Europe Feed Antibiotics Market | 2026-2036
Europe Feed Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Antibiotics Market Foresight
Specialized swine integrators are redrawing procurement patterns across Europe as they displace traditional dairy cooperatives in feed antibiotic volume share. Zoetis Inc. leverages its veterinary channel control across Iberian livestock belts, while BASF SE anchors premix supply relationships with Dutch poultry conglomerates. Elanco Animal Health competes through R&D intensity in macrolide formulations tailored to reduced-residue protocols.
Feed antibiotics comprise antimicrobial compounds administered through animal feed to prevent bacterial infection, promote growth, or treat subclinical disease in livestock populations; active ingredients typically fall within specified concentration ranges governed by withdrawal period requirements and maximum residue limits under EU pharmacovigilance frameworks. Tetracyclines retain the largest share of the product type landscape due to broad-spectrum efficacy and established manufacturing scale, while macrolides represent the fastest-expanding category as swine producers seek alternatives to critically important human antibiotics. Among applications, poultry operations generate the densest margin pools because of short production cycles and high flock turnover rates, though aquaculture demand is accelerating in Norwegian and Greek coastal farming zones.
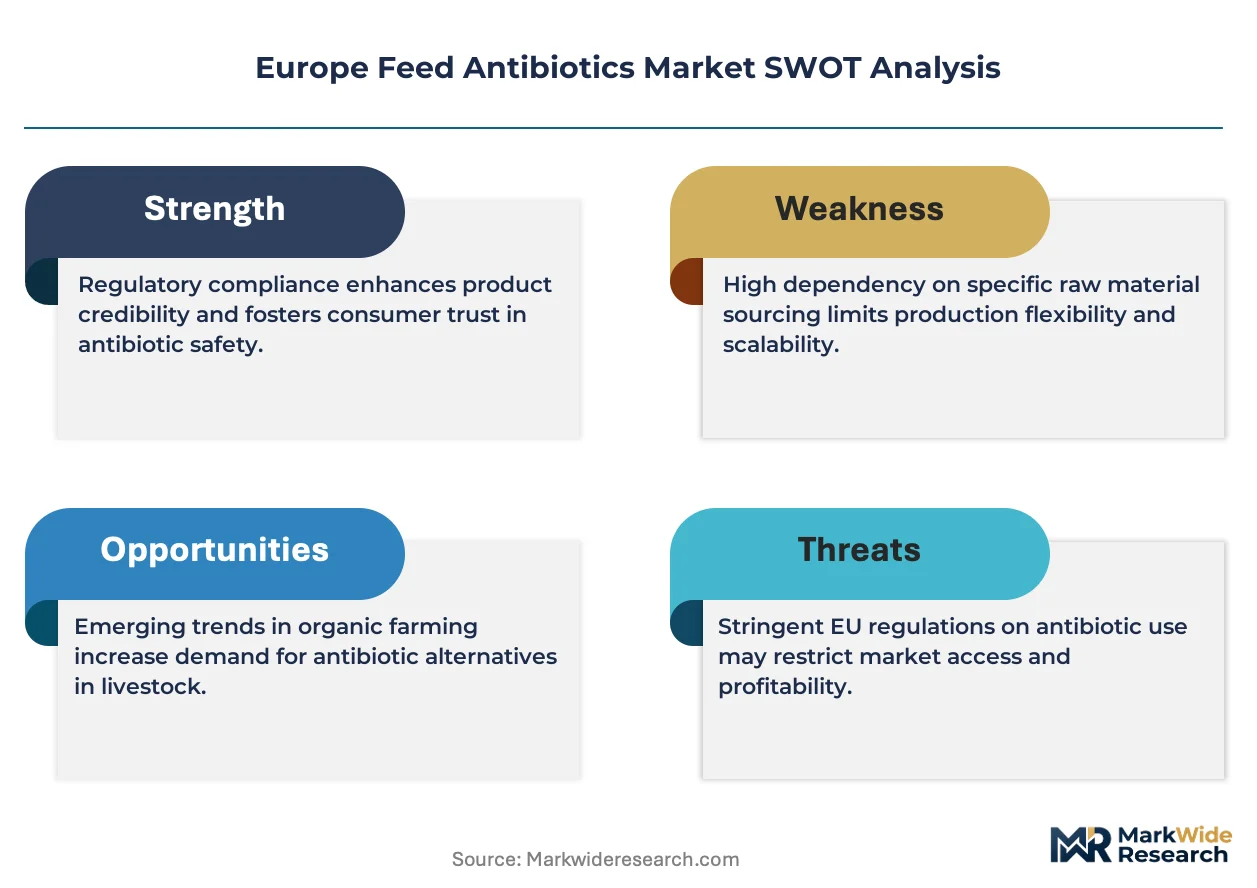
The European Medicines Agency enforces pharmacovigilance monitoring and antimicrobial resistance benchmarks that directly constrain which active ingredients manufacturers may deploy in premix formulations. REACH and the EU Veterinary Medicinal Products Regulation jointly shape product registration pathways, formulation disclosure requirements, and cross-border distribution permissions for compound feed mills. Stakeholders must monitor pending revisions to the EU Green Deal's farm-to-fork antimicrobial reduction targets, as these will determine whether tetracycline and macrolide premixes retain market access or face phased substitution mandates.
Market Dynamics
The EU Veterinary Medicinal Products Regulation is forcing commercial livestock integrators across Iberia and Central Europe to restructure antibiotic procurement channels, tightening prescription oversight while concentrating volume flows through fewer veterinary-controlled supply chains.
Growth Catalysts
- Intensive Swine Operations:Commercial integrators in Spain and Poland are expanding antibiotic procurement for high-density production facilities, driving volume concentration through specialized veterinary channels.
- EU Green Deal Farm-to-Fork Targets:Pending antimicrobial reduction mandates are accelerating investment in residue-compliant formulation technologies ahead of phased substitution timelines.
- REACH Registration Pathways:Streamlined chemical safety dossier approvals for tetracycline premixes are reducing time-to-market for reformulated products targeting German poultry producers.
Market Restraints
- Active Ingredient Concentration Risk:Tetracycline API supply concentrates among Chinese and Indian bulk manufacturers, exposing European formulators to import dependency and price volatility.
- Withdrawal Period Compliance Costs:Extended residue clearance protocols for macrolide premixes inflate working capital requirements for swine operations running sub-24-week production cycles.
- Antimicrobial Resistance Benchmarks:EMA pharmacovigilance thresholds progressively restrict which active ingredients retain premix authorization, compressing the viable formulation pipeline.
Strategic Opportunities
- Norwegian Aquaculture Belt:Coastal salmon farming operations in Bergen and Trondheim zones represent underpenetrated demand for water-stable antibiotic premixes addressing bacterial kidney disease.
- Reduced-Residue Macrolide Formulations:R&D investment in rapid-clearance erythromycin derivatives aligns with EMA incentives for alternatives to critically important human antibiotics.
- Veterinary Channel Integration:Direct distribution partnerships with Iberian livestock veterinary networks bypass traditional feed mill intermediaries, capturing margin and prescription control.
Industry Challenges
- Formulation Stability Expertise Gap:European compound feed mills face acute shortages of pharmaceutical process engineers capable of maintaining tetracycline bioavailability through pelleting thermal stress.
- Cross-Border Distribution Permissions:Divergent national implementations of EU Veterinary Medicinal Products Regulation create licensing friction for premix shipments between German, Polish, and Spanish production sites.
- Legacy Feed Mill Retrofit Costs:Segregated production line requirements for medicated versus non-medicated feeds demand capital expenditure that mid-scale operators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Antibiotics Market |
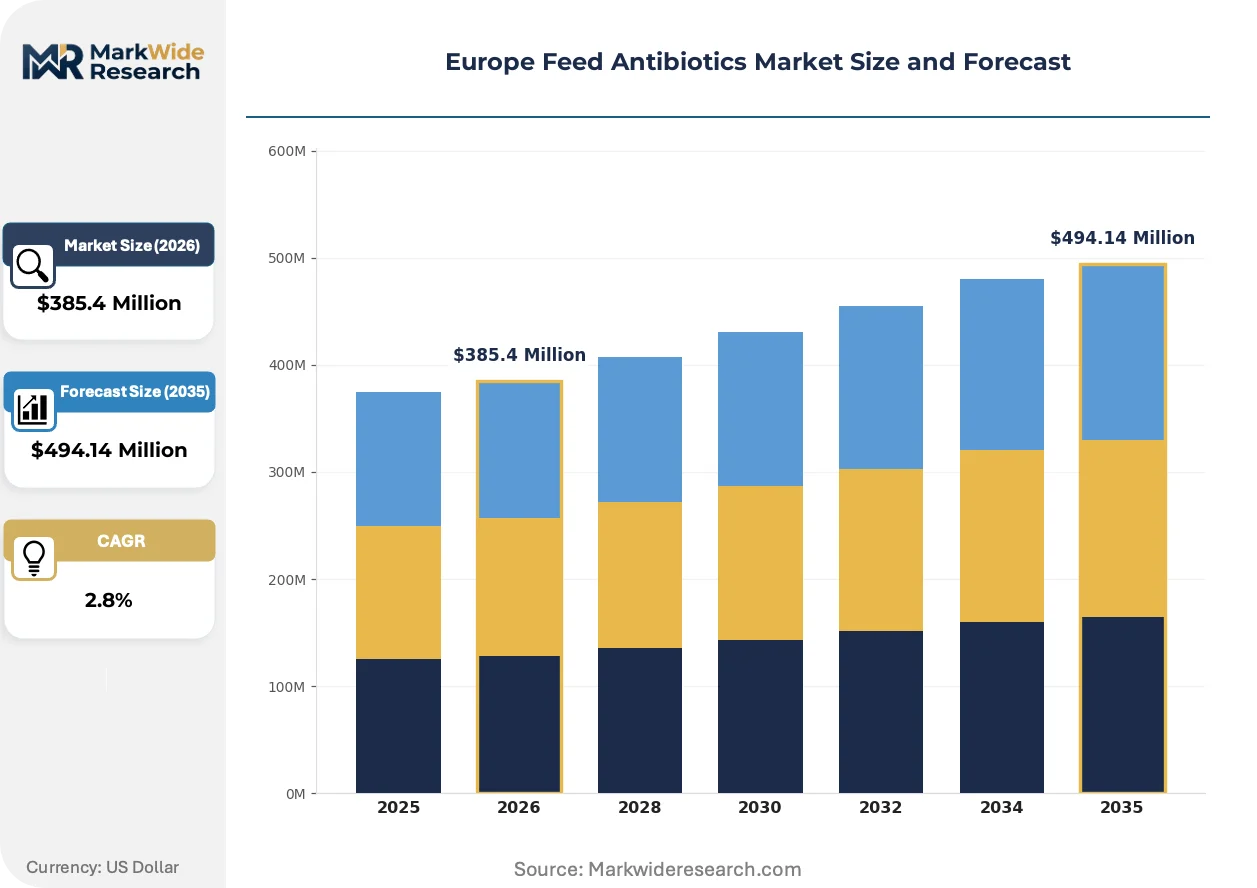
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $494.14 Million |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Macrolides, Tetracyclines, Penicillins, Lincosamides Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granular, Premix Distribution Channel: Online Sales, Veterinary Clinics, Pharmacies, Direct Sales |
| Companies Covered | BASF SE, Elanco Animal Health, Zoetis Inc., Bayer AG, Huvepharma, Virbac S.A., Vetoquinol S.A., Boehringer Ingelheim Denmark A/S, Cargill Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Antibiotics Market Shifts & Advancements
Formulation chemistry and distribution control are converging to reshape competitive advantage in European feed antibiotics, with residue compliance and channel ownership replacing commodity scale as the primary value drivers.
Microencapsulated tetracycline matrices with pH-triggered release mechanisms are displacing conventional premix formats in German and Dutch poultry operations. These delivery systems protect active ingredients from feed processing degradation while ensuring intestinal absorption. Large integrators in Lower Saxony and Gelderland provinces are adopting this technology at accelerated procurement cycles, compressing margins for standard premix suppliers unable to match stability performance.
EMA's pending revisions to antimicrobial resistance monitoring thresholds are tightening maximum residue limit enforcement across all member states. This regulatory pressure is forcing reformulation of legacy macrolide premixes and accelerating withdrawal period documentation requirements. Spanish swine operations in Aragon and Catalonia regions face the most acute compliance burden, driving veterinary prescription consolidation and direct manufacturer relationships.
Livestock integrators are consolidating antibiotic procurement through captive veterinary service networks rather than independent feed distributors. This channel shift concentrates volume with manufacturers offering integrated prescription-to-delivery compliance packages. The transformation is most visible across Iberian poultry belts, where Zoetis-controlled veterinary channels now manage antibiotic allocation for multiple integrated production sites under single prescription frameworks.
Europe Feed Antibiotics Market Segmentation
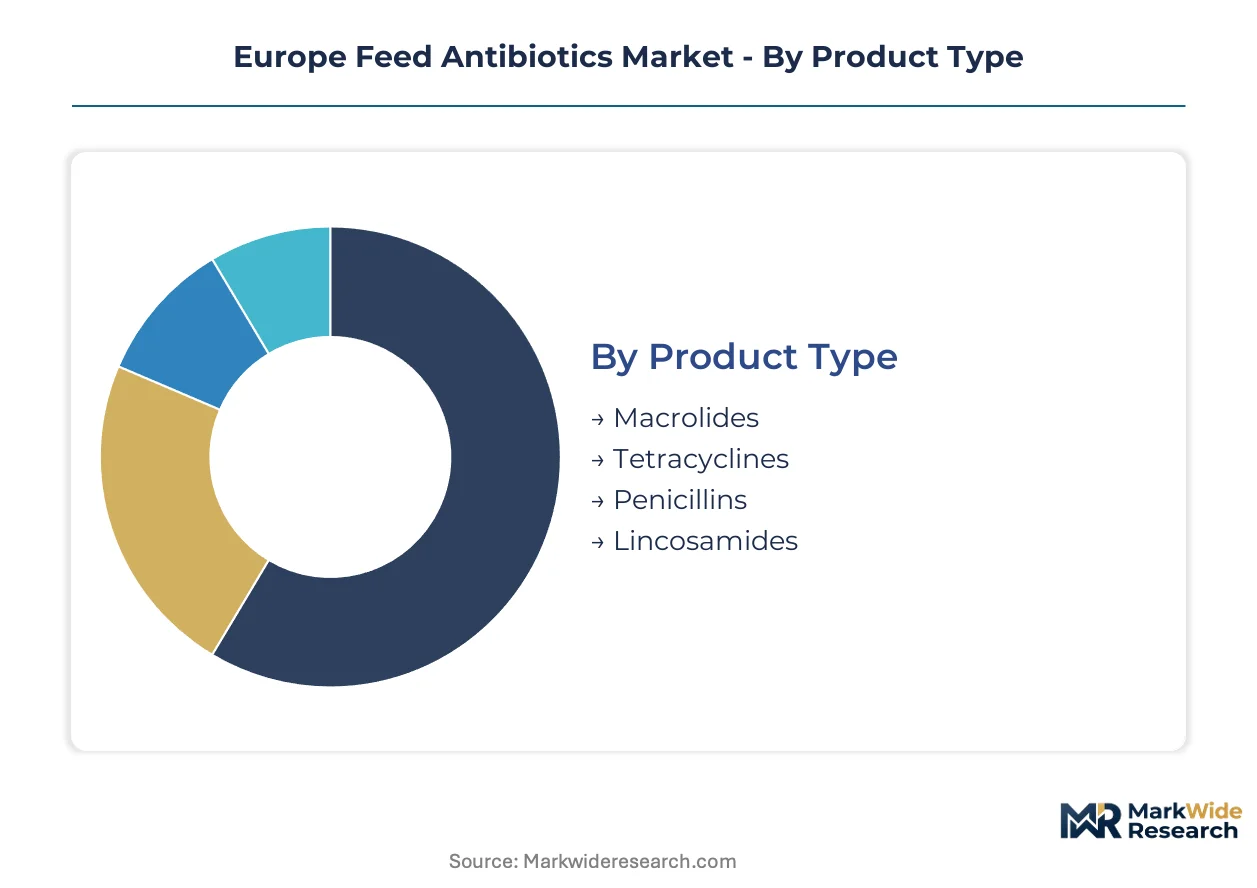
Feed antibiotic procurement channels in Europe fragment sharply across product chemistries and livestock categories, with veterinary prescription requirements under the EU Veterinary Medicinal Products Regulation determining which segments flow through controlled distribution networks versus open commercial channels.
Product Type:
Veterinary-controlled channels concentrate volume for broad-spectrum classes requiring prescription oversight, while narrower-spectrum alternatives move through more fragmented procurement pathways.
- Tetracyclines:Broad-spectrum bacteriostatic compounds formulated as chlortetracycline and oxytetracycline derivatives dominate German poultry premix procurement. Demand concentrates in Lower Saxony and North Rhine-Westphalia production belts where BASF SE and Zoetis Inc. compete on formulation stability through pelleting thermal stress.
- Macrolides:Erythromycin and tylosin-based formulations represent the steepest expansion trajectory as Spanish and Polish swine integrators seek alternatives to critically important human antibiotics. Elanco Animal Health directs R&D investment toward rapid-clearance derivatives aligned with EMA residue compliance incentives.
- Penicillins:Beta-lactam compounds face declining premix authorization under antimicrobial resistance benchmarks, with remaining volume restricted to therapeutic veterinary prescriptions in Dutch dairy operations.
- Lincosamides:Lincomycin formulations serve niche aquaculture applications in Norwegian coastal farming zones, with limited penetration constrained by narrow spectrum and withdrawal period complexity.
Tetracyclines dominate installed base across European livestock production. Macrolides are where expansion concentrates as regulatory pressure reshapes acceptable active ingredient portfolios.
Application:
Production cycle economics and flock density determine which livestock categories generate sustainable margin pools for antibiotic premix suppliers.
- Poultry:Short production cycles and high flock turnover rates generate the densest margin pools for premix formulators. Dutch and German integrators in Gelderland and Lower Saxony provinces drive procurement of microencapsulated tetracycline matrices with pH-triggered release mechanisms.
- Swine:Intensive operations in Aragon and Catalonia regions face acute EMA compliance burdens, consolidating antibiotic allocation through captive veterinary service networks rather than independent feed distributors.
- Ruminants:Dairy cooperatives in the Netherlands and Denmark are losing volume share to specialized swine integrators, with remaining demand concentrated in therapeutic rather than prophylactic applications.
- Aquaculture:Coastal salmon farming in Bergen and Trondheim zones represents underpenetrated demand for water-stable antibiotic premixes addressing bacterial kidney disease, with Norwegian producers accelerating procurement ahead of EU Green Deal antimicrobial reduction timelines.
Poultry commands the deepest margin structure. Aquaculture is where volume is climbing the fastest as coastal farming zones professionalize disease management protocols.
Form:
Processing compatibility and bioavailability protection separate technically capable formulators from commodity premix suppliers.
- Premix:Concentrated carrier-based formulations incorporating tetracycline and macrolide actives at specified inclusion rates serve as the standard delivery mechanism for German and Spanish compound feed mills, with segregation requirements for medicated versus non-medicated production lines demanding capital expenditure that mid-scale operators struggle to finance.
- Powder:Direct-to-feed powder formats retain relevance for smaller-scale Polish and Iberian operations lacking pelleting infrastructure, though thermal degradation during feed processing limits bioavailability compared to protected alternatives.
- Liquid:Water-soluble formulations address post-weaning piglet applications in Spanish intensive operations, with dosing precision requirements driving veterinary channel control over distribution.
- Granular:Extruded granule formats with thermal protection layers command premium positioning for high-temperature pelleting applications in Dutch poultry conglomerates, with formulation stability expertise gaps constraining European compound feed mill adoption.
Premix formats anchor installed base across commercial integrators. Granular delivery systems are where technology investment concentrates as thermal protection becomes a competitive differentiator.
Distribution Channel:
Regulatory prescription requirements are compressing channel diversity, concentrating volume through veterinary-controlled pathways.
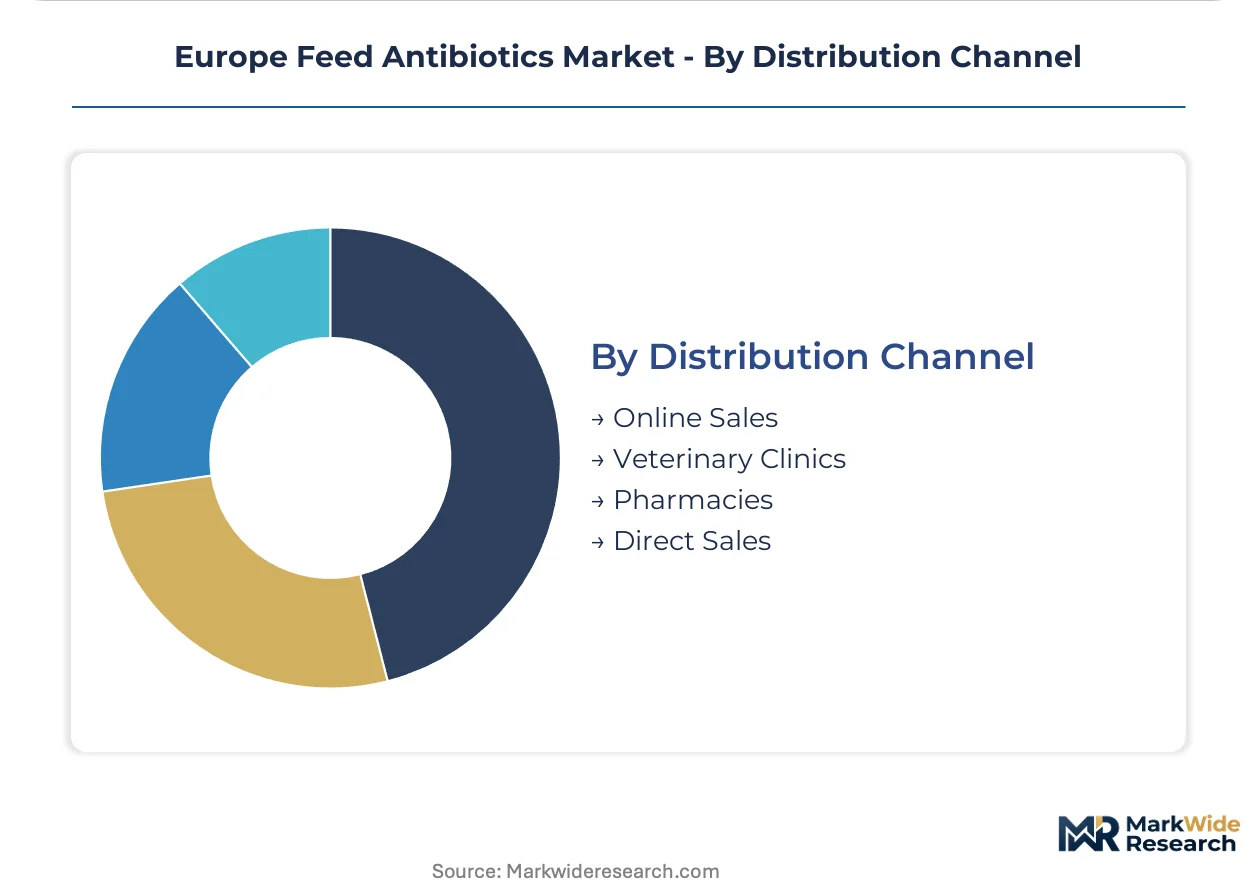
- Veterinary Clinics:Direct distribution partnerships with Iberian livestock veterinary networks bypass traditional feed mill intermediaries, capturing margin and prescription control. Zoetis-controlled channels now manage antibiotic allocation for multiple integrated production sites under single prescription frameworks.
- Direct Sales:Manufacturer relationships with large integrators in Germany and the Netherlands enable integrated prescription-to-delivery compliance packages, with BASF SE anchoring premix supply relationships through technical service bundling.
- Pharmacies:Community pharmacy channels retain residual volume for smaller ruminant operations in France and Italy, with declining relevance as livestock production consolidates.
- Online Sales:Digital procurement platforms face regulatory friction under divergent national implementations of EU Veterinary Medicinal Products Regulation, creating licensing barriers for cross-border premix shipments.
Veterinary clinics dominate prescription-controlled volume. Direct sales are where manufacturer relationship investment concentrates as integrators consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large commercial integrators concentrate antibiotic procurement authority across Europe's livestock belts, with veterinary prescription requirements under EU Veterinary Medicinal Products Regulation reshaping distribution geography. German poultry conglomerates and Iberian swine operations now dominate volume flows.
Germany
Lower Saxony and North Rhine-Westphalia poultry belts drive densest premix demand, with integrators procuring microencapsulated tetracycline matrices for high-throughput operations. REACH registration pathways streamline chemical safety dossiers for reformulated products. BASF SE anchors supply relationships through technical service bundling across these northern production zones.
Spain
Intensive swine operations in Aragon and Catalonia face acute EMA compliance burdens, consolidating antibiotic allocation through captive veterinary networks. Spanish integrators expand procurement for high-density facilities despite tightening prescription oversight. Zoetis-controlled channels now manage allocation across multiple integrated sites under single prescription frameworks.
Poland
Central European swine integrators scale antibiotic procurement for expanding intensive operations, displacing traditional dairy cooperatives in volume share. Polish producers rely on direct-to-feed powder formats where pelleting infrastructure remains limited. Divergent national implementations of EU Veterinary Medicinal Products Regulation create licensing friction for cross-border premix shipments from German suppliers.
Netherlands
Gelderland province poultry conglomerates command premium positioning for granular delivery systems with thermal protection layers. Dutch integrators adopt pH-triggered release tetracycline formulations at accelerated procurement cycles. Segregated production line requirements for medicated versus non-medicated feeds demand capital expenditure that mid-scale operators struggle to finance.
Norway
Coastal salmon farming in Bergen and Trondheim zones represents underpenetrated demand for water-stable antibiotic premixes addressing bacterial kidney disease. Norwegian producers accelerate procurement ahead of EU Green Deal antimicrobial reduction timelines. EMA pharmacovigilance monitoring constrains which active ingredients retain authorization for aquaculture applications.
Europe Feed Antibiotics Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates and veterinary pharmaceutical specialists with established premix formulation capabilities. The competitive structure concentrates around manufacturers controlling both active ingredient supply and veterinary distribution channels. Three archetypes dominate: integrated chemical-pharmaceutical conglomerates with backward integration into API sourcing, veterinary-focused pharmaceutical companies with channel control through prescription networks, and regional premix specialists competing on formulation stability expertise. Dominant competitive moves include direct distribution partnerships bypassing feed mill intermediaries and R&D investment in rapid-clearance macrolide derivatives aligned with EMA residue compliance incentives.
Within the integrated chemical-pharmaceutical tier, BASF SE exemplifies the conglomerate archetype with premix supply relationships anchored through technical service bundling, while Zoetis Inc. represents veterinary channel control through direct prescription-to-delivery frameworks across Iberian livestock belts. Elanco Animal Health occupies a position emphasizing R&D intensity in macrolide formulations tailored to reduced-residue protocols.
| Leading Market Players |
|---|
| BASF SE |
| Elanco Animal Health |
| Zoetis Inc. |
| Bayer AG |
| Huvepharma |
| Virbac S.A. |
| Vetoquinol S.A. |
| Boehringer Ingelheim Denmark A/S |
| Cargill Incorporated |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with active pharmaceutical ingredient suppliers lock in tetracycline feed-grade supply for German and Dutch poultry integrators while anchoring price visibility against volatile Chinese and Indian bulk manufacturing costs. These arrangements concentrate procurement power with formulators capable of backward integration into API sourcing, compressing margins for spot-market-dependent competitors across Iberian and Polish livestock belts.
Pricing Analysis
Cost-plus contracts indexed to tetracycline API commodity benchmarks dominate procurement between European formulators and Asian bulk manufacturers. Three-tier pricing structure across microencapsulated premium formulations, standard premix grades, and unprotected powder formats differentiates BASF SE and Zoetis Inc. offerings from regional specialists. Pricing pressure stems from REACH registration cost recovery requirements and EMA residue compliance documentation burdens. Small-scale Polish swine operations exhibit highest price sensitivity, while Dutch poultry conglomerates prioritize thermal stability performance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German compound feed mills with segregated medicated production lines, while Spanish integrators maintain strategic stockpiles of macrolide premixes to buffer veterinary prescription approval delays. API supply concentrates in China and India for tetracyclines, with European formulators drawing from Hungarian and Italian secondary manufacturing for finished premixes. Single-source vulnerability to API import dependency represents the dominant structural risk. Distribution runs through veterinary-controlled channels rather than independent feed distributors, concentrating volume with manufacturers offering integrated prescription compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe feed antibiotics market is cycling through a regulatory-driven recovery phase as EMA pharmacovigilance thresholds force reformulation investment and channel consolidation. Livestock integrators are rebuilding antibiotic procurement frameworks ahead of EU Green Deal antimicrobial reduction timelines, creating selective expansion windows for technically capable suppliers.
For Market Incumbents: Fortify veterinary channel control through direct prescription-to-delivery partnerships that bypass traditional feed mill intermediaries. BASF SE and Zoetis Inc. should deepen captive API supply relationships to defend against Chinese bulk manufacturer price volatility. Invest in rapid-clearance macrolide R&D to align with EMA incentives for alternatives to critically important human antibiotics before substitution mandates tighten.
For New Entrants and Emerging Players: Lead with water-stable antibiotic formulations targeting Norwegian aquaculture operations in Bergen and Trondheim zones, where bacterial kidney disease management demand outpaces established supplier penetration. Develop granular delivery systems with thermal protection layers for Dutch poultry conglomerates facing acute formulation stability expertise gaps. Partner with Iberian veterinary networks for prescription-controlled distribution rather than competing through commodity premix pricing.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale formulators with proven microencapsulation capabilities and established REACH registration dossiers, as these assets command scarcity premiums under tightening EMA authorization requirements. The long-term viability window favors manufacturers with backward integration into API sourcing and veterinary channel ownership. Watch EMA's pending antimicrobial resistance threshold revisions as the critical inflection signal for macrolide premix authorization scope.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Sourcing | Captive tetracycline supply insulates BASF SE from Chinese bulk manufacturer price volatility and import dependency. |
| Veterinary Channel Acquisition | Zoetis Inc.'s prescription network control across Iberia captures margin and compliance authority from feed distributors. |
| Microencapsulation R&D Investment | pH-triggered release matrices protect bioavailability through German pelleting thermal stress, commanding premium positioning. |
| REACH Registration Streamlining | Accelerated chemical safety dossier approvals reduce time-to-market for reformulated products targeting Dutch poultry. |
| Aquaculture Formulation Development | Water-stable premixes address bacterial kidney disease in Norwegian salmon farming ahead of EU antimicrobial reduction mandates. |
Research Methodology
Cross-validation between primary interviews with veterinary pharmaceutical executives, compound feed mill procurement directors, EMA regulatory affairs specialists, and livestock integrator operations managers anchors the qualitative findings in operational reality. Secondary validation draws from EMA pharmacovigilance databases, REACH registration filings, EU trade customs records, and national veterinary prescription registries across Germany, Spain, Poland, and the Netherlands. Bottom-up segmentation modeling triangulates against top-down market sizing from chemical industry associations and livestock production statistics.
Sensitivity analysis around EMA antimicrobial resistance threshold scenarios and EU Green Deal implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include product chemistry class, livestock application category, formulation delivery mechanism, and distribution channel structure. CAGRs derive from installed base erosion rates for legacy premix formats and penetration curves for microencapsulated alternatives. Forecast inputs incorporate veterinary prescription volume flows, feed mill capacity utilization, and API import dependency ratios.
Forecasts assume regulatory continuity in EMA pharmacovigilance enforcement and EU Veterinary Medicinal Products Regulation implementation; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated tetracycline substitution mandates, REACH authorization withdrawals for key actives, and API supply disruptions from Chinese manufacturing consolidation. Revision becomes warranted when EMA antimicrobial resistance benchmarks cross thresholds that delist currently authorized premix formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Europe Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Neem Extract Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
Agricultural Miticides Market
Agricultural Chemicals
GCC Feed Premix Market