
 US Home Care Packaging Market | 2026-2036
US Home Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Home Care Packaging Market Analytics
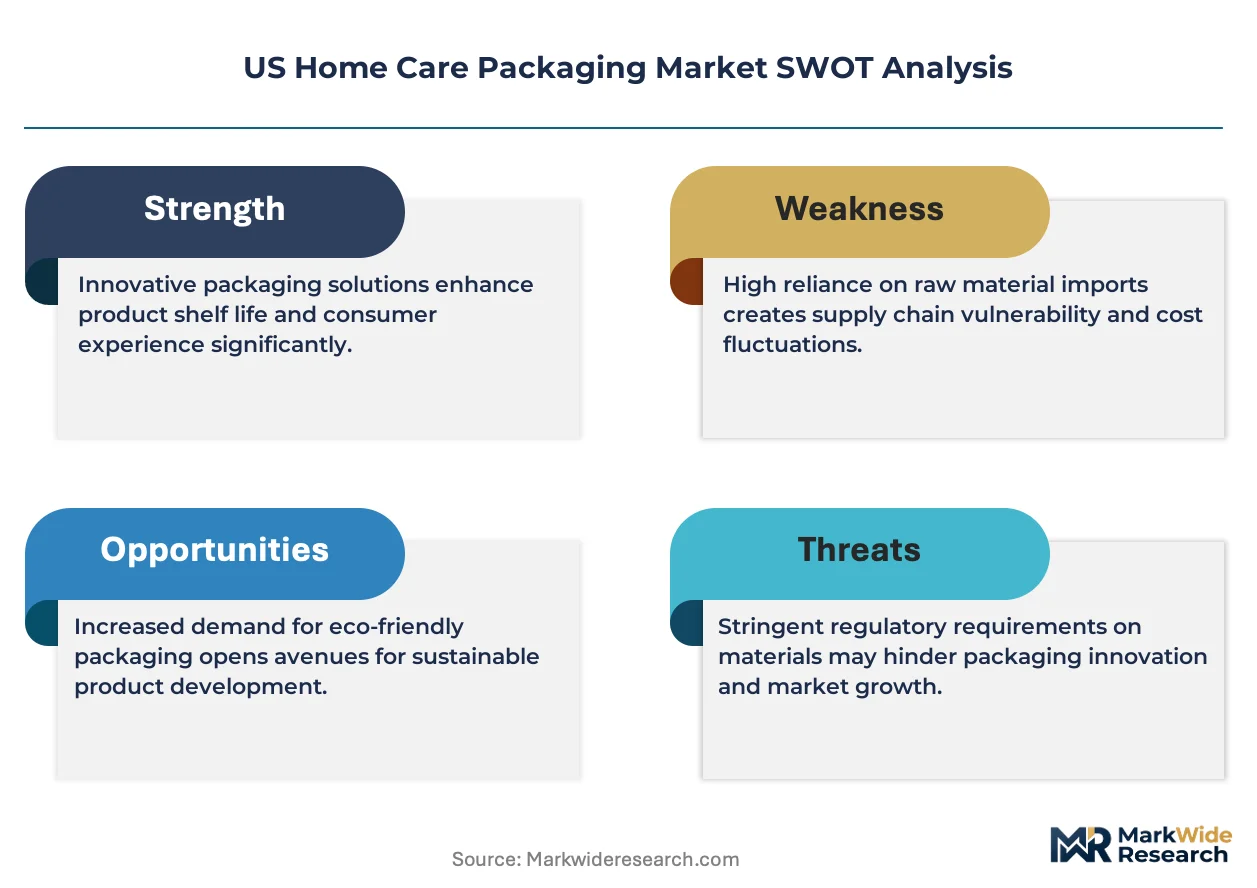
Commercial facilities and healthcare institutions are rotating toward bulk-dispensing and concentrated-format packaging as labor costs and infection-control protocols intensify. AptarGroup leverages precision-dispensing valve technology to sustain contract relationships with institutional janitorial suppliers. Berry Global anchors its position through vertical integration into resin compounding for durable HDPE containers. Amcor competes via lightweighting programs that reduce per-unit freight expenditure across national distribution networks.
US home care packaging encompasses primary and secondary containment systems engineered to preserve chemical stability, enable controlled dispensing, and withstand corrosive formulations including bleach, ammonia, and quaternary ammonium compounds; multilayer coextrusion and fluoropolymer barrier coatings prevent permeation and extend shelf life. Flexible pouches and stand-up formats are capturing the fastest growth as households shift from rigid bottles to refill concentrates that reduce plastic intensity by half. Rigid containers in polypropylene and PET remain the margin pool for premium fragrance and specialty surface cleaners where shelf aesthetics command price premiums.
FDA indirect food-contact regulations, EPA Safer Choice certification requirements, and state-level extended producer responsibility frameworks in California, Oregon, and Maine are elevating recycled-content minimums and restricting single-use virgin plastics. OSHA hazard communication standards further mandate child-resistant closures and durable labeling for caustic formulations. Stakeholders must monitor pending federal packaging legislation and pre-position compliance infrastructure before state patchworks harden into binding national requirements.
Market Dynamics
Extended producer responsibility laws in California, Oregon, and Maine are forcing packaging converters to reengineer material specifications and rebuild supplier networks around post-consumer recycled feedstocks.
Growth Catalysts
- EPA Safer Choice Certification:Household brands pursuing this label are specifying fluoropolymer-free barrier coatings, expanding the addressable market for bio-based alternatives to conventional multilayer structures.
- Refill Concentrate Formats:Flexible pouch demand is accelerating as major retailers dedicate shelf space to dilutable cleaning products that halve plastic intensity per use cycle.
- California SB 54 Mandate:This extended producer responsibility framework requires 25% post-consumer recycled content by 2028, pulling investment toward domestic PCR compounding capacity.
Market Restraints
- Resin Price Volatility:HDPE and polypropylene feedstock costs fluctuate with natural gas liquid yields, compressing margin stability for rigid container specialists.
- Barrier Performance Trade-offs:Current bio-based films lack the oxygen and solvent permeation resistance of fluoropolymer-coated structures, limiting adoption for bleach and ammonia formulations.
- Regional Supply Concentration:Post-consumer recycled resin production clusters in the Gulf Coast and Great Lakes regions, exposing converters to logistics cost spikes during severe weather events.
Strategic Opportunities
- Texas Urban Corridors:Houston and Dallas-Fort Worth metro areas combine high household formation rates with limited refill infrastructure, creating first-mover advantage for concentrated-format distribution networks.
- Monomaterial Flexible Structures:Advances in polyethylene-based barrier films enable full pouch recyclability through store drop-off streams, aligning with How2Recycle labeling requirements.
- Institutional Bulk Dispensing:Healthcare and hospitality sectors are retrofitting janitorial closets with concentrated chemical dilution systems, opening demand for large-format HDPE carboys and precision dosing hardware.
Industry Challenges
- Multilayer Separation Technology:Current mechanical recycling infrastructure cannot process coextruded barrier films, requiring converters to fund advanced sorting equipment or accept limited end-of-life pathways.
- OSHA Hazard Communication Compliance:Caustic formulation packaging must maintain legible GHS labeling through multiple reuse cycles, testing adhesive durability and substrate chemical resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Home Care Packaging Market |
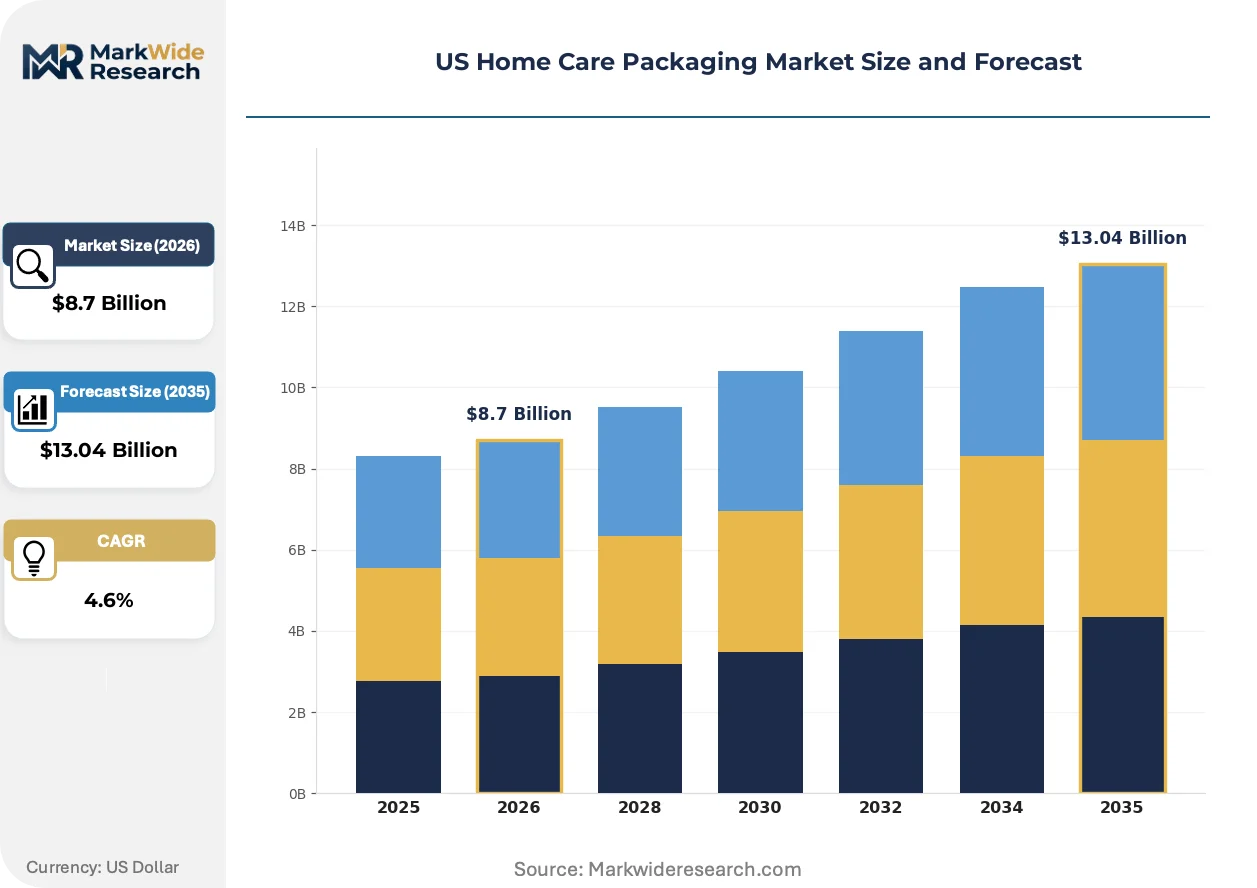
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Bottles, Pouches Material: Plastic, Glass, Metal, Paperboard End User: Households, Commercial Facilities, Healthcare Institutions, Retail Stores Packaging Type: Recyclable, Biodegradable, Multi-Layer, Stand-Up Pouches |
| Companies Covered | AptarGroup, Inc., Ball Corporation, Amcor plc, WestRock, Gerresheimer AG, Berry Global Group, Inc., Silgan Holdings Inc., International Paper Co., Sonoco Products Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Home Care Packaging Market Evolving Landscape
Material science breakthroughs and regulatory compliance deadlines are compressing development cycles for barrier technologies and dispensing systems simultaneously.
Monomaterial polyethylene barrier films with plasma-deposited silicon oxide coatings are decomposing the technical barrier between shelf-life performance and mechanical recyclability. Major household brands in California and New York are piloting these structures for surface cleaner refills. The technology is decomposing the historical trade-off between chemical protection and circular end-of-life processing.
Maine's extended producer responsibility framework requires packaging producers to finance recycling infrastructure based on material type and recyclability tier. This policy is redirecting R&D budgets toward design-for-recycling protocols and third-party certification. Small-format rigid containers for specialty cleaners face the steepest compliance cost escalation.
Direct-to-consumer refill subscription models are fragmenting traditional retail channel dominance for home care products. Concentrate pouches shipped through postal networks bypass shelf-space constraints and enable personalized formulation bundles. This pattern is most pronounced in Pacific Coast metropolitan markets where sustainability preference intensity correlates with e-commerce penetration rates.
US Home Care Packaging Market Segmentation
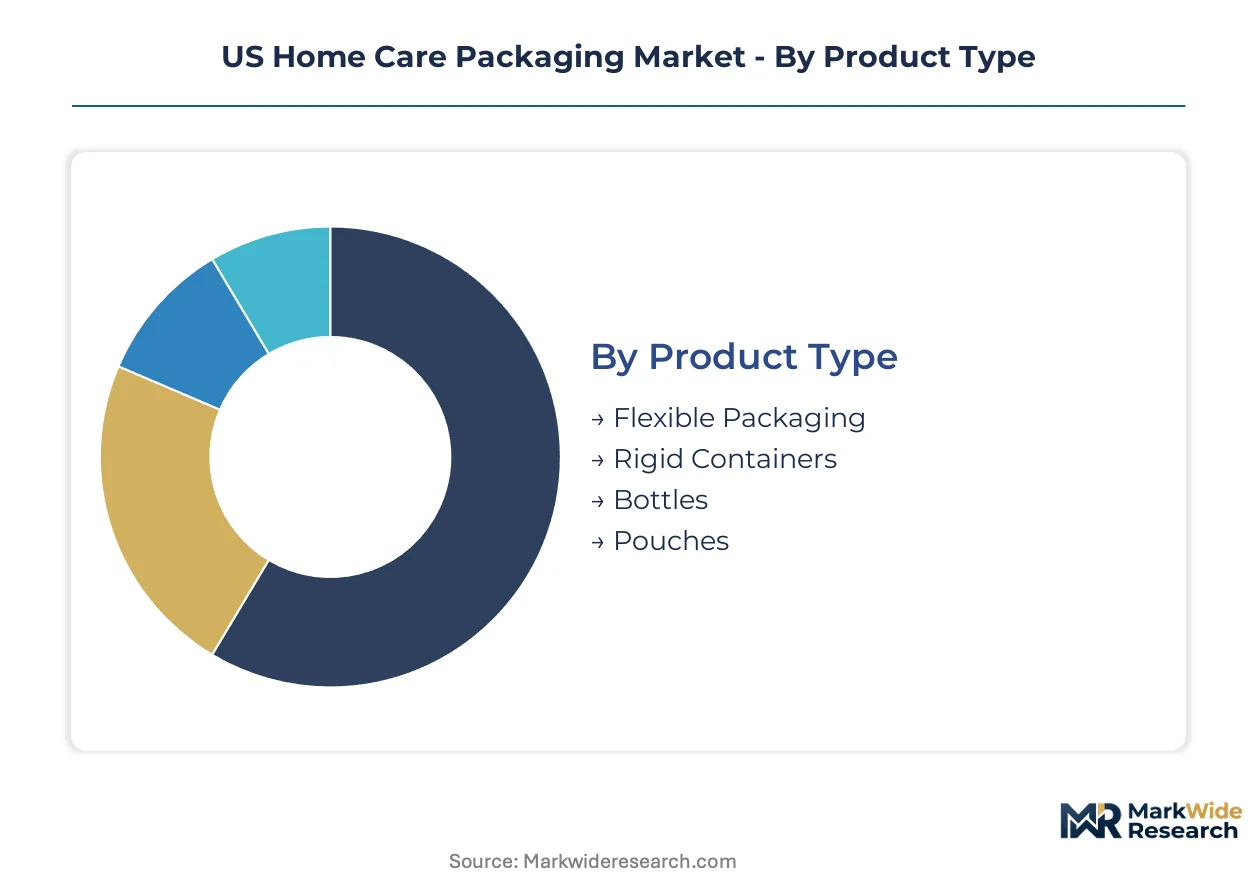
Segmentation in US home care packaging reveals how EPA Safer Choice certification and state EPR mandates are redistributing margin pools across material and format categories. Understanding these divisions exposes where converters must reengineer specifications to maintain contract relationships with institutional buyers and retail channels.
Product Type:
Margin pools concentrate in rigid containers for premium fragrance cleaners and flexible formats for refill concentrates where plastic intensity reductions command shelf placement.
- Flexible Packaging:Multilayer coextruded films with fluoropolymer barrier coatings prevent permeation of bleach and ammonia formulations. Demand clusters in California and New York metro areas where urban households prioritize storage efficiency and sustainability credentials.
- Rigid Containers:HDPE and polypropylene structures withstand corrosive quaternary ammonium compounds while enabling precision dispensing hardware. Commercial facilities in Texas and healthcare institutions specify these for infection-control protocols where durability through multiple reuse cycles justifies unit cost premiums.
- Bottles:PET and HDPE formats dominate premium surface cleaners where shelf aesthetics support price positioning.
- Pouches:Stand-up and flat formats capture dilutable concentrate demand as retailers dedicate linear footage to refill systems.
Rigid containers hold installed capacity. Flexible packaging is rotating up the share rankings.
Material:
Cost tier stratification separates virgin resin specifications for chemical resistance from post-consumer recycled content mandates driving converter supplier network rebuilds.
- Plastic:HDPE, polypropylene, and PET resins form the functional backbone for caustic formulation containment. California SB 54 compliance is forcing specification shifts toward PCR feedstocks that test barrier performance against OSHA hazard communication durability requirements.
- Glass:Premium fragrance and specialty cleaners in California and New York utilize amber and flint containers where perceived quality supports price premiums despite freight cost penalties.
- Metal:Aerosol and pressurized formats serve institutional sanitation applications requiring propellant stability.
- Paperboard:Secondary containment and retail-ready packaging face steepest compliance cost escalation under Maine's EPR framework.
Plastic maintains production dominance. Paperboard is climbing the fastest toward circular design specifications.
End User:
Volume concentration splits between household refill adoption in coastal metros and institutional bulk procurement where labor cost pressures intensify format standardization.
- Households:Eco-conscious purchasers in California, Texas, and New York metro corridors are expanding flexible pouch adoption for dilutable concentrates that halve plastic intensity per cleaning cycle.
- Commercial Facilities:Janitorial contractors in Houston and Dallas-Fort Worth are retrofitting closets with bulk dilution systems requiring large-format HDPE carboys and precision dosing hardware.
- Healthcare Institutions:Infection-control protocols specify rigid containers with child-resistant closures and durable GHS labeling through multiple reuse cycles.
- Retail Stores:Shelf-space constraints in urban markets favor compact flexible formats over rigid bottles for private-label and branded concentrate lines.
Commercial facilities hold procurement scale. Households are expanding most quickly as e-commerce subscription models fragment traditional channel dominance.
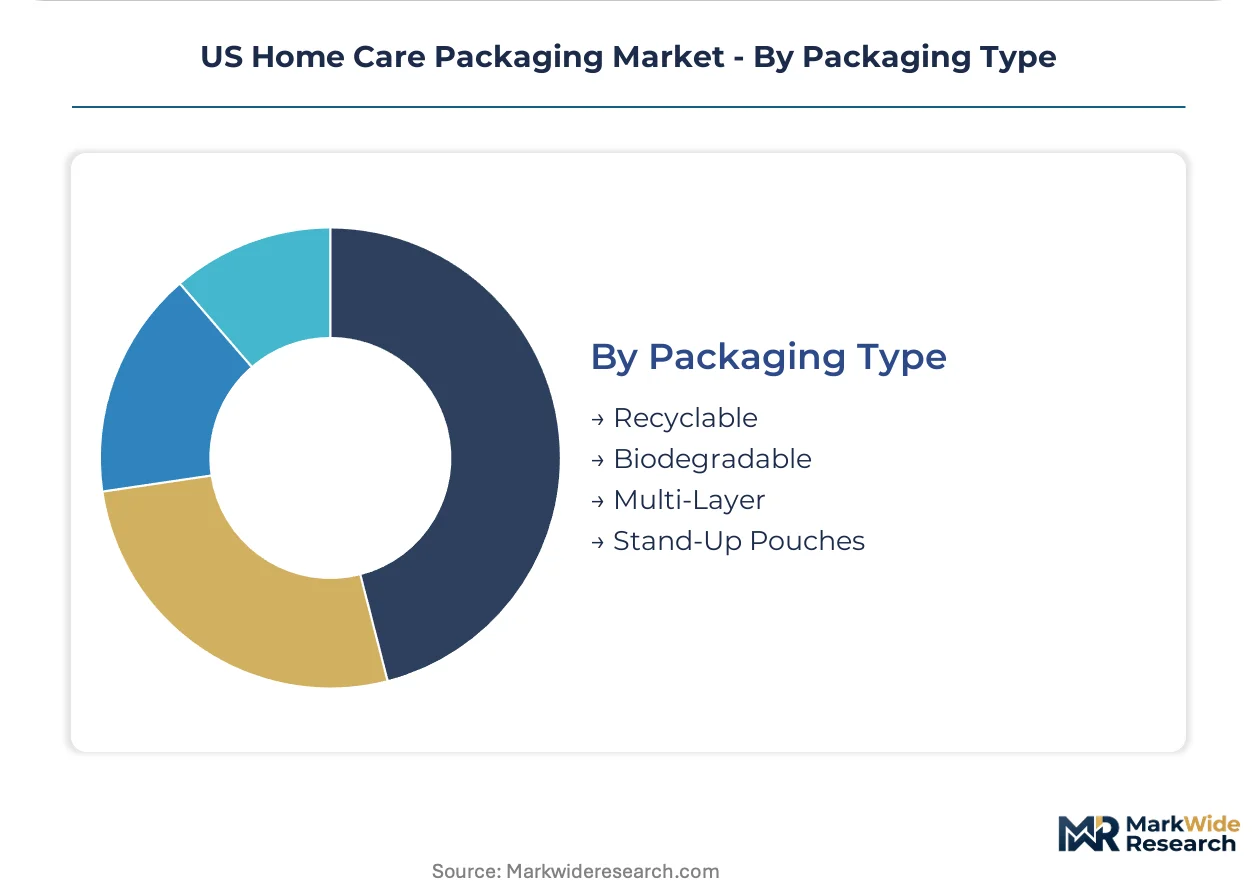
Packaging Type:
Supply concentration clusters around recyclability tier certifications where How2Recycle labeling and store drop-off infrastructure determine format viability.
- Recyclable:Monomaterial polyethylene structures with plasma-deposited silicon oxide coatings enable mechanical processing through existing infrastructure. California and New York pilot programs are validating shelf-life performance against fluoropolymer-coated alternatives.
- Biodegradable:Bio-based films face barrier performance trade-offs for bleach and ammonia formulations that limit adoption to mild surface cleaners.
- Multi-Layer:Coextruded barrier structures maintain chemical stability for caustic formulations but face end-of-life pathway constraints as mechanical recycling infrastructure cannot process adhesive lamination.
- Stand-Up Pouches:Concentrate formats with fitment closures capture retail shelf space and postal distribution efficiency for direct-to-consumer subscription models.
Multi-layer structures hold functional performance leadership. Recyclable formats are gaining share fastest as EPR deadlines compress development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin compounding capacity clusters along the Gulf Coast and Great Lakes corridors, exposing converters to weather-related logistics disruptions. California's SB 54 mandate is pulling investment toward domestic post-consumer recycled feedstock infrastructure. Demand concentrates in coastal metros where sustainability mandates and urban density converge.
California
Eco-conscious households in Los Angeles and San Francisco metro areas are expanding flexible pouch adoption for dilutable cleaning concentrates. SB 54 mandates 25% post-consumer recycled content by 2028, forcing specification shifts toward PCR feedstocks. The Central Valley hosts emerging mechanical recycling infrastructure serving West Coast flexible packaging converters.
Texas
Houston and Dallas-Fort Worth combine high household formation rates with limited refill infrastructure, creating first-mover opportunities for concentrated-format distribution networks. The state's petrochemical corridor supplies virgin HDPE and polypropylene resins to rigid container specialists. Gulf Coast weather events periodically disrupt resin logistics, compressing margin stability for regional converters.
New York
Urban density in the New York metro area favors compact flexible formats over rigid bottles for retail shelf efficiency. The state's extended producer responsibility framework aligns with Maine and Oregon in elevating recycled-content minimums. Brooklyn and Queens distribution centers are piloting direct-to-consumer refill subscription fulfillment for Pacific Coast brands.
Illinois
Chicago's central logistics position anchors national distribution networks for institutional bulk dispensing systems. The state's manufacturing base supplies precision dosing hardware to healthcare and hospitality janitorial contractors. Great Lakes resin production clusters expose converters to winter logistics constraints and Canadian feedstock import dependencies.
Oregon
Portland metro households demonstrate early adoption of monomaterial polyethylene pouch structures with plasma-deposited silicon oxide coatings. The state's extended producer responsibility law predates California SB 54, establishing compliance infrastructure that West Coast brands leverage for multi-state certification. Willamette Valley recycling facilities process store drop-off streams for How2Recycle-labeled flexible formats.
US Home Care Packaging Market Competitive Landscape
Concentration sits with diversified packaging conglomerates that control resin compounding and precision dispensing technology simultaneously. The vendor base spans three tiers: multinational material science platforms with captive PCR supply, mid-cap rigid container specialists serving institutional buyers, and regional flexible film converters targeting retail refill channels. Competitive moves center on backward integration into PCR compounding capacity and technology licensing for monomaterial barrier coatings.
Within the multinational platform tier, AptarGroup, Amcor, and Berry Global exemplify divergent strategic anchors. AptarGroup occupies a position concentrated on precision-dispensing valve technology for institutional janitorial relationships. Amcor exemplifies lightweighting programs that reduce per-unit freight expenditure across national distribution networks. Berry Global anchors a vertically integrated posture through in-house resin compounding for durable HDPE containers. These three entities collectively represent the functional segmentation—dispensing systems, freight optimization, and material supply—that defines competitive positioning in this market.
| Leading Market Players |
|---|
| AptarGroup, Inc. |
| Ball Corporation |
| Amcor plc |
| WestRock |
| Gerresheimer AG |
| Berry Global Group, Inc. |
| Silgan Holdings Inc. |
| International Paper Co. |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
Sixty-day resin inventory cycles at Gulf Coast compounding facilities anchor pricing power for HDPE container specialists serving Texas institutional buyers. California SB 54 compliance deadlines compress these lead times as converters scramble for PCR feedstock access, forcing spot-market premiums that ripple through rigid container pricing tiers.
Pricing Analysis
California SB 54 dictates the pricing tier structure across the US home care packaging landscape. Three-tier pricing separates premium fluoropolymer-coated multilayer films from standard HDPE containers and economy-grade paperboard secondary packaging. Price differentiation rests on EPA Safer Choice certification status and post-consumer recycled content percentages. Pricing pressure stems from resin cost volatility tied to natural gas liquid yields, with spot HDPE commanding premiums during Gulf Coast weather disruptions. Private-label retail channels exhibit acute price sensitivity, while healthcare institutions absorb higher unit costs for OSHA-compliant child-resistant closure systems.
Supply Chain Analysis
Strategic stockpiling of PCR resin dominates inventory strategy as California's 2028 mandate deadlines approach. Domestic supply concentrates in Texas, Louisiana, and Ohio where petrochemical corridors and Great Lakes recycling infrastructure cluster. Raw material dependencies center on natural gas liquids for virgin resin, post-consumer bale supply from municipal collection systems, and silicon oxide precursor chemicals for barrier coatings. Single-source vulnerability runs through Gulf Coast resin production exposed to hurricane-season logistics chokepoints. Distribution runs through Chicago hub-and-spoke networks for institutional bulk dispensing systems and direct-to-consumer postal fulfillment for Pacific Coast subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with converters capable of bridging the gap between California EPR compliance and Texas volume scale. Direct-to-consumer refill subscriptions fragment traditional retail channel concentration, creating niche entry points for specialized flexible film producers.
For Market Incumbents: Shield contract relationships with institutional janitorial suppliers by accelerating backward integration into domestic PCR compounding capacity. AptarGroup-style precision-dispensing technology licensing defends against emerging monomaterial barrier coating specialists. Berry Global's captive resin supply model offers the defensive template for margin preservation against spot-market volatility.
For New Entrants and Emerging Players: Differentiate on monomaterial polyethylene barrier performance validated through How2Recycle store drop-off certification. Texas urban corridors present the most penetrable geography given limited refill infrastructure against high household formation rates. Direct-to-consumer subscription fulfillment partnerships with Pacific Coast brands offer the clearest go-to-market angle bypassing shelf-space constraints.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EPR deadline clustering across California, Oregon, and Maine creates acquisition targets with multi-state compliance infrastructure already embedded. Mid-cap flexible film converters with plasma-deposited coating pilot lines represent the priority acquisition archetype. The signal to watch is EPA Safer Choice certification volume crossing threshold mass for fluoropolymer-free formulation adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| PCR Compounding Capacity Expansion | California SB 54 compliance secures contract renewals with institutional buyers facing 2028 deadlines. |
| Monomaterial Barrier Film Certification | How2Recycle validation opens retail shelf placement in urban markets with store drop-off infrastructure. |
| Precision Dispensing Technology Licensing | AptarGroup-style valve systems defend janitorial supply relationships against commodity container competition. |
| Direct-to-Consumer Subscription Infrastructure | Brooklyn and Queens fulfillment pilots capture Pacific Coast brand demand bypassing traditional retail. |
| OSHA-Compliant Labeling Durability Investment | GHS adhesive performance through multiple reuse cycles commands healthcare institutional premiums. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA Safer Choice certification databases, state EPR regulatory filings, and resin trade flow data. Primary interviews engaged packaging converter operations managers, institutional janitorial procurement directors, retail category buyers, and flexible film R&D leads. Secondary validation drew from OSHA hazard communication standards documentation, How2Recycle labeling protocols, and American Chemistry Council resin production reports. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Segmentation dimensions modeled include packaging format (flexible pouch, rigid container, bottle), material specification (virgin HDPE, PCR-blend, monomaterial polyethylene), end-user archetype (household, commercial facility, healthcare institution), and regional regulatory cluster (California SB 54, Oregon EPR, Maine EPR). CAGRs derived from regression analysis of historical adoption curves for refill concentrate formats cross-referenced with EPR deadline proximity effects. Industry-specific forecast inputs incorporated silicone oxide barrier coating pilot scale-up timelines and municipal PCR collection capacity expansion schedules.
The analysis sits within stated boundaries; outcomes outside sustained EPR enforcement intensity or resin price stability assumptions would require recalibration. Forecasts embed assumptions regarding mechanical recycling infrastructure deployment rates and OSHA labeling durability standards persistence. Revision becomes warranted when bio-based barrier performance crosses permeation resistance thresholds for bleach formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
North America Medical Devices Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Transplant Box Market