
 Asia-Pacific Parenteral Packaging Market | 2026-2036
Asia-Pacific Parenteral Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Parenteral Packaging Market Outlook
Biologics contract manufacturers is unwinding share from traditional small-molecule generic injectable buyers across the Asia-Pacific parenteral packaging landscape. West Pharmaceutical Services anchors its position through elastomeric closure specialization for high-value biologics. SCHOTT AG dominates borosilicate glass supply for premium vial and cartridge formats. NIPRO CORPORATION leverages its vertically integrated polymer and glass operations across Japanese and Southeast Asian manufacturing nodes.
Asia-Pacific parenteral packaging encompasses sterile container and closure systems engineered for drug products administered outside the gastrointestinal tract, typically fabricated from Type I borosilicate glass, cyclic olefin polymers, or multilayer films with dimensional tolerances below 0.1 millimeters to ensure seal integrity under autoclave and gamma sterilization protocols. Its primary purpose is maintaining sterility, chemical stability, and dosing precision for injectable therapeutics from manufacture through patient administration. Vials and cartridges command the deepest margin pools as biologics and GLP-1 formulations drive demand for higher-performance barrier properties and reduced extractables profiles. Plastic infusion bags are displacing rigid containers in hospital and home care settings where portability and reduced breakage risk outweigh premium material costs. Glass retains structural dominance in vaccine and cytotoxic applications where oxygen and moisture barrier specifications remain non-negotiable.
China's NMPA enforces escalating GB pharmacopoeial standards for glass delamination and visible particle limits, forcing domestic converters toward imported or joint-venture glass tubing sources. India's CDSCO aligns with ICH Q1A stability guidelines while its PLI scheme for pharmaceuticals incentivizes local capacity for prefillable syringes and complex closures. Japan's PMDA maintains JIS-compliant traceability requirements that shape supplier qualification timelines. Stakeholders must monitor how divergent sterilization validation protocols across these three regulatory jurisdictions reshape regional sourcing strategies and capital deployment priorities.
Market Dynamics
Biologics fill-finish operations across Asia-Pacific are forcing rapid container system upgrades as GLP-1 therapies and mRNA vaccines demand higher barrier integrity and extractables control than traditional small-molecule packaging.
Growth Catalysts
- Prefillable Syringe Migration:India's PLI scheme for pharmaceuticals incentivizes domestic capacity for complex closure systems serving regulated export markets.
- GB Pharmacopoeia Stringency:China's tightened glass delamination standards push domestic converters toward certified borosilicate tubing sources.
- Home Care Infusion Expansion:Plastic multilayer bags are capturing volume from rigid glass as hospital-at-home protocols spread across Japan and Australia.
Market Restraints
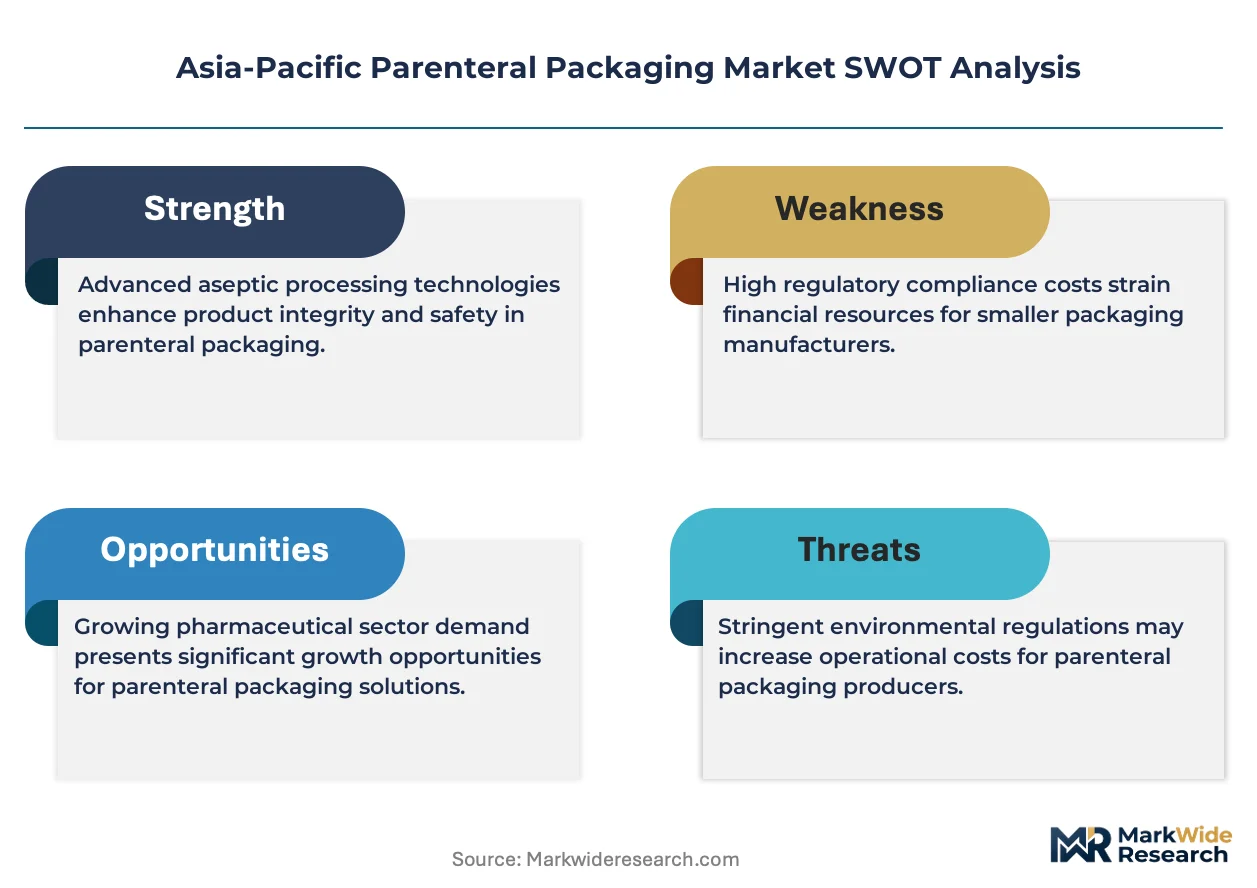
- Specialized Glass Supply Concentration:Premium Type I borosilicate tubing for high-value vials remains captive to limited German and Japanese furnace capacity.
- Cyclic Olefin Polymer Feedstock Volatility:COC resin prices fluctuate with naphtha cracking economics, compressing margin on polymer syringe barrels.
- Sterilization Validation Divergence:Autoclave, gamma, and e-beam protocols vary across China's NMPA, India's CDSCO, and Japan's PMDA, fragmenting equipment qualification.
Strategic Opportunities
- Southeast Asian Manufacturing Nodes:Vietnam and Thailand offer underutilized cleanroom infrastructure for contract packaging serving Australian TGA submissions.
- Ready-to-Use System Integration:Pre-sterilized nested vial and closure formats converge with isolator-based fill-finish lines to cut line clearance times.
- Dual-Carbon Compliance Positioning:China's MEE carbon intensity targets create first-mover advantage for low-energy glass melting and polymer recycling technologies.
Industry Challenges
- Isolator Engineering Talent Scarcity:Qualified technicians for restricted access barrier system validation remain concentrated in Japan and South Korea.
- Extractables Study Burden:Biologics sponsors demand comprehensive USP <665> and <1665> compliance documentation, extending supplier qualification timelines.
- Legacy Glass-to-Polymer Line Conversion:Existing depyrogenation tunnels and washing stations require complete replacement for cyclic olefin polymer handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Parenteral Packaging Market |
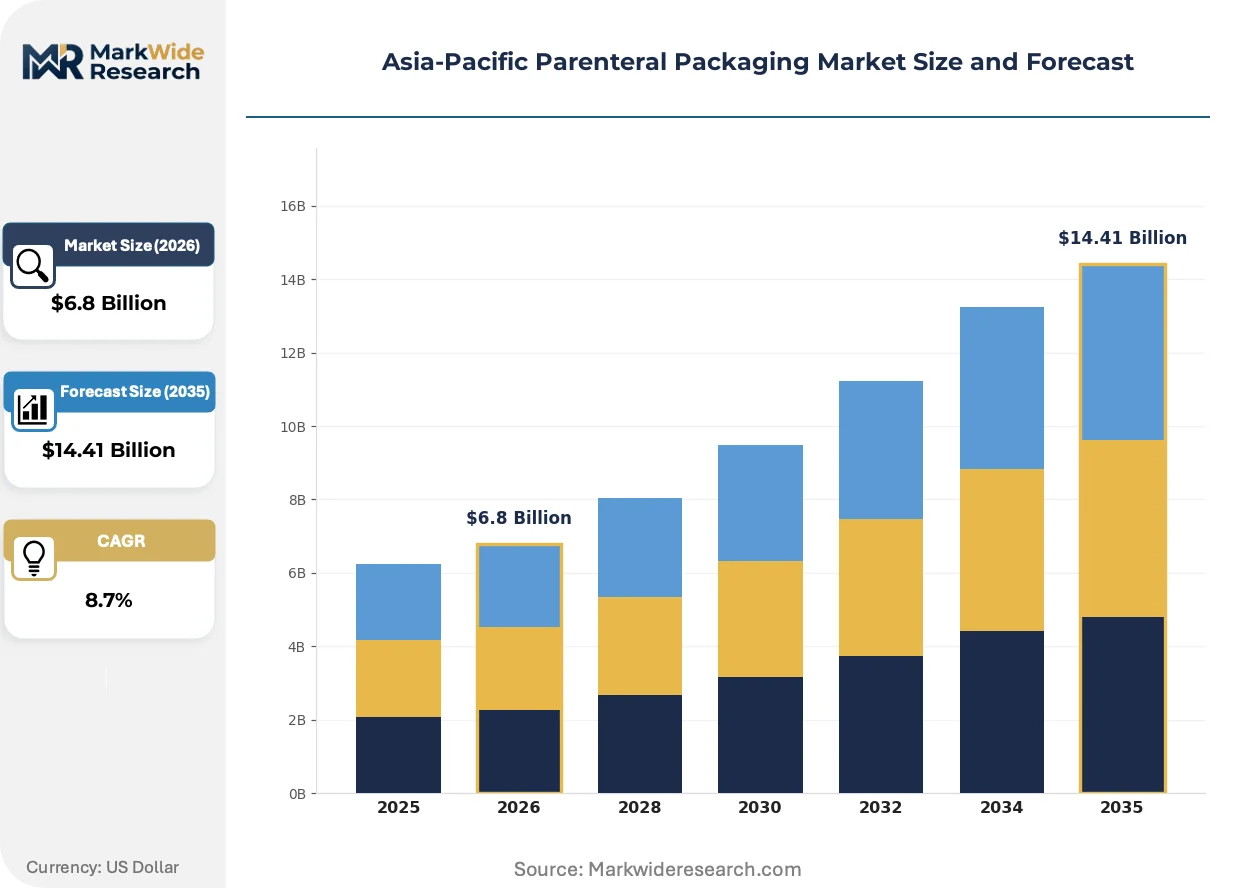
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Cartridges, Infusion Bags Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intraarterial Material: Glass, Plastic, Rubber, Composite End User: Hospitals, Clinics, Home Care, Pharmaceutical Companies |
| Companies Covered | West Pharmaceutical Services, Amcor PLC, AptarGroup, Inc., Gerresheimer AG, SCHOTT AG, SGD Pharma, Becton, Dickinson and Company, NIPRO CORPORATION, Berry Global Group, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Parenteral Packaging Market Strategic Shifts
Container-closure engineering across Asia-Pacific is compressing toward higher-performance formats as biologics sponsors reject commodity packaging for critical therapies.
Cyclic olefin polymer syringe barrels are miniaturizing dead-space volumes while maintaining dimensional tolerances for autoinjector integration. Korean and Japanese device developers are accelerating adoption for GLP-1 dosing regimens. This material shift is compressing glass market share in chronic self-injection categories where breakage risk and weight drive patient preference.
China's NMPA is enforcing visible particle limits under revised GB standards that exceed prior USP <788> equivalence. Domestic vial converters are requalifying supplier bases toward joint-venture borosilicate sources. Vaccine and cytotoxic applications in Shanghai and Suzhou manufacturing clusters are absorbing the highest compliance costs.
Buying patterns among Indian contract manufacturers are compressing supplier panels as CDSCO-aligned ICH Q1A stability requirements raise technical qualification barriers. Single-source elastomeric closure relationships are displacing multi-vendor rotations previously common in generic injectables. This concentration is most visible in Hyderabad and Ahmedabad export corridors serving FDA-inspected facilities.
Asia-Pacific Parenteral Packaging Market Segmentation
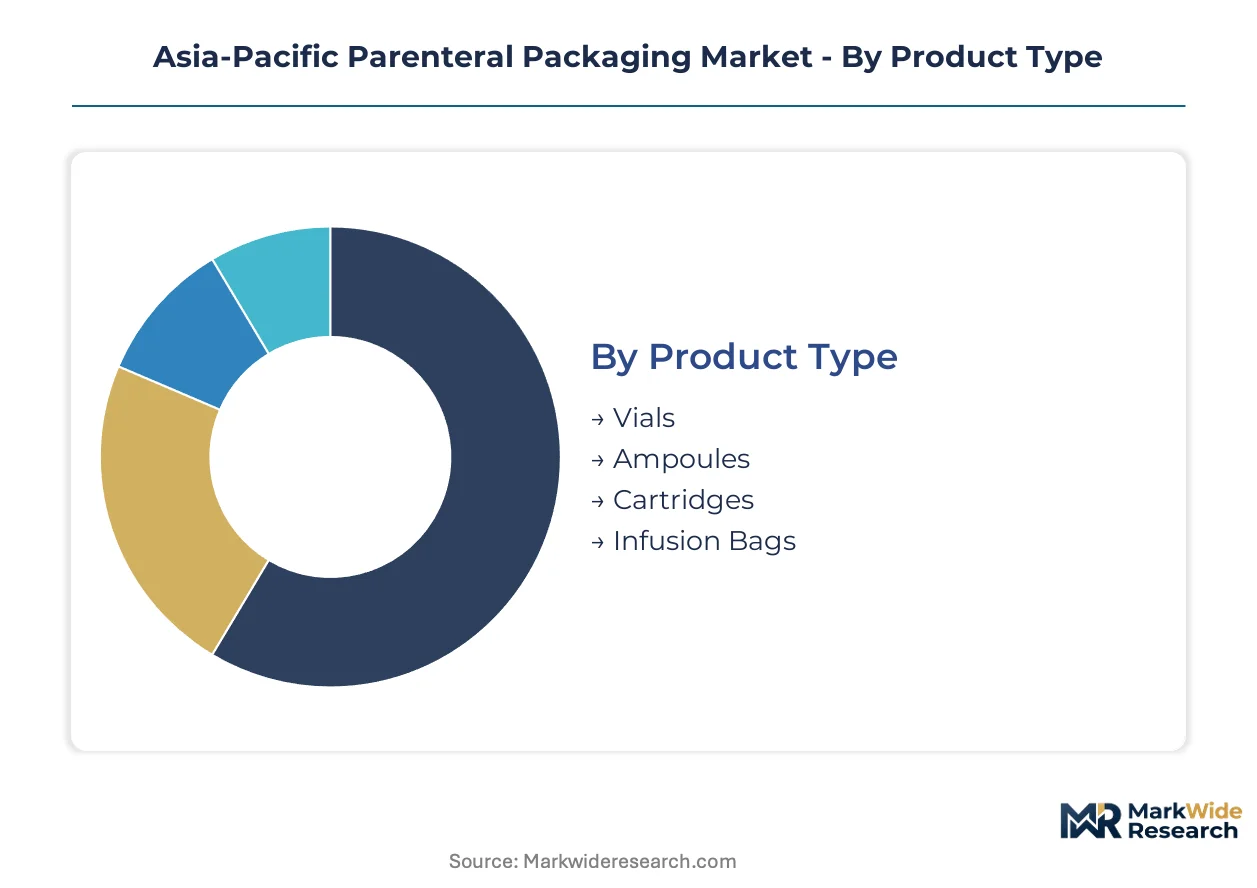
Segmentation in Asia-Pacific parenteral packaging reveals how regulatory stringency, biologics formulation requirements, and sterilization protocols reshape procurement patterns across container formats and delivery modes. Understanding these divisions exposes where capital flows concentrate and which material specifications command premium positioning.
Product Type:
China's NMPA enforces divergent visible particle and delamination thresholds across container formats, forcing converters to maintain separate supplier qualifications and sterilization validations for each product category.
- Vials:Type I borosilicate glass dominates vaccine and cytotoxic applications where oxygen and moisture barrier specifications remain non-negotiable under NMPA GB standards. Demand concentrates in Shanghai and Suzhou manufacturing clusters as biologics sponsors reject commodity packaging for critical therapies.
- Cartridges:Precision-molded glass or cyclic olefin polymer barrels integrate with autoinjector platforms for GLP-1 dosing regimens across Japan and South Korea. Korean device developers are accelerating adoption as chronic self-injection categories expand.
- Ampoules:Single-dose glass units serve emergency and anesthetic applications where immediate access overrides multi-dose convenience.
- Infusion Bags:Multilayer plastic films displace rigid containers in hospital-at-home protocols across Australia and Japan where portability and reduced breakage risk outweigh premium material costs.
Vials handle the majority of throughput; infusion bags are expanding most quickly on share as home care protocols spread.
Delivery Mode:
Cost tier differentiation separates acute hospital administration from chronic self-injection, with subcutaneous formats commanding premium closure engineering and patient-centric design investment.
- Intravenous:Large-volume infusion systems require validated compatibility with peristaltic pumps and gravity drip sets across tertiary hospitals in India and China.
- Subcutaneous:Prefillable syringes and autoinjector-integrated cartridges miniaturize dead-space volumes while maintaining dimensional tolerances below 0.1 millimeters. Japanese and Korean device developers drive specification escalation for biologics and GLP-1 therapies.
- Intramuscular:Vaccine administration favors single-dose vial and prefilled syringe formats with robust cold-chain stability.
- Intraarterial:Specialized catheter-compatible packaging serves interventional radiology and oncology suites with exacting sterility assurance levels.
Intravenous formats dominate hospital procurement volumes; subcutaneous delivery is gaining share fastest as biologics migrate from clinical to home settings.
Material:
Supply concentration for premium inputs—Type I borosilicate tubing and cyclic olefin polymer resin—determines which converters can serve regulated export markets versus domestic-only applications.
- Glass:Borosilicate formulations from German and Japanese furnace capacity remain captive for high-value vial and cartridge production. China's domestic converters face requalification pressure under tightened GB pharmacopoeial standards.
- Plastic:Cyclic olefin polymer and multilayer films enable lighter, break-resistant alternatives for infusion bags and syringe barrels. Resin price volatility with naphtha cracking economics compresses margins on polymer syringe production.
- Rubber:Elastomeric closures and plunger stoppers require extractables profiling under USP standards for biologics compatibility.
- Composite:Laminated structures combine barrier polymers with structural substrates for specialized oxygen-sensitive formulations.
Glass retains structural dominance in vaccine and cytotoxic categories; plastic is climbing the fastest as hospital-at-home protocols expand across Japan and Australia.
End User:
Customer type dictates packaging complexity tiers, with pharmaceutical companies and home care settings driving divergent specification requirements for barrier integrity and patient handling.
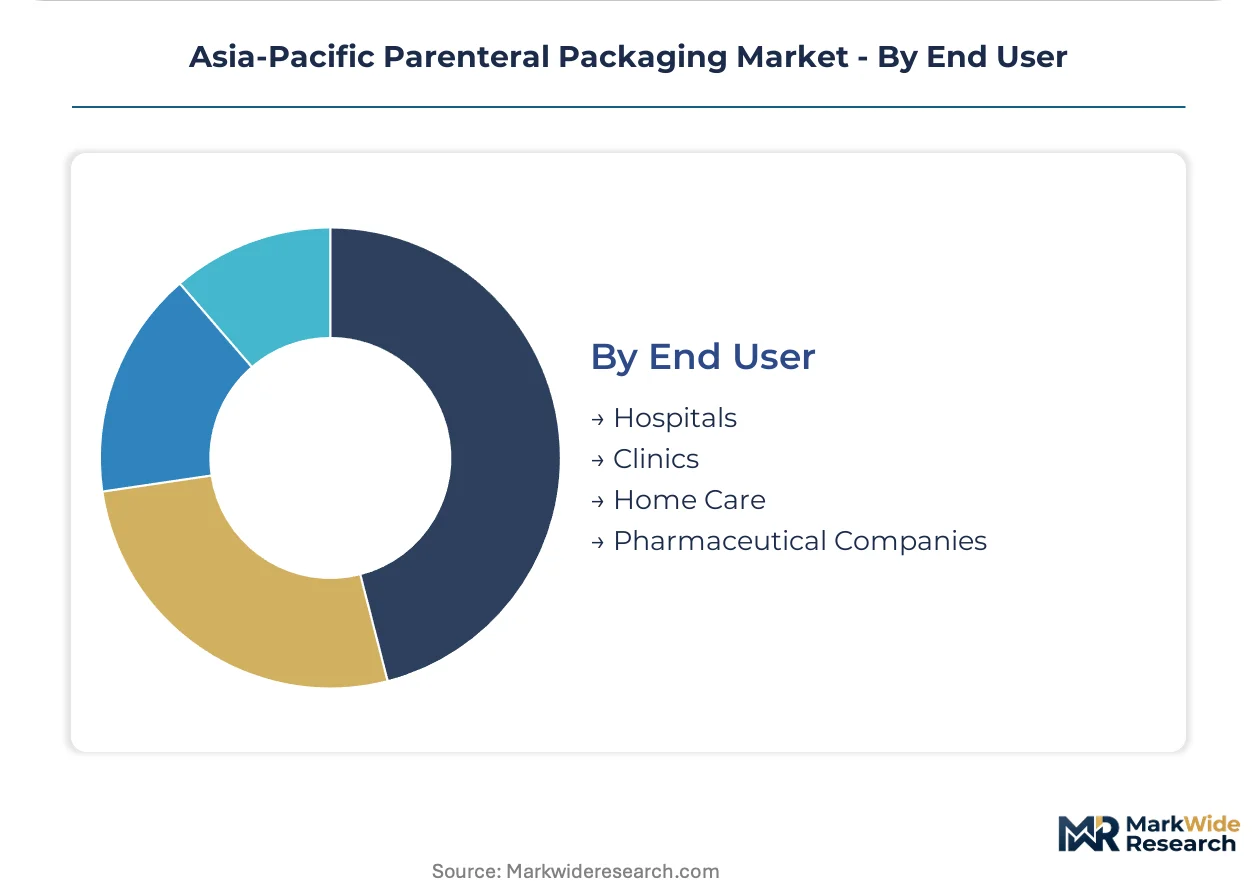
- Pharmaceutical Companies:Sponsors of biologics and GLP-1 therapies demand comprehensive USP extractables documentation and isolator-compatible ready-to-use formats. Indian contract manufacturers in Hyderabad and Ahmedabad are consolidating supplier panels under CDSCO-aligned ICH Q1A stability requirements.
- Home Care:Patients and caregivers require intuitive, breakage-resistant designs with extended ambient stability for subcutaneous self-administration.
- Hospitals:Central pharmacy operations prioritize standardized infusion sets and pump-compatible bag formats with validated sterility assurance.
- Clinics:Outpatient settings favor cost-optimized single-dose formats with minimal preparation complexity.
Pharmaceutical companies anchor procurement value; home care is expanding most rapidly on volume as chronic disease management shifts outside institutional settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in pharmaceutical export logistics, while Singapore's Changi cargo hub funnels specialized packaging materials into Southeast Asian manufacturing nodes.
China
Domestic biologics manufacturing in Suzhou and Shanghai is absorbing premium borosilicate vial capacity as NMPA tightens GB pharmacopoeial standards for glass delamination. The Yangtze River Delta manufacturing cluster is requalifying supplier bases toward joint-venture glass tubing sources to meet visible particle limits exceeding prior USP equivalence.
India
Contract manufacturers in Hyderabad and Ahmedabad are upgrading fill-finish lines to serve FDA-inspected facilities in Europe and North America. CDSCO alignment with ICH Q1A stability guidelines is compressing supplier panels as single-source elastomeric closure relationships displace multi-vendor rotations common in generic injectables.
Japan
Chronic self-injection categories are driving specification escalation for GLP-1 therapies as Korean and Japanese device developers accelerate adoption of cyclic olefin polymer syringe barrels. PMDA's JIS-compliant traceability requirements are shaping supplier qualification timelines across the Kanto and Kansai industrial corridors.
South Korea
Autoinjector platform integration is concentrating demand for precision-molded cartridges with dimensional tolerances below 0.1 millimeters. The Seoul Capital Area's device engineering ecosystem is capturing regional development contracts for biologics delivery systems as MFDS sterilization validation protocols align with export market requirements.
Australia
Hospital-at-home protocols are expanding procurement of multilayer plastic infusion bags as TGA submissions from Vietnamese and Thai contract manufacturers seek Australian market access. Port infrastructure in Melbourne and Sydney is handling increased volume of ready-to-use nested vial formats for isolator-based fill-finish operations.
Asia-Pacific Parenteral Packaging Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory certification tiers, creating a bifurcated structure where scale advantages in glass melting confront agility premiums in polymer conversion. Tier-one positions concentrate around integrated tubing-to-vial operations and elastomeric closure specialization. Tier-two slots fragment across regional converters with isolator-compatible formatting capabilities. Competitive moves center on backward integration into certified borosilicate furnace capacity and strategic partnerships with biologics sponsors for USP extractables documentation.
Among Germany-based fabricators, SCHOTT AG and Gerresheimer AG occupy positions anchoring premium glass supply for high-value vial and cartridge formats. West Pharmaceutical Services exemplifies the elastomeric closure specialization archetype. These three entities represent distinct competitive vectors: captive furnace operations, precision molding integration, and barrier component engineering.
| Leading Market Players |
|---|
| West Pharmaceutical Services |
| Amcor PLC |
| AptarGroup, Inc. |
| Gerresheimer AG |
| SCHOTT AG |
| SGD Pharma |
| Becton, Dickinson and Company |
| NIPRO CORPORATION |
| Berry Global Group, Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory buffers for Type I borosilicate tubing concentrate pricing power among German and Japanese furnace operators, while Chinese converters absorb compliance premiums under NMPA's tightened GB standards. This lead-time structure rewards backward-integrated suppliers with captive glass melting capacity and penalizes regional converters dependent on spot-market polymer resin.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates isolator-ready nested formats from conventional washed-and-depyrogenated vials from commodity ampoules. Price differentiation hinges on USP extractables documentation depth and NMPA certification tier, with biologics sponsors least sensitive and Indian generic injectable exporters most sensitive to unit cost. Cost compression in standard-tier glass vials is intensifying because Chinese domestic converters are requalifying toward joint-venture borosilicate sources.
Supply Chain Analysis
Inventory cycles for cyclic olefin polymer resin stretch sixty to ninety days, exposing converters to naphtha cracking volatility. Supply concentrates in Germany, Japan, and China for premium borosilicate tubing; South Korea and Japan for precision-molded cartridges; and Vietnam and Thailand for emerging cleanroom conversion capacity. Single-source vulnerability runs through German furnace capacity for vaccine-grade glass. Distribution runs through Shanghai's container port for Chinese domestic supply and Singapore's Changi cargo hub for Southeast Asian manufacturing nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Indian contract manufacturers as CDSCO-aligned ICH Q1A requirements compress supplier panels from multi-vendor rotations toward single-source elastomeric closure relationships.
For Market Incumbents: Compound isolator-compatible ready-to-use format penetration to lock in biologics sponsor relationships before Korean device developers capture GLP-1 cartridge integration contracts. Prioritize backward integration into certified borosilicate furnace capacity to defend margin position against Chinese joint-venture glass tubing expansion. The threat of polymer syringe barrel miniaturization for autoinjector platforms demands immediate dimensional tolerance capability investment. For New Entrants and Emerging Players: Differentiate on USP extractables study bundling for mid-tier Indian contract manufacturers in Hyderabad and Ahmedabad export corridors. Target Vietnam and Thailand cleanroom infrastructure for Australian TGA submission pathways, where isolator engineering talent scarcity creates qualification timeline gaps. The most penetrable segment is pre-sterilized nested vial formats for hospital-at-home protocols across Japan and Australia. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cyclic olefin polymer syringe barrel production as Korean and Japanese device developers escalate specification requirements for GLP-1 therapies. Acquisition candidates with isolator-compatible formatting capabilities and existing USP documentation portfolios offer superior long-term viability. Watch for NMPA enforcement actions on visible particle limits as the signal indicating which Chinese converters will survive supplier base consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Furnace Capacity | Captive Type I tubing supply secures NMPA GB compliance for Shanghai and Suzhou manufacturing clusters. |
| Isolator-Compatible Ready-to-Use Format Launch | Pre-sterilized nested vial and closure systems cut line clearance times for biologics fill-finish operations. |
| USP Extractables Documentation Investment | Compliant USP 665 and 1665 profiling accelerates supplier qualification timelines for CDSCO-aligned sponsors. |
| Southeast Asian Cleanroom Infrastructure Expansion | Vietnam and Thailand nodes capture Australian TGA submission volume from underutilized regional capacity. |
| Dual-Carbon Compliance Technology Deployment | Low-energy glass melting aligns with China's MEE carbon intensity targets for first-mover positioning. |
Study Parameters
Initial hypotheses were tested against primary input from biologics fill-finish operations directors, elastomeric closure procurement managers, regulatory affairs leads at CDSCO and NMPA, and isolator validation engineers; these were refined against secondary validation from FDA 483 inspection observations, EMA packaging guidelines, USP compendial updates, and customs trade data for borosilicate glass tubing imports. Bottom-up segment sizing triangulated with top-down market boundary checks.
Variance decomposition across product type, delivery mode, material composition, and end-user procurement tier shaped the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating GLP-1 therapy expansion trajectories and sterilization protocol divergence across NMPA, CDSCO, and PMDA jurisdictions. Forecast inputs included contract manufacturer capital expenditure announcements for fill-finish line upgrades and joint-venture glass tubing facility commissioning timelines.
The analysis sits within stated boundaries; outcomes outside sustained biologics pipeline expansion or abrupt polymer feedstock cost shocks would require recalibration. Forecasts reflect documented assumptions about regulatory enforcement intensity and sponsor qualification behavior. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
North America Medical Devices Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market