
 Medical Implants Sterile Packaging Market | 2026-2036
Medical Implants Sterile Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Implants Sterile Packaging Market Outlook
A shift from single-source to multi-source sterile barrier supply is repositioning how orthopedic and cardiovascular device firms manage packaging risk. Amcor plc leverages global film extrusion networks to serve implant OEMs across multiple continents. Nelipak Healthcare anchors its position through cleanroom thermoforming capacity concentrated near major device manufacturing hubs. West Pharmaceutical Services differentiates via integrated elastomer and packaging combinations for drug-device combination implants.
Medical implants sterile packaging comprises engineered polymer structures—Tyvek lidding, polyethylene films, and thermoformed trays—designed to maintain sterility through terminal sterilization, distribution, and aseptic presentation at the point of use. These systems must achieve specified microbial barrier performance, seal integrity under accelerated aging, and compatibility with ethylene oxide, gamma, or steam sterilization modalities. Pouches and trays dominate current volume as legacy formats with established validation pathways, while roll stock gains traction in automated packaging lines serving high-throughput implant manufacturers. Tyvek maintains premium positioning due to its breathable sterilization compatibility and tear-resistant fiber structure, though polyethylene alternatives compete on cost for lower-risk implant classes.
FDA 21 CFR Part 820 quality system regulations and EU MDR Annex I general safety and performance requirements govern sterile barrier validation, biocompatibility, and post-market surveillance for implant packaging. ISO 11607 standards for packaging materials and systems provide the harmonized technical foundation that both FDA and notified bodies reference during conformity assessment. Stakeholders must monitor evolving EUDAMED traceability mandates and FDA digital submission pathways, as these frameworks will determine which packaging technologies achieve sustainable market access across major regulatory jurisdictions.
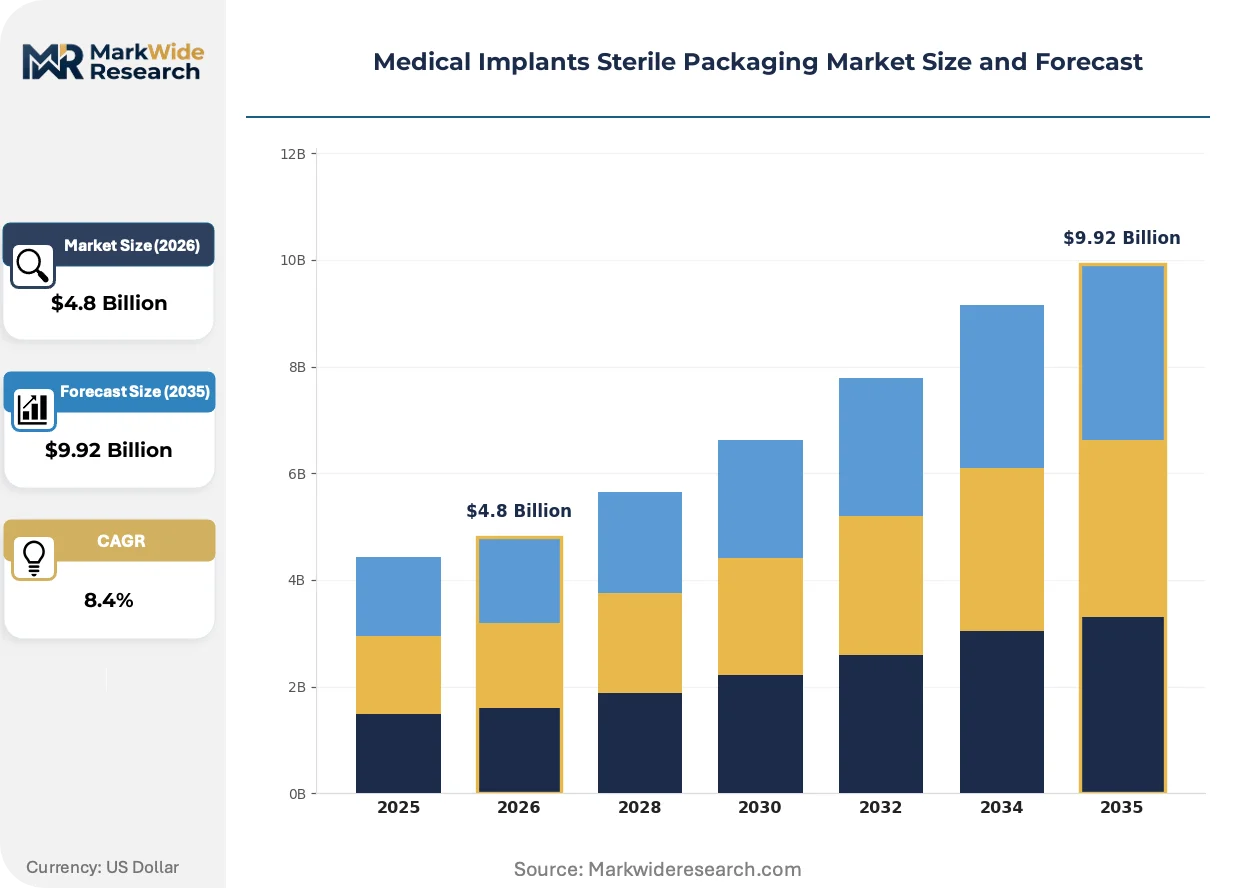
Market Dynamics
EU MDR Annex I general safety and performance requirements are compressing sterile barrier validation timelines while forcing implant OEMs to consolidate supplier bases around notified body-approved packaging systems.
Growth Catalysts
- Orthopedic surgical volume expansion:Rising joint replacement procedures in aging populations across Germany, the United States, and Japan are pulling demand for validated tray and pouch systems through hospital supply chains.
- ISO 11607 harmonization:The unified technical foundation for packaging materials and systems is reducing multi-jurisdictional validation costs and accelerating cross-border sterile barrier approvals.
- Ethylene oxide sterilization persistence:Despite environmental pressure, EtO remains dominant for temperature-sensitive implants, sustaining demand for breathable Tyvek lidding compatible with this modality.
Market Restraints
- Medical-grade polymer feedstock volatility:Specialized polyethylene and fluoropolymer resin supplies concentrate among petrochemical producers in the US Gulf Coast and Middle East, exposing converters to input cost swings.
- Notified body capacity bottlenecks:EU MDR implementation has thinned the field of designated conformity assessment bodies, extending packaging system certification timelines for implant manufacturers.
- Steam sterilization incompatibility:Tyvek's cellulose-based structure degrades under moist heat, limiting its deployment for certain metallic implant categories where steam is preferred.
Strategic Opportunities
- China NMPA pathway acceleration:Streamlined registration routes for imported sterile barrier systems are opening access to domestic implant production clusters in Suzhou and Shenzhen.
- Drug-device combination convergence:Elastomeric closure integration with primary packaging is creating new specification categories for antibiotic-loaded bone cements and localized drug delivery implants.
- Automated packaging line retrofit:Roll stock format adoption in high-throughput orthopedic manufacturing is displacing pre-formed trays, reducing per-unit handling labor and cleanroom footprint.
Industry Challenges
- Accelerated aging protocol execution:FDA 21 CFR Part 820 and ISO 11607-1 stability studies require extended real-time and accelerated validation cycles that compress product launch windows.
- Biocompatibility testing coordination:Cytotoxicity and sensitization assays for novel polymer formulations must synchronize with device biocompatibility submissions, creating interdependency risks in regulatory dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Implants Sterile Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Pouches, Trays, Blisters, Roll Stock Material: Polyethylene, Polypropylene, Tyvek, PVC End User: Hospitals, Clinics, Surgical Centers, Research Facilities Technology: Sterilization, Seal Technology, Barrier Technology, Track & Trace |
| Companies Covered | West Pharmaceutical Services, Nelipak Healthcare, Amcor plc, Placon, Sonoco, Berry Global, Steripack Ltd., Wipak Group, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Implants Sterile Packaging Market Strategic Shifts
Active materials science and digital traceability mandates are restructuring how sterile barrier specifications are developed, validated, and monitored across implant supply chains.
Multi-layer coextruded films with tuned permeability profiles are replacing monolithic structures in cardiovascular and neurological implant packaging. Cardiovascular device manufacturers in Minnesota and Massachusetts are specifying these systems for combination products requiring precise moisture vapor transmission rates. The technology is modularizing how OEMs match barrier performance to specific sterilization modalities without complete format redesign.
EUDAMED traceability mandates under EU MDR are forcing serialization integration at the sterile barrier level. The unique device identification requirement is propagating through pouch and tray production lines, requiring label applicator and vision system upgrades. High-risk implant categories—spinal fusion and cardiac rhythm management devices—face the earliest compliance deadlines and are driving supplier investment in print-and-verify infrastructure.
Hospital sterilization services are consolidating into regional processing centers with standardized aseptic presentation protocols. This concentration is compressing the allowable variation in sterile barrier opening characteristics, forcing packaging designers toward peel strength ranges narrower than legacy specifications permitted. German university hospital networks and US integrated delivery networks are leading this standardization push, transmitting requirements upstream through group purchasing organization technical committees.
Medical Implants Sterile Packaging Market Segmentation
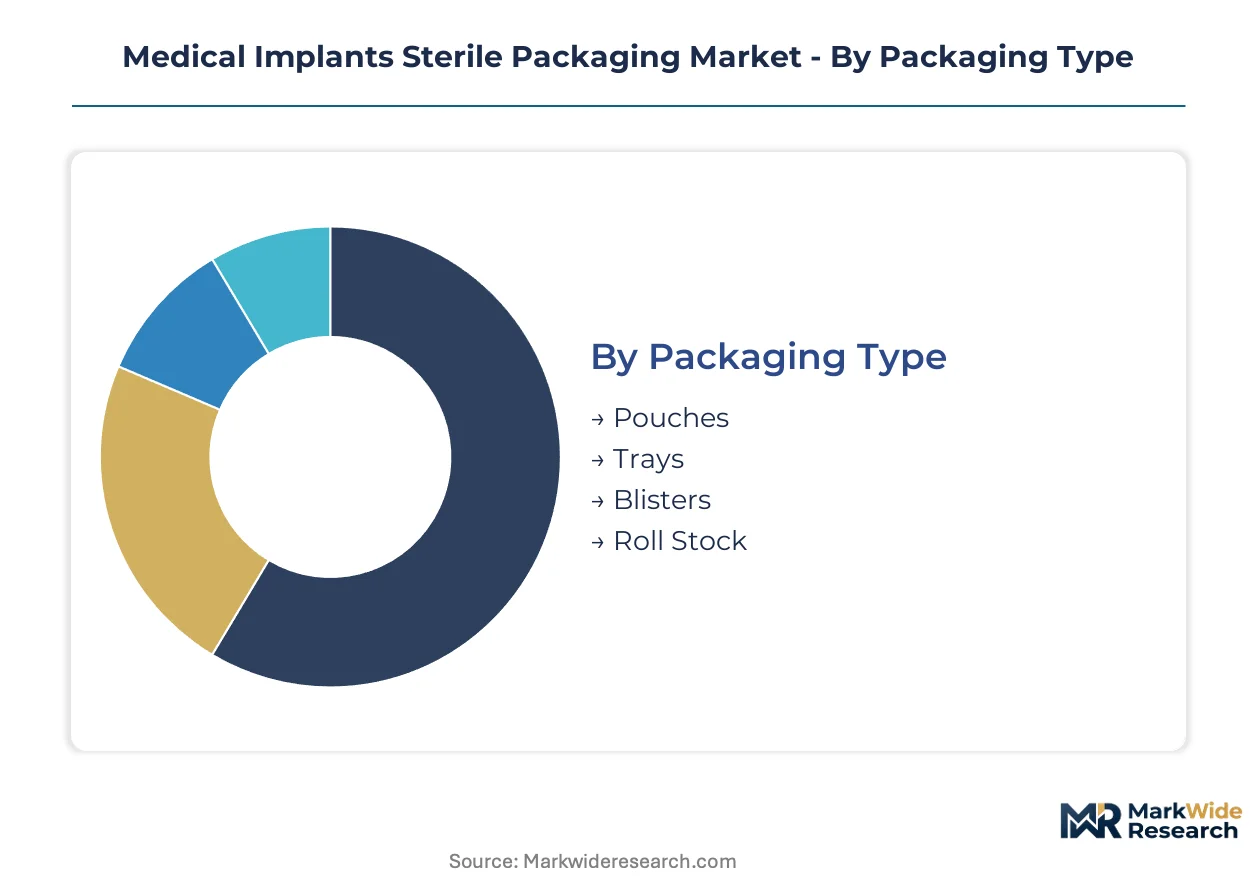
Sterile barrier specifications diverge sharply between high-volume orthopedic tray lines and specialized cardiovascular pouch systems. Segmentation reveals how material choices and format decisions cascade through validation protocols, sterilization compatibility, and end-user handling requirements.
Packaging Type:
Integration depth separates formats deployed as standalone sterile barriers from those embedded within automated production systems.
- Pouches:Multi-layer polymer laminates with peelable Tyvek or film lidding dominate cardiovascular and neurological implant presentation. German hospital networks specify these for cardiac rhythm management devices requiring aseptic opening in catheterization labs.
- Trays:Thermoformed PETG or HIPS structures with Tyvek lids anchor orthopedic and spinal implant packaging. Cleanroom thermoforming capacity concentrates near device manufacturing clusters in Warsaw, Indiana and Memphis, Tennessee to minimize logistics risk.
- Blisters:Form-fill-seal formats serve smaller implant categories and dental applications.
- Roll Stock:Continuous web formats integrate into automated packaging lines, displacing pre-formed components in high-throughput environments.
Volume placements concentrate in Trays; the faster expansion belongs to Roll Stock.
Material:
Cost tier stratification separates premium breathable barriers from commodity film alternatives serving lower-risk implant classes.
- Tyvek:Spunbonded olefin fiber structure delivers breathable sterilization compatibility and tear resistance. FDA and notified body validation pathways for EtO and gamma modalities are most established with this material, sustaining its position despite polyethylene cost competition.
- Polyethylene:Coextruded and monolayer films compete on cost for metallic implants where steam sterilization eliminates Tyvek compatibility requirements. Chinese converters are expanding blown film capacity to serve domestic implant production growth.
- Polypropylene:Oriented and cast variants serve specific clarity and heat resistance requirements.
- PVC:Legacy material retains niche presence in certain European markets.
Revenue concentration sits with Tyvek; polyethylene is climbing the fastest on orthopedic cost optimization.
End User:
Customer type determines aseptic presentation complexity and sterile barrier opening protocol variation.
- Hospitals:Integrated delivery networks in the United States and German university hospital systems drive standardization toward narrow peel strength ranges and EUDAMED-compliant serialization. Group purchasing organization technical committees transmit requirements upstream to packaging converters.
- Surgical Centers:Ambulatory settings favor compact pouch formats with simplified opening characteristics.
- Clinics:Smaller volume requirements concentrate on validated pouch systems with established supply chains.
- Research Facilities:Preclinical and clinical trial packaging demands flexible batch sizes and accelerated validation timelines.
Procurement volume clusters in Hospitals; Surgical Centers are gaining share fastest on outpatient migration.
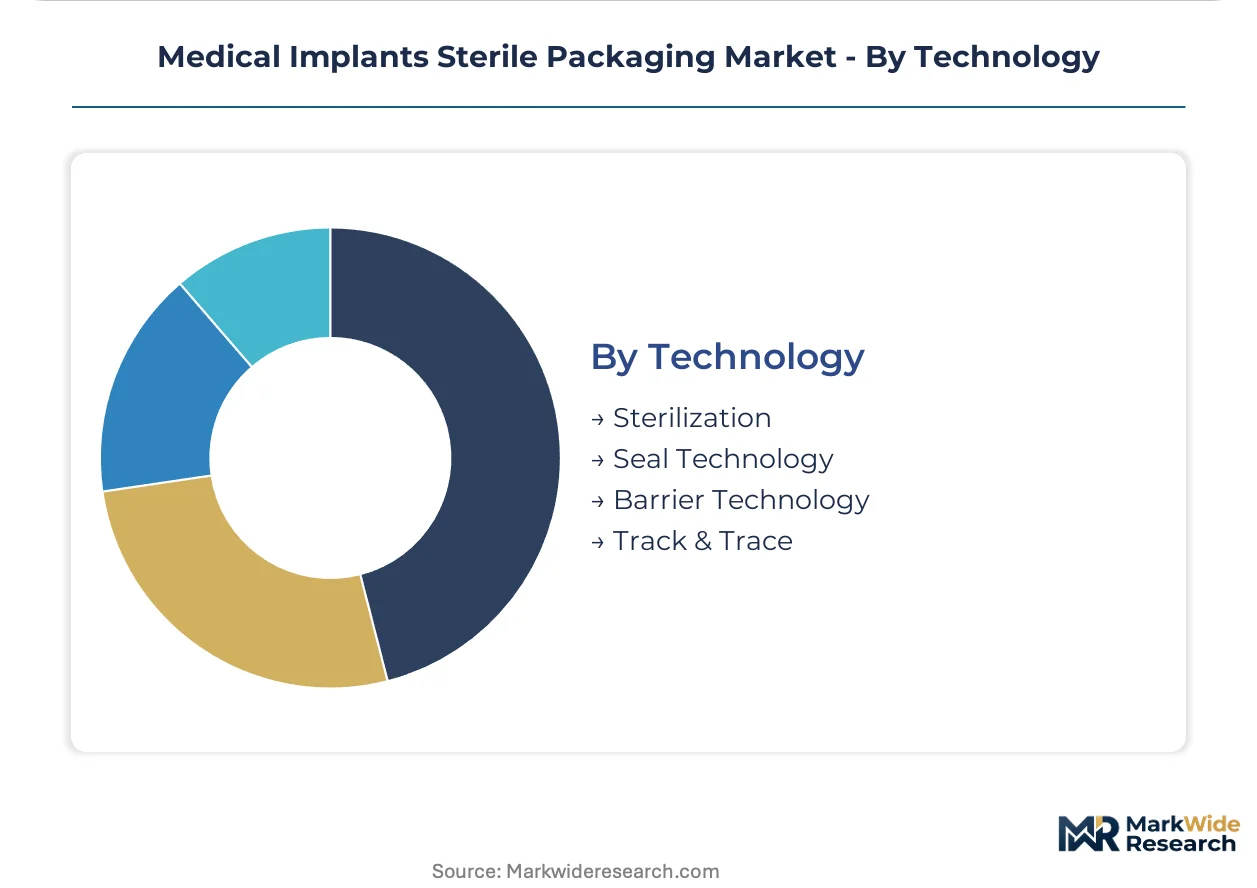
Technology:
Maturity stage separates established sterilization and seal modalities from emerging digital traceability requirements.
- Sterilization:Ethylene oxide, gamma irradiation, and steam modalities each demand material compatibility profiles that constrain format selection. EtO persistence for temperature-sensitive implants sustains breathable barrier demand despite EPA emission scrutiny in the US.
- Track & Trace:EUDAMED unique device identification mandates are forcing serialization integration at the sterile barrier level. Print-and-verify infrastructure investments concentrate on high-risk spinal and cardiac implant categories facing earliest compliance deadlines.
- Seal Technology:Heat seal, ultrasonic, and adhesive methods determine integrity validation protocols.
- Barrier Technology:Multi-layer coextrusion with tuned moisture vapor transmission rates serves combination product requirements.
Deployment breadth favors Sterilization; Track & Trace commands the steepest investment trajectory on regulatory mandate timing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polyethylene and fluoropolymer resin supplies concentrate among petrochemical producers along the US Gulf Coast and in the Middle East, exposing sterile barrier converters to input cost volatility and logistics complexity across implant packaging supply chains.
United States
FDA 21 CFR Part 820 quality system regulations govern sterile barrier validation for orthopedic and cardiovascular implants. The EPA maintains emission scrutiny over ethylene oxide sterilization facilities, sustaining breathable barrier demand despite environmental pressure. Device manufacturing clusters in Warsaw, Indiana and Memphis, Tennessee anchor thermoformed tray production near orthopedic OEMs.
Germany
EU MDR Annex I general safety and performance requirements compress validation timelines for implant packaging systems. Notified body capacity bottlenecks extend certification timelines for sterile barrier manufacturers. University hospital networks in Baden-Württemberg and Bavaria drive standardization toward narrow peel strength ranges through group purchasing organization technical committees.
China
NMPA streamlined registration routes for imported sterile barrier systems accelerate market access. Domestic implant production clusters in Suzhou and Shenzhen pull demand for validated pouch and tray formats. Chinese converters expand blown film capacity to serve metallic implant categories where steam sterilization eliminates Tyvek compatibility requirements.
Japan
PMDA oversight of drug-device combination products creates specification categories for antibiotic-loaded bone cements. METI industrial policy supports advanced polymer processing capabilities for medical-grade applications. Kanto and Kansai manufacturing corridors concentrate cleanroom thermoforming capacity serving domestic and export implant markets.
Switzerland
Swissmedic requirements for high-risk implant categories enforce stringent post-market surveillance on sterile barrier systems. Precision manufacturing heritage supports specialized packaging for spinal fusion and cardiac rhythm management devices. Basel and Zurich industrial zones host contract packaging operations serving EU and global orthopedic OEMs.
Medical Implants Sterile Packaging Market Competitive Environment
Capacity expansion dominates the current landscape as sterile barrier converters respond to EU MDR validation compression and orthopedic surgical volume growth. The vendor base stratifies across three tiers: global diversified materials conglomerates with film extrusion networks, regional cleanroom thermoforming specialists concentrated near device clusters, and integrated elastomer-packaging combination providers. M&A activity and geographic footprint extension represent the dominant competitive moves as firms consolidate supplier relationships around notified body-approved systems.
Among the integrated packaging-materials conglomerates, Amcor plc exemplifies scale-driven global reach through multi-continent film supply networks. Nelipak Healthcare occupies a position within the regional cleanroom specialist archetype, with thermoforming capacity anchored near major device manufacturing hubs. West Pharmaceutical Services represents the combination-product integration tier, bridging elastomeric closure systems with primary sterile barrier formats for drug-device implants.
| Leading Market Players |
|---|
| West Pharmaceutical Services |
| Nelipak Healthcare |
| Amcor plc |
| Placon |
| Sonoco |
| Berry Global |
| Steripack Ltd. |
| Wipak Group |
| DuPont de Nemours |
| Others |
Value Chain & Pricing Dynamics
Polyethylene resin price indices on the US Gulf Coast cascade through sterile barrier converter margins into three-tier pricing structures across premium, standard, and economy levels. Medical-grade polymer feedstock volatility compresses converter profitability and forces tiered pricing separation between Tyvek-based breathable barriers and commodity polyethylene alternatives for metallic implants.
Pricing Analysis
Warranty and validation service bundling separates premium sterile barrier suppliers from unbundled commodity converters in this market. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 11607 certification completeness and notified body approval status, with FDA-validated systems commanding substantial premiums over CE-only equivalents. Pricing pressure stems from Chinese converter expansion of blown film capacity serving domestic implant production clusters. Orthopedic OEMs in Warsaw, Indiana and Memphis, Tennessee exhibit highest price sensitivity on high-volume tray lines, while cardiovascular device manufacturers in Massachusetts show lowest sensitivity due to combination product complexity.
Supply Chain Analysis
China NMPA domestic-content preferences and EU MDR local supplier qualification requirements are reshaping sourcing patterns for implant OEMs. Specialized polyethylene and fluoropolymer resin supplies concentrate in the United States, Saudi Arabia, and South Korea, exposing converters to petrochemical feedstock volatility. Sterile barrier manufacturing draws from medical-grade polymer extrusion, cleanroom thermoforming equipment, and precision die-cutting components. Single-source vulnerability concentrates in Tyvek fiber production. Distribution runs through device manufacturing clusters with just-in-time delivery to orthopedic and cardiovascular OEM cleanrooms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom thermoforming capacity scarcity near major device manufacturing hubs props pricing for validated sterile barrier systems. Notified body bottlenecks under EU MDR extend certification timelines and reinforce incumbent positioning.
For Market Incumbents: Cement market position through backward integration into medical-grade polymer extrusion to capture margin from resin volatility. Expand cleanroom thermoforming capacity in Suzhou and Shenzhen to intercept China NMPA pathway acceleration. Defend against polyethylene converter cost competition by deepening ISO 11607 validation service bundling.
For New Entrants and Emerging Players: Enter via automated roll stock packaging line retrofits for high-throughput orthopedic manufacturers seeking labor and footprint reduction. Target cardiovascular pouch segments in German university hospital networks where EUDAMED serialization mandates create infrastructure upgrade windows. Lead with print-and-verify integration capabilities for high-risk implant categories facing earliest compliance deadlines.
For Investors and Strategic Acquirers: The window for entry favors regional cleanroom specialists with notified body-approved systems and geographic proximity to device clusters. Long-term viability rests on EU MDR validation compression sustaining supplier consolidation momentum. Target acquisition archetype: thermoforming operators with established FDA 510(k) packaging validation pathways. The signal to watch is EUDAMED traceability mandate enforcement timing for mid-risk implant categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | Proximity to Warsaw, Indiana and Memphis device clusters reduces logistics risk for orthopedic OEMs. |
| Backward Integration into Extrusion | In-house polyethylene film production insulates margins from US Gulf Coast resin volatility. |
| EUDAMED Serialization Infrastructure | Print-and-verify system investments capture high-risk spinal and cardiac implant compliance deadlines. |
| China NMPA Registration Acceleration | Streamlined pathways open access to Suzhou and Shenzhen domestic production clusters. |
| Drug-Device Combination Integration | Elastomeric closure bundling serves antibiotic-loaded bone cement specification categories. |
Study Parameters
Independent corroboration across packaging converter executives, biomedical engineers at orthopedic OEMs, hospital purchasing committee members, and regulatory affairs specialists at notified bodies underwrites the qualitative findings. Primary interviews with cleanroom thermoforming operators and sterile barrier validation consultants combined with secondary analysis of FDA 510(k) packaging submissions, EU MDR technical documentation, ISO 11607 guidance documents, and hospital GPO contract databases. Bottom-up demand modeling from implant surgical procedure volumes triangulates against top-down sterile barrier materials consumption estimates.
Rate-of-change decomposition separates volume growth from mix shift and pricing dynamics across the projection horizon. Segmentation dimensions modeled include packaging format, material tier, sterilization modality compatibility, and end-user facility type. CAGRs derive from implant procedure volume trajectories, regulatory validation timeline compression, and materials substitution elasticities. Forecast inputs incorporate ethylene oxide sterilization persistence rates and EUDAMED implementation phasing by device risk class.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity expansion delays or accelerated EPA ethylene oxide emission restrictions. Forecasts reflect assumptions regarding EU MDR enforcement consistency and China NMPA pathway stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Sterile Wraps Market