
 Multi-Med Adherence Packaging Market | 2026-2036
Multi-Med Adherence Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Med Adherence Packaging Market Foresight
Multi-source procurement of automated adherence packaging systems is rebalancing as pharmacy chains and long-term care operators diversify vendor relationships to mitigate supply risk. Omnicell Inc. extends its installed base through robotic dispensing integration, while Cardinal Health Inc. leverages its distribution network to bundle packaging with pharmaceutical supply contracts. Parata Systems LLC specializes in high-throughput automation for central fill pharmacies, competing on throughput metrics rather than equipment price alone.
Multi-med adherence packaging comprises unit-dose or multi-dose containers—typically blister cards, strip pouches, or vial-based systems—designed to organize complex pharmaceutical regimens by time and date, with specifications including child-resistant barriers, moisture barriers down to 0.1 g/m²/day water vapor transmission, and compliance-prompt labeling. The product type dimension shows blister packs dominating current volume due to established pharmacy workflows, while patient-centric packs capture expanding margin pools as personalized medicine protocols proliferate. Material selection is shifting toward aluminum-plastic composites that satisfy USP <671> stability requirements for moisture-sensitive biologics without the bulk of traditional cold-form structures.
The US FDA enforces child-resistant packaging standards under 16 CFR 1700 and DSCSA track-and-trace mandates that elevate serialization infrastructure costs for packaging converters. EMA's Falsified Medicines Directive imposes equivalent verification requirements across European supply chains, while ISO 15378 certifies primary packaging materials for medicinal products against quality management benchmarks. Stakeholders must monitor evolving pharmacovigilance linkages between packaging data and patient outcomes as regulators tighten evidentiary requirements for adherence interventions.
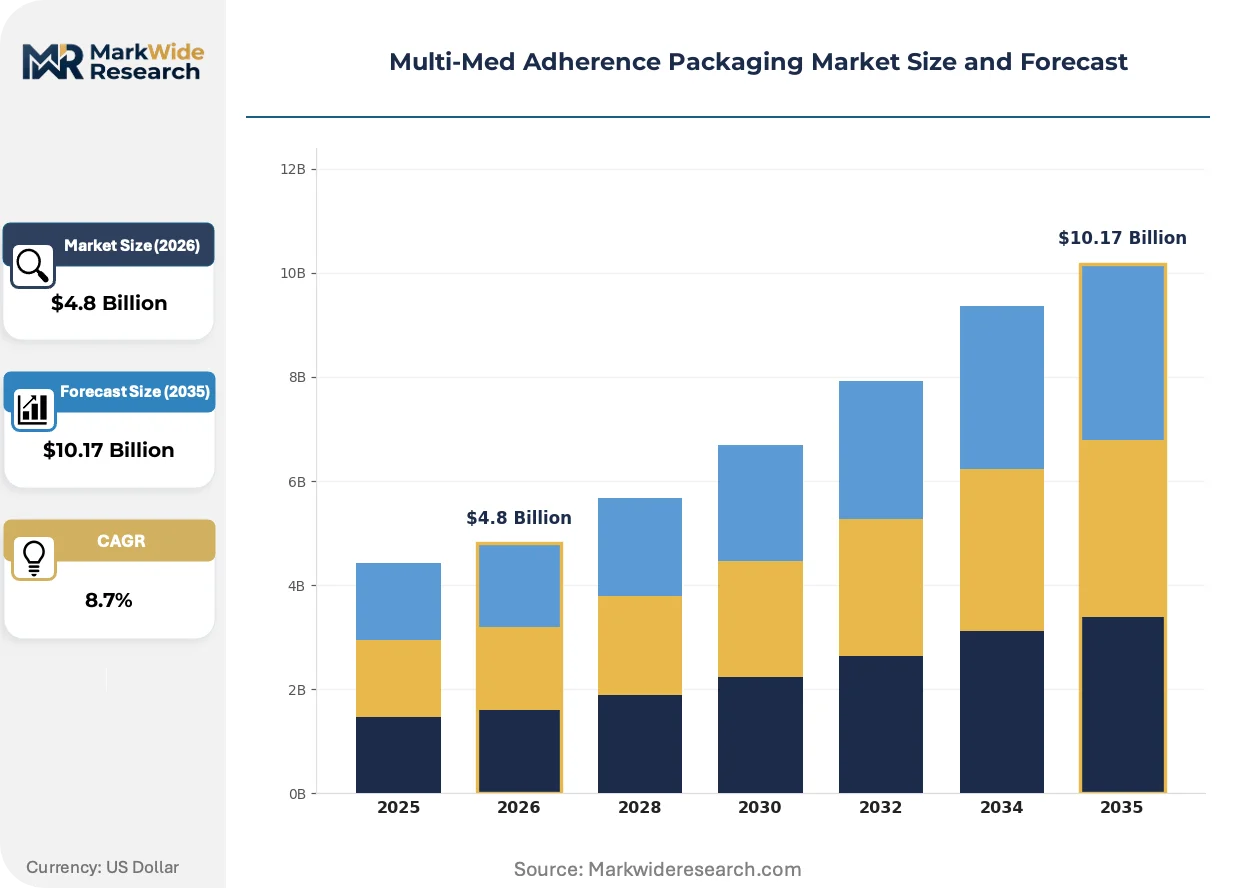
Market Dynamics
The US FDA's DSCSA serialization mandates are forcing packaging converters to rebuild production lines around track-and-trace infrastructure, redistributing capital toward compliance systems and away from capacity expansion.
Growth Catalysts
- Aging demographics:Long-term care facilities in the United States, Japan, and Germany are scaling multi-med adherence programs to manage polypharmacy among residents with five or more chronic conditions.
- 16 CFR 1700 enforcement:Child-resistant packaging standards are tightening test protocols for senior-friendly opening mechanisms, expanding demand for certified barrier designs.
- Biologics proliferation:Moisture-sensitive monoclonal antibodies and cell therapies require aluminum-plastic composite structures that extend stability beyond traditional cold-form capabilities.
Market Restraints
- Aluminum price volatility:Primary aluminum costs on the London Metal Exchange create margin compression for converters of foil-laminated blister structures.
- Equipment supplier concentration:Central-fill pharmacy automation hardware depends on a narrow base of German and Japanese precision-engineering suppliers.
- Legacy vial substitution:Unit-dose vial systems retain pharmacy workflow advantages for low-complexity regimens, limiting adherence packaging penetration in generic substitution markets.
Strategic Opportunities
- Home-based care expansion:Post-acute medication management programs in the United States are piloting direct-to-patient adherence packaging to reduce thirty-day readmission penalties.
- EMA Falsified Medicines Directive alignment:European serialization requirements create service revenue streams for packaging converters offering verification infrastructure.
- Near-infrared authentication:Convergence of spectroscopic sensors with printed electronics enables real-time medication verification at the point of dispensing.
Industry Challenges
- Serialization technician shortage:Packaging lines require operators trained in aggregation hierarchy management and exception handling under DSCSA protocols.
- Legacy pharmacy management system integration:Adherence packaging workflows must interface with proprietary dispensing software that lacks standardized API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Med Adherence Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Strip Packs, Vial Packs, Patient-Centric Packs Delivery Mode: Oral, Injectable, Topical, Inhalation End User: Pharmacies, Hospitals, Home Healthcare, Long-Term Care Facilities Material: Plastic, Paper, Aluminum, Composites |
| Companies Covered | Omnicell Inc., Cardinal Health Inc., Parata Systems LLC, Jones Healthcare Group, Medicine-On-Time LLC, Aptar CSP Technologies Inc., Synergy Medical, Manrex Ltd., Westrock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Med Adherence Packaging Market Shifts & Advancements
Digital traceability infrastructure is absorbing capital and engineering talent across the packaging value chain, compressing innovation cycles in materials science while elevating data architecture as a competitive differentiator.
Printed electronics with embedded temperature-logging circuits are absorbing quality assurance functions previously performed by external data loggers. Cold-chain biologics distributors in the United States are adopting these smart blister formats for high-value oncology therapies. The technology is absorbing compliance documentation costs into the primary package itself.
EMA's Falsified Medicines Directive verification requirements are mandating two-dimensional matrix codes on all prescription packs entering European supply chains. Packaging converters serving EU markets must install camera-based inspection and rejection systems. Hospital pharmacies in France and Germany are prioritizing suppliers with pre-validated serialization workflows.
Consolidation among United States pharmacy benefit managers is concentrating procurement authority within three national entities. Independent packaging converters are losing direct access to formulary decision-makers. Regional long-term care operators in Florida and Texas are responding by forming purchasing cooperatives to restore negotiating leverage.
Multi-Med Adherence Packaging Market Segmentation
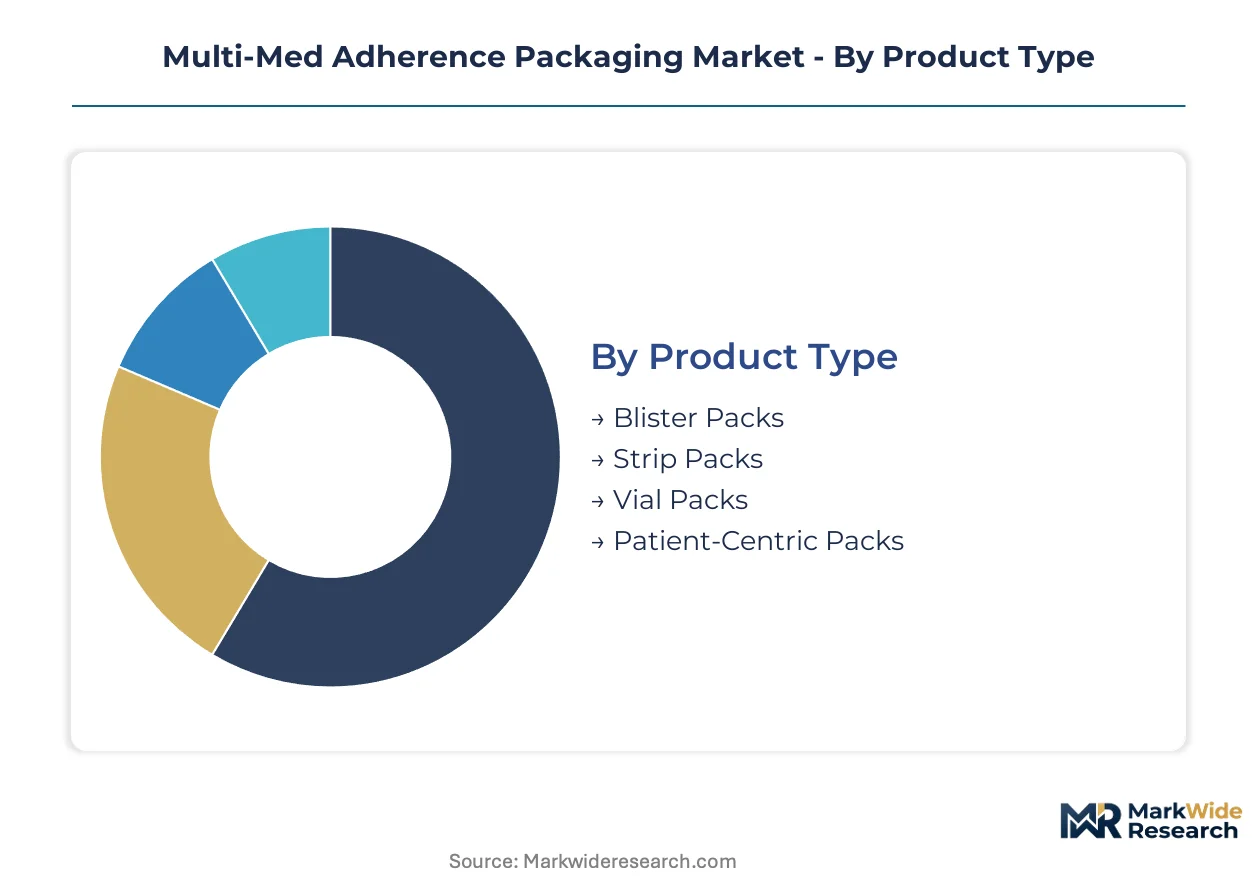
Segmentation in multi-med adherence packaging reveals how packaging specifications diverge across medication complexity, patient mobility, and institutional workflow requirements. Each dimension carries distinct regulatory obligations and margin structures that reshape converter investment priorities.
Product Type:
Pharmacy chains and long-term care operators select formats based on automation compatibility, senior dexterity requirements, and biologic stability demands.
- Blister Packs:Pre-formed plastic or aluminum cavities sealed with lidding foil, dominating central-fill pharmacy automation due to established robotic handling protocols. Demand concentrates in United States retail pharmacy chains where DSCSA serialization mandates favor unit-dose traceability.
- Patient-Centric Packs:Customized adherence formats incorporating large-print labeling, ergonomic opening aids, and calendarized dosing windows. Long-term care facilities in Florida and Texas are scaling procurement as polyphacy rates climb among residents with multiple chronic conditions.
- Strip Packs:Continuous roll-fed pouches with sequential dosing compartments, preferred by mail-order pharmacies for shipping efficiency.
- Vial Packs:Traditional multi-dose containers retaining workflow advantages for low-complexity generic regimens.
Blister packs lead volumes today; patient-centric packs are gaining share fastest.
Delivery Mode:
Packaging specifications escalate with medication stability sensitivity and route-of-administration sterility requirements.
- Injectable:Pre-filled syringes and auto-injector formats demanding barrier integrity against oxygen and moisture ingress. United States oncology distributors are adopting smart blister formats with embedded temperature-logging circuits for cold-chain biologics.
- Oral:Tablets and capsules organized in time-specific compartments, representing the baseline adherence packaging volume across retail pharmacy.
- Topical:Unit-dose sachets and pump dispensers for transdermal therapies.
- Inhalation:Blister-foil combinations for dry powder inhalers requiring precise moisture barriers.
Oral formats dominate current procurement; injectable packaging shows the steepest expansion trajectory as biologics proliferate.
End User:
Institutional buyers impose divergent technical specifications based on patient acuity, staff-to-resident ratios, and reimbursement incentives.
- Long-Term Care Facilities:Skilled nursing and assisted living operations managing complex polypharmacy for immobile populations. Medicare readmission penalties in the United States are driving investment in adherence packaging to reduce thirty-day hospital returns.
- Pharmacies:Retail chains and independent dispensers seeking automation-compatible formats that integrate with existing dispensing software.
- Hospitals:Inpatient and discharge medication reconciliation programs requiring unit-dose verification.
- Home Healthcare:Post-acute and hospice providers delivering direct-to-patient adherence solutions.
Pharmacies anchor current volume; long-term care facilities are expanding most quickly as aging demographics intensify medication management needs.
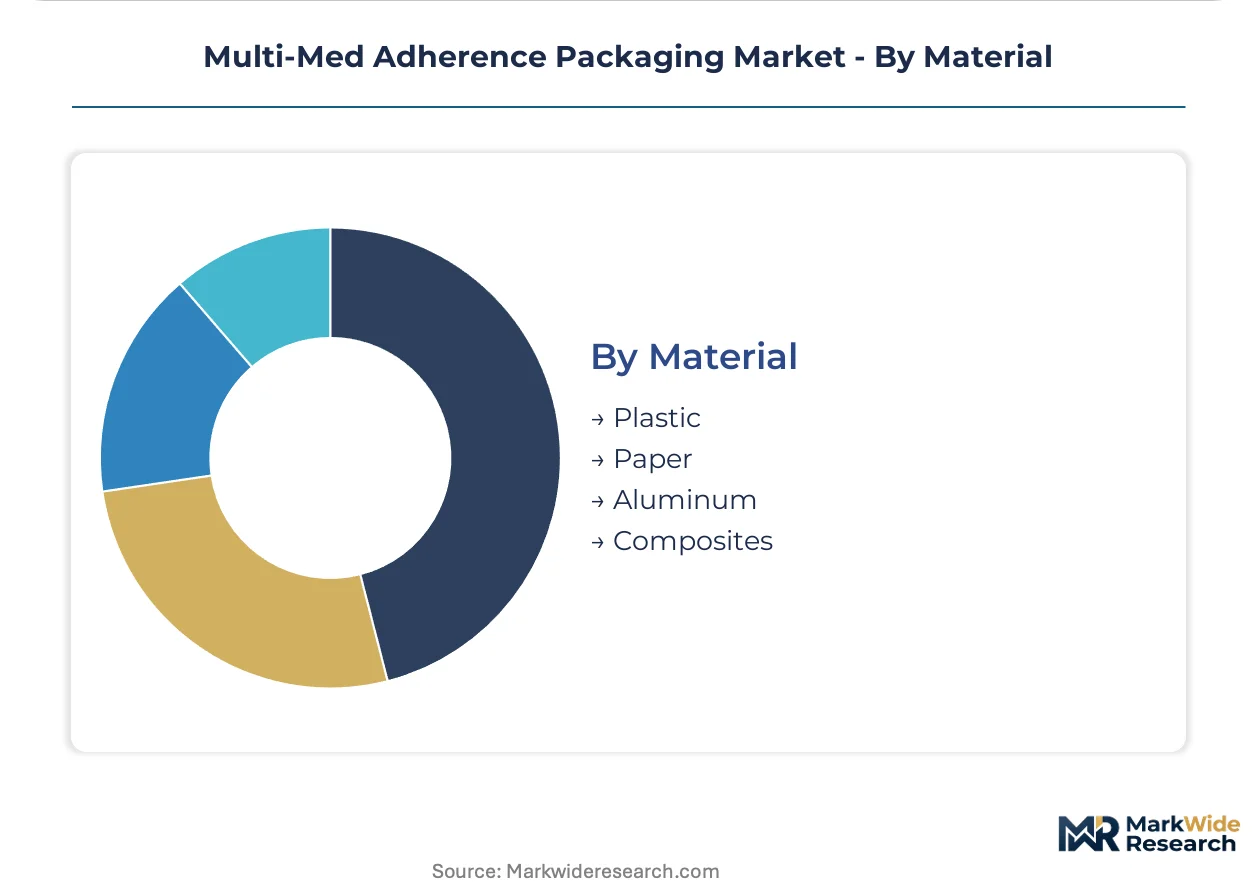
Material:
Material selection balances USP stability requirements against aluminum price volatility and sustainability pressures.
- Composites:Aluminum-plastic laminates achieving moisture barriers down to 0.1 g/m²/day water vapor transmission without cold-form bulk. United States converters are prioritizing these structures for monoclonal antibodies and cell therapies.
- Aluminum:Cold-form foil structures providing maximum barrier protection for highly sensitive APIs.
- Plastic:PVC, PVDC, and cyclic olefin polymers for cost-sensitive oral solid doses.
- Paper:Fiber-based substrates emerging in sustainability-focused pilot programs.
Aluminum structures retain premium positioning; composites are climbing the fastest as biologics reshape stability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Jersey's pharmaceutical corridor anchors multi-med adherence packaging procurement as pharmacy benefit managers and central-fill operators concentrate volume purchasing authority. Regulatory serialization mandates and aging demographics reshape demand patterns across distinct national markets.
United States
Pharmacy benefit manager consolidation concentrates procurement within three national entities, stripping independent converters of direct formulary access. FDA's DSCSA serialization deadlines force production line rebuilds around track-and-trace infrastructure. New Jersey and Pennsylvania host the densest converter clusters serving retail pharmacy chains.
Germany
EMA's Falsified Medicines Directive verification requirements mandate two-dimensional matrix codes on all prescription packs entering European supply chains. Precision-engineering suppliers from Baden-Württemberg dominate central-fill automation hardware. Hospital pharmacies in Bavaria prioritize suppliers with pre-validated serialization workflows.
Japan
Metropolitan Tokyo and Osaka prefectures face acute aging demographics with polypharmacy rates exceeding Western benchmarks. PMDA stability guidelines for moisture-sensitive biologics accelerate aluminum-plastic composite adoption. Regional long-term care cooperatives in Kansai restore negotiating leverage against consolidated distributors.
United Kingdom
Post-acute medication management pilots in Greater Manchester and London test direct-to-patient adherence packaging to reduce hospital readmission penalties. MHRA alignment with EMA serialization standards elevates infrastructure costs for packaging converters. Independent pharmacy networks in the Midlands form purchasing alliances.
India
CDSCO's evolving pharmaceutical packaging standards create compliance windows for export-oriented converters in Gujarat and Maharashtra. Domestic pharmacy automation remains nascent, with Mumbai-based distributors importing German and Japanese equipment. Regional hospital chains in Karnataka pilot adherence programs for chronic disease management.
Multi-Med Adherence Packaging Market Competitive Landscape
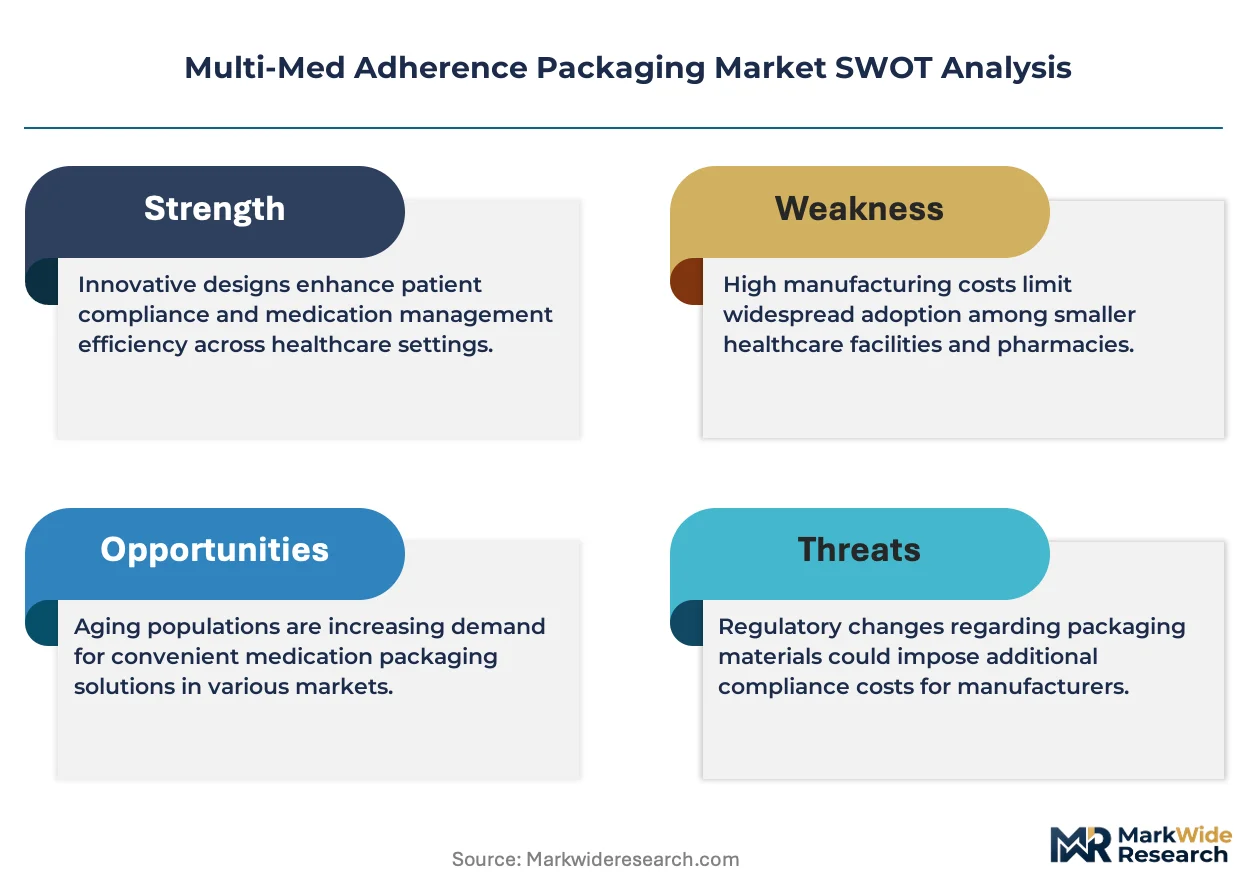
Established producers occupy the standard tier; emerging entrants pursue smart packaging integration and regional service networks. The market structure reflects moderate consolidation among automation-integrated suppliers alongside fragmented specialty converters. Three archetypes dominate: pharmacy automation specialists, diversified health distribution conglomerates, and materials-science packaging engineers. Competitive moves center on robotic dispensing integration and serialization infrastructure bundling.
Within the automation-specialist tier, Omnicell Inc. and Parata Systems LLC exemplify divergent throughput strategies, while Cardinal Health Inc. anchors the distribution-integrated archetype. These entities represent distinct capital allocation patterns—equipment-centric versus supply-contract bundling—without implying specific strategic timelines or performance metrics.
| Leading Market Players |
|---|
| Omnicell Inc. |
| Cardinal Health Inc. |
| Parata Systems LLC |
| Jones Healthcare Group |
| Medicine-On-Time LLC |
| Aptar CSP Technologies Inc. |
| Synergy Medical |
| Manrex Ltd. |
| Westrock Company |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up packaging specialists dominate converter ownership structures, concentrating production capacity among fewer balance sheets and disciplining price competition through portfolio optimization rather than capacity wars. This ownership pattern tightens supply responsiveness to aluminum price swings while embedding subscription-style service contracts that insulate margins from commodity volatility.
Pricing Analysis
Input-cost pass-through from London Metal Exchange aluminum pricing runs through quarterly contract renegotiations, with converters recovering 60-80% of foil-laminated structure increases via surcharge mechanisms. Pricing stratifies across DSCSA-compliant serialization tiers, cold-chain biologics barriers, and standard oral-solid formats, with certification-grade differentiation widening spreads between premium and economy offerings. Cost compression in standard blister packs is intensifying because pharmacy benefit manager consolidation strips negotiating leverage from regional converters. Long-term care cooperatives in Florida and Texas exhibit highest price sensitivity due to Medicare reimbursement caps, while oncology distributors show lowest sensitivity given therapy value density.
Supply Chain Analysis
Aluminum foil supply rests on German and Japanese rolling mills for pharmaceutical-grade substrates, with Chinese converters capturing cost-sensitive generic blister volumes. Robotic dispensing hardware draws from Baden-Württemberg precision-engineering clusters and Osaka automation suppliers, creating single-source vulnerability for central-fill pharmacy deployments. Tariff exposure on aluminum imports from primary smelters in Canada and the Middle East compounds margin pressure for US-based converters. Distribution runs through Cardinal Health and McKesson pharmaceutical networks, with regional long-term care purchasing cooperatives emerging as alternative channel nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in multi-med adherence packaging hinges on aluminum-plastic composite adoption for biologics, where stability premiums offset commodity headwinds and serialization service bundling captures recurring revenue streams.
For Market Incumbents: Lock in pharmacy benefit manager formulary access through pre-validated DSCSA serialization workflows that reduce buyer compliance costs. Defend against emerging smart-packaging entrants by backward integration into printed electronics substrate production, securing temperature-logging circuit supply for oncology cold-chain contracts. For New Entrants and Emerging Players: Direct-to-patient digital channels offer the lowest competitive density for post-acute adherence packaging pilots targeting Medicare readmission penalty reduction. Regional hospital systems in India and the United Kingdom represent the most penetrable buyer segments, with CDSCO and MHRA compliance windows creating temporary procurement flexibility. Pursue white-label manufacturing partnerships with established German automation suppliers to bypass equipment lead time barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among materials-science packaging engineers lacking robotic dispensing integration, as pharmacy automation specialists command premium multiples. The five-to-ten-year viability frame favors converters with aluminum-plastic composite R&D pipelines and European EMA verification infrastructure. Watch for inflection when FDA publishes definitive aggregation hierarchy guidance under DSCSA, triggering capital deployment into exception-handling software capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Bundling | Combines DSCSA-compliant track-and-trace hardware with packaging supply contracts, locking in pharmacy benefit manager volume commitments. |
| Aluminum-Plastic Composite Scale-Up | Extends stability windows for monoclonal antibodies beyond cold-form capabilities, capturing biologics margin premiums. |
| Regional Long-Term Care Cooperative Partnership | Restores converter access to institutional buyers displaced by PBM consolidation in Florida and Texas markets. |
| Smart Blister Temperature-Logging Integration | Embeds quality assurance documentation into primary packaging, reducing oncology distributor compliance labor. |
| EMA Verification Workflow Pre-Validation | Accelerates European market entry for US converters facing Falsified Medicines Directive camera-inspection mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with pharmacy automation specialists, long-term care procurement directors, pharmaceutical packaging engineers, and regulatory compliance officers with secondary validation. FDA DSCSA guidance documents, EMA Falsified Medicines Directive implementation reports, USP stability monographs, and aluminum trade flow data from customs records anchored the quantitative foundation. Bottom-up demand modeling across end-use segments triangulated against top-down converter capacity assessments.
Segment-weighting approaches applied differential growth assumptions by product type, delivery mode, and material substrate across the projection horizon. The analytical framework modeled blister pack, patient-centric pack, strip pack, and vial pack trajectories alongside oral, injectable, topical, and inhalation delivery requirements. CAGRs derived from elasticity-adjusted volume projections incorporating pharmacy automation penetration curves and biologics pipeline expansion. Forecast inputs included PBM consolidation timelines, aluminum price volatility scenarios, and serialization technician labor supply constraints.
The model assumes a particular technology adoption path; alternative pathways for printed electronics temperature-logging integration would alter the outlook if near-infrared spectroscopic sensors achieve cost parity sooner than projected. Forecasts reflect underlying assumptions about DSCSA enforcement consistency and EMA verification infrastructure buildout rates. Material deviation in aluminum price volatility, pharmacy automation hardware delivery timelines, or regulatory guidance publication schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Sterile Packaging Market