
 Syringe Trays Market | 2026-2036
Syringe Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Syringe Trays Market Outlook
Polypropylene is expanding its share in syringe tray construction as manufacturers abandon PVC amid chlorine-content disposal restrictions. Becton, Dickinson and Company leverages captive resin compounding to stabilize input costs across its tray portfolio. Terumo Corporation anchors its position through cleanroom-molded designs that serve Japanese and Southeast Asian hospital procurement networks. Cardinal Health competes on distribution density, bundling trays with broader medication delivery kits to capture pharmacy system contracts.
Syringe trays are rigid containment platforms, typically injection-molded from medical-grade polymers or formed from aluminum, designed to organize, protect, and present hypodermic syringes during sterile procedures, transport, and point-of-care administration; wall thickness generally ranges from 1.2 mm to 3.0 mm depending on sterilization method and stacking load requirements. Plastic material type dominates current volume owing to cost efficiency and gamma-radiation compatibility, though composite segments are gaining fastest as hybrid paper-fiber trays address single-use plastic bans in European healthcare procurement. Reusable product types retain share in surgical suites where autoclave cycles justify capital investment, while single-use variants lead in vaccination campaigns and ambulatory settings where throughput speed outweighs per-unit economics.
FDA 21 CFR Part 820 quality system regulations govern tray validation for US medical device classification, while EU MDR Annex I general safety and performance requirements mandate biocompatibility testing and Unique Device Identification labeling that extends to accessory packaging. Health Canada's Medical Devices Bureau applies similar ISO 13485-aligned scrutiny for tray imports, creating a convergent compliance baseline across North American and European market access pathways. Stakeholders must monitor evolving extended producer responsibility frameworks for hospital plastics, as these policies will determine whether reusable or disposable product architectures deliver lower total cost of ownership.
Market Dynamics
EU MDR traceability mandates and FDA sterilization validation requirements are compressing material certification timelines while simultaneously fragmenting supplier qualification pools across hospital procurement networks.
Growth Catalysts
- Gamma-radiation compatible polymers:Medical-grade polypropylene formulations enable terminal sterilization without ethylene oxide residuals, satisfying hospital infection control protocols in German and Japanese tertiary care centers.
- Extended producer responsibility frameworks:EU Green Deal circular economy targets are accelerating hospital purchasing shifts toward recyclable tray architectures in France, Italy, and the Netherlands.
- Cleanroom-molded manufacturing:ISO 14644-1 Class 7 and Class 8 certified production environments reduce particulate contamination risk for prefilled syringe applications in oncology and biologics administration.
Market Restraints
- Medical-grade resin price volatility:Polypropylene homopolymer and copolymer feedstock costs fluctuate with propylene monomer availability from Gulf Coast petrochemical complexes.
- Concentrated sterilization service capacity:Gamma irradiation facilities cluster in Belgium, Germany, and select US states, creating geographic bottlenecks for tray manufacturers without captive sterilization assets.
- Aluminum tray substitution ceiling:Metal forming limitations prevent sub-1.5 mm wall thicknesses required for high-density syringe counts in mass vaccination formats.
Strategic Opportunities
- Hybrid paper-fiber composite trays:Cellulose-molded platforms with polymer barrier coatings address single-use plastic procurement bans in Nordic hospital systems and Dutch healthcare purchasing cooperatives.
- Unique Device Identification labeling integration:EU MDR Annex VI compliance creates service revenue streams for serialized tray production serving pharmaceutical kit assembly operations.
- Ambulatory surgery center expansion:Freestanding ASC networks in Texas, Florida, and Arizona are disaggregating tray purchasing from integrated delivery network contracts, opening direct manufacturer relationships.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization study queues at notified bodies extend product launch timelines for novel polymer formulations.
- Autoclave cycle validation complexity:Reusable tray manufacturers must document 500+ steam sterilization cycles without dimensional drift, requiring accelerated aging protocols that compress R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syringe Trays Market |
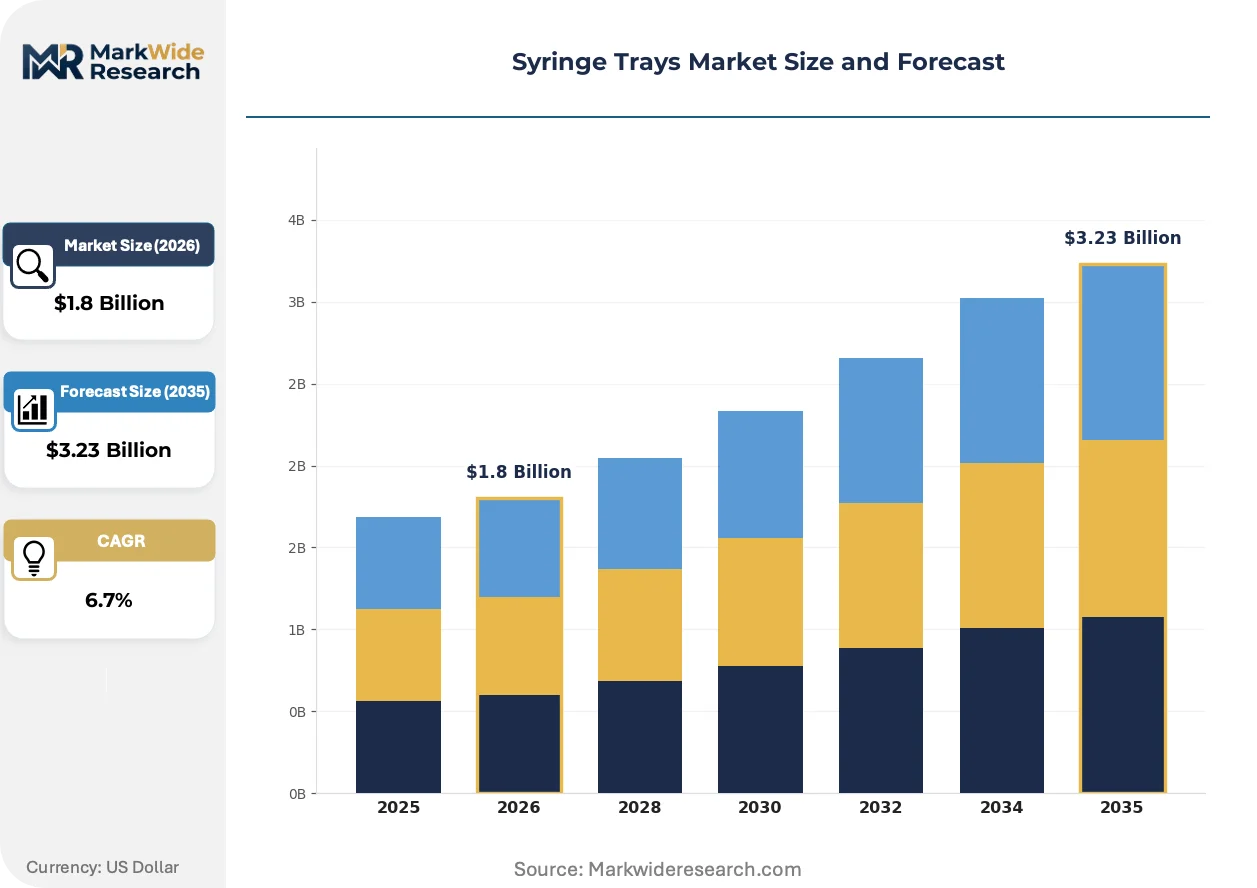
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Glass, Composite End User: Hospitals, Clinics, Laboratories, Pharmacies Product Type: Single-use, Reusable, Disposable, Customizable Capacity: 10-syringe, 20-syringe, 50-syringe, 100-syringe |
| Companies Covered | Becton, Dickinson and Company, Terumo Corporation, Cardinal Health, Medline Industries, Addent Inc., Treiber Trays, Baxter International, Henry Schein, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syringe Trays Market Strategic Shifts
Distributed manufacturing architectures and point-of-care customization capabilities are dissolving the traditional separation between tray production and hospital pharmacy operations.
Microcellular injection molding is decentralizing production economics by enabling 15-20% material density reduction without sacrificing structural rigidity for stacking loads. Regional medical device converters in Poland and the Czech Republic are adopting this technology to serve Central European hospital networks with reduced shipping distances. The process is decentralizing supply chain risk away from concentrated Asian molding centers toward continental European production nodes.
EU MDR Annex I general safety and performance requirements now mandate biocompatibility documentation for all patient-contacting packaging accessories, including syringe trays classified as Class I medical devices. German notified bodies are interpreting this provision strictly, rejecting submissions lacking extractables and leachables data for polymer additives. Tray manufacturers serving EU markets are responding by reformulating colorants and slip agents to eliminate phthalate and bisphenol-A derivatives from masterbatch specifications.
Hospital pharmacy consolidation is compressing supplier rosters as integrated delivery networks centralize purchasing decisions for standardized medication delivery kits. Three-tier pricing structures across premium, standard, and economy certification grades now dominate contract negotiations, with premium tiers reserved for trays bearing USP Class VI and ISO 10993 full-panel testing documentation. This concentration is most visible in California and New York health systems where formulary committees now specify tray performance benchmarks alongside drug product selection criteria.
Syringe Trays Market Segmentation
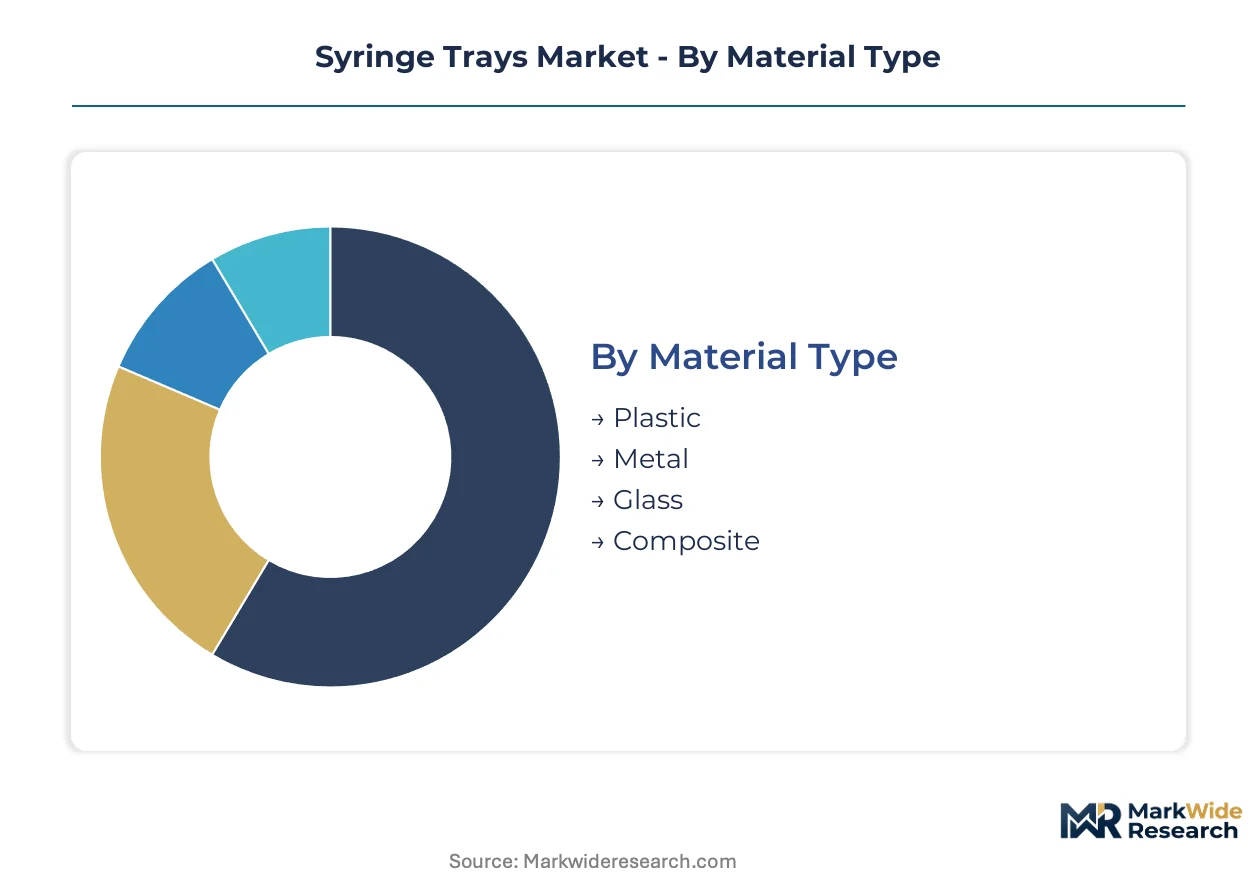
Syringe tray specifications diverge sharply across sterilization compatibility, durability requirements, and point-of-care workflow integration. Material selection and capacity configuration determine whether trays serve high-throughput vaccination campaigns or precision surgical suites.
Material Type:
Polymer formulations and metal alloys compete on gamma-radiation tolerance, autoclave cycle endurance, and disposal pathway economics.
- Plastic:Medical-grade polypropylene homopolymer and copolymer formulations dominate current procurement volumes through cost efficiency and terminal sterilization compatibility. German hospital networks specify ISO 10993-tested grades for oncology prefilled syringe applications where extractables control is paramount.
- Metal:Anodized aluminum trays withstand 500+ steam sterilization cycles in surgical suites, though forming limitations restrict wall thickness to 1.5 mm minimum and constrain high-density syringe configurations. Japanese tertiary care centers retain metal architectures for robotic surgery instrument sets.
- Glass:Borosilicate tray variants serve specialized compounding pharmacy operations requiring inert surfaces for cytotoxic drug preparation.
- Composite:Hybrid cellulose-polymer platforms with barrier coatings address single-use plastic procurement bans in Dutch and Nordic hospital purchasing cooperatives.
Plastic leads on scale; composite gains share fastest through regulatory pressure on disposable polymer consumption.
End User:
Procurement authority concentrates differently across integrated delivery networks, independent facilities, and pharmaceutical manufacturing operations.
- Hospitals:Centralized pharmacy committees in California and New York health systems specify tray performance benchmarks alongside drug formulary decisions, consolidating purchasing around three-tier certification grades.
- Clinics:Freestanding ambulatory surgery centers in Texas, Florida, and Arizona are disaggregating tray procurement from integrated delivery network contracts, opening direct manufacturer relationships.
- Laboratories:Diagnostic and research facilities prioritize particulate control and cleanroom compatibility over unit economics.
- Pharmacies:Retail and specialty pharmacy chains bundle trays with broader medication delivery kits to capture system-level contracts.
Hospitals concentrate purchasing volume; clinics are expanding most quickly as independent facility networks proliferate.
Product Type:
Durability architecture determines capital deployment, sterilization logistics, and total cost of ownership across use cycles.
- Single-use:Gamma-sterilized polypropylene trays dominate mass immunization programs where throughput speed outweighs per-unit material cost. EU Green Deal circular economy targets are accelerating purchasing shifts toward recyclable architectures in France and Italy.
- Reusable:Autoclave-compatible designs retain procurement share in surgical suites where 500+ cycle validation justifies capital investment; manufacturers must document dimensional stability through accelerated aging protocols.
- Disposable:Ethylene oxide or gamma-sterilized variants serve intermediate-use scenarios in emergency medicine and field deployment.
- Customizable:Modular tray systems with configurable cavity counts address pharmaceutical kit assembly operations requiring Unique Device Identification labeling integration.
Single-use commands volume; customizable designs climb fastest through pharmaceutical packaging service revenue expansion.
Capacity:
Syringe count per tray aligns with procedure type, storage density requirements, and automated dispensing system compatibility.
- 10-syringe:Compact formats serve point-of-care administration in oncology and biologics delivery where individual patient dosing precision is paramount.
- 20-syringe:Mid-capacity designs balance handling ergonomics with pharmacy workflow efficiency in hospital central fill operations.
- 50-syringe:Intermediate configurations address regional vaccination campaigns and multi-patient ward stocking.
- 100-syringe:High-density formats maximize transport and storage efficiency for mass immunization programs; wall thickness and stacking load specifications become critical at this scale.
20-syringe formats lead on procurement frequency; 100-syringe configurations are scaling fastest through pandemic preparedness infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision medical device manufacturing corridor concentrates tray production capacity and sterilization infrastructure across the Rhine-Ruhr and Baden-Württemberg industrial zones.
United States
Texas, Florida, and Arizona ambulatory surgery centers are disaggregating tray procurement from integrated delivery network contracts. FDA 21 CFR Part 820 quality system regulations govern validation requirements for US market access. California and New York health systems centralize pharmacy committee purchasing decisions that specify tray performance benchmarks alongside drug formulary selection.
Germany
German tertiary care centers specify ISO 10993-tested polypropylene grades for oncology prefilled syringe applications. EU MDR Annex I general safety and performance requirements mandate biocompatibility documentation and Unique Device Identification labeling. Notified bodies in Frankfurt and Stuttgart enforce strict extractables and leachables data requirements for polymer additive formulations.
Japan
Japanese hospital procurement networks prioritize cleanroom-molded tray designs for infection control protocols in tertiary care centers. PMDA medical device regulations align with ISO 13485 quality management standards for tray imports and domestic production. The Kansai region around Osaka anchors precision molding operations serving Southeast Asian export markets.
Netherlands
Dutch healthcare purchasing cooperatives are accelerating shifts toward hybrid cellulose-polymer composite trays under extended producer responsibility frameworks. EU Green Deal circular economy targets drive recyclable architecture procurement in Amsterdam and Rotterdam hospital networks. Domestic converters leverage barrier coating technologies to address single-use plastic bans without sacrificing sterile barrier performance.
France
French hospital systems are consolidating supplier rosters around three-tier certification grades for standardized medication delivery kits. ANSM national pharmaceutical regulator oversight extends to tray biocompatibility testing requirements under EU MDR harmonization. The Île-de-France region concentrates pharmaceutical kit assembly operations requiring serialized production and UDI labeling integration.
Syringe Trays Market Competitive Environment
Global majors compete with regional champions across sterilization validation capabilities and distribution density. The vendor base segments between captive resin compounders, cleanroom-molded specialists, and distribution-integrated bundlers. Three archetypes dominate: polymer science integrators controlling upstream material specifications, precision molding houses certified to ISO 14644-1 cleanroom standards, and logistics platforms leveraging pharmacy system relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers secure gamma irradiation access and hospital procurement contracts.
Among US-based diversified health care conglomerates, Becton, Dickinson and Company and Cardinal Health occupy positions spanning material science through distribution integration. Terumo Corporation represents the precision manufacturing archetype with Japanese cleanroom-molded production serving Asian hospital networks. These three companies exemplify how geographic origin and corporate structure map to distinct competitive positioning within sterilization-compatible tray supply.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Terumo Corporation |
| Cardinal Health |
| Medline Industries |
| Addent Inc. |
| Treiber Trays |
| Baxter International |
| Henry Schein |
| ICU Medical |
| Others |
Value Chain & Pricing Dynamics
Cleanroom-molded manufacturing specialists concentrated in Germany's Baden-Württemberg and Japan's Kansai regions command wage premiums that compress margins at the standard tier while widening spreads to premium ISO 14644-1 certified grades. Labor-cost differentials between Rhine-Ruhr precision molding clusters and emerging Central European converter networks directly shape three-tier pricing architectures across hospital procurement contracts.
Pricing Analysis
Medical-grade polypropylene resin costs pass through to tray pricing with 2-3 quarter lag structures, compressing margins when propylene monomer supply tightens at Gulf Coast petrochemical complexes. Pricing stratifies across premium, standard, and economy tiers differentiated by ISO 10993 certification completeness and gamma-sterilization validation documentation. Cost compression in the economy tier is intensifying as Indian and Chinese converters enter European hospital supply chains. Ambulatory surgery centers in Texas and Florida exhibit highest price sensitivity, while German oncology pharmacy committees prioritize extractables control over unit economics.
Supply Chain Analysis
Workforce availability for ISO 14644-1 certified technicians concentrates manufacturing gravity in Germany, Japan, and select US Midwest medical device corridors. Raw material supply draws from Saudi and US Gulf Coast propylene feedstock, Belgian gamma-irradiation sterilization services, and Chinese masterbatch additive formulations. Single-source vulnerability clusters around concentrated sterilization capacity in Belgium and Germany, creating geographic bottlenecks for manufacturers lacking captive assets. Distribution runs through integrated delivery network pharmacy committees in California and New York, supplemented by direct manufacturer relationships with disaggregated ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Syringe tray procurement has shifted toward premium specifications as EU MDR traceability mandates and FDA sterilization validation requirements eliminate uncertified competitors from hospital formularies. This quality-upgrading dynamic favors incumbents with existing regulatory dossiers over price-based challengers.
For Market Incumbents: Lock in gamma-irradiation sterilization partnerships in Belgium and Germany to defend against single-source capacity bottlenecks threatening fulfillment commitments. Deepen captive resin compounding capabilities to stabilize input cost exposure from Gulf Coast petrochemical volatility. Prioritize UDI labeling integration investments to capture pharmaceutical kit assembly service revenue before notified body backlogs extend competitor timelines. For New Entrants and Emerging Players: Begin with hybrid cellulose-polymer composite tray production serving Dutch and Nordic hospital purchasing cooperatives facing single-use plastic procurement bans. Target ambulatory surgery center networks in Texas, Florida, and Arizona where disaggregated purchasing from integrated delivery networks opens direct manufacturer relationships. Lead with extended producer responsibility compliance messaging to differentiate against legacy polymer incumbents. For Investors and Strategic Acquirers: Pharmaceutical packaging conglomerates are the most active acquirer in this space, seeking tray manufacturers with EU MDR technical documentation and cleanroom-molded production assets. Long-term viability hinges on regulatory certification moats rather than manufacturing scale alone. Monitor notified body queue lengths for ISO 10993 biocompatibility testing as the signal for competitive entry timing—backlog clearance accelerates new product launches and M&A arbitrage windows.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body scrutiny in Frankfurt and Stuttgart is rejecting submissions lacking extractables data, raising compliance barriers. |
| Gamma Sterilization Partnership | Belgian and German irradiation facility concentration creates captive capacity advantages for contracted manufacturers. |
| Hybrid Composite Material Development | Dutch healthcare purchasing cooperatives are accelerating recyclable tray procurement under EU Green Deal circular economy targets. |
| UDI Labeling Integration Service | Pharmaceutical kit assembly operations in Île-de-France require serialized production creating recurring revenue streams. |
| Cleanroom Manufacturing Certification | ISO 14644-1 Class 7 and Class 8 environments reduce particulate risk for oncology prefilled syringe applications. |
Study Parameters
Multiple input streams — hospital pharmacy procurement managers, biomedical engineers at German tertiary care centers, GPO contracts specialists, and regulatory affairs leads at notified bodies — were reconciled against secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement contract repositories, and customs trade data for medical-grade polymer imports. Bottom-up tray volume estimates by material type and capacity configuration were cross-referenced against top-down healthcare expenditure allocations for medication delivery systems.
Historical shipment patterns were cross-referenced against expert panel inputs to establish baseline demand trajectories across the projection horizon. Segmentation modeling incorporated material type, sterilization compatibility, end-user facility category, and regional regulatory cluster dimensions. CAGRs were derived from weighted average growth contributions across these segments, with specific adjustment for pandemic preparedness infrastructure investment cycles and EU Green Deal circular economy procurement mandate phase-ins.
Several conditions sit outside the modeled scope, including unannounced changes to FDA 21 CFR Part 820 quality system enforcement intensity and unforeseen disruptions to propylene monomer supply from Gulf Coast petrochemical complexes. Practitioners should monitor notified body staffing levels and EU MDR transition deadline extensions for early signals of competitive entry window compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Global First Aid Kit Packaging Market