
 Plastic Healthcare Packaging Market | 2026-2036
Plastic Healthcare Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Healthcare Packaging Market Intelligence
The end-user mix for plastic healthcare packaging is shifting from traditional hospital supply channels toward direct fulfillment for pharmaceutical companies and specialized laboratories. Amcor Limited leverages its global manufacturing footprint to serve large pharmaceutical clients with flexible and rigid packaging. Gerresheimer AG specializes in primary packaging like vials and syringes, competing on material science. West Pharmaceutical Services, Inc. focuses on integrated containment and delivery systems for injectable drugs.
Plastic healthcare packaging comprises polymer-based containers designed to protect and deliver medical devices and pharmaceutical products. It must meet strict sterility, barrier, and leachables/extractables standards to ensure drug stability and patient safety. Primary packaging formats like rigid containers and blister packs constitute the highest-value segment, requiring direct product contact validation. High-performance Polypropylene and PET materials are gaining share from PVC based on superior chemical resistance and safety profiles for sensitive biologics.
The US FDA and the European Medicines Agency (EMA) enforce strict guidelines on material selection, extractables testing, and packaging validation for pharmaceuticals. In parallel, China's NMPA is aligning its own GB standards with international norms, impacting market access for all manufacturers. Stakeholder decisions will center on balancing the cost of advanced polymer resins against the rising compliance burden for new drug delivery systems and combination products.
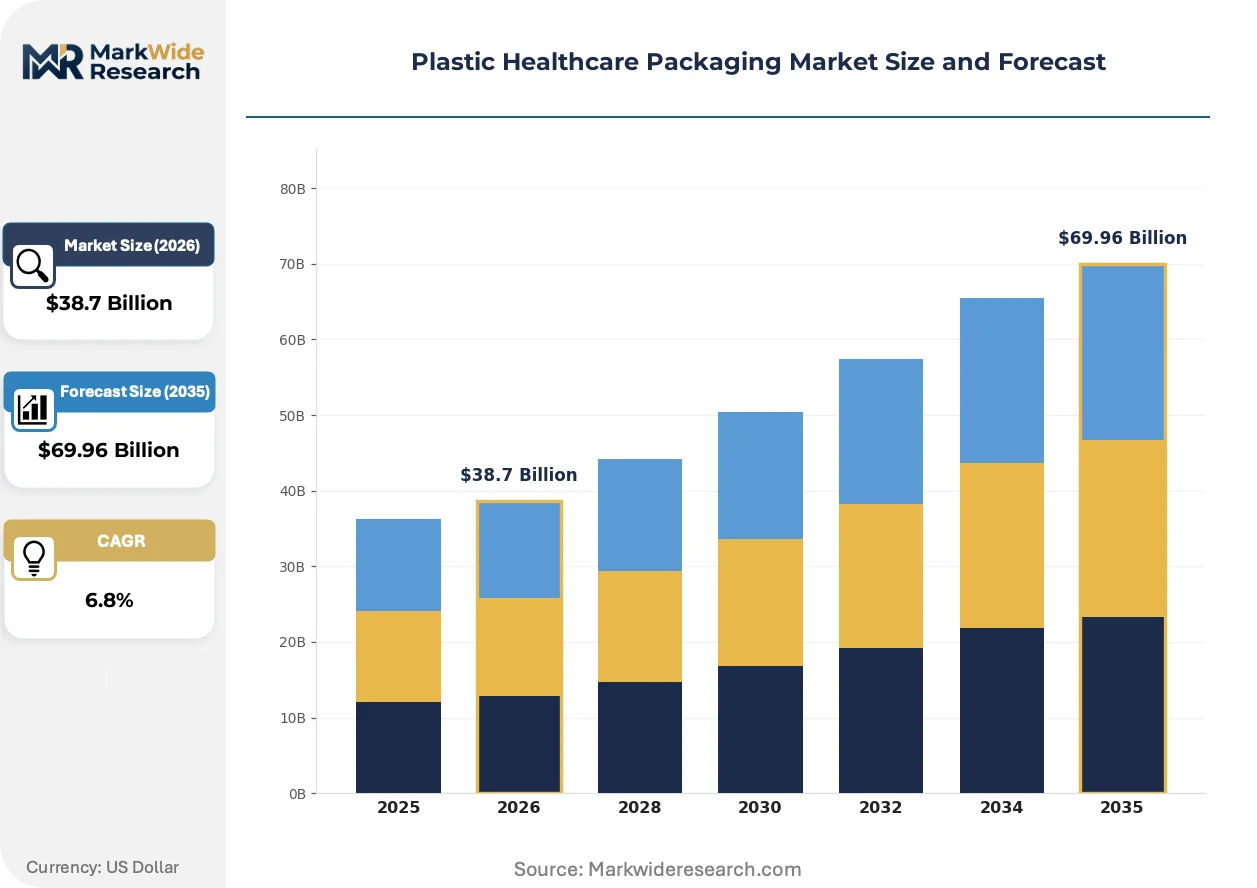
Market Dynamics
The convergence of stringent regulatory frameworks for material safety and rising pharmaceutical demand for high-barrier packaging for biologics defines the market's core tension. This dictates material selection, compliance investment, and manufacturing location.
Growth Catalysts
- Biologic Drug Pipeline:The expansion of biologic and cell therapies requires sterile, inert primary packaging with superior barrier properties, pulling demand for advanced polymers to ensure drug stability.
- EU Medical Device Regulation:The MDR framework mandates stricter material traceability, creating a catalyst for suppliers offering fully validated and compliant material solutions.
- Asian Production Growth:Manufacturing concentration in China and India to support domestic pharmaceutical industries creates localized demand for high-grade plastic packaging.
Market Restraints
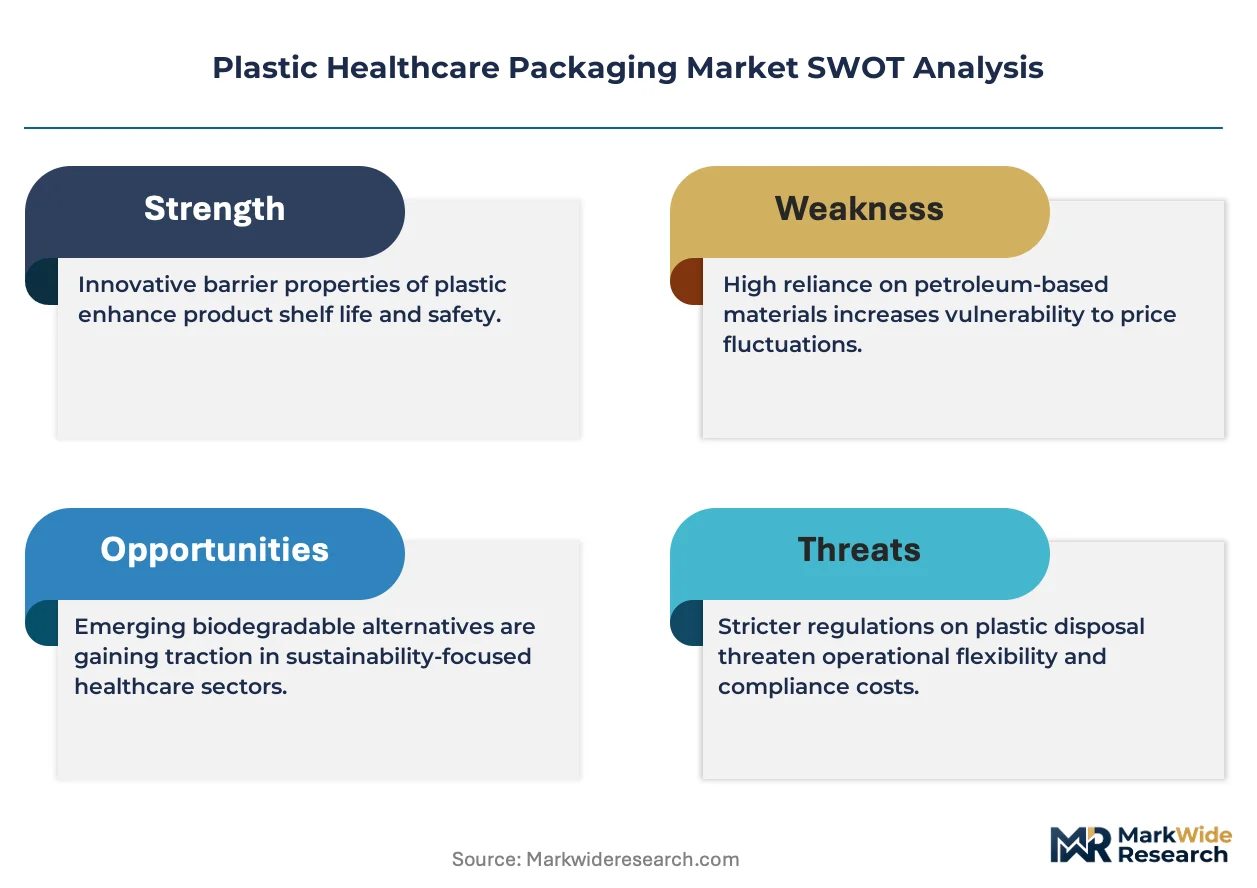
- Resin Price Volatility:The cost of key feedstocks like Polypropylene is linked to fluctuating crude oil prices, creating margin pressure for packaging converters.
- Regulatory Validation Cycles:Lengthy and expensive testing protocols required by the FDA and EMA for new materials can deter innovation and slow market entry.
- Glass Substitution Barrier:Borosilicate glass remains the incumbent material for many injectable drug vials, limiting plastic conversion in some high-value segments due to its established safety profile.
Strategic Opportunities
- Combination Products:Growth of drug-device combination products like autoinjectors opens a market for integrated containment and delivery systems with complex polymer components.
- Southeast Asian Expansion:Rising pharmaceutical manufacturing in countries like Vietnam and Indonesia presents an underpenetrated market for specialized healthcare packaging suppliers.
- Smart Packaging Integration:Embedding sensors into primary packaging enables supply chain tracking and temperature monitoring, creating a new value layer for high-value drugs.
Industry Challenges
- Global Standards Alignment:Complying with divergent standards from the US FDA, European EMA, and China's NMPA creates significant operational complexity and cost for global product lines.
- Capital Expenditure:Building and certifying cleanroom manufacturing facilities for sterile packaging requires substantial upfront capital, raising barriers to entry.
- Specialized Talent Scarcity:A shortage of polymer scientists with expertise in leachables and extractables analysis constrains product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Healthcare Packaging Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Rigid Containers, Pouches, Bottles End User: Hospitals, Pharmaceutical Companies, Clinics, Laboratories Material: Polyethylene, Polypropylene, PVC, PET Packaging Type: Primary Packaging, Secondary Packaging, Tertiary Packaging, Custom Solutions |
| Companies Covered | Amcor Limited, Gerresheimer AG, Schott AG, Berry Global, Inc, AptarGroup, Inc., West Pharmaceutical Services, Inc., WestRock Company, Becton & Dickinson Company, Constantia Flexibles Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Healthcare Packaging Market Strategic Shifts & Innovations
Material science advancements are intersecting with circular economy pressures and evolving regulatory demands. These forces compel a re-evaluation of polymer selection, product design, and supply chain validation across the healthcare packaging sector.
Cyclic olefin copolymers (COCs) provide glass-like clarity and superior barrier properties for sensitive biologics. Pharmaceutical firms developing protein-based therapies and mRNA vaccines are the primary adopters, accelerating qualification. COC's use in pre-filled syringes and vials is expanding into applications traditionally dominated by borosilicate glass, especially for high-value injectable drugs.
The EU's Medical Device Regulation (MDR) imposes stricter requirements for material traceability and post-market surveillance on packaging classified as a medical device. This increases the compliance burden and validation costs for suppliers, especially for combination products. Rigid packaging manufacturers are most affected, investing in more robust quality management systems.
Pharmaceutical firms increasingly bypass hospital distributors for direct sourcing agreements with specialized packaging manufacturers. This disintermediates broad-line distributors, favoring vendors with deep technical expertise for specific drug classes. The trend is most prominent in the United States and Europe for high-value biologics and cell therapy supply chains.
Plastic Healthcare Packaging Market Segmentation
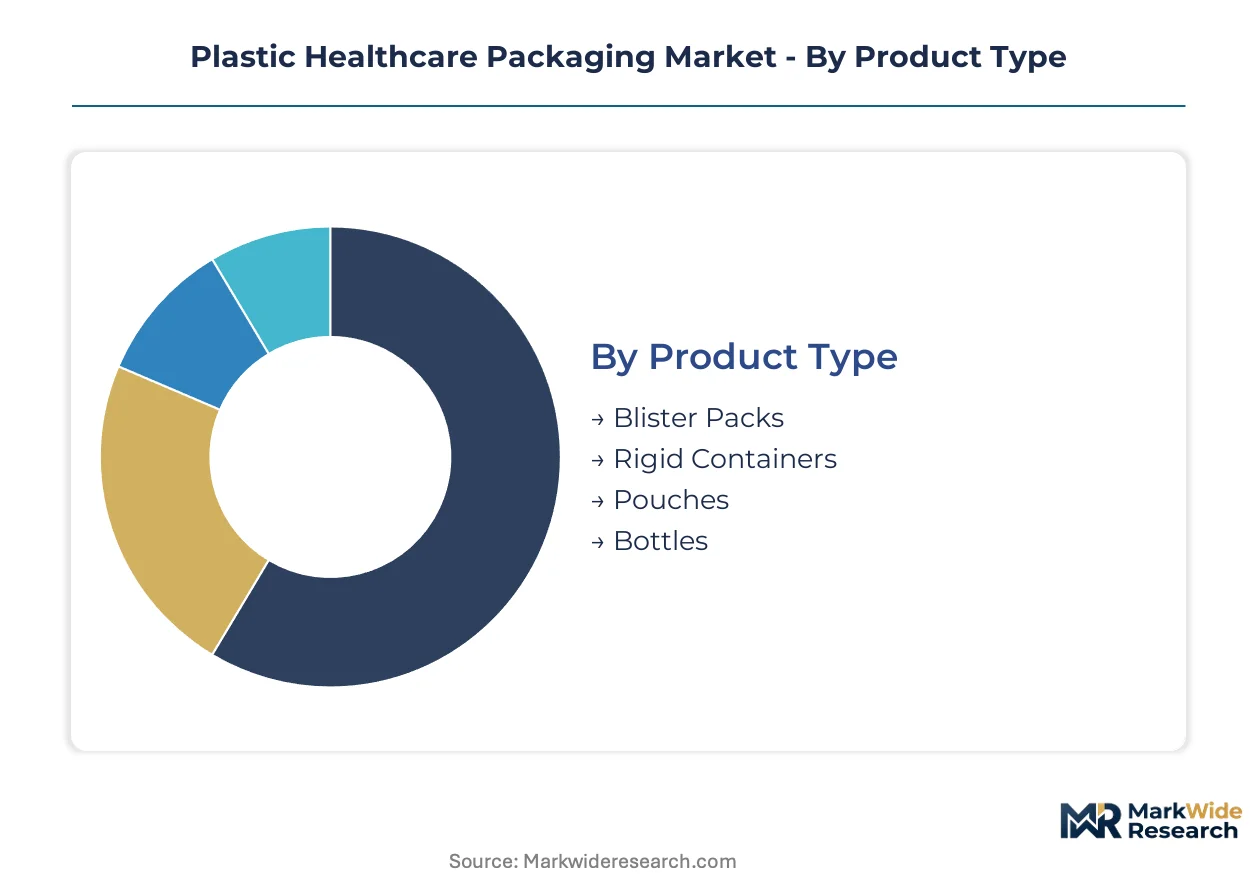
The plastic healthcare packaging market segments reflect the diverse needs of pharmaceutical manufacturers and healthcare providers, balancing cost-effectiveness with stringent regulatory compliance. Understanding these classifications reveals where innovation is concentrating and where established solutions maintain market dominance.
Product Type:
The product type segmentation highlights the balance between high-volume, cost-effective solutions and specialized, high-barrier formats crucial for drug stability.
- Rigid Containers:These robust containers, often made from PET or polypropylene, provide excellent physical protection and barrier properties for solid dose drugs and medical devices. Demand for rigid containers remains strong in pharmaceutical logistics, ensuring product integrity through complex supply chains.
- Blister Packs:Blister packs offer unit-dose protection and tamper-evidence, primarily for tablets and capsules, and are critical for patient compliance and product security. Their widespread use across over-the-counter and prescription medications drives significant volume, particularly in emerging markets like India.
- Pouches:Flexible pouches, typically multi-layered films, provide sterile environments for medical devices and some liquid formulations, offering lightweight and space-efficient packaging.
- Bottles:Plastic bottles, commonly made from HDPE or PET, serve as primary packaging for liquid medications, syrups, and some bulk solid dosage forms, valued for their economy and versatility.
Today's leader: Rigid Containers. Tomorrow's challenger: Blister Packs.
End User:
End-user demand patterns are shifting, reflecting evolving drug delivery models and a direct-to-manufacturer procurement trend for specialized therapies.
- Pharmaceutical Companies:These entities represent a significant and expanding end-user segment, increasingly sourcing specialized primary packaging directly for biologics, cell therapies, and injectables. Their demand is driven by the need for validated, high-performance materials to protect sensitive drug formulations.
- Laboratories:Research and clinical laboratories require specialized plastic packaging for reagents, diagnostic kits, and sample collection, prioritizing material inertness and sterility. Their procurement patterns are influenced by stringent quality control and regulatory standards from bodies like the US FDA and European Medicines Agency.
- Hospitals:Hospitals utilize plastic packaging for a wide array of medical supplies, devices, and sterile disposables, focusing on infection control and operational efficiency.
- Clinics:Smaller medical clinics procure plastic packaging for basic medical supplies and pharmaceutical dispensing, valuing convenience and cost-effectiveness for routine procedures.
Pharmaceutical Companies represent the fastest-growing trajectory, driven by biologics pipelines.
Material:
Material selection is increasingly driven by performance requirements, with advanced polymers displacing traditional options due to enhanced barrier properties and safety profiles.
- Polypropylene:This versatile polymer offers excellent chemical resistance, heat stability for sterilization, and a favorable safety profile, making it a preferred choice for vials, caps, and rigid containers. Polypropylene is gaining share in primary packaging applications, particularly for sensitive biologics and injectables.
- PET:Polyethylene terephthalate provides good barrier properties and transparency, widely used for bottles and some rigid containers for liquid pharmaceuticals and medical devices. Its established recycling infrastructure also supports sustainability objectives within the healthcare sector.
- Polyethylene:High-density polyethylene (HDPE) and low-density polyethylene (LDPE) are common for bottles, caps, and flexible films due to their cost-effectiveness and flexibility.
- PVC:Polyvinyl chloride offers clarity and flexibility but is facing substitution pressures from other polymers due to concerns over leachables and environmental impact, particularly in Europe.
Polypropylene and PET materials are gaining share, while PVC faces compliance pressures.
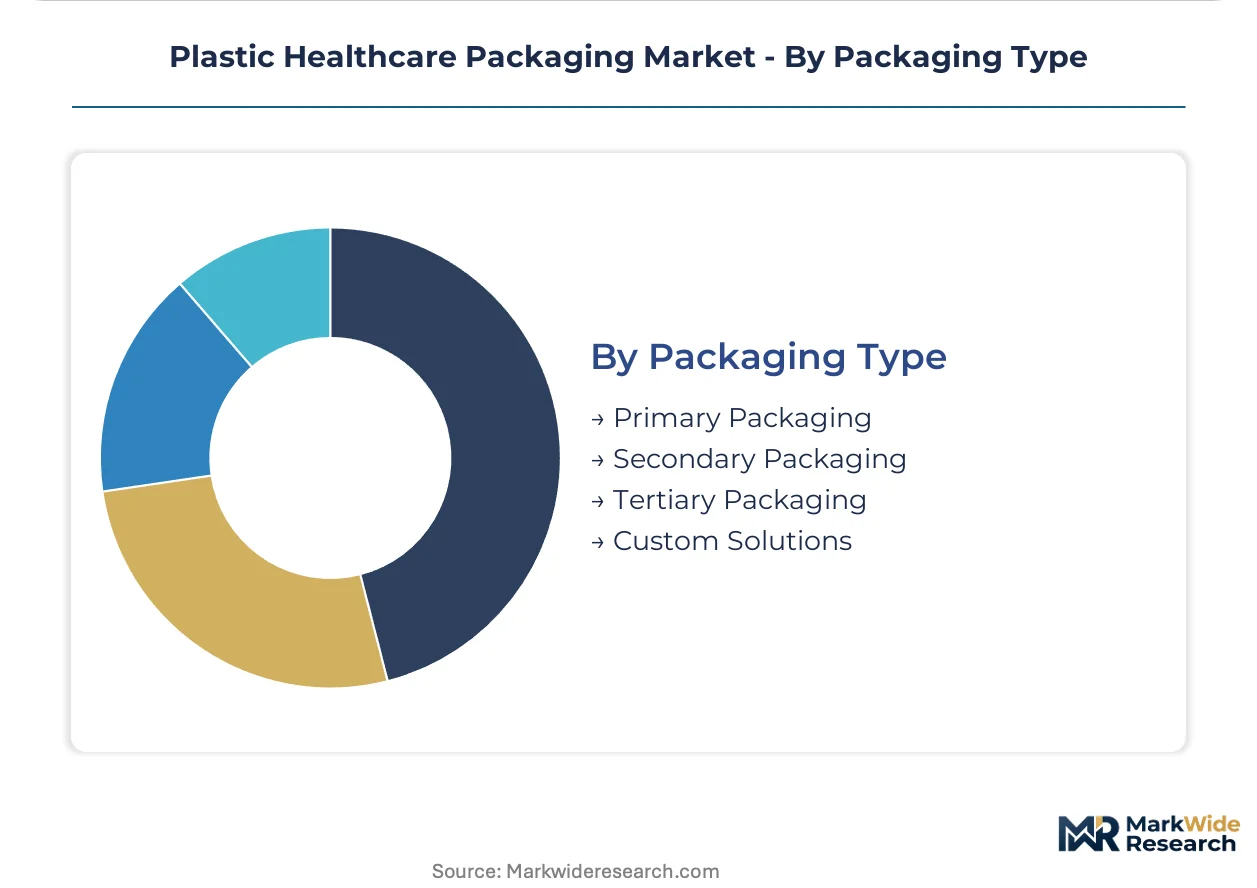
Packaging Type:
The classification by packaging type reflects the distinct functional and regulatory demands across the entire drug delivery value chain.
- Primary Packaging:This category encompasses materials in direct contact with the pharmaceutical product, such as vials, syringes, and blister cavities, requiring the highest levels of sterility and extractables testing. Primary packaging constitutes the highest-value segment, subject to rigorous validation by regulators like China's NMPA.
- Custom Solutions:Tailored packaging designs for specific drug-device combination products or unique delivery systems fall into this segment, demanding specialized polymer engineering and integration expertise. The growth of autoinjectors and complex drug delivery devices fuels demand for these bespoke solutions.
- Secondary Packaging:This includes cartons, boxes, and other protective layers that enclose primary packaging, providing additional protection and space for labeling and patient information.
- Tertiary Packaging:Designed for shipping and logistics, tertiary packaging like pallets and stretch wrap ensures the safe transport of bulk pharmaceutical products and medical devices through the supply chain.
Primary Packaging remains central to patient safety, with Custom Solutions expanding for combination products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's pharmaceutical manufacturing hubs increasingly drive demand for plastic healthcare packaging, reflecting significant domestic drug production and export growth. This concentration influences supply chain development and material innovation across the Asia-Pacific region. Regulatory alignment efforts and specialized material requirements shape market dynamics in key global pharmaceutical centers.
United States
Demand in the United States centers on high-barrier packaging for biologic drugs and advanced cell therapies. The US FDA enforces rigorous guidelines for material selection and extractables testing, impacting new product development cycles. The Boston-Cambridge biotechnology cluster leads in adopting specialized primary packaging for sensitive injectable formulations.
Germany
Germany's market for plastic healthcare packaging focuses on high-performance materials for advanced medical devices and pharmaceutical exports. The European Medicines Agency (EMA) and the EU Medical Device Regulation (MDR) impose strict validation and traceability requirements. The Rhine-Main region, with its strong pharmaceutical industry presence, drives innovation in sterile packaging solutions.
China
China's market expansion is fueled by its rapidly growing domestic pharmaceutical industry and increasing demand for sterile primary packaging. The National Medical Products Administration (NMPA) is aligning its GB standards with international norms, influencing material choices. Manufacturing clusters in the Yangtze River Delta are key production centers for high-grade plastic healthcare packaging.
India
India's demand for plastic healthcare packaging stems from its position as a major producer of generic drugs and vaccines for global markets. The Central Drugs Standard Control Organization (CDSCO) regulates packaging quality and safety for pharmaceutical products. Pharmaceutical manufacturing hubs in Hyderabad and Gujarat are expanding their requirements for cost-effective, compliant packaging materials.
Japan
Japan exhibits consistent demand for high-quality, precision-engineered plastic packaging for its advanced pharmaceutical and medical device sectors. The Pharmaceuticals and Medical Devices Agency (PMDA) sets stringent standards for packaging integrity and patient safety. Tokyo and Osaka remain critical centers for pharmaceutical R&D and specialized packaging procurement.
Plastic Healthcare Packaging Market Key Industry Players
Strategic partnerships dominate the current landscape, as packaging manufacturers collaborate with pharmaceutical companies to develop specialized solutions. The market exhibits a tiered structure, with global leaders offering diverse portfolios alongside niche specialists focusing on specific material science. Global footprint leverage and integrated system development are common competitive moves.
Specialists in material science and integrated solutions, such as Gerresheimer AG, exemplify the focus on primary packaging like vials and syringes. Amcor Limited represents the global diversified players, leveraging its extensive manufacturing footprint to serve large pharmaceutical clients with both flexible and rigid packaging. West Pharmaceutical Services, Inc. occupies a position as an integrated containment and delivery systems specialist for injectable drugs.
| Leading Market Players |
|---|
| Amcor Limited |
| Gerresheimer AG |
| Schott AG |
| Berry Global, Inc |
| AptarGroup, Inc. |
| West Pharmaceutical Services, Inc. |
| WestRock Company |
| Becton & Dickinson Company |
| Constantia Flexibles Group |
| Others |
Cost & Logistics Intelligence
Material science advancements, particularly in advanced polymers, are reshaping cost economics for plastic healthcare packaging while simultaneously driving supply concentration towards specialized manufacturers. This shift impacts both material procurement and final product pricing.
Pricing Analysis
Resin price volatility directly impacts plastic healthcare packaging costs, with converters often passing increased feedstock expenses onto buyers. Pricing predominantly follows contract-based long-term offtake agreements, particularly with large pharmaceutical clients. Material performance, including superior barrier properties for sensitive biologics, and stringent regulatory compliance, drive differentiation. Pricing pressure stems from rising advanced polymer costs and validation expenses, with pharmaceutical companies exhibiting lower price sensitivity than hospitals for high-value biologics.
Supply Chain Analysis
Specialized talent scarcity for polymer scientists in China and India impacts product development timelines for plastic healthcare packaging. Supply concentration centers heavily in China and India, driven by domestic pharmaceutical production, and relies on key feedstocks like Polypropylene and PET. Regulatory divergence among the US FDA, EMA, and China's NMPA presents a significant structural risk. Distribution runs through direct sourcing agreements with pharmaceutical companies for high-value biologics, alongside traditional hospital supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic healthcare packaging market functions as a stable compounder, driven by the consistent expansion of biologic and cell therapies. This sustained demand underpins long-term growth prospects across the sector.
For Market Incumbents: Acquire specialized polymer engineering firms to deepen material science expertise for advanced biologics packaging. Incumbents must invest in expanding certified cleanroom manufacturing facilities to counter capacity constraints and meet stringent regulatory requirements. This defends against emerging material science challengers and lengthy validation cycles, leveraging certification investment.
For New Entrants and Emerging Players: Begin with targeted expansion into Southeast Asian countries like Vietnam and Indonesia, where pharmaceutical manufacturing is rising. Focus on offering fully validated, compliant material solutions for combination products, which represent an underserved niche. This strategy allows new entrants to penetrate under-resourced markets with specialized healthcare packaging.
For Investors and Strategic Acquirers: Valuations sit cheapest among smaller, specialized material science firms with proprietary polymer technologies for healthcare. Focus on long-term viability, driven by sustained demand for high-barrier packaging for biologics and regulatory tailwinds. Target niche specialists in advanced polymers like cyclic olefin copolymers or integrated containment systems. The signal to watch is the accelerated qualification and adoption rates of COCs in pre-filled syringes.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Polymer R&D Investment | Accelerates development of high-barrier materials like COCs for sensitive biologic drugs. |
| Cleanroom Capacity Expansion | Meets rising demand for sterile primary packaging and complies with strict EU MDR standards. |
| Southeast Asia Market Entry | Captures localized demand from pharmaceutical manufacturing growth in countries like India and Vietnam. |
| Integrated Delivery System Development | Supports the growth of complex drug-device combination products like autoinjectors. |
| Regulatory Compliance Platform Upgrade | Streamlines validation processes for new materials under US FDA and China NMPA guidelines. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with robust secondary validation. Interviews engaged pharmaceutical R&D executives, packaging procurement managers, regulatory affairs specialists, and polymer material scientists. Secondary data sources included FDA filings, EMA submissions, China NMPA GB standards, and specialized industry association reports. This approach ensured comprehensive bottom-up and top-down market insights.
Historical reference periods anchored the forecast window, establishing a baseline for projected growth across the analysis window. The analytical framework modeled segmentation dimensions including product type, end user, material, packaging type, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from projected volume and value trends, incorporating inputs like the biologic drug pipeline and regulatory compliance costs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts impacting trade and major new material science breakthroughs. Forecasts reflect assumptions regarding crude oil price stability and sustained regulatory frameworks. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
North America Medical Devices Packaging Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Global First Aid Kit Packaging Market