
 Bio-Medical Packaging Market | 2026-2036
Bio-Medical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Medical Packaging Market Outlook
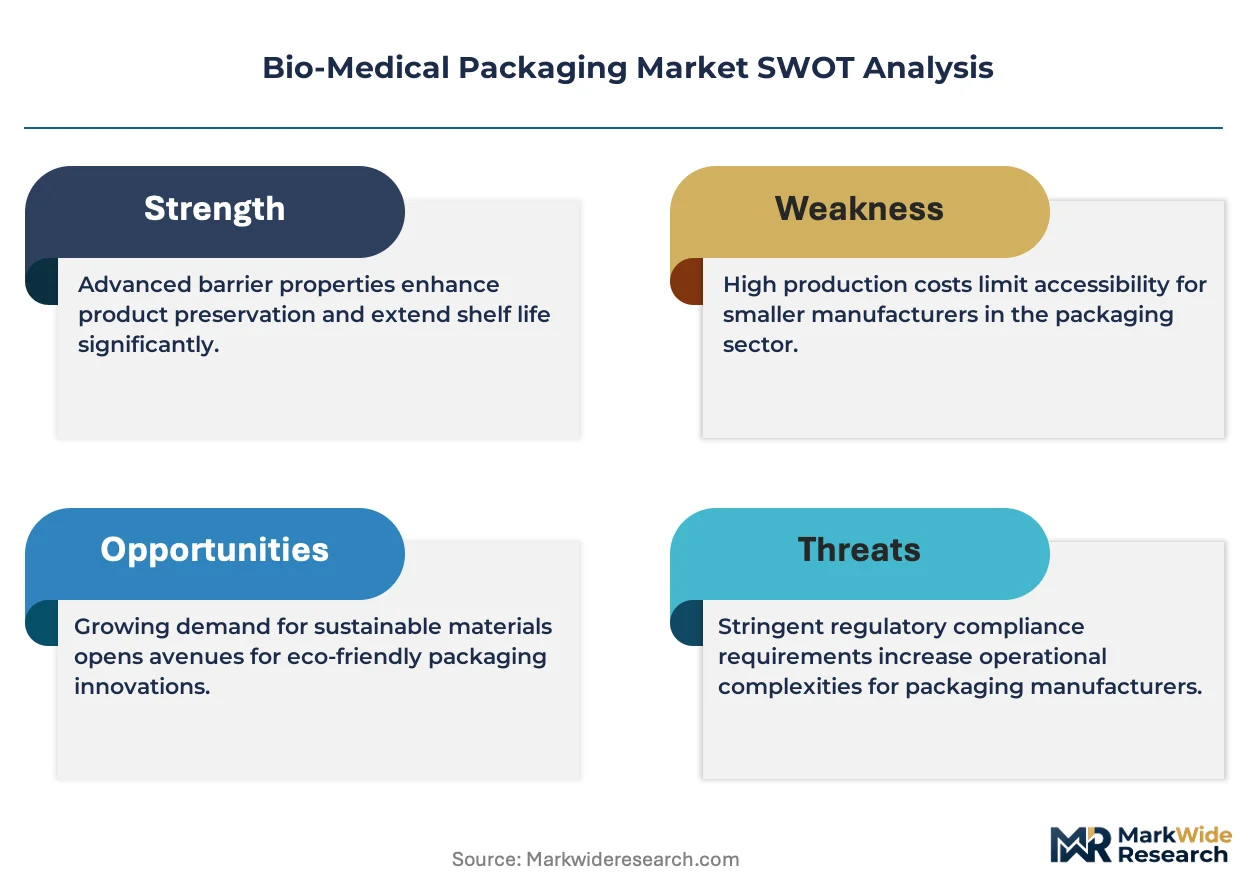
ISO 15378 certification for primary packaging materials is reorganizing competitive access in pharmaceutical supply chains, filtering out suppliers lacking documented quality management systems. Amcor plc leverages its multi-continent manufacturing footprint to sustain compliance across diverse regulatory regimes. Gerresheimer AG anchors its position through specialized glass and polymer solutions for injectable drug delivery. Schott AG dominates in borosilicate glass tubing, a critical input for vial and syringe production.
Bio-medical packaging encompasses sterile barrier systems, temperature-controlled containers, and tamper-evident closures engineered to maintain product integrity from manufacture through patient administration. These systems typically incorporate multi-layer polymer films, desiccant-integrated structures, or validated cold-chain configurations to prevent contamination, moisture ingress, and thermal excursion. Plastic and glass materials command the largest share of material demand, though aluminum blisters are gaining ground in moisture-sensitive oral solid dosage protection. Flexible and semi-rigid formats are expanding fastest as biologics and personalized therapies require adaptive primary packaging geometries that rigid containers cannot accommodate.
FDA's Container Closure System guidance, EMA's Annex 1 revision on sterile manufacturing, and ISO 11607 standards for terminally sterilized medical devices collectively elevate barrier performance and validation documentation requirements. These frameworks compel manufacturers to invest in extractables-leachables testing and accelerated aging protocols before gaining market access. Stakeholders must monitor how evolving serialization and aggregation mandates across regulators reshape packaging line automation investments and supplier qualification timelines.
Market Dynamics
EMA's Annex 1 revision on sterile manufacturing is compressing supplier qualification timelines and forcing pharmaceutical manufacturers to revalidate entire packaging lines, creating a structural bottleneck that favors pre-certified material providers.
Growth Catalysts
- Biologics expansion:Cell and gene therapies require specialized primary containment systems that maintain ultra-cold stability, pulling investment into validated cryogenic pouch formats.
- CDSCO mandate upgrades:India's tightened primary packaging standards for injectables are forcing domestic manufacturers to replace legacy glass and polymer systems with ISO 15378-certified alternatives.
- Cold-chain serialization:German pharmaceutical manufacturers are expanding temperature-assured packaging capacity to meet EMA track-and-trace requirements for biologics distribution.
Market Restraints
- Borosilicate glass supply concentration:Schott AG and a limited European supplier base dominate tubing production, creating vulnerability for vial and syringe manufacturers.
- Extractables-leachables testing burden:FDA Container Closure System guidance requires extensive analytical documentation that extends product development cycles by months.
- Aluminum blister cost volatility:Raw material price swings for moisture-sensitive oral solid dosage protection compress margins for generic drug packagers.
Strategic Opportunities
- Personalized therapy formats:Adaptive primary packaging geometries for small-batch biologics enable premium positioning that rigid containers cannot match.
- Desiccant-integrated structures:Multi-layer polymer films with embedded moisture control open differentiation in tropical climate distribution.
- Automation retrofit demand:Serialization and aggregation mandates across multiple regulators create aftermarket revenue streams for packaging line integration services.
Industry Challenges
- ISO 11607 validation expertise:Terminally sterilized medical device packaging requires specialized quality engineers that contract manufacturers struggle to recruit.
- Accelerated aging protocol investment:Shelf-life verification studies demand capital-intensive environmental chambers that mid-tier suppliers cannot afford.
- Legacy line reconfiguration:Existing rigid container equipment requires costly modification to handle flexible format transitions for biologics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Medical Packaging Market |
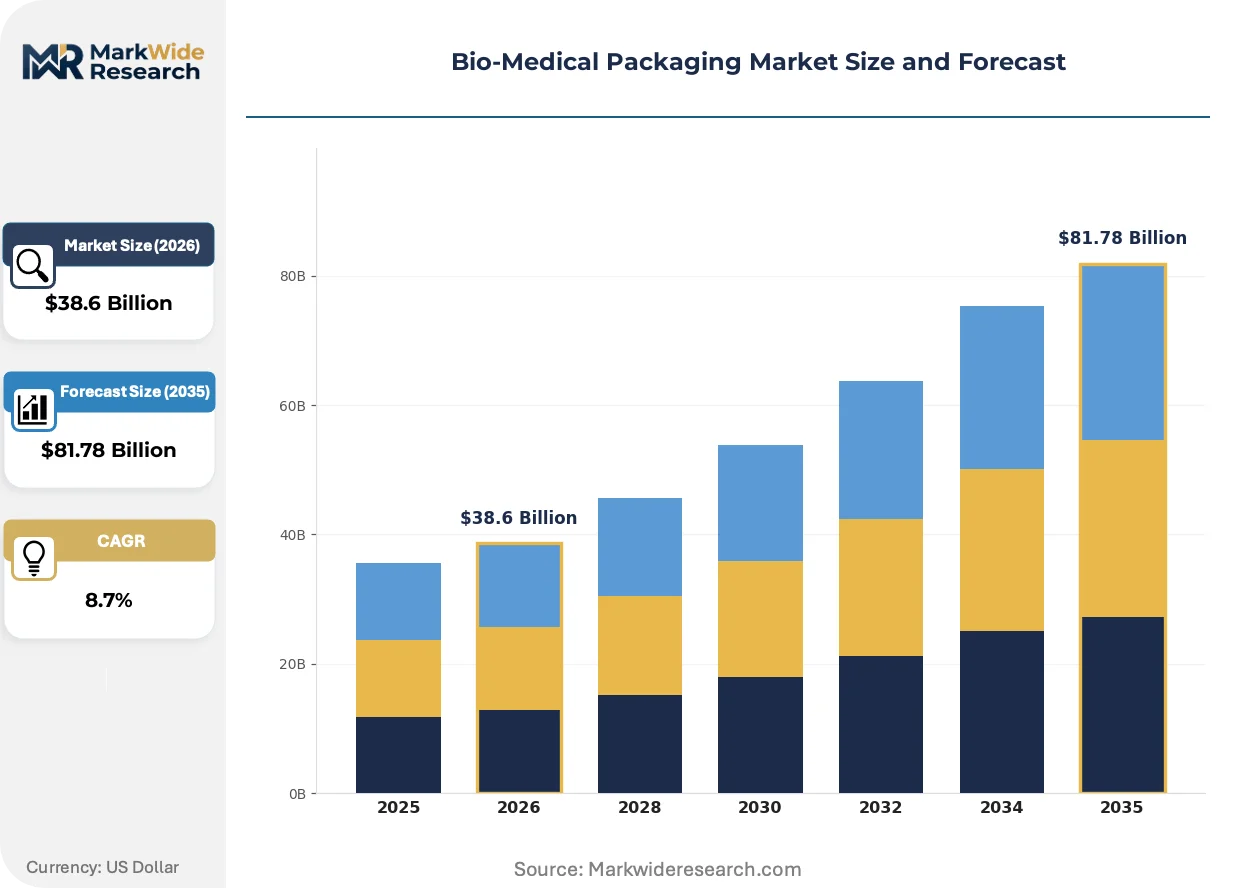
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Pouches, Blisters, Containers Material: Plastic, Glass, Aluminum, Cardboard End User: Pharmaceuticals, Biotechnology, Research Laboratories, Hospitals Form: Rigid, Flexible, Semi-Rigid, Stretchable |
| Companies Covered | Amcor plc, Gerresheimer AG, Schott AG, Berry Global, DuPont de Nemours, AptarGroup, WestRock Company, 3M, West Pharmaceutical Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Medical Packaging Market Strategic Shifts
Material science convergence with regulatory serialization mandates is redefining how sterile barrier systems are engineered, tested, and deployed across pharmaceutical supply chains.
Smart packaging with embedded temperature-logging sensors is fragmenting quality assurance responsibility between manufacturers and logistics providers. Biologics distributors in Germany and the United States are adopting these systems to document cold-chain integrity for EMA and FDA inspections. The technology is fragmenting liability structures and forcing renegotiation of supply contracts to assign accountability for thermal excursions.
REACH restrictions on certain polymer additives are compelling European pharmaceutical packagers to reformulate multi-layer films. The industrial consequence is a scramble for alternative barrier chemistries that maintain moisture and oxygen protection without restricted substances. Oral solid dosage manufacturers in the EU are responding by accelerating supplier audits and dual-sourcing film substrates.
Hospital and clinic buyers are consolidating procurement of sterile barrier systems around pre-validated kit formats that reduce in-house sterilization burden. This consolidation is displacing traditional component purchasing in the United States and Western Europe. Oncology and parenteral nutrition centers are driving this shift to minimize pharmacy compounding risk and streamline inventory management.
Bio-Medical Packaging Market Segmentation
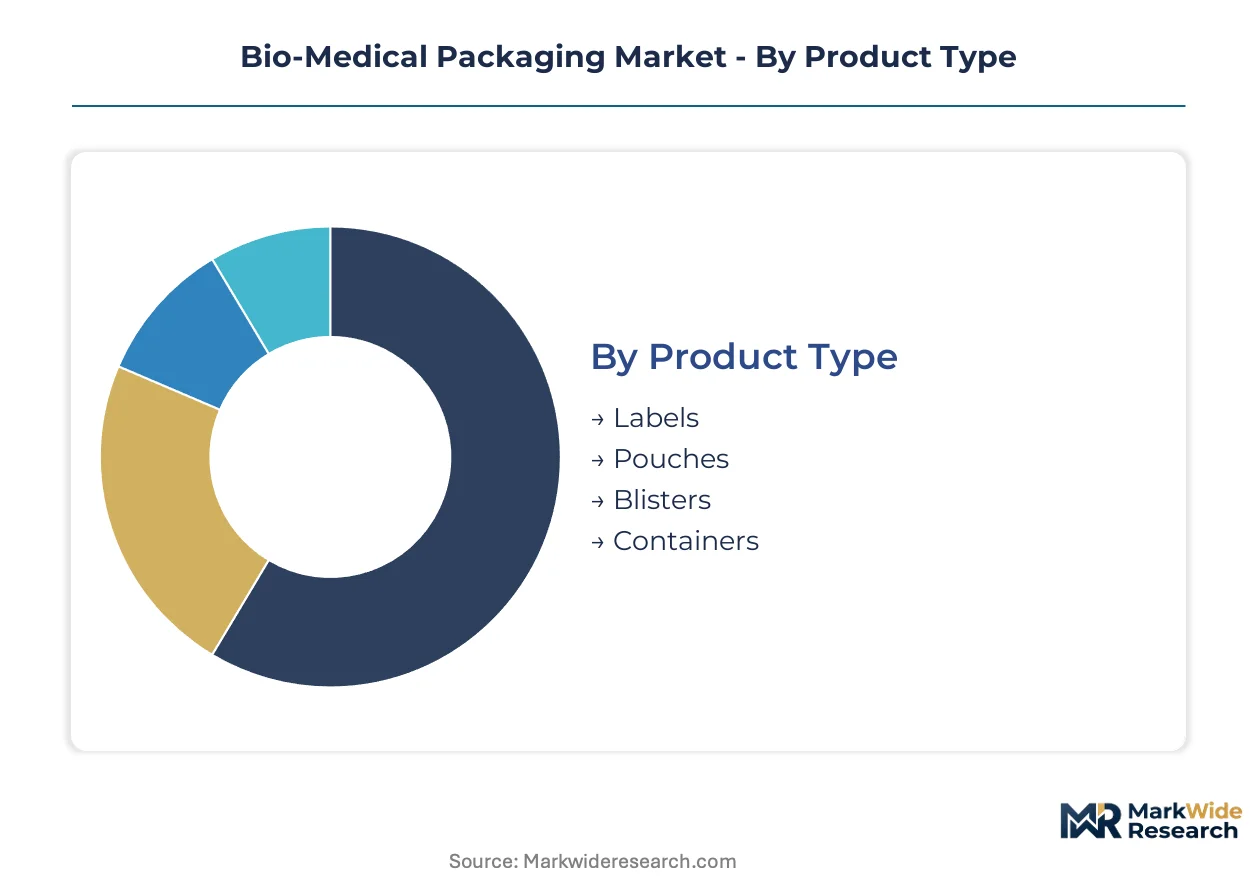
Segmentation in bio-medical packaging reveals how regulatory pressure and therapy format evolution fragment demand across material grades and barrier specifications. Each dimension carries distinct substitution vulnerabilities that reshape supplier positioning.
Product Type:
Substitution pressure concentrates in flexible formats as biologics manufacturers abandon legacy rigid systems for temperature-assured pouch configurations.
- Pouches:Multi-layer polymer laminates with validated cold-chain performance dominate cell and gene therapy containment. German pharmaceutical distributors are expanding temperature-assured pouch capacity to meet EMA serialization mandates for biologics transport.
- Blisters:Aluminum-polymer composites with embedded desiccant structures protect moisture-sensitive oral solid dosages. REACH restrictions on polymer additives are forcing European manufacturers to reformulate barrier chemistries without compromising oxygen protection.
- Containers:Borosilicate glass and engineered polymer vials serve parenteral and injectable drug primary containment. Supply concentrates among Schott AG and limited European tubing producers.
- Labels:Tamper-evident and serialization-compliant substrates integrate track-and-trace functionality for regulatory compliance.
Pouches gain share at the steepest rate while containers anchor the volume base across injectable drug supply chains.
Material:
Cost tier stratification separates premium barrier materials from commodity substrates as extractables-leachables testing elevates qualification thresholds.
- Plastic:Multi-layer polymer films and engineered resins constitute the largest material demand by volume. India's CDSCO tightened primary packaging standards are forcing domestic injectables manufacturers to replace legacy polymer systems with ISO 15378-certified alternatives.
- Glass:Borosilicate tubing for vial and syringe production maintains dominance in parenteral applications. FDA Container Closure System guidance demands extensive extractables-leachables documentation that extends development cycles.
- Aluminum:Foil laminates and cold-form blister substrates protect moisture-sensitive formulations. Raw material price volatility compresses margins for generic drug packagers.
- Cardboard:Secondary and tertiary packaging for distribution protection and serialization aggregation. Demand concentrates in hospital kit consolidation trends across the United States and Western Europe.
Plastic anchors the volume base while aluminum climbs the fastest amid moisture-protection requirements in tropical distribution.
End User:
Application-specific validation requirements create divergent procurement patterns across therapeutic development and patient administration settings.
- Pharmaceuticals:Sterile barrier systems for small-molecule and biologic drug commercialization. EMA Annex 1 revision on sterile manufacturing compresses supplier qualification timelines and forces packaging line revalidation.
- Biotechnology:Ultra-cold containment for cell and gene therapy clinical and commercial supply. Temperature-assured pouch formats are displacing rigid containers in personalized therapy logistics.
- Hospitals:Pre-validated sterile kit procurement to reduce in-house sterilization burden. Oncology and parenteral nutrition centers in the United States drive consolidation around streamlined inventory formats.
- Research Laboratories:Small-batch containment for investigational compounds and clinical trial materials. Flexible format demand expands as adaptive geometries accommodate diverse molecule scales.
Pharmaceuticals anchor the volume base while biotechnology expands most quickly on cell and gene therapy commercialization.
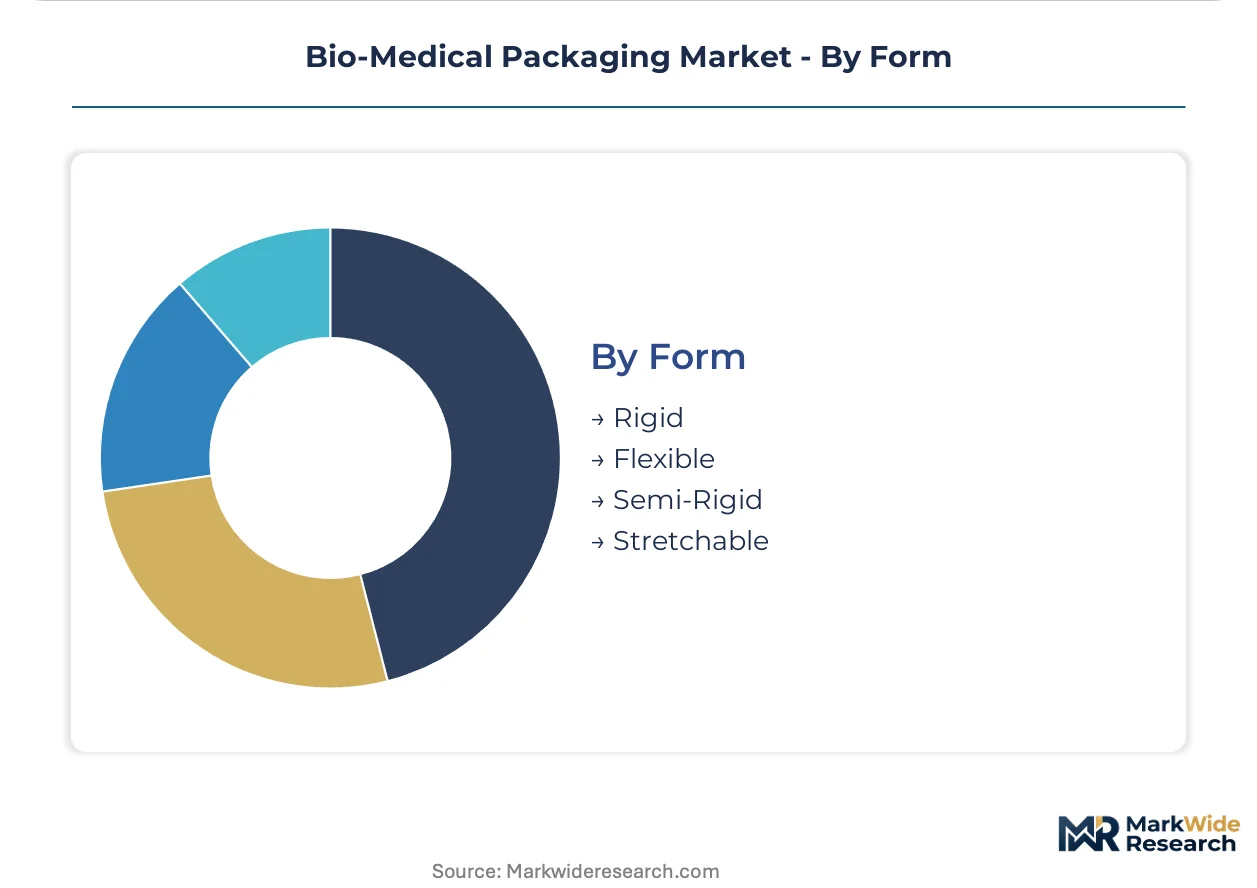
Form:
Supply concentration in rigid equipment manufacturing creates retrofit demand as biologics pull flexible format adoption.
- Flexible:Adaptive polymer films and laminates for small-batch biologics and personalized therapies. ISO 11607 validation expertise for terminally sterilized medical device packaging remains scarce among contract manufacturers.
- Semi-Rigid:Intermediate stiffness formats balancing protection with material efficiency. Demand concentrates in tropical climate distribution requiring desiccant-integrated moisture control.
- Rigid:Established glass and polymer containers with proven barrier performance. Legacy line reconfiguration costs impede transition to flexible formats for many established manufacturers.
- Stretchable:Elastomeric containment for specialized drug-device combination products. Niche applications in wearable and implantable delivery systems.
Rigid formats anchor the volume base while flexible systems gain share at the steepest rate on biologics format transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers concentrate procurement decisions around cold-chain serialization mandates and ISO 15378 certification requirements. Buyer archetypes split between large-scale biologics producers seeking validated pouch formats and generic drug packagers managing aluminum cost volatility. Regional regulatory divergence creates distinct qualification timelines across manufacturing clusters.
Germany
EMA serialization mandates for biologics distribution drive temperature-assured packaging capacity expansion. German pharmaceutical distributors retrofit cold-chain infrastructure to meet Annex 1 sterile manufacturing revisions. The Rhine-Main cluster anchors borosilicate glass tubing demand for vial and syringe production serving European injectables supply chains.
United States
FDA Container Closure System guidance elevates extractables-leachables documentation requirements for primary packaging materials. Hospital procurement consolidation around pre-validated sterile kits reduces in-house sterilization burden in oncology centers. The Greater Boston biotech corridor generates specialized demand for ultra-cold containment in cell and gene therapy commercialization.
India
CDSCO tightened primary packaging standards force domestic injectables manufacturers to replace legacy polymer systems. ISO 15378 certification filters out suppliers lacking documented quality management systems across the domestic supply base. The Mumbai-Pune pharmaceutical belt concentrates upgrade investments in glass and certified polymer alternatives for export compliance.
China
NMPA alignment with international sterile manufacturing standards accelerates validation protocol adoption for terminally sterilized medical devices. Multi-layer film producers reformulate barrier chemistries to maintain moisture protection under evolving additive restrictions. The Yangtze River Delta packaging hub scales desiccant-integrated structures for tropical climate distribution requirements.
Switzerland
Swissmedic serialization enforcement for biologics transport pulls investment into track-and-trace compliant label substrates. Precision pharmaceutical manufacturing clusters demand adaptive primary packaging geometries for small-batch personalized therapies. The Basel region concentrates specialist suppliers serving global biologics producers with cryogenic pouch validation expertise.
Bio-Medical Packaging Market Competitive Environment
Player mix skews toward integrated material suppliers with multi-continent manufacturing footprints and specialized glass or polymer solution providers. Tier-one positions concentrate among firms sustaining compliance across FDA, EMA, and CDSCO regimes simultaneously. Three archetypes dominate: diversified packaging conglomerates with regulatory breadth, specialized primary containment engineers, and regional glass tubing monopolists. Competitive moves center on backward integration into raw material supply and automation retrofit services for serialization line integration.
Among diversified packaging conglomerates, Amcor plc exemplifies the multi-regional compliance archetype through its distributed manufacturing presence. Specialized glass and polymer solution providers include Gerresheimer AG and Schott AG, with the latter occupying a concentrated position in borosilicate glass tubing supply. These three anchors represent distinct competitive vectors: geographic diversification, material science depth, and critical input control respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| Schott AG |
| Berry Global |
| DuPont de Nemours |
| AptarGroup |
| WestRock Company |
| 3M |
| West Pharmaceutical Services |
| Others |
Value Chain & Pricing Dynamics
Flexible pouch formats displacing rigid glass containers for biologics transport simultaneously redraw supply geography toward multi-layer polymer film producers and compress pricing power among legacy borosilicate tubing manufacturers. German pharmaceutical distributors now source temperature-assured laminates from certified polymer specialists while Schott AG's glass tubing margins face pressure from shrinking vial demand in cell therapy logistics.
Pricing Analysis
Cost-plus contracts with aluminum London Metal Exchange indexation dominate oral solid dosage blister agreements, insulating generic packagers from raw material spikes while compressing margins during sustained price rallies. Three-tier pricing structure across ISO 15378-certified premium, validated standard, and uncertified economy levels separates CDSCO-compliant Indian suppliers from legacy domestic competitors. Pricing pressure stems from REACH-driven polymer reformulation costs in European multi-layer film production. Generic drug packagers exhibit highest price sensitivity, while biologics manufacturers prioritize validation documentation over unit cost.
Supply Chain Analysis
Strategic stockpiling of borosilicate glass tubing prevails among vial manufacturers confronting Schott AG's concentrated European supply base, while just-in-time polymer film delivery dominates flexible format procurement. Raw material flows center on Germany for glass tubing, China for multi-layer film substrates, and India for aluminum foil laminates. Single-source vulnerability concentrates in Schott AG's borosilicate tubing monopoly. Distribution runs through pharmaceutical distributors with validated cold-chain credentials serving hospital and biotechnology end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible polymer formats are accelerating substitution against rigid glass containment, forcing incumbents to defend validation expertise moats while new entrants exploit certification gaps in emerging biologics corridors.
For Market Incumbents: Fortify backward integration into polymer film substrate production to capture margin pools migrating from glass tubing. Anchor capacity expansion in the Mumbai-Pune pharmaceutical belt to intercept CDSCO-driven certification upgrades. ISO 15378 audit readiness separates defensible premium positioning from commodity polymer competition. For New Entrants and Emerging Players: Lead with cryogenic pouch validation services targeting German biologics distributors retrofitting for EMA serialization mandates. Exploit capability scarcity in ISO 11607 terminally sterilized medical device expertise among contract manufacturers. Position through automation retrofit partnerships for packaging line integration rather than material supply alone. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized primary containment engineers with multi-regulatory certification breadth. Five-to-ten year viability hinges on adaptive format capabilities displacing rigid legacy infrastructure. Target acquisition archetypes combine polymer science depth with validated cold-chain documentation. Watch EMA Annex 1 enforcement intensity as inflection signal for packaging line revalidation spending.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | CDSCO mandates in India filter uncertified suppliers from injectables supply chains. |
| Cryogenic Pouch Validation | German distributors adopt temperature-assured formats for EMA biologics serialization. |
| Backward Integration into Film Substrates | REACH restrictions force captive polymer chemistry control for barrier performance. |
| Automation Retrofit Services | Serialization mandates create aftermarket revenue in packaging line integration. |
| Dual Sourcing of Borosilicate Tubing | Schott AG concentration risk drives vial manufacturers toward supplier diversification. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary research phases, encompassing pharmaceutical packaging procurement managers, regulatory affairs directors at CDSCO and EMA, cold-chain logistics coordinators, and polymer film plant engineers. Secondary validation drew from FDA Container Closure System guidance documents, EMA Annex 1 revision drafts, ISO 15378 certification registries, and customs trade data for borosilicate glass tubing flows. Bottom-up demand modeling across therapy formats triangulated with top-down material consumption estimates.
Across the analysis window, forecasts incorporate segmentation by product type, material grade, end-user application, and regional regulatory cluster. CAGRs derive from validated adoption curves for flexible formats in biologics logistics, cross-referenced with pharmaceutical production capacity expansion in Germany, India, and the United States. Industry-specific inputs include CDSCO certification timelines, EMA serialization enforcement phases, and REACH additive restriction implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained biologics commercialization velocity or abrupt regulatory harmonization shifts would require recalibration. Forecasts embed assumptions regarding cold-chain infrastructure investment continuity and polymer barrier chemistry reformulation success. Revision becomes warranted when aluminum raw material volatility or borosilicate supply disruption crosses thresholds that restructure generic versus biologics packaging economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
North America Medical Devices Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market