
 Steer-by-Wire Road Wheel Actuator Modules Market | 2026-2036
Steer-by-Wire Road Wheel Actuator Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Steer-by-Wire Road Wheel Actuator Modules Market Insights
German tier-1 actuator production is broadening as automakers commit to redundant steering architectures for Level 3+ autonomy. ZF Friedrichshafen leverages its integrated chassis systems portfolio to dominate electromechanical actuator development for premium platforms. Robert Bosch sustains R&D intensity in brushless DC motor control algorithms that govern road wheel precision. Continental competes through its safety-critical electronics heritage and fail-operational design capabilities.
Steer-by-Wire Road Wheel Actuator Modules replace mechanical steering columns with electronic signal transmission to actuator motors at each wheel hub, typically employing dual-channel brushless DC motors with torque ratings exceeding 15 Nm and position feedback resolution below 0.1 degrees to ensure functional safety under ISO 26262 ASIL-D requirements. Electric actuators lead current revenue contribution due to their compatibility with battery-electric vehicle platforms and elimination of hydraulic fluid maintenance. Autonomous vehicle applications represent the fastest-expanding segment as robotaxi fleets mandate fully redundant steering without mechanical backup. Brushless DC motor technology anchors the largest margin pool given its efficiency advantages and established supplier ecosystems.
NHTSA in the United States and ECE R79 in Europe govern steering system performance and failure-mode behavior, compelling suppliers to validate actuator modules through accelerated lifecycle testing exceeding two million steering cycles. Japan's METI promotes steer-by-wire adoption through its Society 5.0 mobility roadmap, while China's MIIT integrates redundant steering into intelligent connected vehicle standards. Stakeholders must monitor regulatory divergence between fail-operational requirements in Europe and the United States versus China's emphasis on data sovereignty in vehicle control systems.
Market Dynamics
The transition from mechanical steering columns to fully electronic architectures is compressing development cycles and forcing tier-1 suppliers to restructure R&D allocation toward redundant actuator systems.
Growth Catalysts
- Level 3+ Autonomy Mandates:Robotaxi fleet operators require fail-operational steering without mechanical backup, creating dedicated procurement channels for dual-channel actuator modules.
- FMVSS Evolution:NHTSA's updated steering control standards are accelerating validation protocols for electronic steering systems in Detroit Three platforms.
- Brushless DC Efficiency Gains:Permanent magnet motor architectures are displacing hydraulic alternatives in Stuttgart's premium vehicle engineering corridor.
Market Restraints
- Rare Earth Magnet Dependency:Neodymium price volatility constrains cost predictability for high-torque actuator motor production.
- Validation Cycle Duration:ISO 26262 ASIL-D certification demands exceed 24 months, freezing supplier qualification pipelines.
- Hydraulic Steering Residual Demand:Heavy commercial vehicle segments retain mechanical backup requirements that delay full electrification.
Strategic Opportunities
- Software-Defined Steering:Over-the-air calibration capabilities enable recurring revenue models through feature subscription tiers.
- India Automotive Corridor:Tamil Nadu and Maharashtra manufacturing hubs lack indigenous steer-by-wire capacity, opening joint venture entry points.
- EU Battery Regulation Alignment:Circular economy mandates for actuator recyclability favor modular motor designs with standardized disassembly protocols.
Industry Challenges
- Functional Safety Engineering Scarcity:ISO 26262 certified systems architects command premium compensation that strains mid-tier supplier payroll structures.
- Legacy Platform Integration:Retrofitting steer-by-wire into existing vehicle electrical architectures requires custom gateway controllers that fragment development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steer-by-Wire Road Wheel Actuator Modules Market |
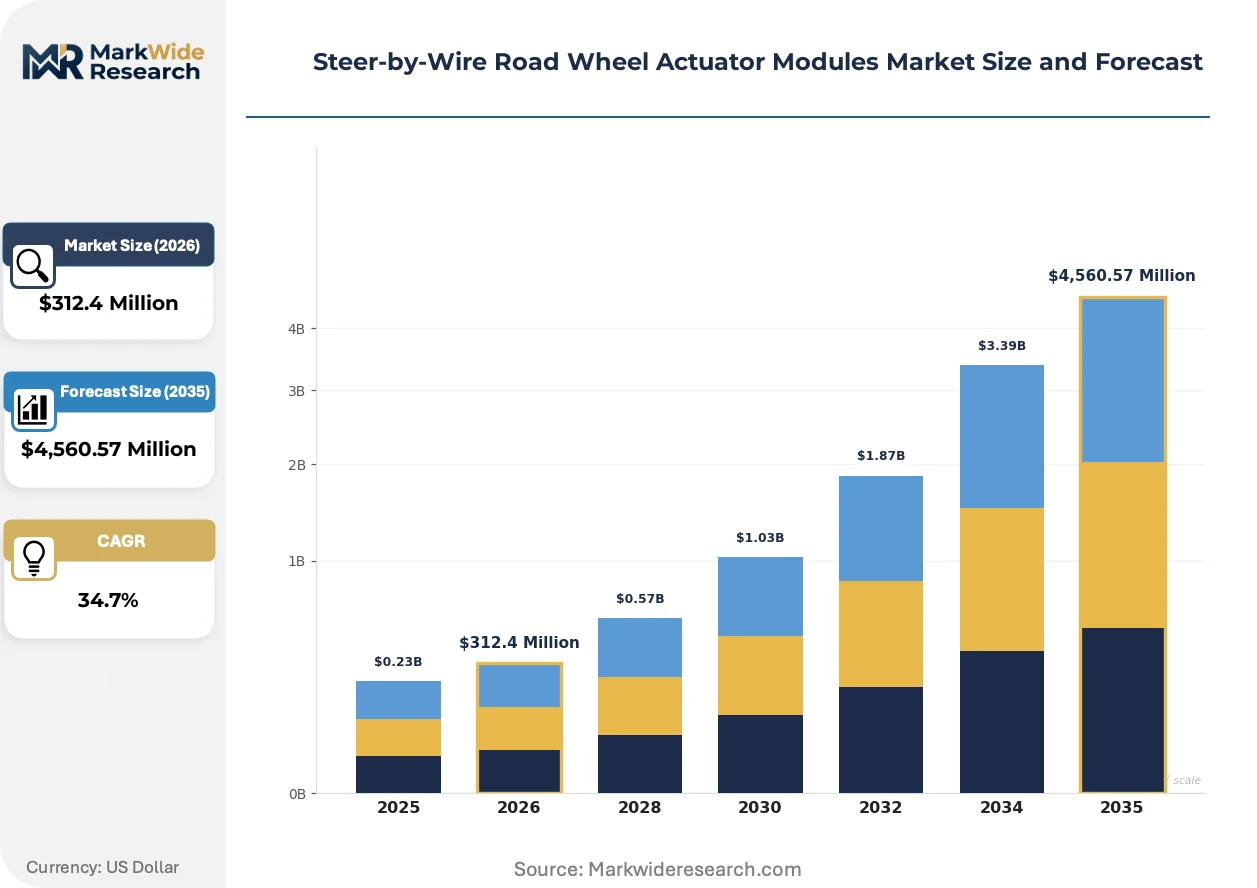
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $4,560.57 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Electro-Hydraulic Actuators, Electro-Mechanical Actuators Technology: Brushless DC Motors, Stepper Motors, Servo Motors, Piezoelectric Actuators Application: Passenger Vehicles, Commercial Trucks, Off-Road Vehicles, Autonomous Vehicles, Specialty Vehicles End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | ZF Friedrichshafen, Robert Bosch, Continental, Nexteer Automotive, JTEKT, DENSO Corporation, Aptiv, Thyssenkrupp, Kongsberg Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steer-by-Wire Road Wheel Actuator Modules Market Trends and Innovations
Electromechanical redundancy architectures are displacing single-channel designs as the baseline specification for autonomous-capable platforms, compressing supplier differentiation timelines.
Dual-motor torque vectoring actuators are overtaking conventional single-motor designs in premium battery-electric platforms. Mercedes-Benz and BMW Group procurement specifications now mandate independent wheel-level steering authority for advanced driver assistance suites. This shift is compressing margins for suppliers lacking integrated chassis control software competencies.
ECE R79 revision cycles are tightening steering system failure-mode documentation requirements for European type approval. Suppliers must now submit real-time diagnostic data streams as part of homologation packages. German KBA enforcement has accelerated adoption of deterministic Ethernet backbones for actuator command transmission.
Fleet operators are consolidating procurement authority through direct tier-1 contracts rather than OEM-mediated sourcing. Waymo and Cruise are establishing dedicated supplier development programs for robotaxi-specific actuator durability standards. This disintermediation is most visible in California and Arizona testing corridors where fleet scale justifies custom module specifications.
Steer-by-Wire Road Wheel Actuator Modules Market Segmentation
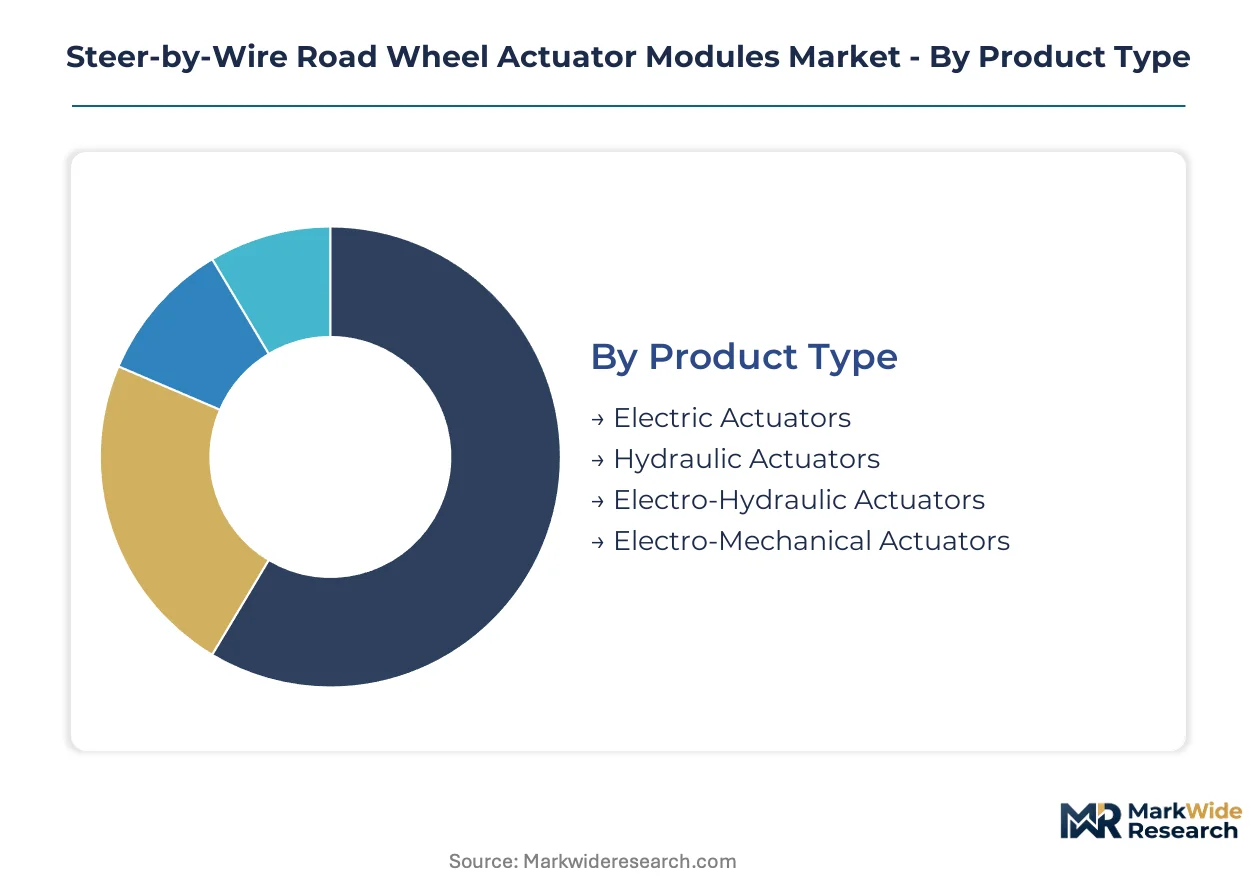
Segmentation reveals how actuator module specifications diverge across electrification platforms and autonomy tiers. Procurement patterns split between integrated chassis systems and standalone retrofit architectures, with each configuration demanding distinct torque densities and safety certification levels.
Product Type:
Integration depth varies sharply: electric and electro-mechanical variants embed directly into wheel hub assemblies, while hydraulic and electro-hydraulic systems retain standalone rack-mounted configurations with mechanical backup linkages.
- Electric Actuators:Permanent magnet synchronous motors deliver torque outputs exceeding 15 Nm with position feedback resolution below 0.1 degrees. Battery-electric vehicle platforms in Stuttgart's engineering corridor specify these modules for their elimination of hydraulic fluid maintenance and compatibility with 48V electrical architectures.
- Electro-Mechanical Actuators:Dual-channel brushless DC motor arrays with redundant position sensors satisfy ISO 26262 ASIL-D requirements. Robotaxi fleet operators in California and Arizona procurement channels mandate these configurations for fail-operational steering without mechanical backup columns.
- Hydraulic Actuators:Piston-driven fluid power systems persist in heavy commercial vehicle segments requiring mechanical redundancy.
- Electro-Hydraulic Actuators:Hybrid architectures bridge legacy hydraulic infrastructure with electronic command interfaces for transitional platform generations.
Electric actuators lead volumes today; electro-mechanical variants are gaining share fastest.
Technology:
Cost tiers separate established motor topologies from emerging precision actuation methods, with premium platforms absorbing advanced technologies while volume production favors mature supply chains.
- Brushless DC Motors:Neodymium permanent magnet rotors achieve efficiency ratings above 90% with deterministic torque response. German tier-1 suppliers dominate this segment through integrated chassis control software competencies and established magnet sourcing relationships.
- Servo Motors:Closed-loop position control with encoder feedback enables sub-degree steering precision for advanced driver assistance suites. Premium OEM procurement specifications from Mercedes-Benz and BMW Group require these modules for independent wheel-level steering authority.
- Stepper Motors:Open-loop incremental positioning suits cost-constrained auxiliary steering applications with lower torque demands.
- Piezoelectric Actuators:Ceramic-stack linear motion delivers nanometer-scale precision for prototype autonomous research platforms.
Brushless DC motors anchor current revenue concentration; servo motor configurations are expanding most quickly in premium battery-electric segments.
Application:
Customer type determines redundancy requirements: passenger and autonomous vehicle mandates specify dual-channel architectures, while commercial and off-road segments retain mechanical backup tolerance.
- Autonomous Vehicles:Fail-operational actuator modules with dual-motor torque vectoring architectures eliminate steering column mechanical linkages entirely. Waymo and Cruise direct procurement programs in California and Arizona testing corridors establish custom durability standards exceeding two million steering cycles.
- Passenger Vehicles:Level 2+ driver assistance compatibility drives electromechanical redundancy adoption across Stuttgart and Munich premium platforms. NHTSA FMVSS evolution accelerates validation protocols for electronic steering systems in Detroit Three vehicle programs.
- Commercial Trucks:Hydraulic steering residual demand delays full electrification in heavy-duty segments requiring mechanical backup compliance.
- Off-Road Vehicles:Contaminated operating environments favor sealed hydraulic architectures over electronic precision components.
- Specialty Vehicles:Low-volume custom chassis applications accommodate non-standard actuator mounting configurations.
Passenger vehicles dominate procurement volumes today; autonomous vehicle applications are climbing the fastest.
End User:
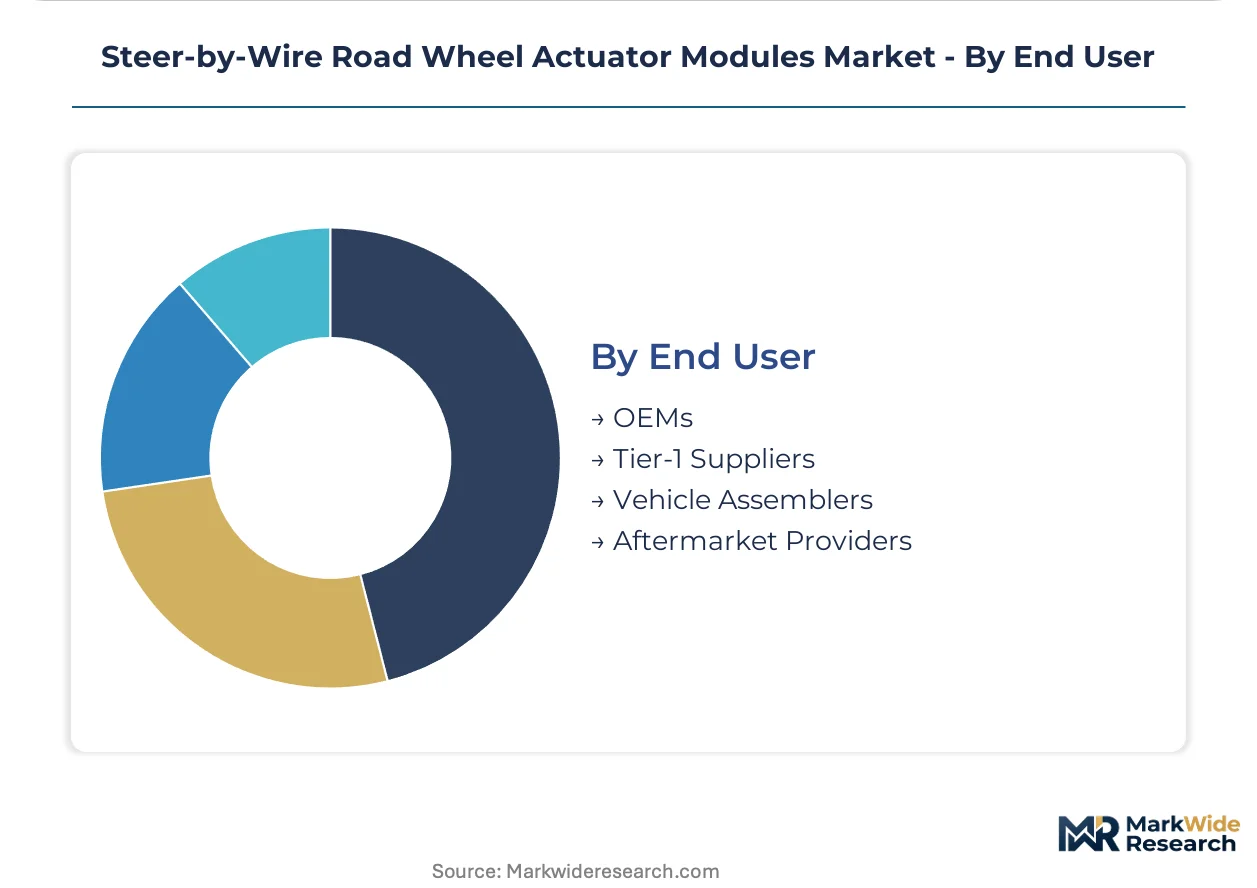
Supply concentration patterns split between captive in-house production and outsourced tier-1 procurement, with fleet operators increasingly consolidating authority through direct supplier contracts.
- OEMs:Vertically integrated chassis engineering divisions at premium manufacturers specify proprietary actuator interfaces and calibration protocols. BMW Group and Mercedes-Benz maintain direct development relationships with German actuator specialists.
- Tier-1 Suppliers:Independent module houses supply standardized actuator platforms to multiple OEM programs. ZF Friedrichshafen and Robert Bosch leverage integrated portfolio breadth to dominate electromechanical development.
- Vehicle Assemblers:Contract manufacturing operations receive pre-validated actuator modules for final chassis integration.
- Aftermarket Providers:Replacement and retrofit channels serve legacy platform steering system upgrades.
Tier-1 suppliers capture the largest volume share today; OEM direct procurement is expanding most quickly for autonomous platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates engineering-grade actuator development while the United States accelerates fleet-scale procurement for autonomous platforms. Regulatory divergence between fail-operational mandates and data sovereignty requirements shapes divergent certification pathways across major automotive corridors.
United States
Robotaxi fleet operators in California and Arizona testing corridors drive concentrated demand for dual-channel redundant architectures. NHTSA's evolving FMVSS steering control standards compress validation timelines for Detroit Three platform integration. Michigan's automotive engineering cluster around Detroit anchors tier-1 supplier development programs for electromechanical actuator systems.
Germany
Premium OEM procurement specifications from Stuttgart and Munich mandate independent wheel-level steering authority for Level 3+ autonomy suites. ECE R79 revision cycles tighten failure-mode documentation requirements enforced by KBA for European type approval. Baden-Württemberg's engineering corridor hosts integrated chassis systems development for fail-operational actuator modules.
Japan
Domestic automakers advance steer-by-wire adoption through Society 5.0 mobility roadmap initiatives promoted by METI. Precision motor control heritage from industrial automation sectors transfers into automotive actuator development. Nagoya's Chubu manufacturing region concentrates electromechanical component production for export-oriented platform supply.
China
Intelligent connected vehicle standards issued by MIIT integrate redundant steering architectures into national certification frameworks. Domestic battery-electric vehicle platforms absorb high-torque actuator modules for software-defined chassis control. Yangtze River Delta manufacturing hubs around Shanghai expand electromechanical component capacity for regional OEM supply chains.
India
Tamil Nadu and Maharashtra automotive manufacturing corridors lack indigenous steer-by-wire capacity, creating joint venture entry opportunities for tier-1 suppliers. Central government PLI scheme incentives for advanced automotive components accelerate technology transfer negotiations. Pune's engineering cluster hosts emerging chassis systems development for domestic electric vehicle programs.
Steer-by-Wire Road Wheel Actuator Modules Market Competitive Landscape
German producers anchor the premium tier through integrated chassis systems portfolios; Japanese specialists hold precision motor control positions. The vendor base splits between consolidated tier-1 module houses and captive OEM engineering divisions. Three archetypes dominate: full-system integrators, motor control specialists, and safety-critical electronics houses. Competitive moves concentrate on strategic partnerships for fail-operational software stacks and geographic expansion into underserved Asian manufacturing corridors.
Among German-based integrated suppliers, ZF Friedrichshafen and Continental occupy positions exemplifying full-system chassis control capability. Robert Bosch represents the motor control specialist archetype through established brushless DC algorithm development. These three entities anchor the premium-tier competitive vector where redundant actuator architectures and ISO 26262 ASIL-D certification credentials determine procurement access.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Robert Bosch |
| Continental |
| Nexteer Automotive |
| JTEKT |
| DENSO Corporation |
| Aptiv |
| Thyssenkrupp |
| Kongsberg Automotive |
| Others |
Pricing and Supply Chain Analysis
Neodymium oxide price indices cascade through brushless DC motor supply chains, compressing margins for high-torque actuator producers while amplifying pricing power for German tier-1 suppliers with captive magnet sourcing. Cost pass-through mechanisms stratify procurement tiers, with robotaxi fleet operators absorbing premium pricing for ASIL-D certified modules and commercial vehicle segments resisting electrification due to residual hydraulic alternatives.
Pricing Analysis
Direct-to-OEM contract structures eliminate distributor markups for volume fleet procurement, while aftermarket channels retain 25-35 point premiums for replacement modules. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 certification grade and torque density specifications. Pricing pressure stems from rare earth magnet cost volatility, with neodymium price swings forcing quarterly contract renegotiations. Commercial truck operators exhibit highest price sensitivity due to mechanical backup requirements, whereas autonomous vehicle developers prioritize fail-operational redundancy over unit cost.
Supply Chain Analysis
ISO 26262 ASIL-D certification gates tier-1 supplier qualification, freezing mid-tier competitors out of premium OEM procurement channels. Production concentrates in Germany, China, and Japan, with Baden-Württemberg hosting integrated chassis systems development and Yangtze River Delta expanding electromechanical component capacity. Supply chains draw from neodymium permanent magnet processors, silicon steel laminators, and deterministic Ethernet chipset fabricators. Single-source vulnerability concentrates in rare earth magnet refining, where Chinese processing dominance creates tariff exposure for Western actuator assemblers. Distribution runs through captive OEM engineering divisions and independent tier-1 module houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in steer-by-wire actuators hinges on software-defined steering calibration revenue and modular motor designs that slash rare earth content per newton-meter of output. Cost-down trajectories in brushless DC control algorithms are shifting value capture toward integrated chassis software stacks.
For Market Incumbents: Anticipate disintermediation pressure from robotaxi fleet operators consolidating direct tier-1 procurement authority. Defensive positioning requires deepening backward integration into permanent magnet sourcing and expanding fail-operational software competencies. Capacity addition in Tamil Nadu and Maharashtra manufacturing corridors captures emerging Indian electric vehicle demand before indigenous competitors mature. Certification investment in China's MIIT intelligent connected vehicle standards secures access to Yangtze River Delta battery-electric platform supply chains. For New Entrants and Emerging Players: India's PLI scheme for advanced automotive components opens a window for joint venture entry into steer-by-wire module assembly. White-space targets include aftermarket retrofit channels for legacy platform steering upgrades and cost-optimized electro-mechanical actuators for Level 2+ passenger vehicle programs. The most penetrable segment sits in Tamil Nadu contract manufacturing operations lacking indigenous actuator capacity. A direct tier-1 supply relationship with emerging domestic OEMs bypasses entrenched German supplier relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with motor control specialists possessing ISO 26262 certified firmware architectures and established magnet sourcing relationships. Long-term viability favors suppliers integrating software-defined steering capabilities that enable recurring calibration revenue streams. Acquisition targets should display integrated chassis control software competencies and fail-operational design heritage. The signal to watch is NHTSA FMVSS steering control standard finalization, which will accelerate validation protocol convergence and consolidate procurement authority around pre-qualified tier-1 suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Fail-Operational Software Stack Development | Captures robotaxi procurement mandates from Waymo and Cruise in California testing corridors. |
| Rare Earth Magnet Supply Agreement | Insulates margin stability against neodymium price volatility through Chinese processor relationships. |
| Indian Manufacturing Joint Venture | Establishes local assembly presence ahead of PLI scheme incentive maturation in Tamil Nadu. |
| Deterministic Ethernet Backbone Integration | Satisfies ECE R79 revision requirements enforced by German KBA for European type approval. |
| Modular Motor Design Standardization | Aligns with EU Battery Regulation circular economy mandates for actuator recyclability protocols. |
Research Methodology
Multiple input streams — primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, SEC filings, and NHTSA FMVSS docket records; and trade flow analysis of rare earth magnet customs data — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations spanned Stuttgart's premium engineering corridor, Detroit Three platform development centers, and California robotaxi testing operations.
Data-stream reconciliation across product type, technology topology, application tier, and end-user concentration dimensions anchored the analytical framework. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, and regional production cluster variables throughout the forecast period. CAGRs derived from unit shipment trajectories and average selling price evolution, with cross-validation against OEM platform launch schedules and autonomy tier adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NHTSA regulatory delay scenarios or neodymium supply disruption events. Forecasts reflect assumptions regarding Level 3+ autonomy commercialization timelines and fleet operator procurement consolidation trends. A model refresh is warranted upon material change in FMVSS steering control standard finalization or MIIT intelligent connected vehicle certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Portable Wheel Jack Market
Vehicle Components
Rear Axle Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Wheel Seals Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Headlight Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Europe Trailer Axle Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Locomotive Pantographs Market