
 Denmark Wind Energy Market | 2026-2036
Denmark Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Wind Energy Market Outlook
Multi-source contracting for turbine supply chains is pivoting toward captive manufacturing partnerships across Danish offshore zones. Ørsted A/S anchors its project pipeline through direct blade supply agreements with Siemens Gamesa Renewable Energy SA. Vestas Wind Systems A/S leverages its domestic nacelle assembly footprint to compete on delivery speed for North Sea arrays. Copenhagen Infrastructure Partners sustains capital deployment into floating demonstration sites near Thyborøn.
Denmark wind energy encompasses the conversion of kinetic atmospheric flow into grid-ready electricity through horizontal-axis and vertical-axis turbine systems, with offshore units typically rated above 8 MW and hub heights exceeding 100 meters to capture stable marine wind regimes. The technology serves baseload displacement and industrial decarbonization for Nordic power pools. Offshore turbines command the dominant share of capital allocation due to higher capacity factors and dedicated seabed concessions, while floating turbines represent the fastest-expanding installation category as water depths beyond 60 meters open for development. Energy storage applications are gaining structural importance as grid stabilization mandates tighten across Energinet's transmission network.
The Danish Energy Agency shapes project economics through tender design and seabed allocation rounds, while the Danish Maritime Authority enforces installation standards for jack-up vessel operations. EU Green Deal alignment pressures accelerate domestic content requirements for tower and foundation steel. Stakeholders must monitor floating foundation certification timelines and port infrastructure readiness at Esbjerg and Hanstholm before committing capital to next-phase lease areas.
Market Dynamics
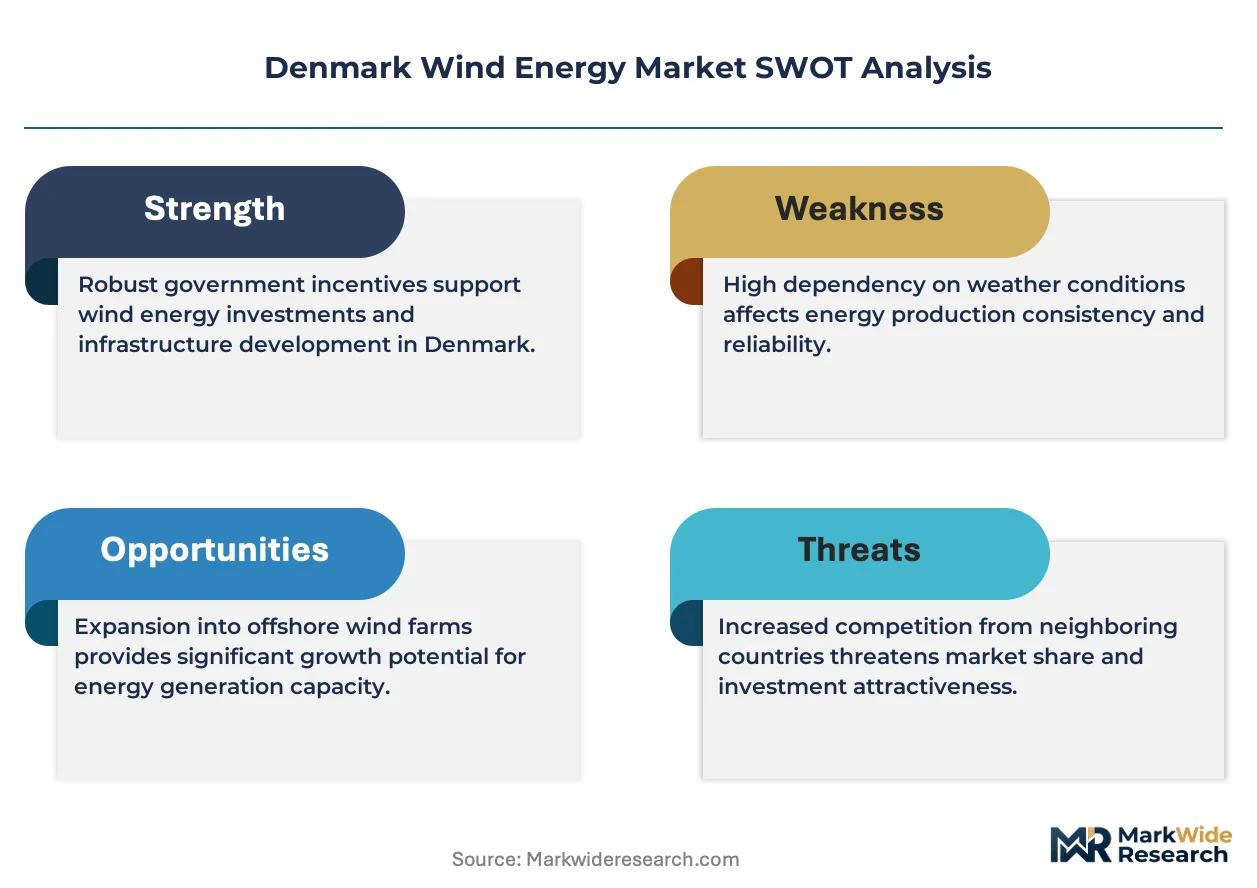
Offshore wind developers face mounting pressure from the Danish Energy Agency's stricter seabed leasing terms, which now mandate faster deployment timelines and higher domestic content thresholds. These regulatory shifts are compressing project development cycles while forcing supply chain localization decisions.
Growth Catalysts
- Esbjerg Port Expansion:Denmark's primary offshore wind logistics hub is deepening quayside capacity to accommodate next-generation jack-up vessels and floating foundation assembly.
- EU Green Deal Alignment:The European Union's domestic content requirements for steel components in renewable energy infrastructure are accelerating tower and foundation manufacturing investments across Jutland.
- Floating Foundation Maturation:Water depths beyond sixty meters in the Kattegat and North Sea are unlocking lease areas previously inaccessible to fixed-bottom turbine technology.
Market Restraints
- Specialized Vessel Bottleneck:The global fleet of turbine installation jack-up vessels remains concentrated among a handful of European marine contractors, creating slot scarcity for Danish projects.
- Grid Connection Delays:Energinet's onshore substation upgrade timelines lag behind offshore generation capacity additions, stranding power before transmission reinforcement completion.
- Foundation Steel Price Volatility:Anti-dumping duties on Chinese steel plate have destabilized monopile cost structures for North Sea arrays.
Strategic Opportunities
- Thyborøn Floating Demonstration Zone:Copenhagen Infrastructure Partners and other capital deployers are securing early-mover positions in deep-water turbine testing before commercial scale-up.
- Power-to-X Industrial Offtake:Ammonia and e-fuel producers in the Aalborg corridor are contracting dedicated offshore wind capacity to meet Scope 3 decarbonization commitments.
- Hanstholm Port Diversification:The northern Jutland facility is positioning as an alternative marshalling yard to reduce Esbjerg congestion for Kattegat-facing projects.
Industry Challenges
- Marine Electrical Technician Shortage:High-voltage cable installation and turbine commissioning require specialized skills that Danish technical institutes are not producing at replacement rates.
- Floating Foundation Certification Lag:DNV and other classification societies have not finalized unified standards for semi-submersible and spar-type platforms, delaying project financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Wind Energy Market |
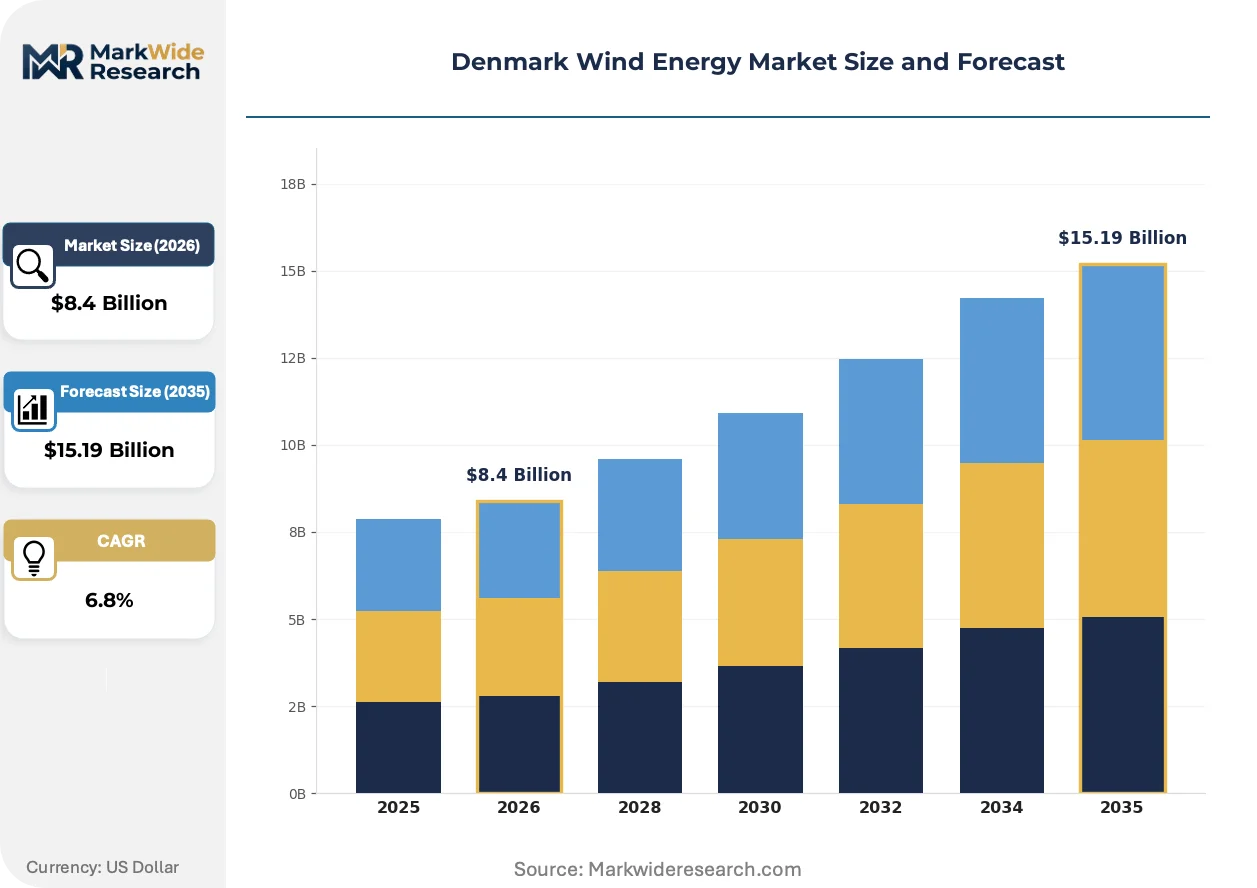
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore Turbines, Offshore Turbines, Vertical-Axis Turbines, Floating Turbines Application: Power Generation, Energy Storage, Grid Stabilization, Offshore Operations End User: Utilities, Independent Power Producers, Government Bodies, Commercial Users Installation: Ground-Mounted, Fixed Offshore, Floating Offshore, Hybrid Systems |
| Companies Covered | Siemens Gamesa Renewable Energy SA, Copenhagen Infrastructure Partners, Ørsted A/S, TotalEnergies Renewables, RWE Renewables GmbH, Vestas Wind Systems A/S, MHI Vestas Offshore Wind A/S, European Energy A/S, Vattenfall AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Wind Energy Market Strategic Shifts
Turbine scaling and digitalization are converging to reshape Danish offshore wind economics. The sector is pivoting from incremental efficiency gains to structural redesign of installation and operations models.
Direct-drive permanent magnet generators are eliminating gearbox failure modes in offshore turbines. Ørsted and other developers are specifying these systems for North Sea projects rated above twelve megawatts. The technology is integrating predictive maintenance algorithms that compress unplanned outage duration and shift O&M from calendar-based to condition-based scheduling.
The EU Green Deal's domestic content mandates are tightening supply chain traceability requirements for steel and rare earth components. Danish project developers must now document origin certificates through tier-three suppliers to qualify for seabed leases. Fixed-bottom installations in shallower North Sea zones face the steepest compliance cost escalation as foundation fabricators requalify Asian material sources.
Industrial offtakers are moving from spot market participation to twenty-year power purchase agreements with offshore wind farms. Data center operators in Fredericia and pharmaceutical manufacturers in Kalundborg are bypassing traditional utility intermediaries to contract directly with project sponsors. This bilateral contracting is most visible in the Kattegat corridor, where grid constraints make merchant exposure unpalatable to risk-averse corporate buyers.
Denmark Wind Energy Market Segmentation
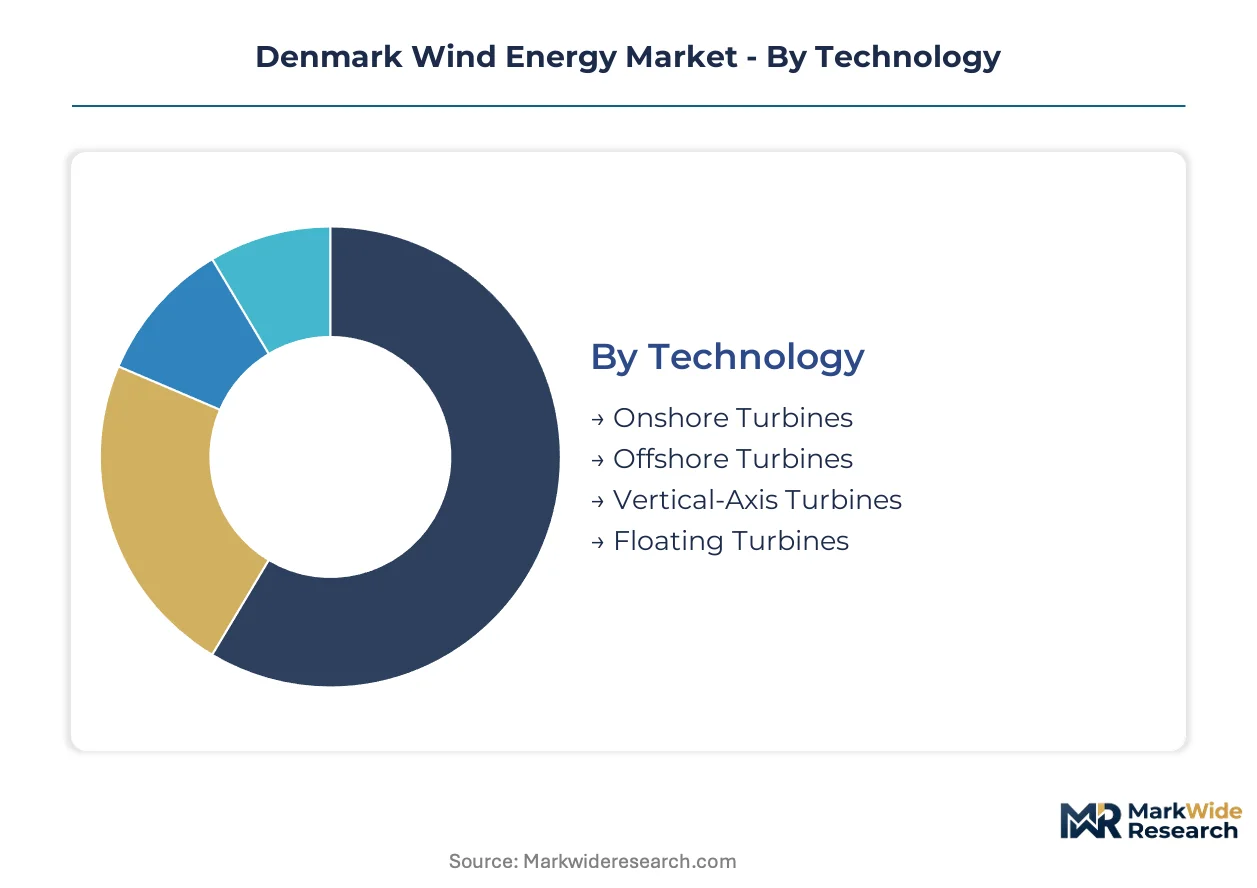
Segmentation reveals how capital allocation splits across turbine technologies, installation methods, and offtake structures in the Danish market. Each dimension carries distinct regulatory, supply chain, and financing implications for developers and investors.
Technology:
Standalone turbine systems dominate Danish procurement, while embedded hybrid configurations occupy niche positions in island grids and industrial microgrids.
- Onshore Turbines:Horizontal-axis units rated 3-6 MW with hub heights of 80-120 meters capture terrestrial wind regimes across Jutland and Zealand. Danish utilities deploy these for distributed generation and grid balancing services in regions with lower seabed lease access.
- Offshore Turbines:Fixed-bottom horizontal-axis systems rated 8-15 MW with rotor diameters exceeding 160 meters anchor Danish generation capacity. Ørsted and Copenhagen Infrastructure Partners concentrate procurement in the North Sea corridor between Esbjerg and the Kattegat due to superior capacity factors and dedicated seabed concessions from the Danish Energy Agency.
- Vertical-Axis Turbines:Darrieus and Savonius configurations serve specialized urban and small-scale applications with lower tip-speed ratios.
- Floating Turbines:Semi-submersible and spar-type platforms unlock water depths beyond 60 meters previously inaccessible to fixed foundations.
Volume placements concentrate in Offshore Turbines; the faster expansion belongs to Floating Turbines.
Application:
Cost tier differentiation separates merchant-exposed generation from contracted grid services and industrial offtake arrangements.
- Power Generation:Bulk electricity production for Nordic power pool integration and cross-border export to Germany and Sweden. Danish projects under the Energinet transmission mandate prioritize this application for baseload displacement and industrial decarbonization commitments.
- Energy Storage:Co-located battery systems and power-to-X facilities convert intermittent generation into dispatchable molecules. Developers near Aalborg and Fredericia are pairing offshore capacity with ammonia and e-fuel production to capture Scope 3 offtake contracts from shipping and aviation customers.
- Grid Stabilization:Frequency response and voltage regulation services through synthetic inertia provision.
- Offshore Operations:Direct power supply to oil and gas platform electrification and marine charging infrastructure.
Revenue concentration sits with Power Generation; the steepest expansion trajectory is in Energy Storage.
End User:
Customer type determines contracting structure, with integrated utilities favoring asset ownership and independent generators pursuing merchant or bilateral offtake models.
- Utilities:Vertically integrated Nordic power companies with regulated transmission assets and long-term seabed leases. Ørsted anchors this segment through direct ownership of North Sea arrays and preferential access to Energinet grid connection queues.
- Independent Power Producers:Project-specific vehicles and infrastructure funds deploying capital on a non-recourse basis. Copenhagen Infrastructure Partners exemplifies this model through floating demonstration sites near Thyborøn and merchant exposure strategies in the Kattegat.
- Government Bodies:Danish Energy Agency and municipal energy companies procuring capacity for public service obligations.
- Commercial Users:Data center operators, pharmaceutical manufacturers, and e-fuel producers contracting dedicated capacity.
Capacity ownership concentrates in Utilities; the fastest share gain is in Commercial Users.
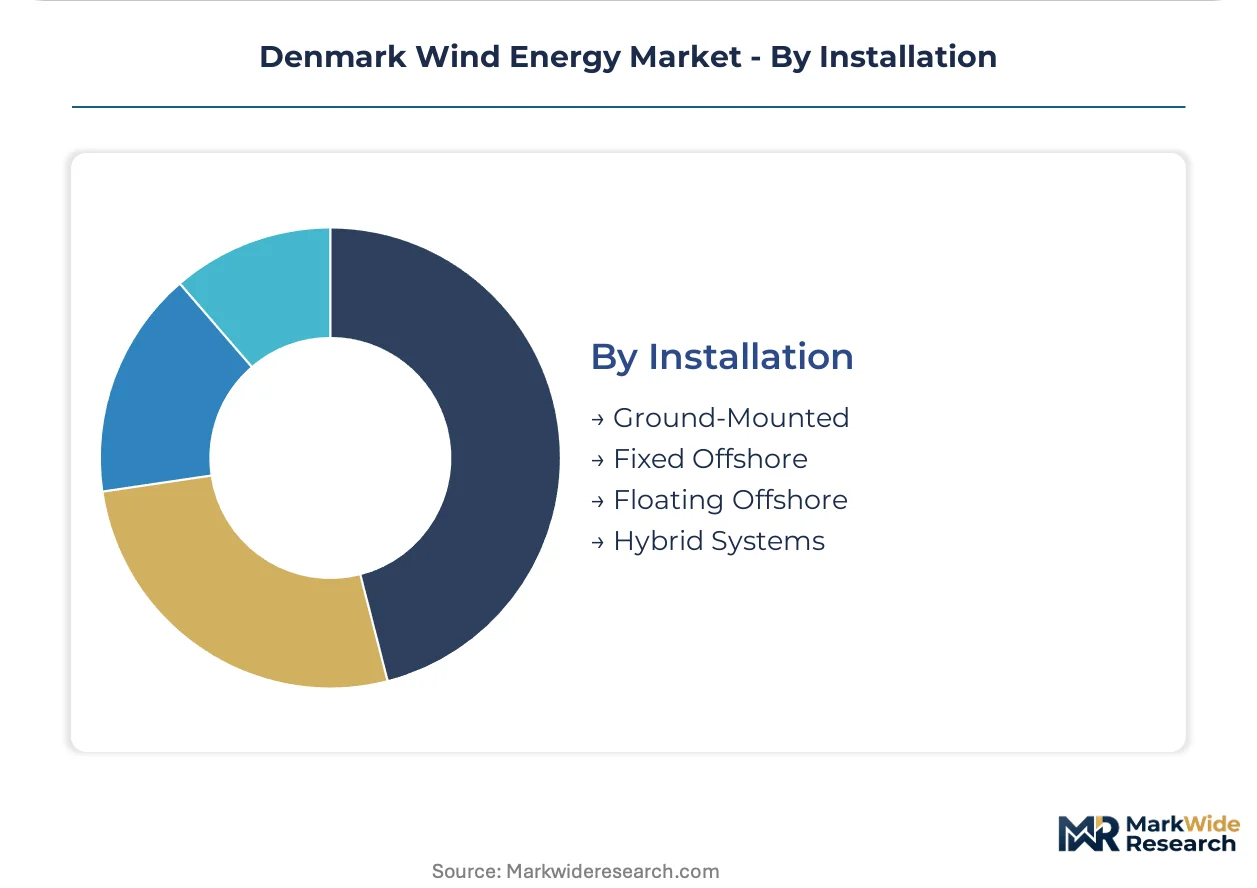
Installation:
Geography and water depth dictate foundation selection, with shallower zones favoring fixed structures and deeper waters requiring floating solutions.
- Ground-Mounted:Onshore concrete and steel tower foundations with direct grid connection through overhead lines. Jutland's western coast hosts these installations where seabed leasing constraints or grid proximity favor terrestrial deployment.
- Fixed Offshore:Monopile and jacket foundations in water depths below 60 meters. The Danish Energy Agency's seabed allocation rounds concentrate these installations in the North Sea corridor, with Esbjerg Port serving as the primary marshalling and assembly hub.
- Floating Offshore:Tension-leg platforms and semi-submersible hulls anchored with catenary or taut mooring systems.
- Hybrid Systems:Combined wind-solar-storage configurations for island grids and industrial microgrids.
Capital deployment concentrates in Fixed Offshore; the climbing trajectory belongs to Floating Offshore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea seabed anchors Denmark's wind energy geography, with Esbjerg serving as the primary logistics corridor for turbine assembly and offshore installation. Jutland's western coastline hosts the densest concentration of operational capacity, while the Kattegat corridor opens deeper waters for floating foundation deployment.
North Jutland
Offshore wind demand concentrates around Hanstholm Port, where developers are diversifying marshalling capacity to reduce Esbjerg congestion for Kattegat-facing projects. The Danish Maritime Authority enforces installation standards for jack-up vessel operations across these northern lease areas. Thyborøn hosts floating demonstration sites where Copenhagen Infrastructure Partners tests semi-submersible platforms before commercial scale-up.
South Jutland
Esbjerg anchors the heaviest capital deployment, with quayside deepening projects accommodating next-generation turbine components and floating foundation assembly. The Danish Energy Agency's seabed allocation rounds concentrate fixed-bottom installations in this corridor due to superior capacity factors. RWE Renewables GmbH and TotalEnergies Renewables hold active lease positions between Esbjerg and the German border.
Zealand
Grid stabilization mandates from Energinet drive onshore turbine deployment across the island's western coast, with utilities targeting distributed generation where seabed access is constrained. The Danish Energy Agency's stricter domestic content thresholds apply equally to Zealand-connected offshore arrays. Kalundborg hosts pharmaceutical manufacturers contracting dedicated offshore capacity for Scope 3 decarbonization.
Funen
The Kattegat corridor facing Funen unlocks water depths beyond sixty meters for floating turbine technology previously inaccessible to fixed foundations. European Energy A/S and Vattenfall AB are securing early positions in these deep-water lease areas ahead of unified certification standards. Middelfart serves as a secondary logistics node for cable landing and onshore substation integration.
Denmark Wind Energy Market Competitive Environment
Global majors compete with regional champions across turbine supply and project development, creating a tiered structure where scale-driven manufacturers face capital-light developers. The market consolidates around three strategic archetypes: integrated utilities with preferential grid access, independent power producers deploying non-recourse financing, and equipment suppliers capturing value through captive manufacturing partnerships. Dominant competitive moves include backward integration into blade and nacelle production and strategic port infrastructure control.
Among Danish-anchored developers, Ørsted A/S and Vestas Wind Systems A/S exemplify the integrated utility and domestic manufacturing archetypes respectively. Siemens Gamesa Renewable Energy SA represents the global turbine supplier tier competing on direct-drive permanent magnet technology. Copenhagen Infrastructure Partners occupies the independent capital deployer position, with floating demonstration exposure near Thyborøn distinguishing its risk profile from utility-backed competitors.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy SA |
| Copenhagen Infrastructure Partners |
| Ørsted A/S |
| TotalEnergies Renewables |
| RWE Renewables GmbH |
| Vestas Wind Systems A/S |
| MHI Vestas Offshore Wind A/S |
| European Energy A/S |
| Vattenfall AB |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between DNV-classified floating foundations and uncertified prototypes splits Danish offshore wind procurement into premium long-term offtake tiers and speculative demonstration slots, with that divergence embedding into both Esbjerg Port logistics premiums and domestic content compliance costs across Jutland manufacturing clusters.
Pricing Analysis
Full-service installation warranties bundled with twenty-year O&M contracts command premiums over unbundled equipment-only transactions in Danish seabed auctions. Price differentiation rests on DNV certification status and domestic steel origin documentation under EU Green Deal mandates. Cost compression in fixed-bottom monopile supply chains intensifies as Asian plate fabricators face anti-dumping duty exposure. Merchant-exposed independent power producers exhibit highest price sensitivity; integrated utilities with preferential Energinet queue access absorb premium tiering without volume reduction.
Supply Chain Analysis
Direct-to-developer channels handle hyperscale turbine procurement for Ørsted and Copenhagen Infrastructure Partners, bypassing distributor markups for North Sea arrays. Manufacturing gravity centers on Denmark, Germany, and Spain for nacelle assembly and blade fabrication. Rare earth magnet supply draws from Chinese processing dominance and Vietnamese separation facilities. Single-source vulnerability in jack-up vessel chartering concentrates installation slot control among European marine contractors. Distribution runs through Esbjerg and Hanstholm port infrastructure for Kattegat-facing projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Danish offshore wind is consolidating around developers with captive port access and certified floating technology pipelines, as the Danish Energy Agency's accelerated deployment timelines and domestic content thresholds force capital-light entrants into joint venture structures or exit.
For Market Incumbents: Extend backward integration into blade manufacturing through Siemens Gamesa partnerships to secure supply priority during jack-up vessel slot scarcity. Deepen Esbjerg Port infrastructure control to lock out competing developers from marshalling capacity. The threat of Hanstholm-based challengers gaining Kattegat logistics share makes quayside investment the critical defensive lever. For New Entrants and Emerging Players: The premium-to-economy price gap in floating foundation certification opens white-space positioning in Thyborøn demonstration zones before DNV standards unify. Target pharmaceutical offtakers in Kalundborg and data center operators in Fredericia for bilateral PPA structures bypassing utility intermediaries. A Power-to-X co-location strategy with Aalborg ammonia producers offers the most penetrable entry vector. For Investors and Strategic Acquirers: Re-rating potential sits with independent power producers holding floating demonstration exposure given DNV certification finalization as a catalyst. Long-term viability across the analysis window favors developers with secured seabed leases in water depths beyond sixty meters. Acquisition focus should center on project vehicles with Energinet grid connection queue positions. The signal to monitor is unified floating foundation standards release triggering construction finance availability.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Foundation Certification | DNV standard finalization unlocks project financing for Thyborøn demonstration sites. |
| Port Infrastructure Control | Esbjerg quayside deepening secures marshalling monopoly for next-generation turbines. |
| Domestic Content Compliance | EU Green Deal steel traceability mandates requalify Jutland foundation fabricators. |
| Power Purchase Agreement Structuring | Bilateral corporate offtakes with Kalundborg manufacturers bypass merchant price exposure. |
| Power-to-X Co-location | Aalborg ammonia producers anchor dedicated offshore capacity for Scope 3 decarbonization. |
Study Parameters
Independent corroboration across Danish Energy Agency seabed allocation records, Energinet transmission planning documents, and port authority infrastructure disclosures underwrites the qualitative findings. Primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and jack-up vessel operators combined with secondary validation from EU Green Deal regulatory filings, DNV certification timelines, and customs steel import data. Bottom-up project pipeline aggregation and top-down Nordic power pool demand modeling provided triangulation checks.
Rate-of-change decomposition across turbine scaling curves, domestic content compliance cost trajectories, and floating foundation learning rates structured the analytical framework over the projection horizon. Segmentation dimensions modeled include technology tier, installation depth category, offtake structure, and regulatory framework alignment. CAGRs derived from capacity addition schedules and capital cost evolution curves incorporated Energinet grid connection queue timelines and seabed lease auction cadence as industry-specific inputs.
Inputs from Danish Maritime Authority installation standards and DNV classification society draft guidelines were available through the study window; gaps in finalized floating foundation certification protocols introduce uncertainty bands around project finance availability assumptions. Forecasts reflect documented base-case assumptions regarding domestic content threshold enforcement and jack-up vessel fleet expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Peru Wind Energy Market