
 Steel Salvage Drums Market | 2026-2036
Steel Salvage Drums Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Salvage Drums Market Analytics
UN 1A2/X certification for steel salvage drums is collapsing the supplier base to manufacturers with tested closure systems and hydrostatic validation capabilities. Greif sustains North American production scale through captive steel forming and integrated lining operations. Skolnik Industries specializes in small-batch custom overpacks for nuclear and pharmaceutical waste streams. Mauser Packaging Solutions extends European manufacturing footprint through reusable drum pooling networks.
Steel salvage drums are cylindrical containers fabricated from cold-rolled carbon steel with epoxy-phenolic or zinc interior linings, designed to recover, transport, or overpack damaged or leaking hazardous material containers. Wall thickness typically ranges from 0.9 mm to 1.2 mm with rolled top and bottom chimes for structural rigidity under stack loads. Tight head drums dominate chemical industry procurement for liquid containment, while open head configurations capture waste management demand where interior access simplifies decontamination cycles. Fifty-five gallon capacity anchors volume shipments across oil terminal and agricultural chemical distributor networks.
EPA's Resource Conservation and Recovery Act container standards and DOT 49 CFR hazardous materials packaging regulations govern salvage drum construction, testing intervals, and reuse permissions across United States commerce. OSHA spill containment requirements for facilities handling flammable liquids above threshold quantities further mandate on-site overpack inventory. Stakeholders must weigh steel price volatility against extended drum lifecycles when negotiating multi-year supply agreements with certified fabricators.
Market Dynamics
UN 1A2/X certification requirements are compressing the supplier base toward fabricators with validated hydrostatic testing and captive closure-system production, reshaping competitive economics across salvage drum procurement.
Growth Catalysts
- DOT 49 CFR hazardous materials regulations:Mandated container upgrades across US chemical terminals and refineries sustain replacement drum demand through compliance-driven procurement cycles.
- Superfund remediation projects:Federal and state-led environmental cleanups in the United States generate sustained volume for 55-gallon overpack configurations at contaminated sites.
- Epoxy-phenolic lining technology:Advanced interior coatings extend drum reusability in corrosive chemical service, reducing lifecycle costs for hazardous waste handlers.
Market Restraints
- Cold-rolled steel price volatility:Input cost swings compress fabricator margins and destabilize multi-year supply contract negotiations with industrial buyers.
- Supplier concentration in North American steel forming:Limited domestic capacity for certified salvage drum production creates lead-time vulnerability during demand surges.
- Plastic drum substitution in non-corrosive applications:HDPE alternatives capture lower-risk waste streams where UN certification requirements are less stringent.
Strategic Opportunities
- Reusable drum pooling networks:Asset-light logistics models reduce capital intensity for waste management firms while securing recurring revenue streams for pool operators.
- Small-batch custom overpacks for nuclear decommissioning:Specialized fabrication for radioactive material containment commands premium pricing outside commodity drum markets.
- OSHA spill containment mandates:Threshold quantity requirements for flammable liquid handling force on-site overpack inventory buildup at manufacturing facilities.
Industry Challenges
- Hydrostatic validation testing bottlenecks:Third-party certification backlogs delay new product introductions and constrain capacity expansion timelines for emerging fabricators.
- Welding technician scarcity:Specialized skill requirements for seam welding and chime rolling limit production scale-up at regional drum manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Salvage Drums Market |
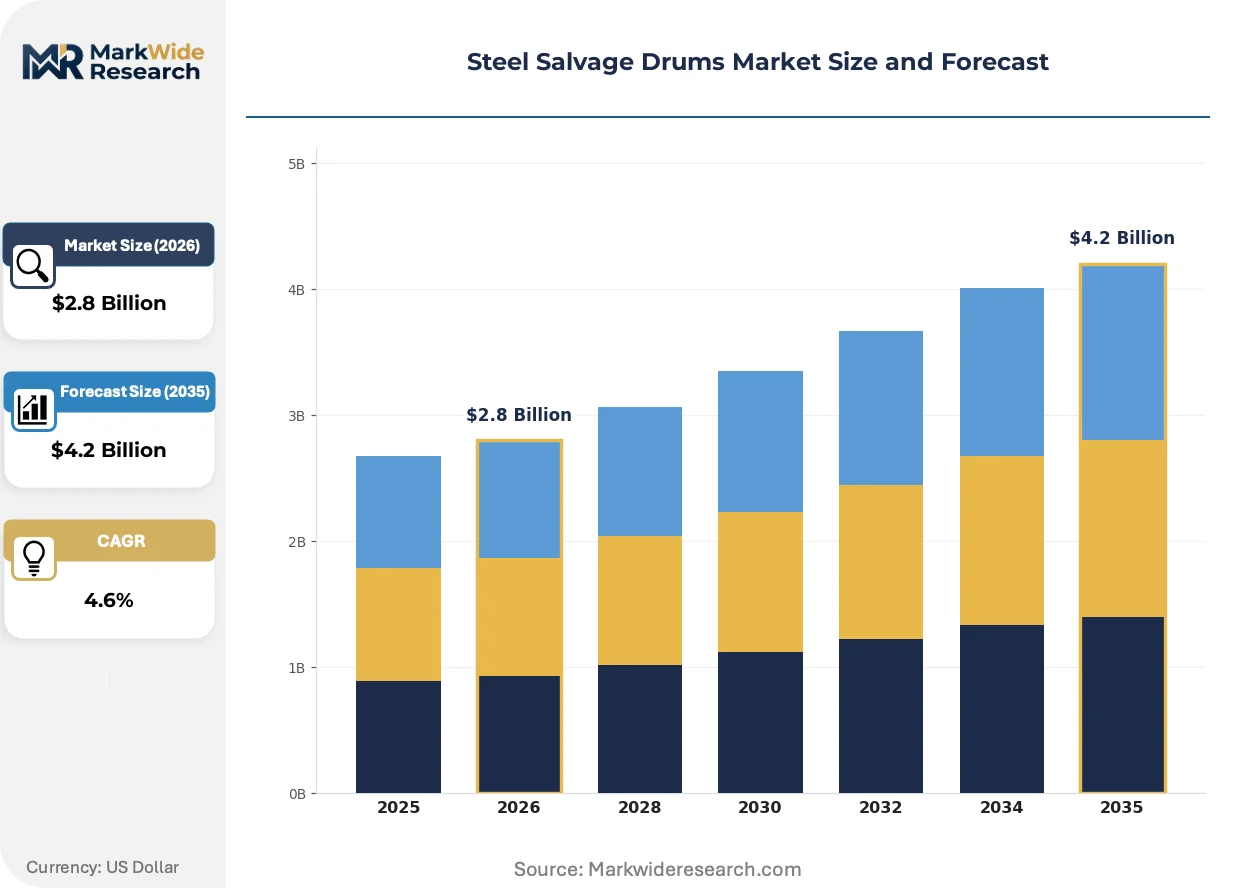
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Overpacks, Tight Head Drums, Open Head Drums, Composite Drums End User: Chemical Industry, Agriculture, Oil & Gas, Waste Management Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers Capacity: 30 Gallons, 55 Gallons, 85 Gallons, 120 Gallons |
| Companies Covered | Greif, Skolnik Industries, Mauser Packaging Solutions, Schutz Container Systems, General Steel Drum, Balmer Lawrie, Rahway Steel Drum, Quitman O'Neill Packaging, Denios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Salvage Drums Market Evolving Landscape
Active transformation across steel salvage drums centers on regulatory ratcheting, materials engineering advances, and procurement model restructuring that together redefine supplier-buyer relationships.
Composite-reinforced steel hybrid drums are miniaturizing the performance gap between traditional salvage drums and specialized overpacks for extreme service conditions. Nuclear waste handlers and pharmaceutical manufacturers are piloting these configurations for high-value containment applications. The technology is miniaturizing the addressable market for premium-grade salvage solutions by compressing the cost differential against custom-fabricated alternatives.
EPA's Resource Conservation and Recovery Act container standards are tightening reuse permission windows and mandating more frequent integrity testing intervals. Waste management operators face accelerated drum retirement schedules and expanded documentation burdens. Chemical processors in the United States are responding by consolidating supplier relationships toward vertically integrated fabricators with in-house testing capabilities.
Buyers are unbundling drum procurement from legacy integrated waste service contracts and negotiating direct supply agreements with certified manufacturers. This disintermediation compresses distributor margins while transferring specification accountability to end-users. Refinery maintenance contractors in Texas and Louisiana are most visibly adopting this model, leveraging volume concentration to secure price advantages and custom lining configurations.
Steel Salvage Drums Market Segmentation
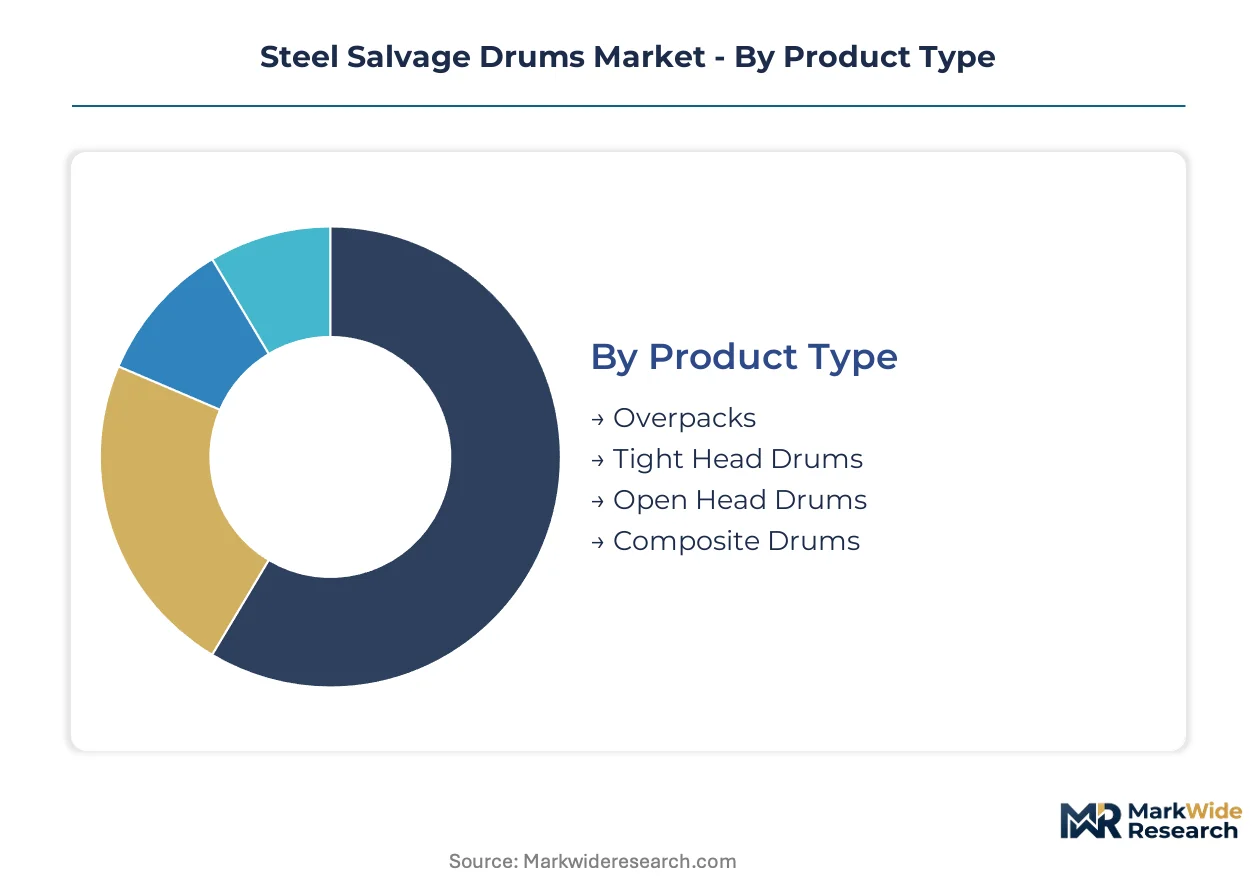
Segmentation in steel salvage drums reveals how regulatory pressure and operational requirements fragment demand across distinct technical specifications. Procurement patterns diverge sharply between compliance-driven replacement cycles and specialized containment applications.
Product Type:
Domestic fabrication dominates tight head and open head configurations, while composite drums draw heavily on European coating technology and Asian steel forming inputs.
- Tight Head Drums:Seam-walled cylinders with permanently attached tops suit liquid chemical containment where vapor retention matters. Refinery maintenance contractors in Texas and Louisiana concentrate procurement here, driven by DOT 49 CFR upgrade mandates for terminal storage.
- Open Head Drums:Removable lid configurations with bolt-ring closures enable interior access for decontamination cycles. Waste management operators across EPA Superfund sites favor these for soil remediation where drum cleaning and reuse extends asset life.
- Overpacks:Secondary containment vessels for damaged primary containers. Chemical distributors stock these for spill response compliance under OSHA threshold quantity rules.
- Composite Drums:Steel-polymer hybrid walls for corrosive service. Nuclear decommissioning projects in the United States pilot these for radioactive waste streams.
Tight head drums hold the largest share; momentum sits with composite drums.
End User:
Cost tier segmentation separates commodity drum buyers from premium containment purchasers willing to absorb custom fabrication premiums.
- Chemical Industry:Processors of acids, solvents, and reactive intermediates require epoxy-phenolic lined drums with UN 1A2/X certification. Batch chemical manufacturers in the US Gulf Coast sustain volume demand through recurring replacement schedules tied to corrosion monitoring.
- Waste Management:Hazardous waste handlers and environmental remediation firms deploy salvage drums for spill containment and overpacking damaged containers. Federal Superfund allocations drive procurement timing across contaminated site portfolios.
- Oil & Gas:Upstream operators and terminal operators stock drums for crude oil sample containment and refinery turnaround waste. Maintenance cycle timing concentrates purchases in Q1-Q2 pre-turnaround periods.
- Agriculture:Pesticide and fertilizer distributors use salvage drums for damaged container recovery. Seasonal application windows compress demand into planting and harvest periods.
Chemical industry procurement holds the largest share; waste management is expanding most quickly.
Distribution Channel:
Volume concentration favors direct manufacturer relationships for large accounts, while fragmented buyers rely on distributor inventory buffers.
- Direct Sales:Refinery contractors and national waste management firms negotiate multi-year supply agreements with certified fabricators. This channel captures specification accountability and custom lining requirements.
- Distributors:Regional industrial supply houses maintain salvage drum inventory for emergency spill response and smaller chemical processors. Lead time advantages attract buyers without advance procurement planning.
- Wholesalers:Bulk aggregators serve agricultural cooperatives and independent oilfield service companies. Price-sensitive procurement dominates this tier.
- Online Retail:E-commerce platforms capture small-lot buyers and replacement drum searches. Limited to standard configurations without custom lining options.
Direct sales holds the largest share; distributors are gaining share fastest.
Capacity:
Application requirements and handling logistics determine capacity selection, with regulatory packaging rules constraining certain waste streams to specific volumes.
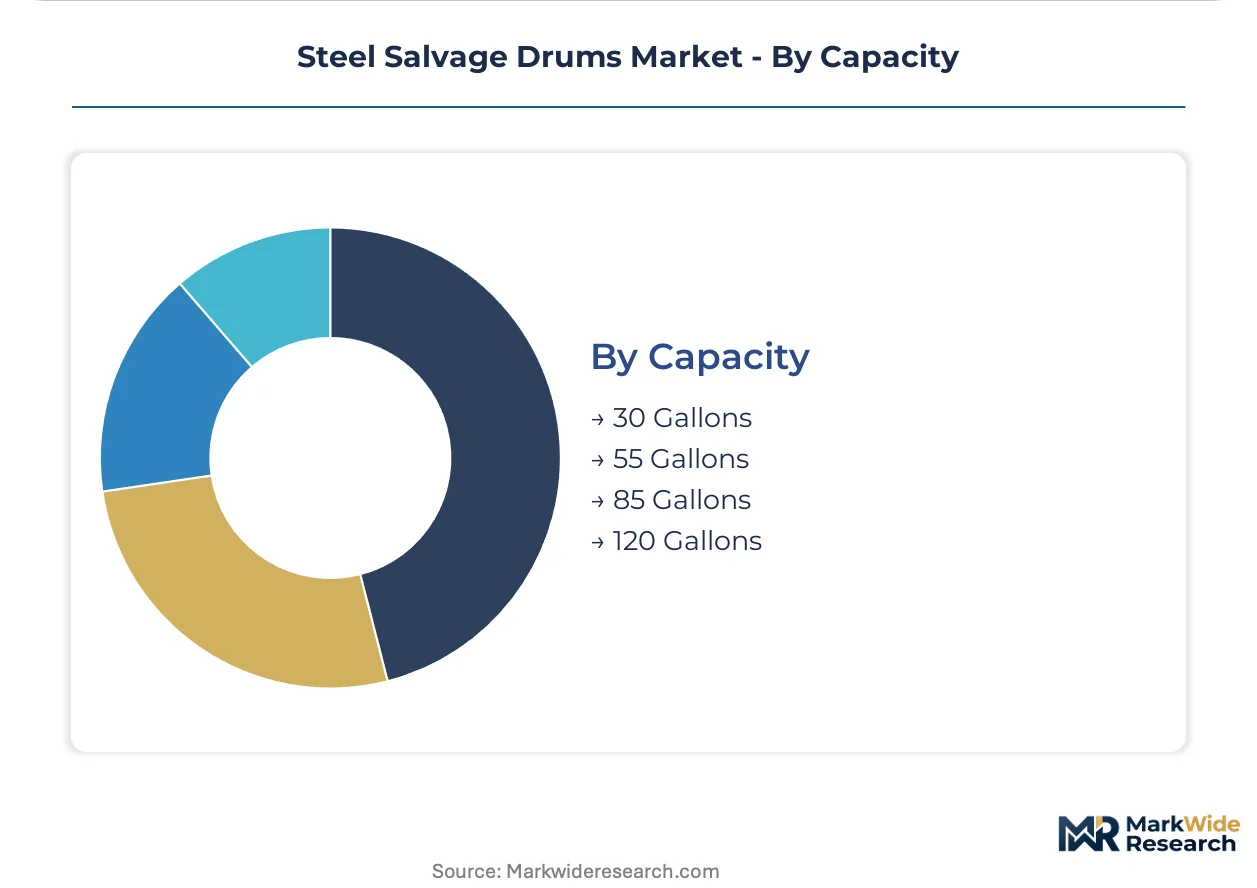
- 55 Gallons:The standard reference capacity anchoring oil terminal and chemical distributor networks. DOT regulations standardize handling equipment and storage rack dimensions around this specification.
- 30 Gallons:Compact drums for laboratory waste and small-batch chemical handling. Pharmaceutical manufacturers and university research facilities concentrate demand here.
- 85 Gallons:Intermediate capacity capturing bulk waste consolidation applications. Regional waste treatment facilities use these for intermediate storage prior to bulk transport.
- 120 Gallons:Large-format drums for high-volume waste streams and bulk liquid overpacking. Limited adoption due to handling equipment requirements and transport weight restrictions.
Fifty-five gallon drums hold the largest share; thirty gallon configurations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DOT 49 CFR hazardous materials regulations and EPA container standards are concentrating procurement upgrades in North American facilities, while European REACH compliance and Asian industrial safety codes reshape demand patterns across distinct regulatory environments.
United States
Refinery maintenance cycles and Superfund remediation projects sustain replacement purchases across Gulf Coast chemical terminals. EPA Resource Conservation and Recovery Act container standards mandate integrity testing intervals that accelerate drum retirement schedules. Houston and Port Arthur industrial clusters concentrate procurement volume for 55-gallon overpack configurations during Q1-Q2 turnaround periods.
Germany
Chemical processors along the Rhine corridor require UN-certified salvage drums for corrosive intermediate containment under ECHA REACH substance restrictions. The country's national hazardous materials regulator enforces packaging performance standards that exceed baseline EU requirements. BASF and Bayer supplier networks in Ludwigshafen and Leverkusen drive demand for epoxy-phenolic lined tight head configurations.
China
Petrochemical expansion in Zhejiang and Jiangsu provinces generates volume for spill containment infrastructure under GB standards for dangerous goods packaging. The Ministry of Ecology and Environment tightens waste container traceability rules that favor certified steel drum suppliers. Ningbo-Zhoushan port operations anchor procurement for crude oil sample containment and terminal waste handling.
India
Pesticide distributors in Gujarat and Maharashtra deploy salvage drums for damaged container recovery during seasonal application windows. The Central Pollution Control Board mandates hazardous waste manifest systems that require documented overpack chain-of-custody. Ankleshwar and Vapi industrial estates concentrate demand for open head configurations that simplify decontamination cycles.
Brazil
Agricultural chemical cooperatives in São Paulo and Paraná states stock salvage drums for fertilizer and agrochemical spill response. ANVISA pharmaceutical packaging regulations extend to active ingredient transport containers for domestic formulation facilities. Campinas and São José dos Campos manufacturing corridors pilot composite-reinforced drums for high-value chemical containment.
Steel Salvage Drums Market Competitive Landscape
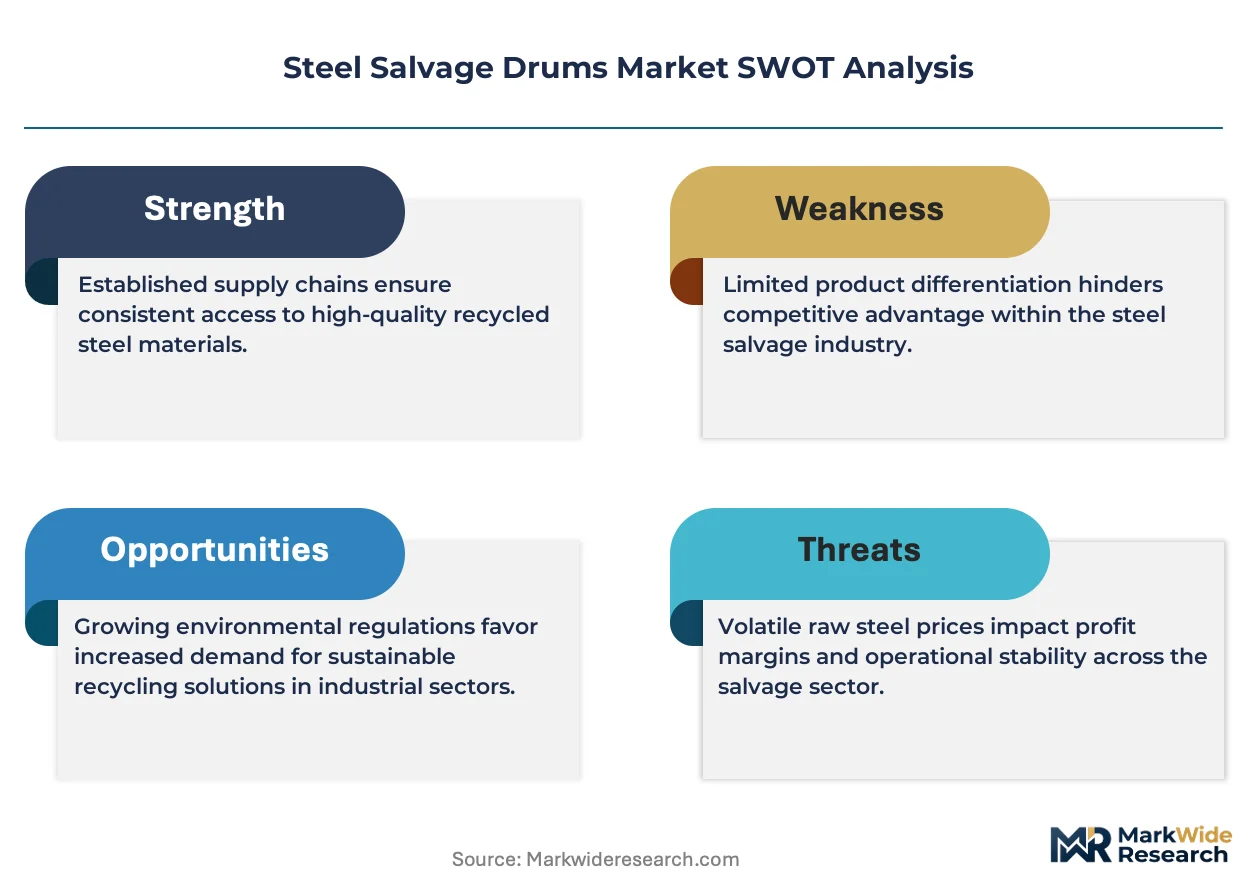
Player mix skews toward vertically integrated metal packaging conglomerates with captive steel forming and in-house UN certification capabilities. Tiering separates commodity drum fabricators serving agricultural and oilfield waste streams from specialists in nuclear and pharmaceutical containment. Two dominant competitive moves are reshaping positioning: backward integration into cold-rolled steel supply to buffer price volatility, and geographic expansion through reusable drum pooling networks that reduce customer capital intensity.
Among North American-based fabricators, Greif exemplifies the scale-driven archetype through integrated lining operations and hydrostatic validation capabilities. Skolnik Industries occupies the specialist tier with small-batch custom overpack positioning for radioactive material containment. Mauser Packaging Solutions anchors the European expansion vector through reusable pooling network deployment across industrial waste management accounts.
| Leading Market Players |
|---|
| Greif |
| Skolnik Industries |
| Mauser Packaging Solutions |
| Schutz Container Systems |
| General Steel Drum |
| Balmer Lawrie |
| Rahway Steel Drum |
| Quitman O'Neill Packaging |
| Denios |
| Others |
Value Network & Pricing Analysis
Captive hydrostatic testing capacity at North American fabricators creates scale advantages that compress per-unit certification costs and establish price floors for UN 1A2/X-grade salvage drums. Cold-rolled steel input volatility and DOT-mandated container upgrade cycles concentrate procurement power among vertically integrated suppliers with in-house lining operations.
Pricing Analysis
Certification grade—specifically UN 1A2/X versus non-certified salvage configurations—creates the primary price spread across the market. Three-tier pricing structure across premium UN-certified, standard industrial-grade, and economy non-certified levels dominates contract negotiations. Cost compression in the economy tier is intensifying because HDPE drum substitution captures lower-risk waste streams. Agricultural cooperatives and independent oilfield service companies exhibit highest price sensitivity, while nuclear decommissioning contractors and pharmaceutical manufacturers absorb premium multiples for custom overpack specifications.
Supply Chain Analysis
Inventory buffers at regional distributor warehouses stretch lead times during Q1-Q2 refinery turnaround surges, forcing buyers into premium expedited procurement. Supply concentrates in the United States, Germany, and China for certified steel forming and epoxy-phenolic lining operations. Fabrication draws from cold-rolled carbon steel, zinc interior coatings, and bolt-ring closure hardware. Single-source vulnerability around third-party hydrostatic validation testing creates certification bottlenecks that constrain capacity expansion. Distribution runs through direct manufacturer relationships for large accounts, with regional industrial supply houses capturing emergency spill-response demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drum pooling and logistics services expand faster than hardware sales, converting capital expenditure into recurring revenue streams for operators with asset-light network deployment capabilities.
For Market Incumbents: Fortify backward integration into cold-rolled steel supply to buffer margin compression from commodity price swings. Expand captive hydrostatic testing capacity to eliminate third-party certification bottlenecks that constrain volume scaling during DOT-mandated upgrade cycles. Defend against plastic drum substitution by emphasizing UN 1A2/X certification irreplaceability in corrosive chemical service. For New Entrants and Emerging Players: Differentiate on small-batch custom fabrication for nuclear decommissioning and pharmaceutical radioactive waste streams where premium pricing escapes commodity competition. Target composite-reinforced steel hybrid configurations for high-value containment applications with limited incumbent specialization. Pursue direct sales channel establishment with refinery maintenance contractors in Texas and Louisiana seeking specification accountability outside legacy distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fabricators with integrated lining operations and validated closure-system production over pure assembly players. Long-term viability hinges on regulatory ratcheting persistence across EPA and DOT jurisdictions. Acquisition focus should center on regional manufacturers with UN certification capabilities but limited pooling network exposure. Watch for HDPE substitution acceleration in non-corrosive applications as inflection signal for steel drum demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Captive cold-rolled input sourcing buffers margin compression from commodity volatility cycles. |
| Reusable Drum Pooling Network Expansion | Asset-light logistics models convert capital expenditure into recurring revenue across waste management accounts. |
| Custom Overpack Fabrication Capability | Specialized nuclear and pharmaceutical containment commands pricing multiples outside commodity drum markets. |
| In-House Hydrostatic Testing Investment | Eliminating third-party certification bottlenecks accelerates product introduction timelines and capacity scaling. |
| Direct Sales Channel Development | Disintermediation captures specification accountability and custom lining requirements from refinery contractors. |
Research Methodology
Cross-validation between primary fieldwork with drum fabricators and secondary trade data anchors the qualitative findings on procurement pattern shifts. Plant managers at Gulf Coast refineries, hazardous waste procurement leads, distribution channel partners, and EPA compliance officers provided operational validation. Secondary sources included DOT hazmat enforcement records, EPA RCRA facility reports, customs steel drum trade data, and ACC chemical industry expenditure surveys. Bottom-up shipment analysis triangulates against top-down market sizing across product type and end-use dimensions.
Sensitivity analysis around steel price volatility and regulatory enforcement intensity bounds the forecast range across the projection horizon. Segmentation modeling incorporates product type, end-use industry, distribution channel, and capacity tier dimensions. CAGRs derive from regression analysis of historical replacement cycles correlated with DOT upgrade mandates and Superfund allocation patterns. Forecast inputs include refinery maintenance scheduling data and EPA enforcement action trends.
The analysis sits within stated boundaries; outcomes outside sustained DOT regulatory enforcement or accelerated HDPE substitution would require recalibration. Forecasts reflect assumptions about certification backlog persistence and steel input cost trajectories. Revision becomes warranted when plastic drum penetration in chemical handling crosses threshold levels or EPA integrity testing intervals tighten beyond modeled scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Transition Metals Market
Metals
Clutch Spring Wires Market
Metals
HSLA Steel Plate Market
Metals
Global Wire Rods Market
Metals
Copper Chromium Black Market
Metals
Aluminum Fluoride Market
Metals
Arc Ferrite Magnet Market
Metals
Aluminum Smelting Market
Metals
South America Metal Finishing Market
Metals
Neodymium Market
Metals
US and Mexico Stainless Steel Market
Metals
Barium Market
Metals
Metal Recycling Market
Metals
Global Copper Cathode Market
Metals
Silver-Platinum Paste Market
Metals
Silver Nitrate Market