
 Brazil Power Market | 2026-2036
Brazil Power Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Power Market Analysis
Wholesale power procurement channels is reconfiguring as bilateral contracting and regulated auctions split volume flows between free and captive consumers. Eletrobrás leverages its federal transmission backbone to anchor interregional capacity transfers. Engie Brasil Energia competes through renewable-heavy generation portfolios in the Northeast and South. Neoenergia S.A. sustains retail dominance across multiple concession areas through integrated distribution control.
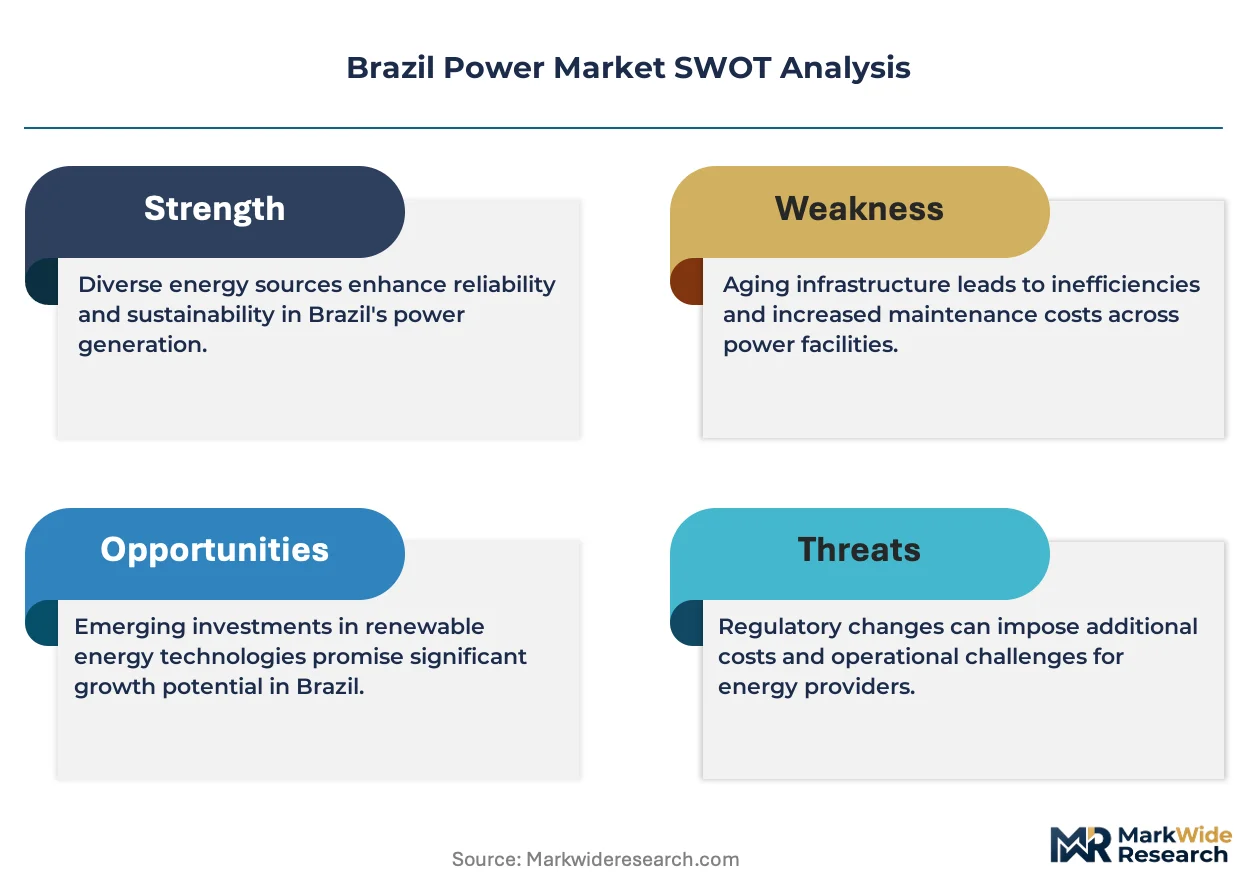
Brazil power encompasses electricity generated, transmitted, distributed, and sold across voltage classes from 127V residential to 500kV trunk lines, with system frequency standardized at 60Hz and grid code compliance enforced under ANEEL's Module 3 resolutions. Its primary purpose is to supply motive force, process heat, and building services across industrial, commercial, and residential loads. Generation type shows renewable capacity leading absolute additions, while distributed generation segments grow fastest from small solar deployments under net metering. Service type reveals transmission and distribution as mature margin pools with regulated returns, whereas retail faces competitive pressure from energy traders and self-producers.
ANEEL sets tariff methodologies and auction rules that directly shape plant dispatch order and investor returns, while the Ministry of Mines and Energy coordinates long-term planning through the Plano Decenal de Expansão de Energia. Environmental licensing under IBAMA constrains hydropower site development, pushing developer portfolios toward lower-impact wind and solar siting. Stakeholders must monitor how proposed tax reform interacts with existing PIS/COFINS exemptions for renewable equipment imports and whether grid access queues clear fast enough to match contracted project timelines.
Market Dynamics
Brazil's power sector is undergoing structural reconfiguration as ANEEL's auction mechanisms redirect capital flows toward wind and solar portfolios while transmission expansion in the Northeast corridor unlocks previously stranded renewable resources.
Growth Catalysts
- Leilão de Energia Nova auctions:ANEEL's competitive procurement framework mandates distributors contract new capacity through price-clearing mechanisms, pulling private investment toward utility-scale wind and solar parks.
- Mining sector load growth:Industrial buyers in iron ore and copper extraction are expanding bilateral contracting for firm renewable supply to meet Scope 3 emissions targets and secure price hedges.
- Northeast transmission corridors:Federal backbone expansion through Eletrobrás-controlled trunk lines is converging with exceptional wind resource quality to concentrate generation investment in Ceará, Rio Grande do Norte, and Bahia.
Market Restraints
- Grid access queue congestion:ANEEL's connection approval timelines for distributed generation projects now stretch 18-24 months, creating project completion risk against auction delivery deadlines.
- Equipment import dependency:Solar PV module and wind turbine nacelle supply concentrates on Asian manufacturing bases, exposing developers to freight cost volatility and currency mismatch between dollar-denominated equipment and real-contracted revenues.
- Environmental licensing friction:IBAMA's watershed impact assessments for run-of-river hydro sites now average 4.7 years, pushing developer portfolios away from dispatchable renewable baseload toward intermittent wind and solar.
Strategic Opportunities
- Distributed generation under net metering:ANEEL's Resolução Normativa 1,000 enables commercial and industrial self-producers to offset grid consumption with behind-the-meter solar, opening retail bypass channels in high-tariff distribution areas.
- Green hydrogen export corridors:Port of Pecém and Port of Suape infrastructure investments position Northeast wind surplus for electrolyzer feedstock supply to European offtake contracts.
- Hybrid solar-wind co-location:Complementary generation profiles on shared grid connection points are compressing firming costs and improving capacity factor metrics for merchant power exposure.
Industry Challenges
- Transmission planning misalignment:Plano Decenal de Expansão de Energia capacity forecasts and ONS operational dispatch priorities diverge from actual renewable project commissioning timelines, creating curtailment risk in high-penetration zones.
- Distribution workforce transition:Concessionaire technical staff require retraining from electromechanical meter maintenance to digital grid management systems as smart metering mandates accelerate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Power Market |
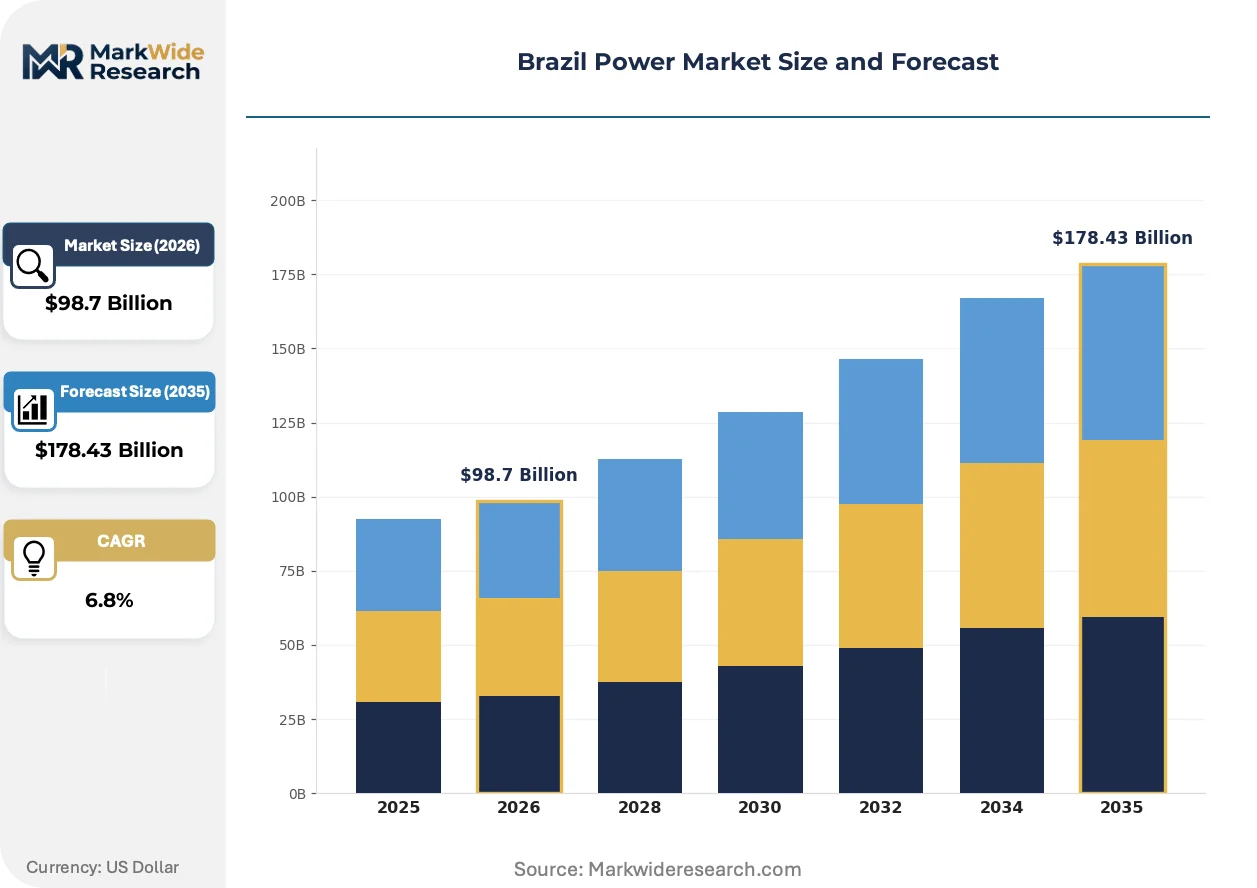
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Non-Renewable, Hybrid, Distributed Generation Service Type: Generation, Transmission, Distribution, Retail Energy Source: Hydropower, Wind, Solar, Biomass End User: Residential, Commercial, Industrial, Government |
| Companies Covered | CPFL Energia S.A., Companhia Energética de Minas Gerais (Cemig), Centrais Elétricas Brasileiras S.A. (Eletrobrás), Eneva S.A., Equatorial Energia S.A., Neoenergia S.A., Engie Brasil Energia S.A., State Grid Brazil Holding, Enel Brasil S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Power Market Emerging Trajectories
Technology convergence and regulatory recalibration are compressing traditional competitive advantages in Brazil's power sector, with digital infrastructure and procurement model innovation creating new entry points for non-incumbent players.
Utility-scale battery energy storage systems paired with solar PV are rendering obsolete the historical reliance on gas-fired peaking plants for evening ramp requirements. Mining consortiums in Minas Gerais and Pará are contracting hybrid solar-storage configurations to displace diesel generation at remote extraction sites. This technology pairing is compressing the merchant power revenue window for thermal assets in the Northeast and South regions.
ANEEL's proposed revisions to Module 3 grid code resolutions are tightening frequency response and reactive power requirements for inverter-based resources. Developer engineering teams must retrofit existing solar farms with upgraded power electronics or face derating penalties. Wind projects above 75MW in the Northeast corridor face the most concentrated compliance timelines given their 2026-2028 commissioning windows.
Large industrial offtakers are consolidating procurement through energy traders rather than direct bilateral contracts with generators. Traders now intermediate roughly 40% of free-market volume in Southeast load centers, disaggregating the traditional generator-retailer relationship. This channel shift is most visible in São Paulo state's automotive and cement manufacturing clusters where procurement functions centralize at holding-company level.
Brazil Power Market Segmentation
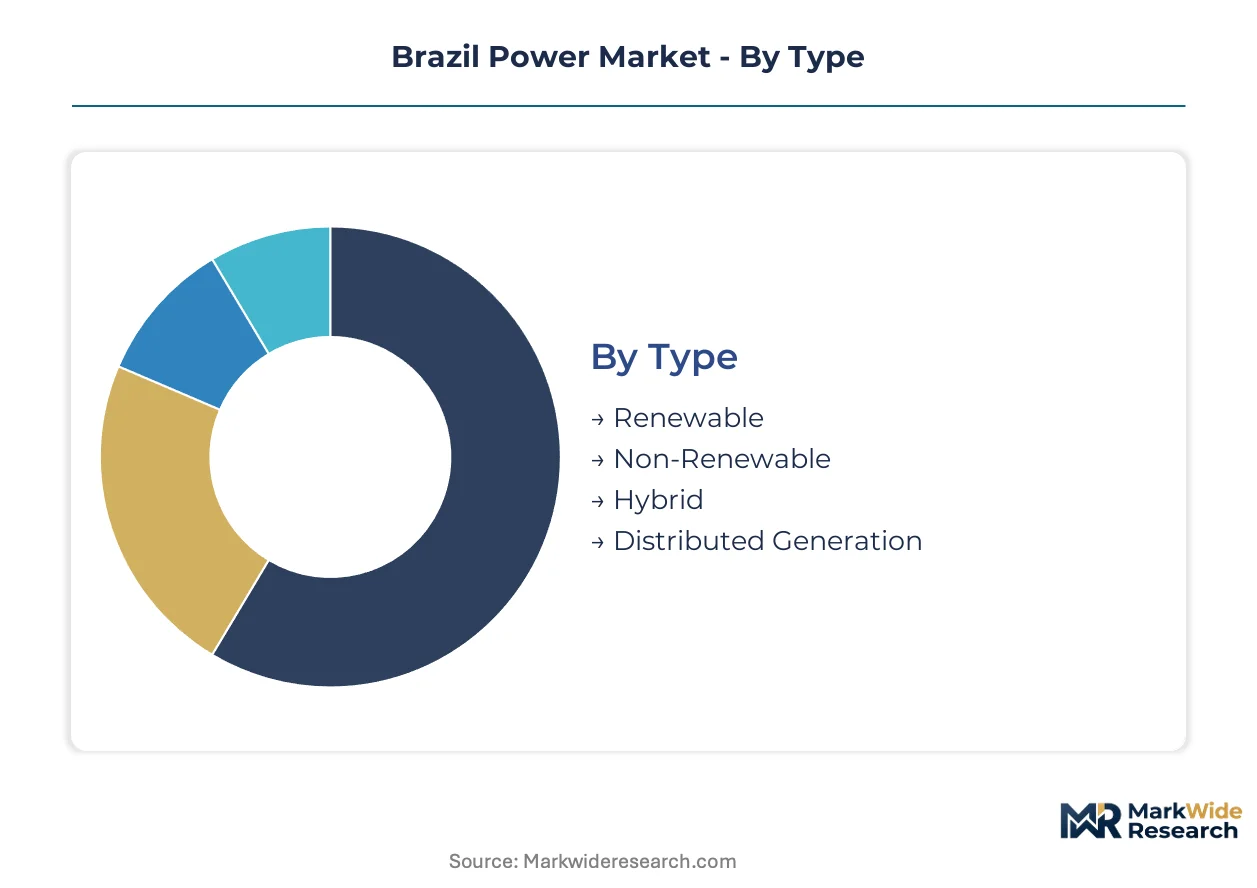
Brazil's power market segmentation reveals how regulatory frameworks and resource endowments allocate investment across generation technologies and service layers. Understanding these divisions exposes where ANEEL auction mechanisms and transmission expansion are redirecting capital flows.
Type:
Cost tier differentiation separates centralized utility-scale projects from behind-the-meter installations, with capital intensity and offtake risk varying sharply across the spectrum.
- Renewable:Wind and solar parks dominate new capacity additions under Leilão de Energia Nova procurement. Northeast corridor developers concentrate in Ceará and Rio Grande do Norte where resource quality meets expanding transmission backbone.
- Non-Renewable:Natural gas peakers and residual coal-fired units provide system flexibility and evening ramp coverage. Grid operators in Southeast load centers dispatch these assets when hydrological conditions constrain reservoir levels.
- Hybrid:Co-located solar-wind configurations with shared grid connection points are compressing firming costs. Merchant power developers in Bahia deploy these pairings to improve capacity factor metrics and reduce transmission wheeling charges.
- Distributed Generation:Behind-the-meter solar installations under ANEEL's net metering framework enable commercial and industrial self-producers to offset regulated tariff exposure.
Renewable holds installed capacity. Hybrid configurations are rotating up the share rankings.
Service Type:
Application focus distinguishes regulated infrastructure from competitive service layers, with margin profiles and capital recovery mechanisms diverging accordingly.
- Generation:Power plant development and operation spans utility-scale auctions and bilateral contracting. Eletrobrás federal hydroelectric dominance competes with private wind and solar portfolios in wholesale energy markets.
- Transmission:High-voltage trunk lines and substations operate under ANEEL concession frameworks with regulated returns. Federal backbone expansion unlocks stranded renewable resources in the Northeast corridor.
- Distribution:Last-mile voltage step-down and metering services remain concession-based with tariff methodologies set by ANEEL. Neoenergia S.A. maintains integrated control across multiple concession areas.
- Retail:Energy trading and supply to free-market consumers faces competitive pressure from self-producers and trader intermediation. São Paulo industrial clusters now route roughly 40% of volume through trader channels rather than direct generator contracts.
Generation commands capital deployment. Retail is gaining commercial attention as trader intermediation expands.
Energy Source:
Volume concentration tracks resource endowment geography, with federal planning prioritizing lowest-cost dispatchable and variable renewable integration.
- Hydropower:Reservoir and run-of-river facilities provide baseload and frequency regulation services. IBAMA environmental licensing timelines averaging 4.7 years are pushing developer portfolios toward lower-impact alternatives.
- Wind:Onshore turbines in the Northeast corridor exploit exceptional capacity factors. ANEEL Module 3 grid code revisions are tightening frequency response requirements for projects above 75MW with 2026-2028 commissioning windows.
- Solar:Utility-scale PV and distributed rooftop installations lead absolute capacity additions. Asian-manufactured module supply exposes developers to freight cost volatility and currency mismatch against real-denominated revenues.
- Biomass:Bagasse-fired cogeneration serves sugar-ethanol processing clusters with dispatchable renewable output. São Paulo state mills anchor installed capacity with integrated agricultural processing.
Wind and solar are climbing the fastest. Hydropower retains dispatch priority in system operations.
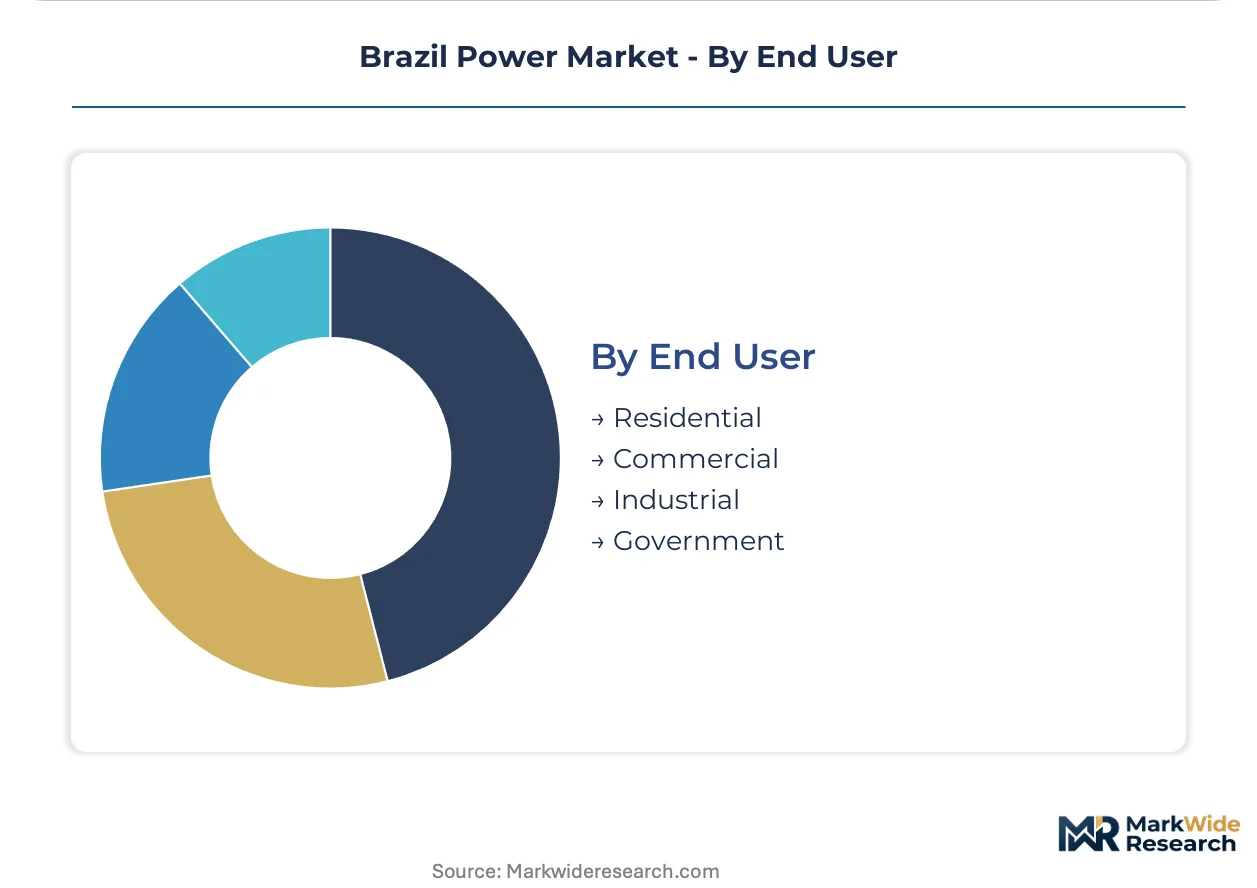
End User:
Customer type segmentation maps tariff exposure and procurement sophistication, with industrial buyers leading the shift toward bilateral renewable contracting.
- Residential:Regulated tariff consumers across distribution concession areas with limited switching options. Smart metering mandates are accelerating digital infrastructure replacement of electromechanical systems.
- Commercial:Small and medium enterprises with rising participation in distributed generation net metering. High-tariff distribution areas drive behind-the-meter solar adoption for consumption offset.
- Industrial:Mining and metals extraction operations in Minas Gerais and Pará are expanding firm renewable supply contracts. Iron ore and copper producers target Scope 3 emissions reductions and price hedges through bilateral procurement.
- Government:Federal and state facility energy demand procured through centralized purchasing frameworks. Public building solar installations support distributed generation targets under national renewable policy.
Industrial load is expanding most quickly. Residential maintains volume concentration across distribution territories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state commands tariff premiums that exceed Northeast corridor contract prices by substantial margins, concentrating industrial procurement sophistication in the Southeast while generation investment migrates toward resource-rich northern states.
São Paulo
Automotive and cement manufacturing clusters in São Paulo state's ABC region centralize procurement through energy traders rather than direct generator contracts. ANEEL's regulated tariff methodologies create arbitrage opportunities for commercial self-producers deploying behind-the-meter solar under Resolução Normativa 1,000. The São Paulo metropolitan area anchors Brazil's highest electricity consumption density with integrated distribution control.
Minas Gerais
Iron ore extraction operations in the Iron Quadrangle expand bilateral renewable contracting to displace diesel generation at remote mine sites. The Ministry of Mines and Energy coordinates federal transmission backbone expansion through Eletrobrás-controlled trunk lines serving southeastern load centers. Belo Horizonte's industrial periphery concentrates bagasse-fired cogeneration capacity from integrated sugar-ethanol processing mills.
Bahia
Merchant power developers deploy hybrid solar-wind configurations on shared grid connection points to improve capacity factor metrics and reduce transmission wheeling charges. IBAMA's watershed impact assessments push developer portfolios toward lower-impact wind and solar siting versus run-of-river hydro alternatives. The Port of Suape infrastructure investments position Northeast wind surplus for green hydrogen electrolyzer feedstock supply.
Rio Grande do Norte
Exceptional onshore wind capacity factors attract utility-scale park development under Leilão de Energia Nova procurement frameworks. ANEEL Module 3 grid code revisions tighten frequency response requirements for projects above 75MW with 2026-2028 commissioning windows. Natal-centered transmission expansion unlocks previously stranded renewable resources for interregional capacity transfers.
Pará
Copper and bauxite extraction operations in the Carajás mineral province target Scope 3 emissions reductions through firm renewable supply contracts. Environmental licensing friction for hydropower site development concentrates investment portfolios toward intermittent wind and solar alternatives. Belém's industrial corridor sustains distributed generation growth through commercial self-producer net metering participation.
Brazil Power Market Vendor Landscape
Federal incumbents and private renewable specialists split the market along regulated infrastructure versus competitive generation lines. Eletrobrás leverages its transmission backbone dominance to anchor interregional capacity transfers, while private developers concentrate auction-winning wind and solar portfolios in the Northeast corridor. Three archetypes define competitive positioning: federal utility holding companies, international energy majors with Brazilian renewable platforms, and regional integrated utilities with distribution concession control. Capacity expansion through auction participation and strategic partnerships for grid access queue positioning represent the dominant competitive moves reshaping participant rankings.
Among federal utility holding companies, Centrais Elétricas Brasileiras S.A. (Eletrobrás) exemplifies the transmission-anchored archetype with its control over interregional trunk line infrastructure. International energy majors with Brazilian platforms include Engie Brasil Energia S.A., which occupies a position concentrated in renewable-heavy generation portfolios, and Neoenergia S.A., which anchors retail dominance across multiple concession areas through integrated distribution control. These three companies represent the structural fault lines between regulated infrastructure returns and competitive merchant power exposure.
| Leading Market Players |
|---|
| CPFL Energia S.A. |
| Companhia Energética de Minas Gerais (Cemig) |
| Centrais Elétricas Brasileiras S.A. (Eletrobrás) |
| Eneva S.A. |
| Equatorial Energia S.A. |
| Neoenergia S.A. |
| Engie Brasil Energia S.A. |
| State Grid Brazil Holding |
| Enel Brasil S.A. |
| Others |
Supply Flow & Price Mechanics
The Port of Pecém logistics corridor exposes equipment freight costs that amplify supply concentration effects, compressing margins for developers locked into dollar-denominated solar module contracts while enabling price differentiation between Northeast wind parks and Southeast industrial offtakers.
Pricing Analysis
The customization-premium spread separates standard auction-tariff projects from configured-to-order bilateral contracts with mining consortiums. Leilão de Energia Nova clearing prices anchor the base tier, while firm renewable supply agreements with iron ore extractors in Minas Gerais command substantial premia for dispatchability guarantees. Pricing pressure stems from Asian-manufactured equipment cost volatility against real-denominated revenues. Industrial buyers in the Southeast exhibit lowest price sensitivity due to Scope 3 compliance mandates, whereas commercial self-producers face acute tariff arbitrage calculations.
Supply Chain Analysis
Upstream feedstock for solar PV modules concentrates in Chinese polysilicon ingot production, with wind turbine nacelle assembly anchored in Denmark and Spain. Brazilian developers draw from these manufacturing bases for photovoltaic cells, power electronics, and blade composites. Single-source vulnerability runs through semiconductor components for grid-tied inverters under ANEEL Module 3 compliance timelines. Distribution runs through Eletrobrás-controlled federal trunk lines to regional distribution concessionaires.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through ANEEL concession frameworks creates durable incumbent advantages against merchant power volatility.
For Market Incumbents: Harden grid access queue positioning through pre-approved connection reserves at high-penetration substations in Rio Grande do Norte and Bahia. Deepen backward integration into power electronics manufacturing to mitigate inverter supply bottlenecks under tightening Module 3 frequency response mandates. The emerging threat of trader intermediation disaggregating generator-retailer relationships demands channel control reinforcement.
For New Entrants and Emerging Players: Mid-market commercial buildings in high-tariff distribution areas of São Paulo state represent the most penetrable entry point for behind-the-meter solar deployment under Resolução Normativa 1,000. Green hydrogen electrolyzer offtake contracts with European importers via Port of Suape infrastructure offer second-mover positioning in Northeast wind surplus monetization. The go-to-market angle centers on integrated energy-as-a-service bundling with smart metering infrastructure.
For Investors and Strategic Acquirers: Carve-out targets emerge from federal utility holding companies divesting non-core generation assets under privatization timelines. Long-term viability across the analysis window hinges on renewable-heavy portfolios with contracted auction volumes and transmission access certainty. The signal to watch is clearance velocity in ANEEL's distributed generation connection queues as a proxy for project completion risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Solar-Wind Capacity Buildout | Co-located configurations in Bahia improve capacity factors and reduce wheeling charges through shared substations. |
| Power Purchase Agreement Restructuring | Long-term firm supply contracts with mining consortiums in Minas Gerais lock in Scope 3 compliance premiums. |
| Grid Code Technology Licensing | Module 3 compliance retrofit services for existing solar farms facing ANEEL derating penalties create recurring revenue. |
| Backward Integration into Storage | Utility-scale battery pairing with Northeast wind parks displaces gas peakers for evening ramp requirements. |
| Green Certification Program | IBAMA-aligned environmental licensing for low-impact solar siting accelerates project timelines versus hydro alternatives. |
Methodological Framework
The analysis maps generation technology segments, service layer divisions, and regional grid configurations, each validated through structured engagement with IPP project developers, ANEEL regulatory officers, EPC contractors, and distribution concession planners. Primary interview findings were cross-referenced against ANEEL auction databases, ONS operational dispatch records, Eletrobrás transmission expansion filings, and IBAMA environmental licensing trackers. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling were reconciled through iterative triangulation.
Assumptions around auction clearing price trajectories, transmission expansion delivery schedules, and equipment import cost pass-through were held fixed across baseline scenarios while hydrological variability, currency fluctuation bands, and grid access queue clearance rates were stress-tested. Segmentation dimensions modeled include fuel source, generation capacity tier, regulatory framework, and regional grid type. CAGRs were derived from contracted capacity flows and commissioning timeline probabilities. Forecast inputs incorporated Plano Decenal de Expansão de Energia capacity targets and mining sector load growth projections.
Stress conditions across equipment freight cost volatility, environmental licensing duration, and auction participation intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including regulatory reform of PIS/COFINS exemptions and proposed tax restructuring. Cross-checking against ANEEL's official auction results database and ONS real-time dispatch statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
India Power Market
Power
Wind Alarm Controller Market
Power
India Uninterruptible Power Supply (UPS) Market
Power
Robotic Power Source Market
Power
Germany Solar Inverter Market
Power
Denmark Power Market
Power
Europe Power Market
Power
Middle-East and Africa Power Market
Power
Critical Power Market
Power
Modified Sine Wave Home Inverters Market
Power
United States Power Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Malaysia Power EPC Market
Power
Compact Substation Market
Power
Power Purchase Agreement Market
Power
Australia Power Market