
 Anti-Graffiti Coatings Market | 2026-2036
Anti-Graffiti Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Graffiti Coatings Market Analysis
Specialty coatings distribution is fragmenting as regional applicators and direct-to-contractor platforms gain share against traditional industrial distributors. BASF SE leverages its polymer research depth to sustain formulation leadership across European infrastructure projects. The Sherwin-Williams Company anchors North American supply through its architectural coatings network and on-site technical service. Teknos Group competes in Nordic municipal tenders where cold-climate durability requirements dominate specification sheets.
Anti-graffiti coatings comprise sacrificial or permanent film-forming systems, typically silicone- or fluoropolymer-based, engineered to prevent paint adhesion or enable low-pressure removal without substrate damage. Water-based formulations are gaining specification share as VOC thresholds tighten across jurisdictions, while permanent technology coatings command premium positioning due to their multi-cycle cleanability and reduced reapplication frequency. Municipal end users represent the deepest volume pool, though commercial buildings generate higher per-project margins through decorative finish integrations.
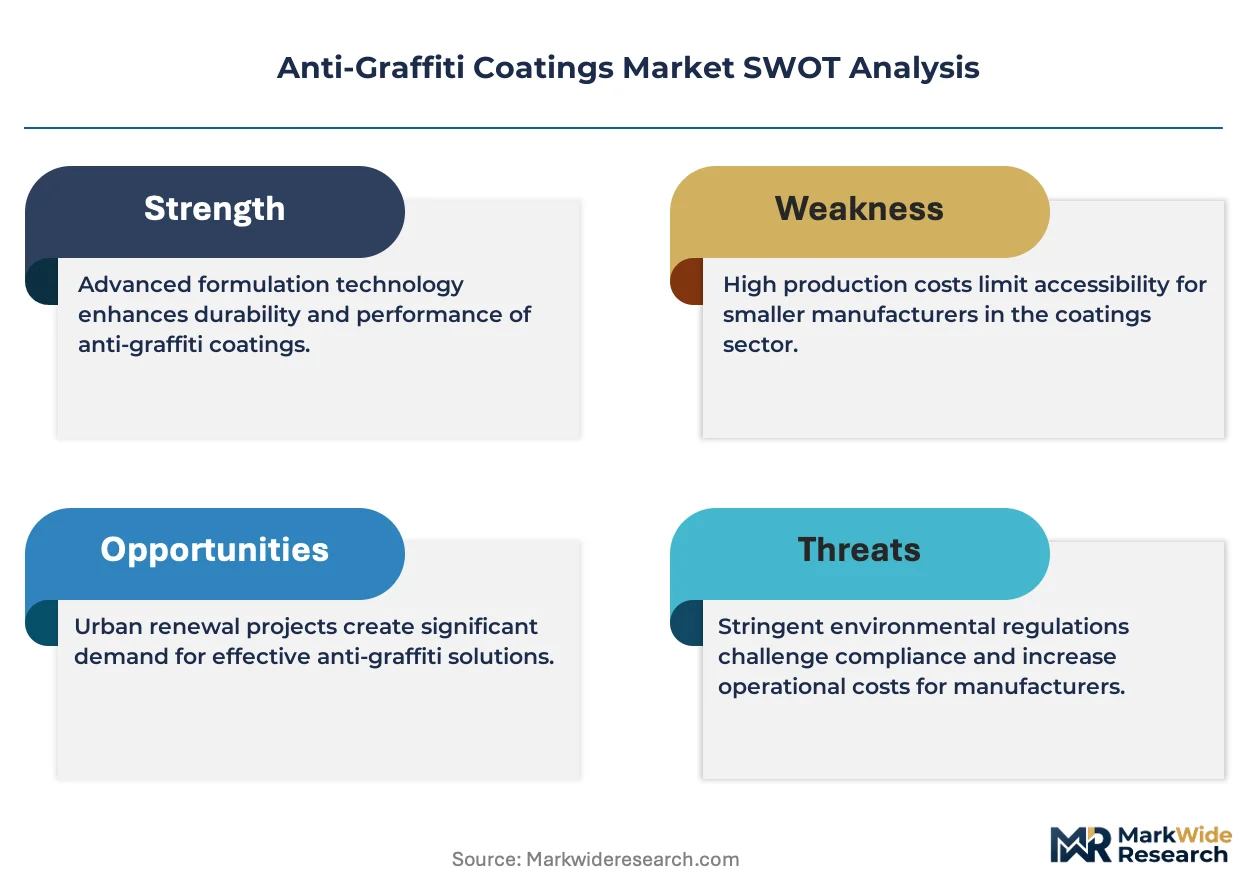
EPA Clean Air Act standards constrain solvent-based product placement in the US, while REACH and RoHS frameworks in Europe mandate disclosure of fluorinated compound content, reshaping R&D allocation toward bio-based precursors. Municipal procurement offices and facilities managers must weigh total lifecycle cleaning costs against first-install chemistry premiums when specifying protection systems for high-vandalism exposure zones.
Market Dynamics
The transition from solvent-based to water-borne and bio-based chemistries constitutes the dominant structural force reshaping competitive positioning, as regulatory thresholds harden and municipal procurement offices recalibrate lifecycle cost models.
Growth Catalysts
- Clean Air Act VOC limits:EPA emission ceilings accelerate formulation turnover toward compliant water-based systems in US municipal transit and infrastructure applications.
- Heritage structure mandates:German federal building maintenance protocols sustain premium coating procurement for protected monuments and public facades.
- Silicone-fluoropolymer hybridization:Advanced film-forming technologies enable multi-cycle cleanability without substrate degradation, expanding specification in high-vandalism zones.
Market Restraints
- Fluorinated compound disclosure:REACH and RoHS frameworks in Europe mandate transparency on PFAS content, constraining R&D allocation and extending certification timelines.
- Petrochemical feedstock volatility:Silicone resin and fluoropolymer precursor costs fluctuate with energy markets, compressing margin predictability for permanent coating formulations.
- Application skill concentration:Proper film thickness and cure protocols require trained applicators, creating bottleneck risks in markets with sparse certified contractor networks.
Strategic Opportunities
- Direct-to-contractor platforms:Digital procurement channels bypass traditional industrial distributors, capturing margin and specification influence in North American municipal segments.
- Cold-climate durability specialization:Nordic tender requirements for freeze-thaw resistance create defensible positioning for formulations validated in sub-zero conditions.
- Bio-based precursor development:Plant-derived silicone alternatives align with EU Green Deal procurement preferences, opening public-sector specification pathways.
Industry Challenges
- Cross-jurisdictional certification fragmentation:Divergent VOC thresholds and performance test methods between US states and EU member states multiply compliance costs for multi-market suppliers.
- Substrate compatibility validation:Historic masonry, modern composites, and coated metals each demand tailored adhesion protocols, stretching technical service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Graffiti Coatings Market |
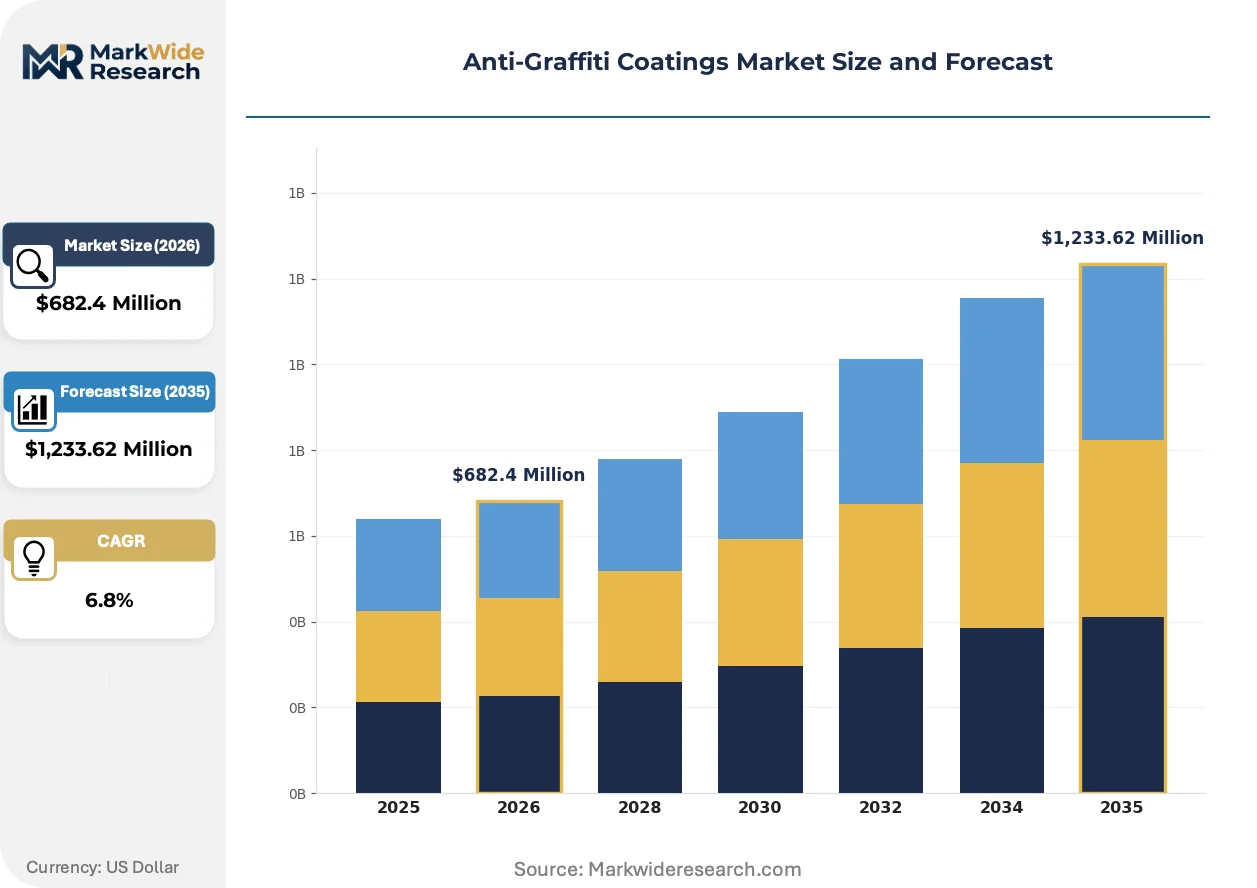
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,233.62 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Bio-Based, Hybrid Application: Wall Protection, Surface Coating, Clear Coating, Decorative Finishes End User: Municipalities, Commercial Buildings, Residential Properties, Educational Institutions Technology: Self-Cleaning, Easy-Clean, Permanent, Removable |
| Companies Covered | BASF SE, Wacker Chemie AG, The Sherwin-Williams Company, Teknos Group, PPG Industries, 3M, Axalta Coating Systems, Sika AG, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Graffiti Coatings Market Emerging Trajectories
Formulation science and procurement mechanics are evolving in parallel, with chemistry migration toward lower-emission platforms coinciding with distribution restructuring and buyer-side total-cost accounting.
Fluoropolymer-silicone hybrid coatings deliver permanent protection through ultra-low surface energy films that reject paint bonding and enable pressure-wash removal. Municipal transit authorities in Germany and the Netherlands specify these systems for station infrastructure requiring decade-long service intervals. The technology is migrating from premium heritage applications toward standard municipal procurement as lifecycle cost models demonstrate reapplication savings.
EPA Clean Air Act standards under Title I constrain solvent-based product placement in US architectural and infrastructure markets, with state implementation plans tightening thresholds beyond federal floors. Manufacturers reformulate with water-borne acrylic-urethane hybrids and bio-based alkyds to maintain specification access. California Air Resources Board protocols now influence formulation decisions for suppliers serving multiple North American jurisdictions.
Facilities managers and municipal procurement offices increasingly specify coatings through total lifecycle cleaning cost models rather than first-install price points. Direct-to-contractor digital platforms displace traditional industrial distributor relationships in mid-sized North American metro markets. This behavioral shift is most pronounced in transit authority tenders where graffiti removal labor costs dominate 10-year ownership calculations.
Anti-Graffiti Coatings Market Segmentation
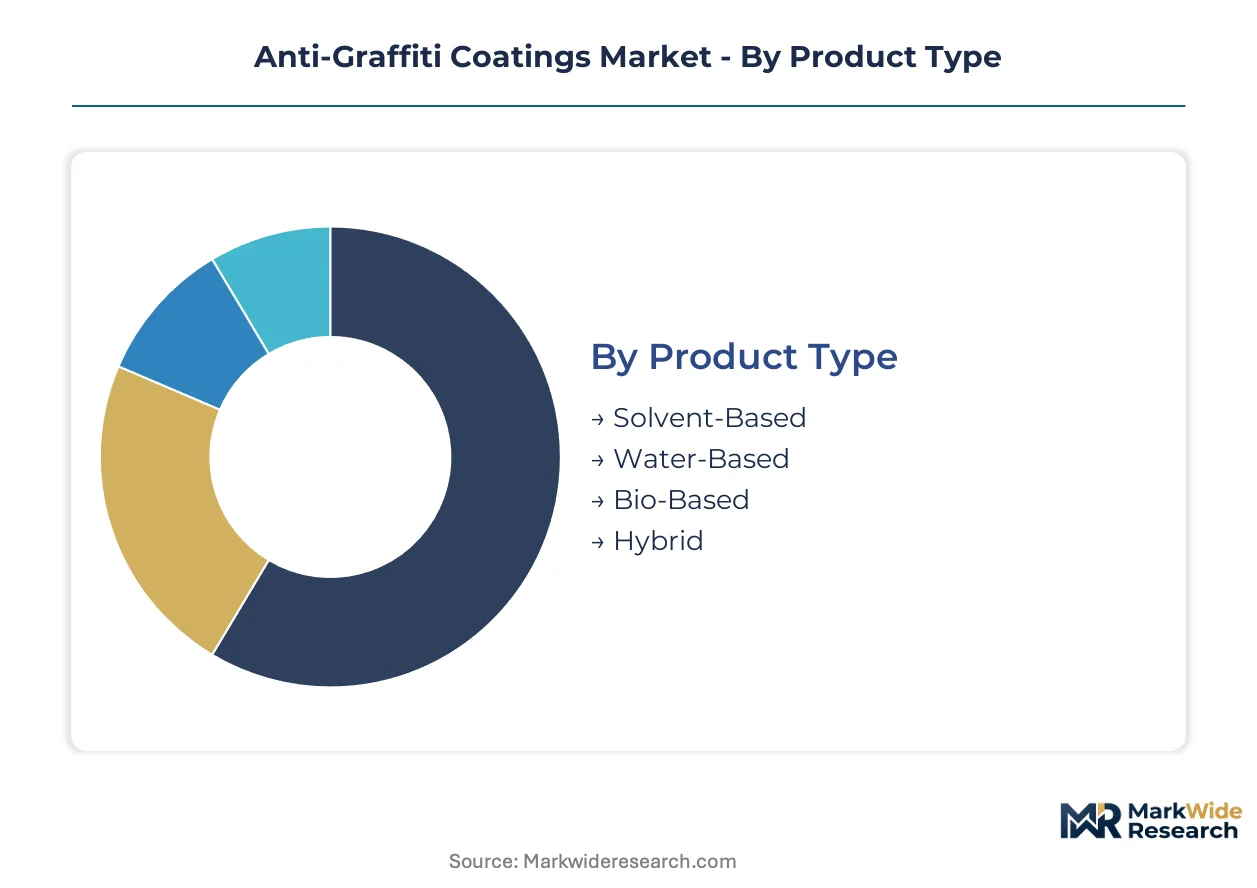
Anti-graffiti coating procurement splits across chemistry platforms, application methods, and protection technologies that each carry distinct cost structures and regulatory footprints. Specification decisions hinge on substrate compatibility, vandalism exposure intensity, and lifecycle maintenance budgets rather than upfront material costs alone.
Product Type:
Use-case spectrum spans heritage monument restoration requiring breathable formulations to high-traffic transit infrastructure demanding rapid-cure durability.
- Solvent-Based:Alkyd and urethane systems deliver rapid cure times and superior adhesion to weathered masonry. German heritage conservation offices specify these for protected facades where water-borne alternatives risk substrate damage. EPA VOC ceilings under Title I constrain specification growth in US municipal tenders.
- Water-Based:Acrylic-urethane hybrids dominate North American transit authority procurement as California Air Resources Board thresholds propagate across state implementation plans. These formulations sacrifice some chemical resistance for compliance access and reduced applicator exposure hazards.
- Bio-Based:Plant-derived alkyd precursors align with EU Green Deal procurement preferences in Dutch and Danish municipal frameworks.
- Hybrid:Silicone-fluoropolymer combinations command premium positioning through multi-cycle cleanability without film degradation.
The dominant share belongs to Water-Based formulations, while Hybrid systems are closing the gap fastest as lifecycle cost models gain procurement influence.
Application:
Cost tier differentiation separates specification-grade heritage treatments from high-volume transit infrastructure coatings.
- Wall Protection:Thick-film systems for concrete and masonry substrates in subway stations and pedestrian underpasses. Chicago Transit Authority and Berlin BVG specify these for vertical surfaces bearing repeated graffiti exposure.
- Surface Coating:Thin-film treatments for metal panels, composite cladding, and coated substrates where adhesion chemistry demands precise matching. Commercial building facades in Frankfurt and Amsterdam generate premium-margin specification.
- Clear Coating:Invisible protection preserving natural stone and brick aesthetics on historic monuments. Bavarian state heritage offices mandate these for protected structures under federal maintenance protocols.
- Decorative Finishes:Pigmented systems integrating anti-graffiti function with color-matched architectural aesthetics. High-end commercial developments in London and Paris specify these for brand-aligned exterior presentation.
Wall Protection commands the deepest volume pool, though Decorative Finishes generate the highest per-project margins through specification bundling.
End User:
Customer type segmentation reflects divergent procurement sophistication and total-cost-accounting maturity across buyer organizations.
- Municipalities:Transit authorities and public works departments dominate procurement volume through multi-year infrastructure maintenance contracts. These buyers apply 10-year lifecycle models weighing reapplication frequency against cleaning labor costs.
- Commercial Buildings:Property managers and facilities operators generate premium-margin demand through decorative integration and rapid-response maintenance requirements. German commercial real estate investment trusts specify permanent coatings for Class A office assets.
- Residential Properties:Homeowner association and multi-family housing demand concentrates in high-vandalism urban districts. Price sensitivity limits specification to sacrificial systems with lower upfront investment.
- Educational Institutions:University facilities managers balance budget constraints with high-visibility vandalism exposure on campus landmarks. Dutch higher education procurement frameworks increasingly require environmental product declarations.
Municipalities anchor procurement volume, while Educational Institutions are expanding specification share fastest as campus security budgets incorporate surface protection.
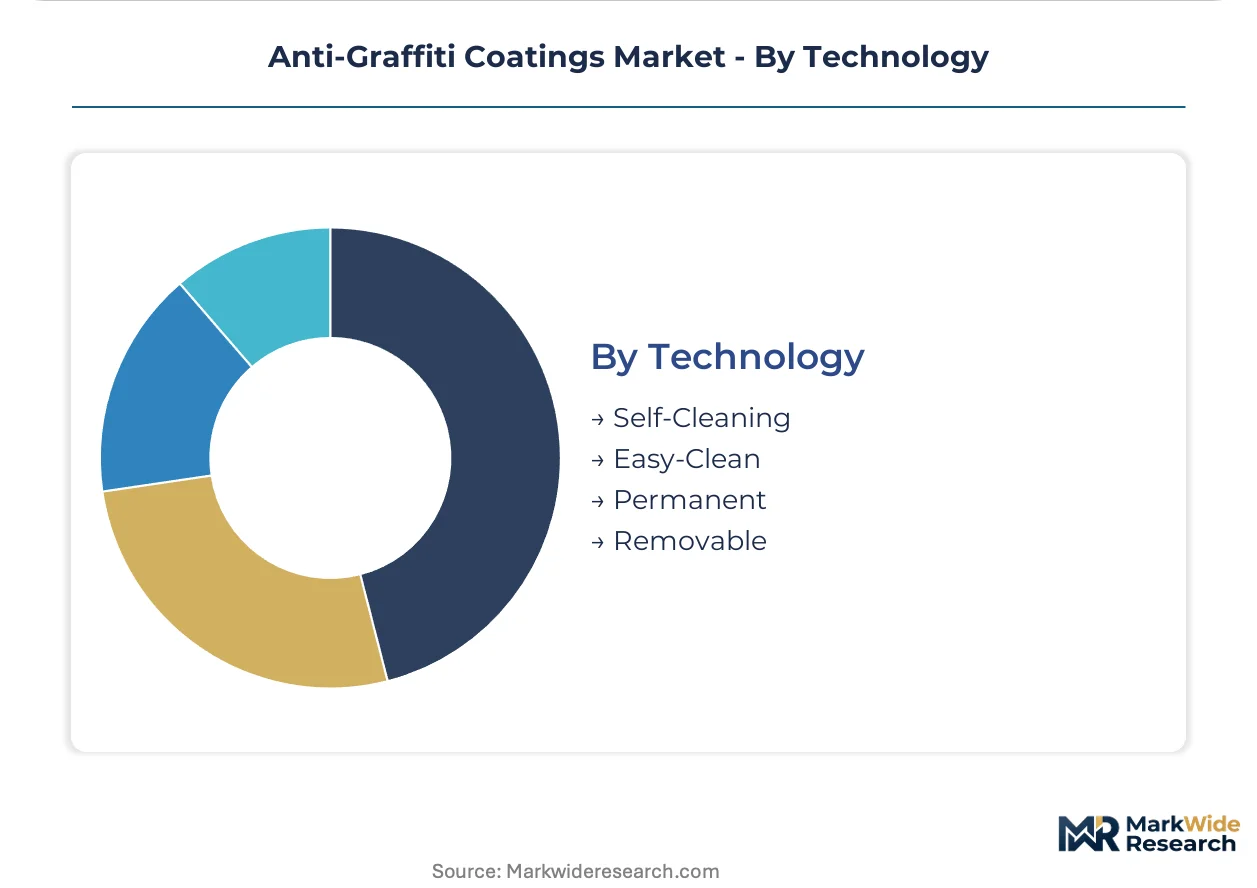
Technology:
Application maturity separates established sacrificial systems from emerging permanent film technologies reshaping competitive positioning.
- Permanent:Fluoropolymer and silicone-based ultra-low surface energy films enable pressure-wash removal without coating degradation. German municipal transit infrastructure specifies these for decade-long service intervals.
- Removable:Sacrificial wax or polymer layers that lift off with graffiti during cleaning, requiring reapplication after each incident. Lower upfront costs sustain demand in budget-constrained residential and small commercial segments.
- Self-Cleaning:Photocatalytic titanium dioxide coatings leveraging UV activation to degrade organic contaminants. Limited commercial deployment pending durability validation in high-pollution environments.
- Easy-Clean:Modified surface energy treatments reducing adhesion without full permanent protection. Intermediate positioning attracts commercial buyers seeking compromise between performance and cost.
Permanent technology holds the specification lead in premium infrastructure, while Easy-Clean alternatives are gaining traction fastest among cost-optimizing commercial facilities managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chicago Transit Authority's elevated rail infrastructure sustains North American demand concentration. German federal railway networks anchor European specification volumes. Japanese urban rail corridors drive precision coating requirements across East Asia.
United States
Metropolitan transit authorities in Chicago, New York, and Los Angeles specify permanent anti-graffiti systems for station infrastructure and rolling stock. EPA Clean Air Act Title I VOC ceilings constrain solvent-based product placement, accelerating water-borne acrylic-urethane adoption. California Air Resources Board thresholds propagate across state implementation plans, reshaping formulation decisions for suppliers serving multiple jurisdictions.
Germany
Federal building maintenance protocols and heritage structure protection laws sustain premium coating procurement for protected monuments and public facades. REACH and RoHS frameworks mandate disclosure of fluorinated compound content, extending certification timelines for permanent film technologies. Bavarian state heritage offices and Berlin BVG transit infrastructure represent the deepest specification pools within federal procurement frameworks.
Netherlands
Municipal tender requirements for cold-climate durability and environmental product declarations reshape competitive positioning. EU Green Deal procurement preferences accelerate bio-based alkyd precursor specification in Dutch municipal frameworks. Amsterdam and Rotterdam transit authorities apply decade-long lifecycle cost models weighing reapplication frequency against cleaning labor expenditures.
Japan
Urban rail operators in Tokyo and Osaka specify ultra-low surface energy films for station infrastructure requiring pressure-wash removal compatibility. METI industrial standards and JIS performance test methods govern coating certification for public infrastructure applications. Kanto and Kansai metropolitan clusters concentrate demand through concentrated transit authority procurement offices.
United Kingdom
Transport for London and Network Rail infrastructure maintenance contracts drive specification for thick-film wall protection systems. CSRD sustainability disclosure requirements influence procurement criteria for commercial building applications. London and Manchester commercial real estate investment trusts specify permanent coatings for Class A office assets in high-vandalism exposure zones.
Anti-Graffiti Coatings Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying resin precursors and film-forming technologies. The supplier base organizes around three strategic archetypes: diversified chemical conglomerates with polymer research depth, regional coating formulators with applicator network control, and specialty additive suppliers with surface chemistry expertise. Consolidation pressure operates through backward integration into silicone resin production and forward integration into direct-to-contractor digital distribution channels.
Among diversified chemical conglomerates, BASF SE and Wacker Chemie AG exemplify the integrated platform model with captive polymer research capabilities spanning European infrastructure projects. The Sherwin-Williams Company anchors North American supply through architectural coatings network density. Teknos Group occupies a specialized position within Nordic municipal tender environments where freeze-thaw validation requirements dominate specification sheets.
| Leading Market Players |
|---|
| BASF SE |
| Wacker Chemie AG |
| The Sherwin-Williams Company |
| Teknos Group |
| PPG Industries |
| 3M |
| Axalta Coating Systems |
| Sika AG |
| Akzo Nobel N.V. |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's volatile container rates transmit directly into silicone resin landed costs, concentrating margin pressure on German formulators while amplifying price spreads between permanent and sacrificial coating tiers across European municipal procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fluoropolymer-silicone hybrids from water-borne acrylics and basic sacrificial waxes. Certification grade under EU Green Deal protocols and volume scale in multi-year transit authority contracts drive price differentiation. Cost compression in the standard tier is intensifying because REACH fluorinated compound disclosure extends certification timelines. Residential homeowner associations exhibit the highest price sensitivity, while German heritage conservation offices demonstrate the least.
Supply Chain Analysis
Silicone resin and fluoropolymer precursor production draws from Germany, Japan, and the United States. Key inputs span petrochemical-derived silanes, fluorinated monomers, and plant-derived alkyd oils. Single-source vulnerability in fluoropolymer feedstock concentrates risk for permanent coating manufacturers. Distribution runs through direct-to-contractor digital platforms displacing traditional industrial distributors in North American metro markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Clean Air Act Title I VOC ceilings constitute a regulatory inflection accelerating formulation turnover and compressing solvent-based incumbents, positioning water-borne and bio-based platforms for disproportionate growth capture.
For Market Incumbents: Entrench formulation leadership through captive silicone resin production and accelerated bio-based precursor R&D. BASF SE and Wacker Chemie AG anchor European supply through polymer research depth; defending this position requires backward integration into plant-derived alkyd feedstocks as EU Green Deal procurement preferences harden. Channel control through certified applicator networks represents the priority lever against direct-to-contractor platform erosion. For New Entrants and Emerging Players: Establish a beachhead in Nordic municipal tenders where Teknos Group's freeze-thaw specialization has validated cold-climate durability as a specification gate. Dutch and Danish transit authority frameworks under EU Green Deal protocols present the most penetrable procurement entry points. A go-to-market angle centered on environmental product declarations and decade-long lifecycle cost models bypasses incumbent brand recognition advantages. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates' non-core coating divisions where anti-graffiti portfolios lack dedicated R&D allocation. Long-term viability hinges on permanent technology migration and bio-based formulation readiness. The signal to watch is California Air Resources Board threshold propagation across additional state implementation plans, which would accelerate water-borne specification share and strand solvent-based capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Resin | Captive supply of fluoropolymer precursors insulates BASF SE and Wacker Chemie AG from petrochemical volatility. |
| Bio-Based Alkyd Precursor Development | Plant-derived alternatives align with Dutch and Danish municipal procurement under EU Green Deal frameworks. |
| Direct-to-Contractor Platform Launch | Digital channels capture margin and specification influence in Chicago Transit Authority and Los Angeles Metro tenders. |
| Cold-Climate Durability Certification | Freeze-thaw validation opens Nordic municipal tender access beyond Teknos Group's incumbent positioning. |
| Environmental Product Declaration Investment | Third-party lifecycle documentation satisfies Dutch higher education and German commercial REIT procurement criteria. |
Methodological Framework
A spread of perspectives from coating formulators, municipal procurement officers, certified applicators, and heritage conservation technical directors converged on the working assumptions. Primary fieldwork combined structured interviews with plant managers at silicone resin production facilities, transit authority maintenance directors in Germany and the Netherlands, and distribution channel partners across North American metro markets. Secondary validation drew from EPA Clean Air Act regulatory filings, ECHA REACH substance registrations, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade data on fluoropolymer precursor imports. Bottom-up demand modeling triangulated against top-down market sizing across chemistry platforms and protection technologies.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions spanned chemistry platform, application method, protection technology, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends across premium and standard tiers. Industry-specific forecast inputs incorporated REACH fluorinated compound disclosure timeline assumptions and California Air Resources Board threshold propagation patterns.
Stress conditions across petrochemical feedstock volatility, REACH certification timeline extensions, and municipal budget contraction scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on water-borne formulation adoption curves and direct-to-contractor platform penetration rates. Regulatory acceleration or deceleration in EPA state implementation plans and EU Green Deal procurement enforcement could materially revise trajectory. Cross-checking against ECHA substance registration volumes and North American transit authority maintenance expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Automotive Conformal Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
Europe Powder Coatings Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Coating Resins Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
North America Superhydrophobic Coating Market
Coatings
Global Waterborne Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
Architectural Metal Coatings Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
Global Sputter Coatings Market