
 Stationery Products Market | 2026-2036
Stationery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Stationery Products Market Intelligence
A clear divergence between premium, design-led products and mass-market commodity items is realigning the competitive landscape. Faber-Castell differentiates through its focus on high-quality art supplies and premium writing instruments. In contrast, BIC leverages immense manufacturing scale to compete effectively in the high-volume, price-sensitive commodity segment. Newell Brands operates across both tiers with distinct brand strategies for each.
Stationery products encompass a range of tools and materials used for writing, drawing, record-keeping, and office correspondence. These items are typically manufactured from paper, plastic, wood, or metal and are designed for manual use in academic, professional, or personal settings. While pens and notebooks represent mature, high-volume product types, the art application segment shows significant margin potential. The academic application continues to form the largest base of consumption, driven by annual school cycles.
Product safety and material standards are critical regulatory hurdles, governed by frameworks like the EU's REACH for chemical substances and US Consumer Product Safety Commission rules for children's products. In China, GB standards dictate material safety and performance for items sold domestically. Navigating the shift toward sustainable and recycled materials while managing supply chain costs remains the central strategic challenge for manufacturers.
Market Dynamics
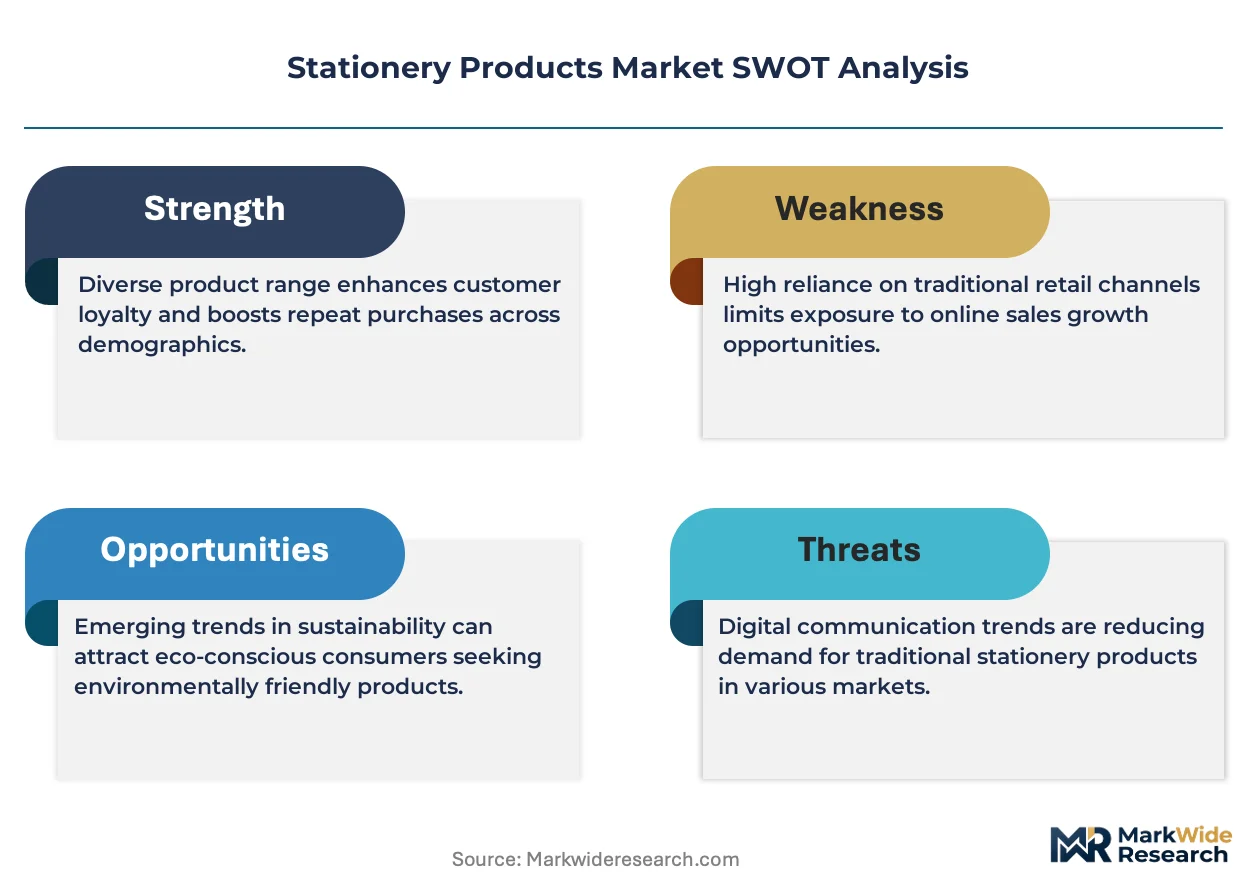
The central dynamic shaping the stationery market is the dual pressure of regulatory compliance and consumer demand for sustainability. This forces manufacturers to re-engineer supply chains for recycled and non-toxic materials, impacting cost structures and product design across all price tiers.
Growth Catalysts
- Personalization Demand:The expansion of journaling, scrapbooking, and hobbyist art communities creates consistent demand for specialized, high-margin pens, papers, and accessories, independent of academic or corporate cycles.
- Educational Expansion in India:Government initiatives and private sector investment in education across India are expanding the student population, creating a large, recurring consumer base for essential school supplies.
- Corporate ESG Policies:A growing number of corporations are implementing sustainable procurement policies, favoring stationery products made from recycled, certified, or biodegradable materials for their office supplies.
Market Restraints
- Digital Substitution:Digital note-taking apps and collaborative software in corporate and academic settings directly substitute for paper-based products like notebooks and planners.
- Raw Material Volatility:Price fluctuations in key inputs such as paper pulp, petrochemicals for plastics, and specialty pigments create margin pressure and supply chain unpredictability for manufacturers.
- EU REACH Compliance:The European Union's REACH regulation imposes significant testing and documentation burdens for chemical substances used in inks, adhesives, and plastics, creating a barrier for non-compliant products.
Strategic Opportunities
- DTC E-commerce Channels:Developing direct-to-consumer online platforms allows niche and premium brands to bypass traditional retail, build direct customer relationships, and capture higher margins on specialty items.
- Smart Stationery Integration:There is an opportunity in embedding digital technology into traditional products, such as smart pens that digitize notes or notebooks with app-based functionality, targeting tech-savvy professionals.
- African Education Markets:Rising school enrollment rates and economic development in countries like Nigeria and Ethiopia present underpenetrated markets for basic and affordable academic stationery products.
Industry Challenges
- Sustainable Material Sourcing:Securing a consistent, cost-effective supply of high-quality recycled materials that meet performance standards is a primary operational challenge.
- Navigating Global Standards:Manufacturers face complexity and cost in ensuring products simultaneously meet divergent safety and material regulations, such as China's GB standards, EU REACH, and US CPSC rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stationery Products Market |
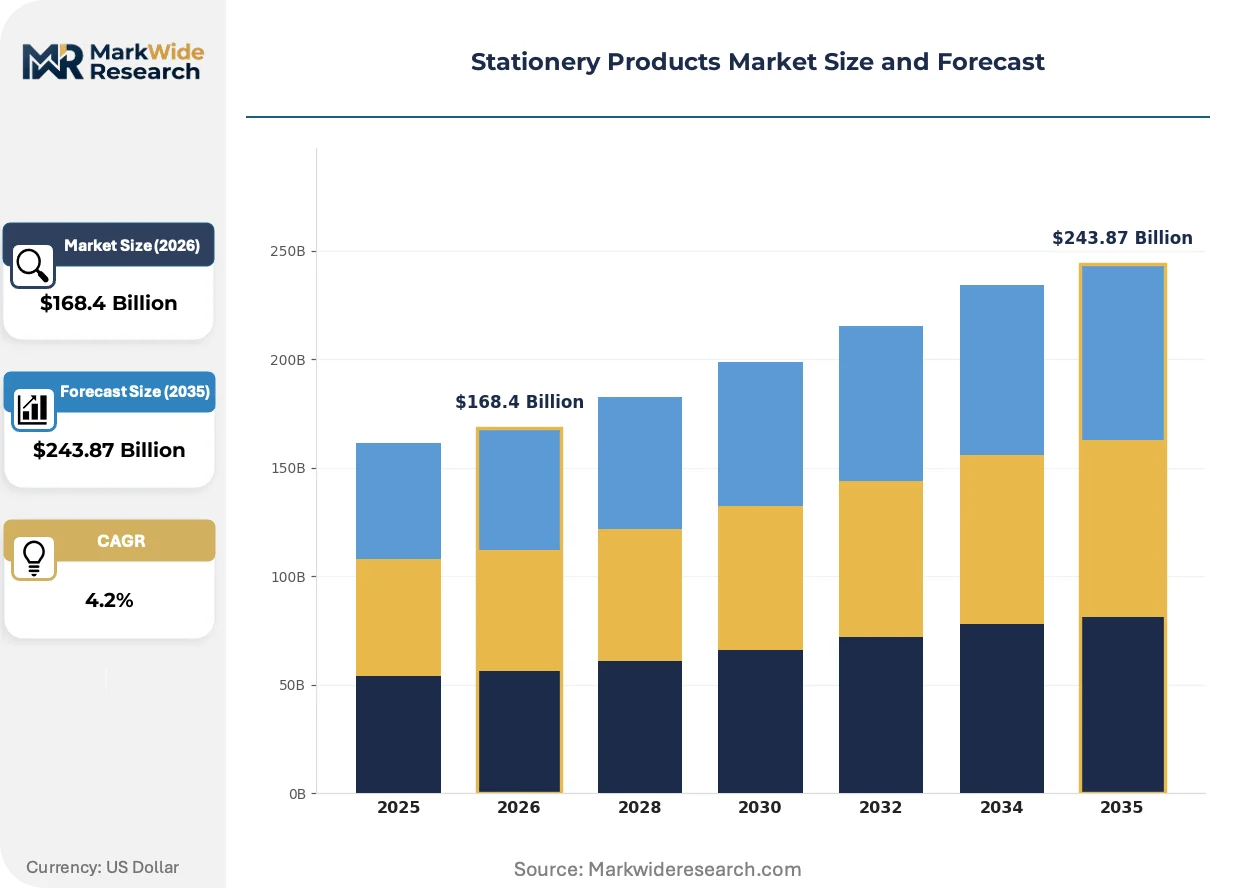
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $243.87 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pens, Pencils, Notebooks, Markers Application: Office, Academic, Art, Personal Use Material: Paper, Plastic, Metal, Wood Distribution Channel: Online, Retail Stores, Wholesale, Supermarkets |
| Companies Covered | Faber-Castell, 3M, Newell Brands, Kokuyo, Crayola, BIC, Pilot Corporation, Maped, ACCO Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stationery Products Market Strategic Shifts & Innovations
Sustainability and personalization are the defining forces in product innovation, compelling a move toward materials with certified origins and designs that cater to niche user communities. This shift creates new value propositions beyond simple utility and price.
Bio-based polymers and Forest Stewardship Council (FSC) certified paper pulp represent a key material evolution. Corporate procurement and environmentally conscious consumers are driving adoption of these materials to meet internal ESG targets and personal values. This shift toward sustainable inputs is overtaking traditional petroleum-based plastics and virgin fiber in new product development and marketing claims.
The US Consumer Product Safety Commission's (CPSC) stringent rules on lead and phthalate content in children's articles are a significant regulatory driver. These rules mandate rigorous third-party testing and certification before products can be sold, increasing compliance overhead. The children's art supply segment is most affected, prompting widespread reformulation of crayons, paints, and modeling clays.
A move from single-item purchasing toward curated kits and subscription box services is altering consumption patterns. This model disrupts traditional stationery retail by emphasizing discovery and convenience, favoring specialized e-commerce brands. The trend is most pronounced in North America and Western Europe, particularly within the premium writing and hobbyist art supply segments.
Stationery Products Market Segmentation
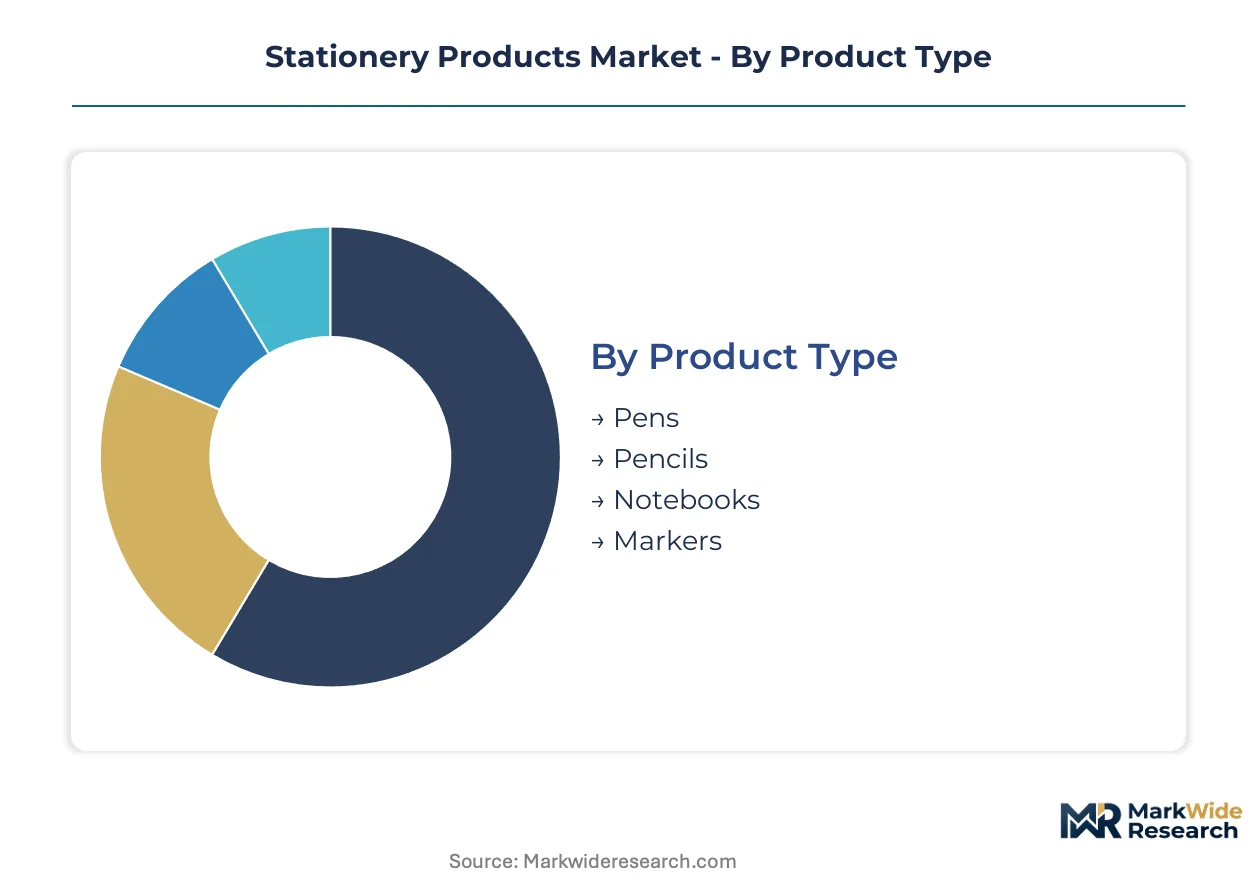
Understanding the distinct segments within the stationery products market reveals the varied forces driving demand and supply. Each product type, application, material, and distribution channel exhibits unique characteristics concerning manufacturing complexity, consumer behavior, and regulatory adherence. This granular view enables manufacturers to tailor product development and market entry strategies effectively.
Product Type:
The capital-intensive nature of manufacturing processes significantly influences competitive dynamics across product types. Producing certain items requires specialized machinery and large-scale operations to achieve cost efficiencies.
- Pens:These writing instruments, often comprising plastic, metal, and ink, offer diverse functionalities from basic ballpoints to sophisticated fountain pens. Demand concentrates in educational institutions across India and corporate offices in Germany, driven by daily writing needs and brand preference.
- Notebooks:Composed primarily of paper and binding materials, notebooks serve as essential tools for record-keeping and creative expression. Their consumption is highest in academic settings globally, particularly in China's expanding school system, where annual procurement cycles ensure consistent volume.
- Pencils:Crafted from wood and graphite, pencils provide a versatile medium for writing, drawing, and sketching.
- Markers:These tools, containing ink and a porous tip, are used for highlighting, art, and presentation purposes.
Most installed capacity flows through Pens. Expansion is steepest in Notebooks.
Application:
The volume of consumption varies significantly across different applications, reflecting distinct user needs and procurement patterns within the stationery market.
- Academic:This segment encompasses products essential for student learning, including notebooks, pens, and art supplies for school curricula. Annual back-to-school purchasing cycles in countries like the United States and Brazil ensure high, recurring demand, influenced by educational policies.
- Office:Products such as notepads, staplers, and files facilitate administrative tasks and professional communication within corporate environments. Procurement in large organizations in Japan and the UK often prioritizes bulk purchases and products meeting corporate sustainability standards.
- Art:Specialized papers, paints, and drawing instruments cater to professional artists and hobbyists seeking specific creative tools.
- Personal Use:This category includes items for journaling, scrapbooking, and personal organization, driven by individual preferences and lifestyle trends.
The largest consumer base resides in Academic. Growth is accelerating in Personal Use.
Material:
Customer type preferences and regulatory requirements dictate material selection and innovation within the stationery sector.
- Paper:Sourced from wood pulp or recycled fibers, paper forms the base for notebooks, planners, and various writing surfaces. Corporate procurement in France increasingly favors FSC-certified paper, aligning with environmental, social, and governance (ESG) policies.
- Plastic:Utilized in pen casings, rulers, and storage solutions, plastic materials offer durability and cost-effectiveness. EU REACH regulations influence the types of plastics and chemical additives permissible, particularly for products sold in Germany.
- Metal:Found in premium pens, staplers, and clips, metal components offer durability and a high-quality aesthetic.
- Wood:Primarily used for pencils and some desk accessories, wood provides a traditional, often sustainable, material option.
Predominant material usage is concentrated in Paper. Innovation is most visible in Plastic.
Distribution Channel:
Margin structures for stationery products differ significantly across distribution channels, reflecting varying operational costs and customer access points.
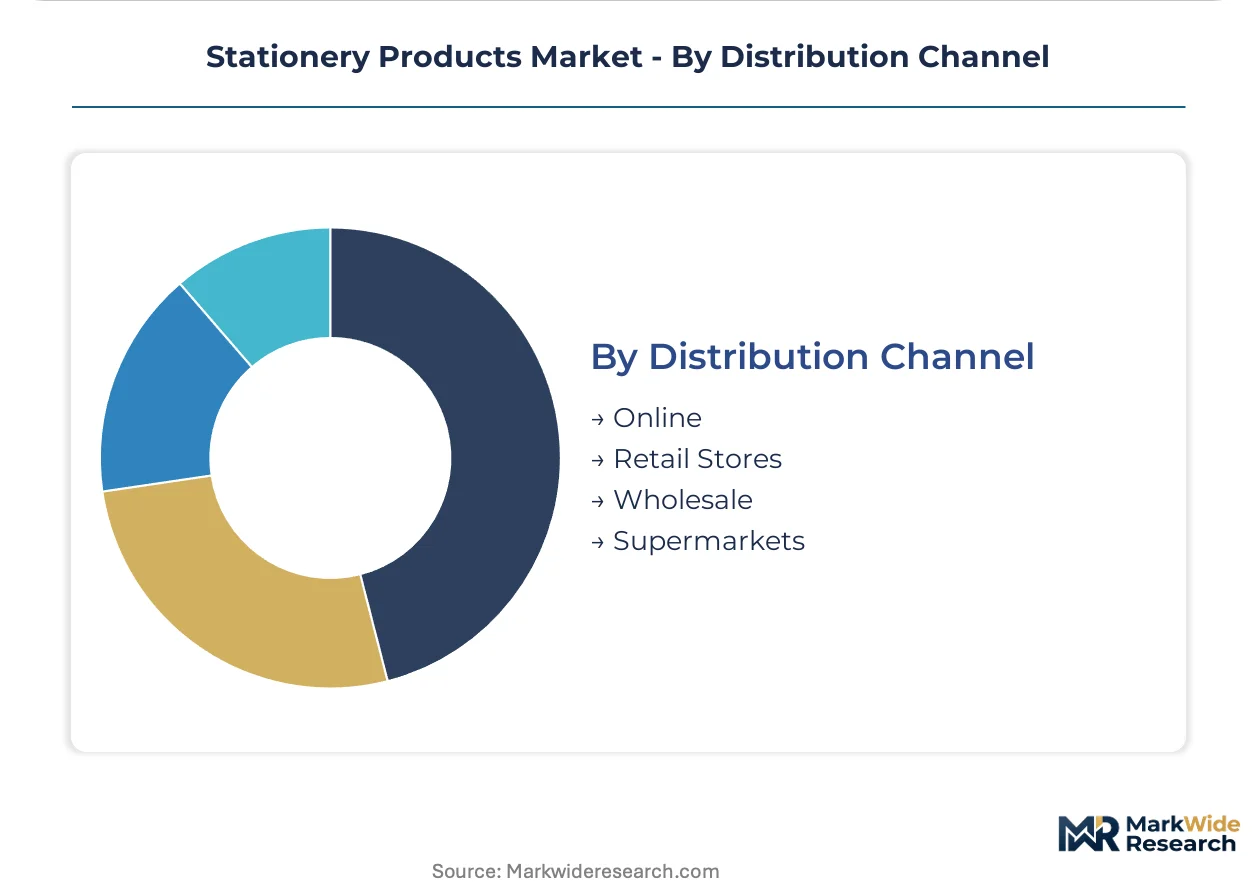
- Online:E-commerce platforms offer a broad selection and convenience, allowing niche brands to reach global audiences directly. Direct-to-consumer (DTC) models in the US and Canada allow for higher margins on specialized art supplies due to reduced intermediary costs.
- Retail Stores:Physical outlets, including stationery shops and department stores, provide immediate access and tactile product experience. These channels remain vital for impulse purchases and basic school supplies in urban centers across Mexico.
- Wholesale:This channel supplies large quantities to businesses, educational institutions, and other retailers, focusing on bulk pricing and logistics efficiency.
- Supermarkets:Grocery stores offer convenience for everyday stationery items, often positioning them as complementary purchases alongside other household goods.
The primary sales volume channels through Retail Stores. Direct customer engagement is expanding fastest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's substantial student population and growing corporate workforce anchor significant demand for stationery products. Government initiatives supporting education further stimulate consumption across the country. This strong domestic base drives consistent market expansion.
India
India's educational expansion creates a large, recurring consumer base for essential school supplies. The country's PLI scheme for manufacturing could incentivize domestic production of certain stationery items. Urban centers like Bengaluru and Hyderabad show strong growth in personalized and premium stationery demand.
China
Expanding educational enrollment in China drives substantial annual procurement of notebooks and pens. Strict GB standards ensure product material safety for items sold within the market. Manufacturing hubs in the Pearl River Delta demonstrate high-volume production capabilities for various stationery goods.
United States
Annual back-to-school purchasing cycles in the United States sustain high demand for academic stationery. The US CPSC rules impose stringent testing requirements for children's art supplies. E-commerce platforms based in California facilitate direct-to-consumer sales of niche and specialized products.
Germany
Corporate procurement in Germany prioritizes durable and sustainable office stationery. EU REACH regulations significantly impact the chemical composition of inks and plastics used in products. The Bavaria region, with its strong manufacturing base, supports innovation in premium writing instruments.
Japan
Japanese corporate environments drive consistent demand for high-quality office stationery and organizational tools. Japan's METI promotes industrial standards that often influence product design and material quality. The Kanto region, including Tokyo, serves as a major hub for both consumption and design innovation in stationery.
Stationery Products Market Key Industry Players
Top-tier vendors anchor the premium and design-led segment, while high-volume manufacturers compete in the mass-market commodity space. This market exhibits a tiered structure, with distinct strategies for quality, brand, and price. Strategic archetypes include specialized art supply creators, broad-line office product providers, and cost-efficient commodity producers. Companies pursue portfolio diversification and manufacturing scale optimization to maintain competitive positioning.
Within the premium and design-led archetype, Faber-Castell exemplifies a focus on high-quality art supplies and sophisticated writing instruments. In contrast, BIC occupies a position as a mass-market volume player, leveraging immense manufacturing scale for cost-effective commodity items. Newell Brands represents a diversified approach, operating across both premium and mass-market tiers with distinct brand strategies for each segment. These companies illustrate the varied competitive approaches to product differentiation and market reach.
| Leading Market Players |
|---|
| Faber-Castell |
| 3M |
| Newell Brands |
| Kokuyo |
| Crayola |
| BIC |
| Pilot Corporation |
| Maped |
| ACCO Brands |
| Others |
Cost & Logistics Intelligence
Paper pulp futures volatility directly cascades through the stationery supply chain, impacting raw material costs for notebooks and packaging, subsequently influencing pricing tiers for finished goods.
Pricing Analysis
The unbundled nature of stationery product sales drives price differentiation across various tiers. Premium-mid-economy pricing differentiation exists, separating high-quality art supplies from mass-market commodities. Brand premium and certification level, such as FSC-certified paper, serve as significant differentiation drivers. Pricing pressure stems from digital substitution in corporate settings and raw material volatility for plastics. The academic segment demonstrates high price sensitivity, while hobbyist art communities exhibit lower sensitivity for specialized tools.
Supply Chain Analysis
Rigorous product safety certifications, including EU REACH and US CPSC rules, gate market access and influence material sourcing decisions. Supply concentration centers in China for high-volume manufacturing and Germany for premium writing instruments. The supply chain draws from paper pulp, petrochemicals for plastics, and specialty pigments. Raw material volatility represents a structural risk, creating unpredictability for manufacturers. Distribution runs through a fragmented network of retail stores and expanding direct-to-consumer online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stationery products market functions as a stable compounder, driven by consistent demand from expanding educational sectors globally.
For Market Incumbents:Cement market leadership through proactive investment in sustainable material sourcing and advanced manufacturing capabilities. Diversify product portfolios into high-margin art and personalization segments to counter digital substitution threats. Invest in certification compliance for global markets, especially EU REACH and China GB standards, to maintain broad market access. Control key distribution channels, including direct-to-consumer e-commerce, to capture higher margins.
For New Entrants and Emerging Players:The significant price-point gap between mass-market commodities and premium design-led products offers new entrants opportunities. Target niche hobbyist art communities and underpenetrated African education markets for specialized product offerings. Leverage direct-to-consumer e-commerce platforms to build brand identity and bypass traditional retail gatekeepers. Focus on sustainable and non-toxic materials as a core go-to-market angle, aligning with consumer and corporate ESG policies.
For Investors and Strategic Acquirers:Asymmetric upside sits with vertically integrated mid-cap specialists focused on sustainable and personalized stationery solutions. The long-term viability of the stationery market is supported by recurring academic cycles and growing personal use demand. Target acquisition profiles include innovative brands with strong intellectual property in smart stationery or bio-based materials. A signal to watch is the increasing adoption rate of corporate sustainable procurement policies across major economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Material Integration | Reduces regulatory risk and meets growing consumer and corporate demand for eco-friendly products. |
| DTC Channel Expansion | Enhances brand control and allows for higher margins on specialized and premium stationery items. |
| Smart Stationery R&D | Captures tech-savvy professional segments by embedding digital functionality into traditional tools. |
| Emerging Market Entry (Africa) | Taps into large, underpenetrated consumer bases driven by rising educational enrollment rates. |
| Premium Art Supply Diversification | Captures high-margin demand from hobbyist and professional artists, independent of academic cycles. |
Research Approach
Direct dialogue with stationery manufacturers' R&D heads, procurement managers, and retail buyers informed primary data collection. This qualitative grounding was validated against secondary sources including EU REACH documentation, US CPSC reports, and China GB standards. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and market representation.
The analytical framework integrated bottom-up demand modeling with top-down market sizing across the projection horizon. Segmentation dimensions modeled included product type, application, material, distribution channel, and regional educational enrollment trends. Compound annual growth rates were derived from historical growth rates and future demand projections, incorporating industry-specific inputs like annual back-to-school purchasing cycles and corporate ESG policy adoption.
The model assumes a particular technology adoption path; alternative pathways for smart stationery integration would alter the outlook. Forecasts reflect assumptions regarding raw material price stability and the efficacy of regulatory compliance measures. A model refresh is warranted upon material change in global educational policy or key raw material pricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Student Stationery Market
Office Supplies
GCC School Stationery Supplies Market
Office Supplies
Copiers Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
Printer Ink Cartridge Market
Office Supplies
Pencil Sharpeners Market
Office Supplies
Stamp Pad Market
Office Supplies
Diaries & Planners Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Business Card Holder Market
Office Supplies
Cutter Staplers Market
Office Supplies
Global Stationery and Supplies Market
Office Supplies
Writing Instruments Market
Office Supplies
Dictionary Pen Market
Office Supplies
Stationery Market
Office Supplies
Perforated File Market