
 Dictionary Pen Market | 2026-2036
Dictionary Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Dictionary Pen Market Insights
CE marking under the EU Radio Equipment Directive is reorganizing which manufacturers can serve European educators, forcing hardware redesigns and documentation overhauls. Hanvon Technology leverages deep R&D ties with Chinese universities to sustain its domestic channel dominance. C-Pen competes through Nordic distribution partnerships that anchor its presence in Northern European language institutes. ScanMarker differentiates by specializing in slim-form optical modules that appeal to traveling professionals.
A dictionary pen is a handheld electronic device integrating optical character recognition sensors, microprocessors, and embedded lexical databases to scan printed text and deliver instant definitions, translations, or pronunciation guidance. Manufacturing prioritizes compact CMOS image sensors with minimum 300 DPI resolution and low-latency ARM-based chipsets to ensure sub-second query response. Smart pens with voice recognition technology occupy the highest-margin tier as schools and corporate trainers pay premiums for multimodal input. Optical character recognition remains the volume backbone across exam preparation use cases where silent operation is mandatory. Wireless connectivity is accelerating fastest among language enthusiasts who sync scanned vocabulary to cloud-based spaced-repetition platforms.
FCC electromagnetic emissions rules in the United States and CE marking requirements in Europe both constrain wireless-enabled models, while China's GB 4943.1 standard governs electrical safety for devices sold through state procurement channels. These frameworks elevate compliance costs for smaller assemblers and privilege manufacturers with in-house certification teams. Stakeholders must monitor whether emerging AI-integrated pens trigger fresh algorithmic transparency obligations under the EU AI Act before committing to next-generation platform investments.
Market Dynamics
GB 4943.1 electrical safety certification is restructuring China's state procurement channels, forcing domestic assemblers to absorb compliance costs while foreign entrants face exclusion from tier-one city tenders.
Growth Catalysts
- OCR-enabled reading tools:East Asian K-12 institutions are expanding device deployment for exam preparation and silent study environments. Procurement volumes concentrate in provincial education bureaus.
- FCC electromagnetic emissions frameworks:US regulatory clarity on wireless-enabled models is accelerating retailer certification timelines. Big-box electronics chains now stock connected dictionary pens.
- Cloud-based spaced-repetition platforms:Language enthusiasts demand seamless vocabulary sync. Wireless connectivity modules are capturing premium positioning among self-directed learners.
Market Restraints
- CMOS sensor supply concentration:Compact 300+ DPI image sensors rely on Taiwanese and South Korean foundry capacity. Geopolitical friction elevates input cost volatility.
- EU Radio Equipment Directive compliance:CE marking documentation overhauls consume 8-14 month certification cycles. Smaller hardware redesigns drain R&D budgets.
- Smartphone translation apps:Free optical character recognition alternatives constrain pricing power in consumer segments. Device manufacturers must defend hardware value propositions.
Strategic Opportunities
- Corporate training procurement:Multinational employers seek multimodal input devices for workforce language upskilling. Voice recognition pens command premium positioning.
- EU AI Act algorithmic transparency:Early compliance with emerging AI-integrated pen standards creates first-mover advantage. Certification teams gain procurement preference.
- Nordic language institute partnerships:Northern European distribution alliances remain underpenetrated. Specialized lexical databases for minority languages open channel access.
Industry Challenges
- Embedded firmware integration:ARM-based chipset optimization for sub-second query response requires scarce low-latency engineering talent. Hiring cycles extend competitive timelines.
- Multi-jurisdiction certification parallelism:Simultaneous FCC, CE, and GB standard compliance demands dedicated in-house regulatory teams. Smaller assemblers face capital constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dictionary Pen Market |
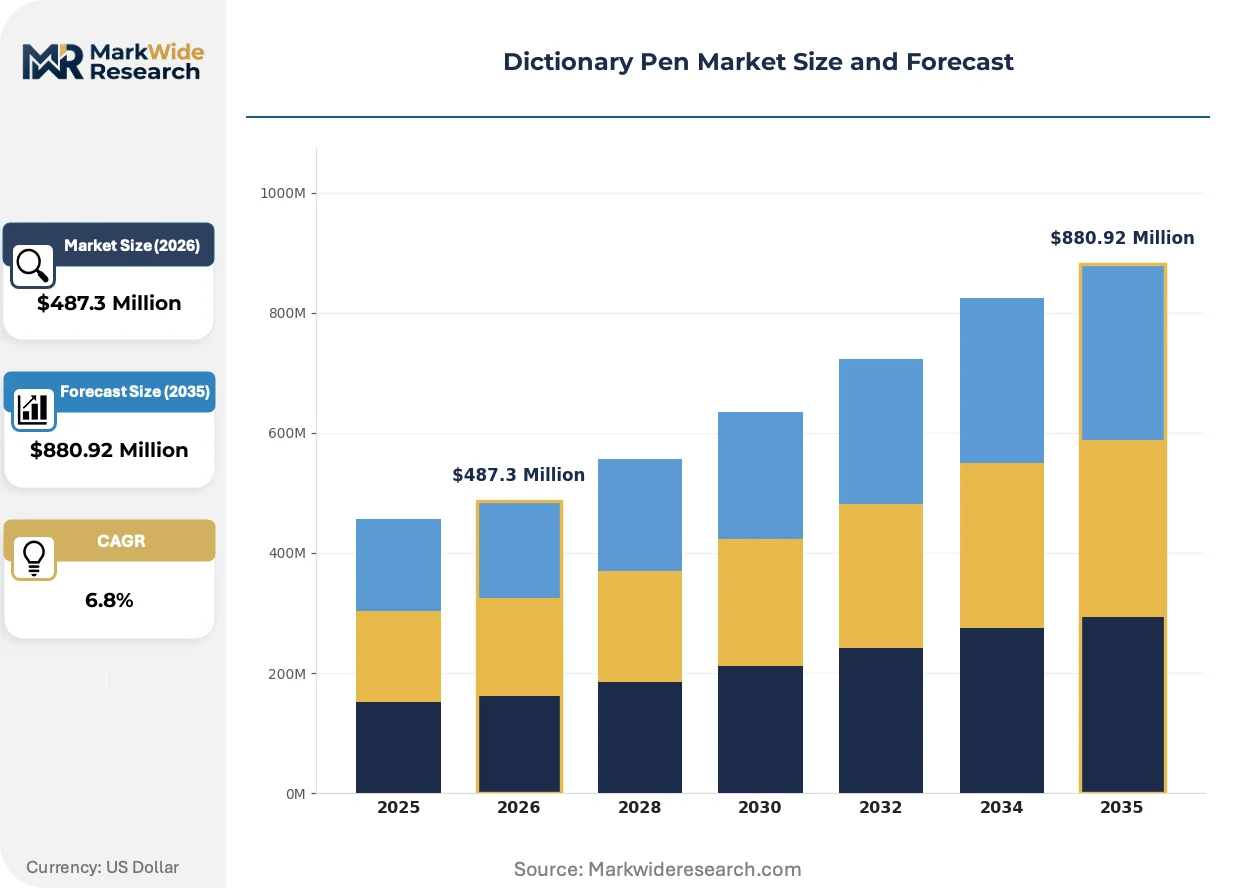
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Pens, Traditional Pens, Digital Pens, Interactive Pens Technology: Voice Recognition, Optical Character Recognition, Wireless Connectivity, Touch Screen Use Case: Language Learning, Exam Preparation, Note Taking, Translation Assistance Target Audience: Students, Educators, Professionals, Language Enthusiasts |
| Companies Covered | Anhui Taoyun Technology, Hanvon Technology, HKUST Xunfei, Wizcom, Pen Power, Shenzhen Friends of Learning Technology, Guangzhou Netease Computer System, C-Pen, ScanMarker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dictionary Pen Market Trends and Innovations
Multimodal input architectures are redrawing competitive boundaries as voice recognition modules penetrate professional training segments previously dominated by silent OCR devices.
Neural network-based optical character recognition is displacing traditional template-matching algorithms in premium device tiers. Language institutes and corporate trainers are adopting these models for handwritten text capture. The technology is compressing error rates in cursive recognition while extending hardware replacement cycles.
China's MIIT is tightening GB standard enforcement for electronic learning devices sold through state procurement. Manufacturers must submit accelerated safety testing documentation. Domestic channel dominance now hinges on certification team scale rather than component cost position.
Institutional buyers are consolidating vendor relationships around full-service maintenance contracts. Language schools and examination centers now bundle device refresh cycles with technical support. This pattern is most visible in China's tier-one cities where procurement bureaus centralize technology decisions.
Dictionary Pen Market Segmentation
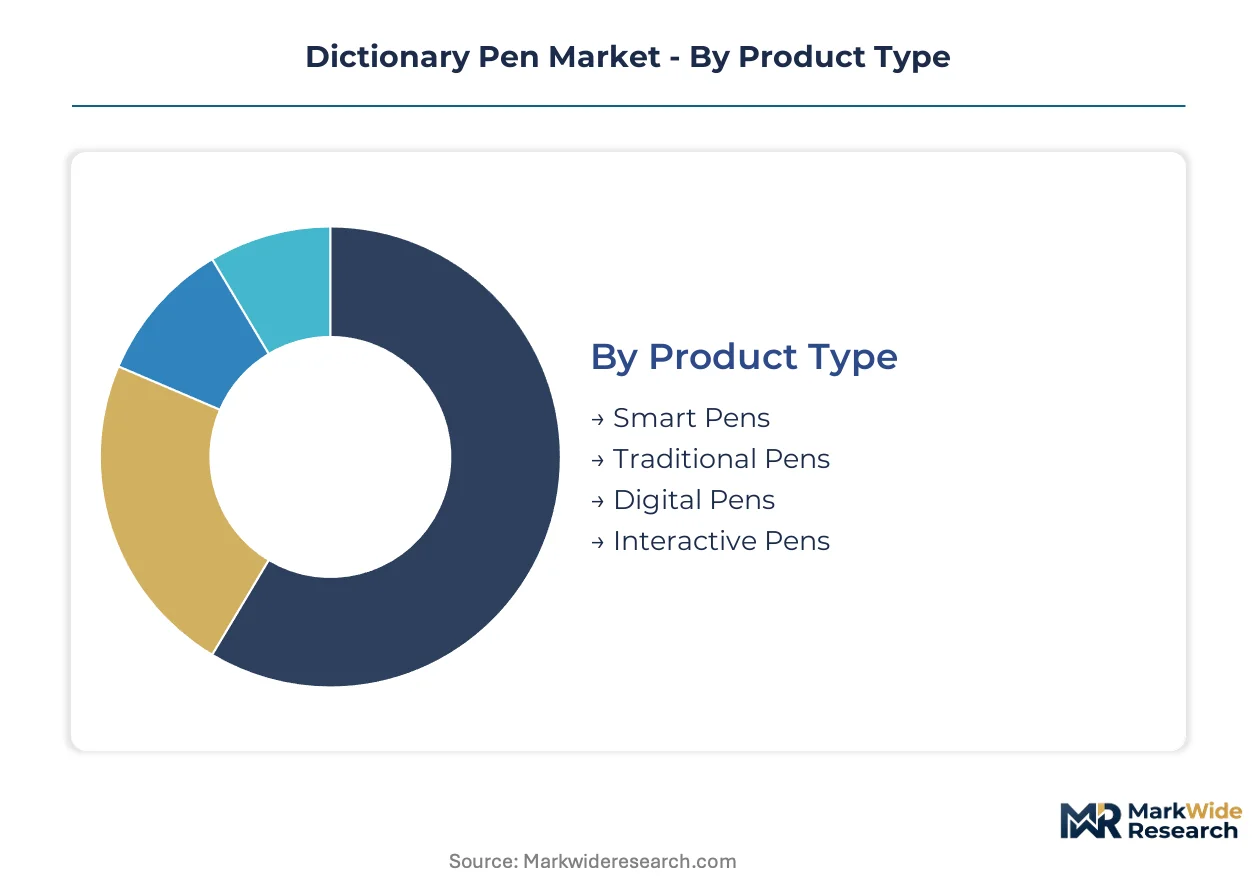
Segmentation in the dictionary pen market reveals how regulatory compliance, input modality, and end-use environment reshape procurement priorities across education and professional channels. Manufacturers configure hardware specifications and certification pathways differently for each slice, creating divergent margin structures and competitive barriers.
Product Type:
FCC electromagnetic emissions rules and China's GB 4943.1 electrical safety standard are segmenting product type viability across procurement channels, with wireless-enabled smart pens facing stricter documentation burdens than silent traditional alternatives.
- Smart Pens:These devices integrate voice recognition modules, ARM-based chipsets, and cloud-sync capabilities for multimodal vocabulary capture. China's tier-one city education bureaus are consolidating procurement around these units for corporate training partnerships despite premium pricing, driven by workforce language upskilling mandates from provincial human resource departments.
- Traditional Pens:Silent OCR-only operation with embedded lexical databases and no wireless transmission. Exam preparation centers across East Asian K-12 systems favor these units for their compliance with testing environment restrictions, with procurement volumes concentrating in provincial education bureau tenders where electronic device policies prohibit connectivity.
- Digital Pens:Basic optical scanning with onboard storage and USB data transfer. These units serve budget-constrained institutional buyers in secondary cities where GB standard certification costs already strain procurement budgets.
- Interactive Pens:Touch-screen interfaces with stylus input for annotation and vocabulary management. Language institutes in Northern Europe are piloting these for minority language database integration where specialized lexical content justifies hardware premiums.
Established volume favors traditional pens; emerging adoption favors smart pens.
Technology:
Cost tier differentiation separates premium voice-enabled modules from baseline optical systems, with wireless connectivity commanding hardware premiums that self-directed learners absorb for cloud platform synchronization.
- Voice Recognition:Neural network-based audio processing enabling spoken query input and pronunciation feedback. Multinational employers in China's Yangtze River Delta economic zone are procuring these for executive language training programs, with procurement decisions centralized through Shanghai municipal human resource development funds.
- Optical Character Recognition:Template-matching and neural OCR algorithms for printed text capture. K-12 examination preparation remains the volume anchor, with East Asian provincial education bureaus specifying minimum 300 DPI CMOS sensor resolution in technical procurement documents.
- Wireless Connectivity:Bluetooth and Wi-Fi modules for real-time vocabulary sync to spaced-repetition platforms. Language enthusiasts in Beijing and Shenzhen are driving fastest expansion here, with device manufacturers embedding firmware for Anki and Quizlet platform integration.
- Touch Screen:Capacitive input layers for manual annotation and interface navigation. Professional translators in Guangzhou and Chengdu are adopting these for document markup workflows where hybrid input speeds terminology verification.
Volume concentration sits with optical character recognition; margin expansion sits with voice recognition.
Use Case:
Application environment dictates hardware specification, with silent operation requirements in examination settings constraining feature sets that travel freely in self-directed learning contexts.
- Language Learning:Continuous vocabulary acquisition across structured curricula and informal practice. China's state-run Confucius Institutes are standardizing device specifications for overseas classroom deployment, with procurement routed through Beijing headquarters for Hanban-funded programs.
- Exam Preparation:Silent, offline operation for high-stakes testing environments. South Korea's CSAT preparation academies and China's gaokao tutoring centers specify traditional OCR pens exclusively, with municipal education bureaus banning wireless-enabled devices from examination halls.
- Note Taking:Handwritten text capture and digital organization. University students in Tokyo and Seoul are adopting neural OCR models for cursive recognition, extending device replacement cycles through improved accuracy.
- Translation Assistance:Real-time cross-lingual conversion for professional document review. Shenzhen-based export manufacturers are procuring these for technical documentation teams handling multilingual specification sheets.
Procurement scale favors exam preparation; technology refresh favors language learning.
Target Audience:
Customer type determines channel structure, with institutional buyers consolidating vendor relationships around maintenance contracts that individual consumers bypass through retail purchase.
- Students:K-12 and university learners in structured educational programs. China's provincial education bureaus are centralizing technology decisions for public school procurement, with tier-one city clusters standardizing on GB-certified devices.
- Educators:Classroom instructors and curriculum administrators. Language schools in Shanghai and Beijing are bundling device refresh cycles with technical support contracts, consolidating vendor relationships around full-service maintenance agreements.
- Professionals:Corporate workforce and technical specialists requiring specialized terminology. Multinational employers in Singapore and Hong Kong are procuring voice recognition pens for regional headquarters language training, with HR departments specifying multimodal input for executive cohorts.
- Language Enthusiasts:Self-directed learners pursuing informal skill development. Nordic distribution partnerships are penetrating this segment through specialized lexical databases for Danish, Norwegian, and Swedish minority dialects.
Institutional consolidation favors educators; discretionary upgrade frequency favors language enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement bureaus in China's tier-one cities anchor institutional demand, while language institutes in Northern Europe and examination centers across East Asia drive specialized segment volumes.
China
Provincial education bureaus in Shanghai and Beijing are consolidating technology decisions around GB 4943.1-certified devices. MIIT is tightening enforcement timelines for electronic learning device safety documentation. The Yangtze River Delta cluster houses domestic assemblers absorbing compliance costs to maintain state procurement channel access.
South Korea
CSAT preparation academies specify silent OCR-only pens for high-stakes testing environments. The national curriculum authority restricts wireless-enabled devices from examination halls. Seoul metropolitan tutoring centers drive volume concentration for traditional pen procurement.
Germany
CE marking under the EU Radio Equipment Directive is extending certification cycles for wireless-enabled models. The country's federal network regulator is scrutinizing electromagnetic emissions documentation. Bavarian technical institutes are piloting neural OCR devices for handwritten text capture.
United States
FCC electromagnetic emissions rules are accelerating retailer certification timelines for connected dictionary pens. Big-box electronics chains in California and Texas are expanding shelf space for wireless-enabled models. The Pacific Northwest cluster hosts distributors serving self-directed language learners.
Japan
METI standards for electronic learning devices are elevating documentation requirements for imported hardware. University students in Tokyo are adopting neural OCR models for cursive recognition. The Kansai region's language schools are bundling device refresh cycles with technical support contracts.
Dictionary Pen Market Competitive Landscape
Player mix skews toward domestic Chinese assemblers with certification team scale, European specialists with distribution partnerships, and hardware-focused innovators with optical module expertise. Two strategic archetypes dominate: GB-certified domestic channel leaders and CE-marked European distribution anchors. Competitive moves center on regulatory compliance parallelism and full-service maintenance contract bundling.
Within the domestic Chinese tier, Anhui Taoyun Technology and Hanvon Technology represent archetypes leveraging university R&D ties and certification team scale to secure provincial education bureau tenders. HKUST Xunfei occupies a position bridging voice recognition development with institutional procurement channels. Among European specialists, C-Pen exemplifies distribution partnership strategies anchoring Northern European language institute access. ScanMarker sits within the hardware innovation archetype, with slim-form optical modules targeting professional mobility segments.
| Leading Market Players |
|---|
| Anhui Taoyun Technology |
| Hanvon Technology |
| HKUST Xunfei |
| Wizcom |
| Pen Power |
| Shenzhen Friends of Learning Technology |
| Guangzhou Netease Computer System |
| C-Pen |
| ScanMarker |
| Others |
Pricing and Supply Chain Analysis
Long-term procurement contracts with China's provincial education bureaus lock in both CMOS sensor supply access and price visibility for GB-certified manufacturers, insulating domestic assemblers from spot-market volatility while foreign entrants absorb premium certification costs to compete in tier-one city tenders.
Pricing Analysis
Cost-plus contracts with Taiwanese foundry indexation anchor component pricing for ARM-based chipsets and 300+ DPI image sensors. Three-tier pricing structure across premium smart pens, standard traditional pens, and economy digital pens separates voice recognition modules from silent OCR devices from basic storage units. Cost compression in economy tiers intensifies because smartphone translation apps constrain hardware value propositions. K-12 examination preparation centers exhibit highest price sensitivity; multinational corporate training programs show lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of CMOS sensors prevails among domestic Chinese assemblers facing MIIT enforcement timelines, while just-in-time inventory characterizes Nordic distribution partners serving language institutes. Manufacturing concentrates in China, Taiwan, and South Korea. Component sourcing draws from compact image sensors, low-latency ARM chipsets, and embedded lexical databases. Single-source vulnerability runs through Taiwanese foundry capacity for premium sensor tiers. Distribution runs through provincial education bureau tenders in China and electronics retail chains in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as procurement decentralization across China's provincial education bureaus and Northern European language institutes creates niche entry points for specialized lexical database providers.
For Market Incumbents: Compound certification team scale advantages by accelerating GB 4943.1 documentation throughput for state procurement channel dominance. Deepen backward integration into CMOS sensor supply relationships to buffer Taiwanese foundry concentration risk. Voice recognition module commoditization from HKUST Xunfei and university R&D partnerships threatens premium positioning. For New Entrants and Emerging Players: Differentiate on minority language lexical database specialization for Nordic distribution partnerships anchoring Northern European language institute access. White-space targets include interactive pens with touch-screen interfaces for professional translator workflows in Guangzhou and Chengdu, and neural OCR devices for cursive recognition among university students in Tokyo and Seoul. Go-to-market angle: pilot bundled maintenance contracts with full-service technical support. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors certification-heavy domestic assemblers with university R&D ties. Long-term viability over the next decade hinges on AI-integrated pen compliance with emerging algorithmic transparency obligations. Acquisition target archetype: European distribution specialists with CE-marked wireless-enabled model portfolios. Signal to watch: EU AI Act enforcement timelines triggering hardware redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| GB 4943.1 Certification Acceleration | MIIT enforcement timelines favor manufacturers with in-house safety documentation teams. |
| Neural OCR Module Development | Bavarian technical institutes pilot handwriting capture for professional training segments. |
| Nordic Distribution Partnership | C-Pen anchors Northern European language institute access through specialized lexical databases. |
| Cloud Platform Firmware Integration | Anki and Quizlet synchronization commands premium positioning among Beijing language enthusiasts. |
| Full-Service Maintenance Contract Bundling | Shanghai municipal procurement bureaus consolidate vendor relationships around technical support. |
Research Methodology
A standing panel of provincial education bureau procurement officers, ARM chipset engineering leads, CMOS sensor supply managers, and language institute curriculum directors provided ongoing calibration. Primary interviews combined with secondary validation from FCC equipment authorization databases, MIIT GB standard filings, EU Radio Equipment Directive notifications, and customs trade records. Bottom-up device shipment modeling and top-down education technology expenditure triangulation anchored volume estimates.
Consistency checks against hyperscaler cloud platform partnership disclosures and spaced-repetition application user metrics validated output ranges across the projection horizon. Segmentation dimensions modeled include input modality, connectivity architecture, end-use environment, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating K-12 institution procurement cycle timing and corporate training budget elasticity. Neural OCR accuracy improvement curves and voice recognition module cost-down trajectories informed technology tier transitions.
Material uncertainties — geopolitical friction affecting Taiwanese foundry capacity, EU AI Act algorithmic transparency enforcement sequencing, and smartphone translation app feature expansion — sit outside the modeled envelope. Forecasts reflect assumptions about procurement centralization patterns and certification timeline stability. Revision becomes warranted when GB standard enforcement intensity or FCC electromagnetic emissions rule changes cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Business Card Holder Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Cutter Staplers Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Stationery Market
Office Supplies
School Stationery Supplies Market
Office Supplies
Writing and Marking Instruments Market
Office Supplies
Letter Opener Market
Office Supplies
Writing Instruments Market
Office Supplies
Marker Pens Market
Office Supplies
Copiers Market
Office Supplies
Perforated File Market
Office Supplies
Printer Ink Cartridge Market
Office Supplies
Thumb Hole Book Page Holder Market
Office Supplies
Stationery Products Market
Office Supplies
GCC School Stationery Supplies Market